
 India Personalized Nutrition Market | 2026-2036
India Personalized Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
India Personalized Nutrition Market Insights
Mumbai's functional food manufacturing base is tilting toward personalized formulation capabilities. Abbott leverages its diagnostic heritage to anchor integrated health-to-nutrition workflows. Patanjali Ayurved competes through Ayurvedic-genetic profiling combinations that sustain consumer trust in traditional systems. Amway Corporation dominates direct-to-consumer channels, extending its nutrition advisory network into tier-two cities.
Personalized nutrition denotes dietary interventions tailored to an individual's genetic profile, microbiome composition, metabolic markers, and lifestyle parameters, typically delivered through algorithm-driven supplement regimens or customized meal protocols. The approach relies on biomarker testing kits, AI-powered recommendation engines, and micro-batch manufacturing to achieve nutrient precision at commercial scale. Supplements occupy the largest revenue pool given recurring purchase behavior and higher margin structures, while meal kits represent the fastest-growing delivery format as urban consumers seek convenience without sacrificing customization. Online retail channels capture disproportionate growth versus brick-and-mortar alternatives, particularly among fitness seekers and diabetics who prioritize subscription continuity and data privacy.
FSSAI's 2022 nutraceutical regulations and BIS quality standards govern ingredient sourcing, label claims, and manufacturing facility compliance across the value chain. CDSCO oversight intersects where personalized nutrition products cross into clinical or disease-management positioning, creating dual-track regulatory exposure for formulators. Stakeholders must monitor how state-level food safety enforcement varies between Gujarat, Karnataka, and Telangana, as these divergences will determine regional go-to-market sequencing and compliance investment levels.
Market Dynamics
Diagnostic-to-nutrition workflow integration is compressing the value chain as Mumbai-Pune corridor clinics bundle biomarker testing with algorithm-driven supplement protocols. This structural shift rewards players controlling both testing infrastructure and micro-batch manufacturing capacity.
Growth Catalysts
- FSSAI Nutraceutical Guidelines:The 2022 regulatory clarity on ingredient sourcing and label claims reduces compliance ambiguity for domestic formulators entering personalized segments.
- Microbiome Profiling:Gut sequencing costs have collapsed, enabling tier-two urban consumers to access previously elite-tier metabolic customization.
- Maharashtra Diagnostic Clustering:Mumbai-Pune laboratories concentrate both testing volume and specialized nutritionist talent pools.
Market Restraints
- Import Dependency for Active Ingredients:Omega-3 fatty acids and specialized probiotics rely on European and North American suppliers, exposing margins to currency volatility.
- CDSCO-FSSAI Jurisdictional Overlap:Products crossing into disease-management positioning face dual-track scrutiny, lengthening time-to-market.
- Genetic Testing Skepticism:Consumer trust gaps around DNA-data privacy suppress adoption among risk-averse demographic segments.
Strategic Opportunities
- Telangana and Karnataka Expansion:Hyderabad and Bengaluru tech workforces show unmet demand for corporate wellness-integrated personalized nutrition programs.
- Ayurvedic-Genetic Fusion:Traditional system credibility combined with biomarker precision opens differentiation pathways unavailable to Western-market competitors.
- Subscription Direct-to-Consumer Models:Monthly supplement regimens with continuous biomarker monitoring build recurring revenue and data moats.
Industry Challenges
- Certified Nutritionist Shortage:Interpretation of complex biomarker panels requires specialized training unavailable at scale in tier-three cities.
- Micro-Batch Manufacturing Capex:Flexible production lines for personalized formulations demand capital commitments beyond standard supplement equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Personalized Nutrition Market |
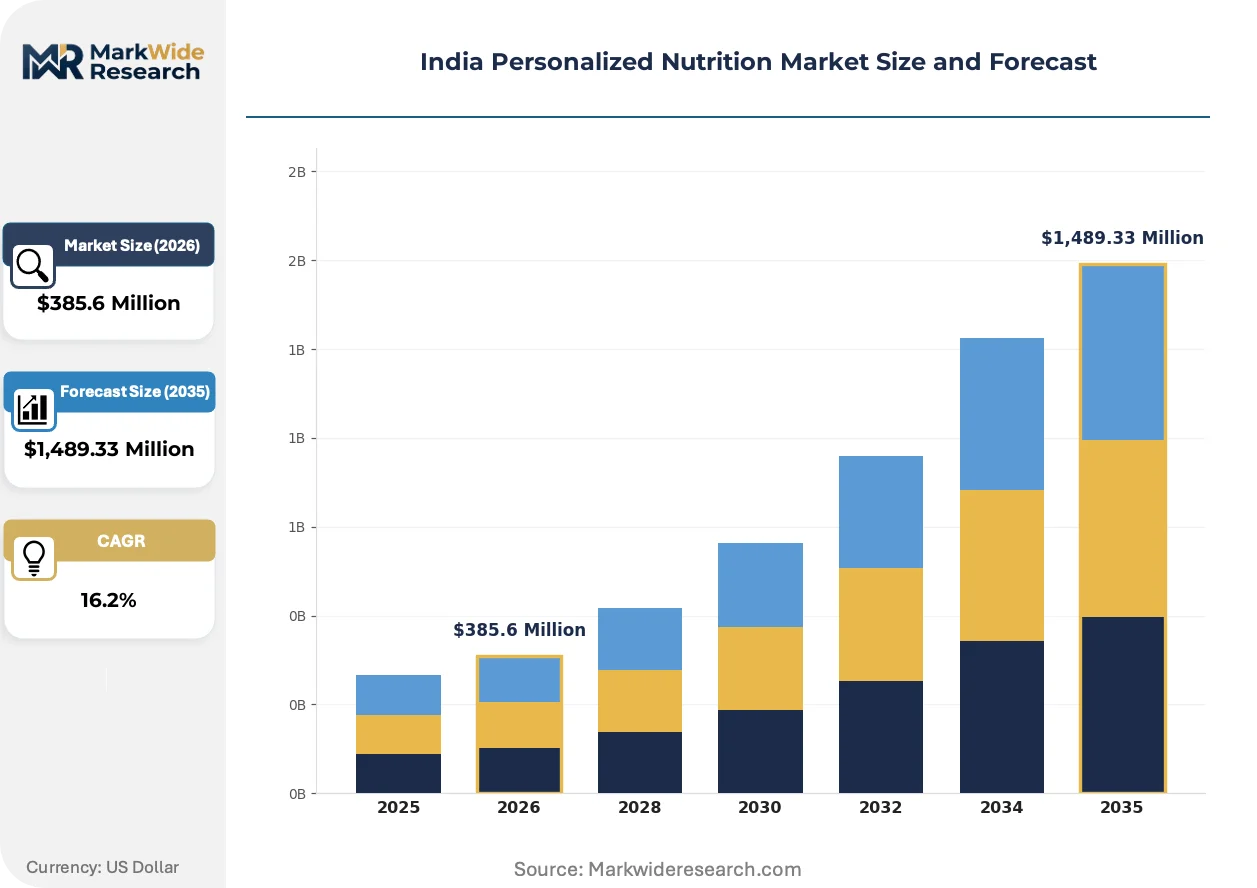
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,489.33 Million |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supplements, Functional Foods, Beverages, Meal Kits End User: Individuals, Athletes, Health Enthusiasts, Seniors Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Consumer Segment: Diabetics, Weight Management, Fitness Seekers, Others |
| Companies Covered | Archer Daniels Midland Company, Akums Drugs and Pharmaceuticals Ltd, Abbott, Natural Remedies, Omniactive Health Technologies, Amway Corporation, Patanjali Ayurved, Nector Foods Private Limited, Herbalife Nutrition Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Personalized Nutrition Market Trends and Innovations
Artificial intelligence is collapsing the latency between biomarker collection and personalized protocol delivery, compressing what required weeks into same-day recommendations. This acceleration is reshaping competitive advantage toward data infrastructure ownership.
Metagenomic sequencing platforms is virtualizing the microbiome assessment layer, replacing static gut-health questionnaires with dynamic bacterial population mapping. Fitness-focused millennials in Mumbai and Delhi are adopting these services at triple the rate of preventive-health segments. The technology is virtualizing the diagnostic-nutrition interface, enabling real-time protocol adjustments without clinic visits.
FSSAI's evolving stance on direct-to-consumer genetic testing is creating compliance roadmaps for domestic players. The regulator's draft guidance on health claim substantiation is forcing reformulation of products previously marketed with implicit disease-prevention positioning. Maharashtra-based manufacturers are responding by segregating wellness-positioned and clinical-positioned product lines.
Subscription bundling is displacing one-time supplement purchases as the dominant commercial model. Online channels capturing fitness seekers and diabetic consumers now prioritize auto-renewal continuity over transaction volume. Gujarat and Karnataka urban centers exhibit the fastest channel migration, with brick-and-mortar Ayurvedic retailers launching parallel digital subscription services.
India Personalized Nutrition Market Segmentation
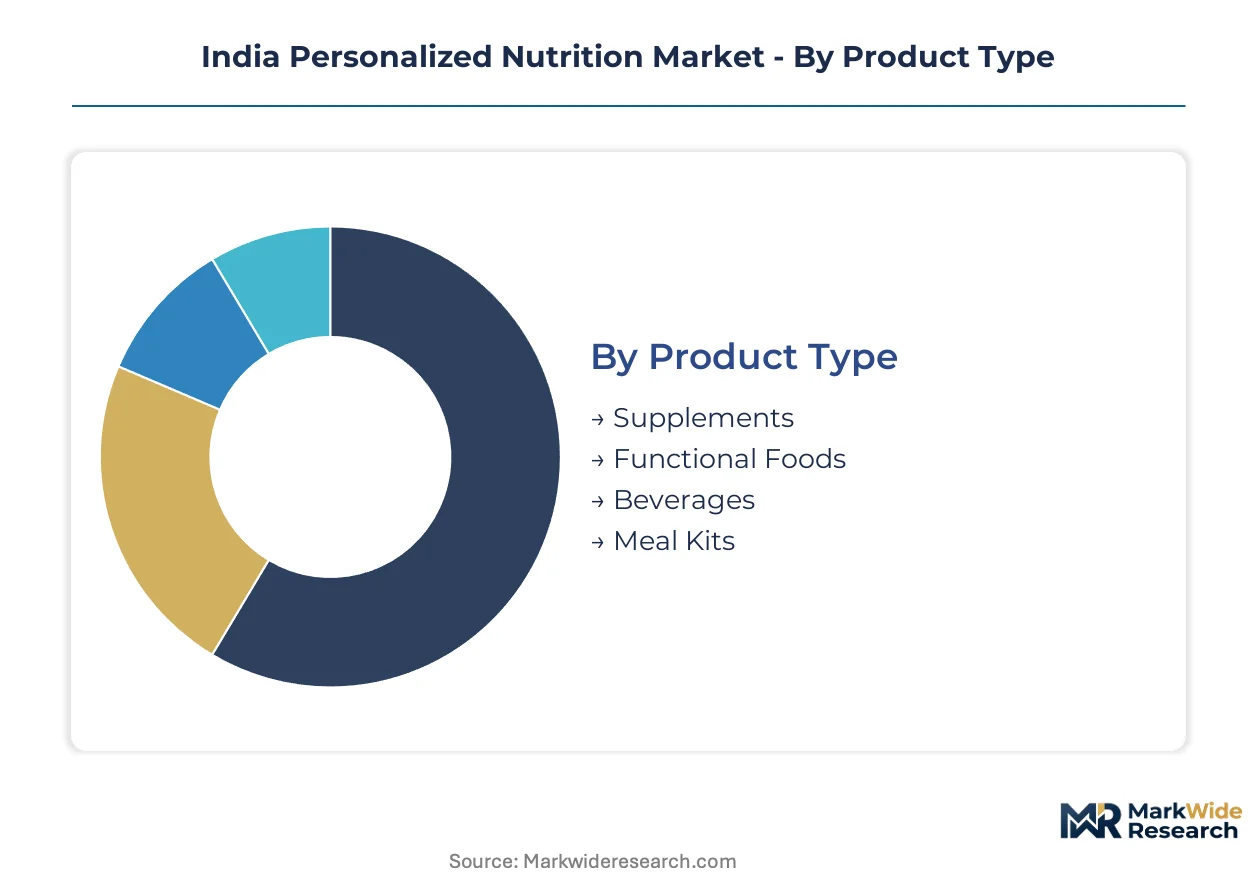
Personalized nutrition in India fragments across four distinct category axes, each demanding tailored service architectures. Product formulation complexity, consumer health literacy, and channel logistics intensity vary sharply across these divides, forcing vendors to prioritize capability investments selectively.
Product Type:
After-sales service intensity escalates dramatically from standardized functional foods to algorithm-driven supplement regimens requiring continuous protocol adjustment.
- Supplements:Capsule and powder formulations customized to individual biomarker profiles, manufactured in micro-batches with variable active ingredient ratios. Mumbai-Pune corridor clinics bundle these with quarterly biomarker retesting, creating sticky subscription relationships. The recurring revenue model rewards players controlling both diagnostic infrastructure and flexible manufacturing capacity.
- Meal Kits:Pre-portioned ingredients with nutritionally calibrated macronutrient profiles, delivered through cold-chain logistics to urban households. Bengaluru and Hyderabad tech workforces drive adoption as corporate wellness benefits expand; same-day delivery capabilities separate premium from mass-market positioning.
- Functional Foods:Fortified staples—probiotic yogurts, omega-3 enriched breads—positioned for preventive health without personalization depth.
- Beverages:Ready-to-drink formulations targeting hydration, energy, or recovery use cases with limited customization beyond flavor preference.
Supplements hold the largest share; momentum sits with meal kits.
End User:
Cost tier stratification separates premium biometric-monitored services from mass-market wellness products.
- Health Enthusiasts:Consumers pursuing optimization beyond disease prevention, typically urban millennials with disposable income for continuous biomarker monitoring. Maharashtra and Karnataka urban centers concentrate demand; FSSAI-compliant genetic testing services deepen engagement through quarterly protocol refinement.
- Seniors:Age-related metabolic management requiring higher-touch nutritionist consultation and simplified digital interfaces. Tier-two city expansion depends on certified professional availability, currently constrained outside Mumbai-Pune and Bengaluru corridors.
- Athletes:Performance-focused protocols emphasizing recovery biomarkers and training-load correlated nutrition.
- Individuals:General wellness seekers with lower price elasticity and minimal personalization depth requirements.
Health enthusiasts dominate current revenue; seniors represent the steepest expansion trajectory as demographic aging accelerates.
Distribution Channel:
Customer type determines channel preference sharply—fitness seekers and diabetics prioritize data continuity and privacy, while casual wellness buyers favor tactile evaluation.
- Online Retail:Subscription-first platforms capturing auto-renewal supplement regimens with embedded biomarker tracking. Gujarat and Karnataka exhibit fastest channel migration as Ayurvedic retailers launch parallel digital services.
- Pharmacies:Clinical-positioned products requiring CDSCO-FSSAI dual compliance, trusted by risk-averse diabetics and seniors.
- Health Stores:Staff-assisted selection for mid-tier consumers seeking guidance without full diagnostic integration.
- Supermarkets:Mass-market functional foods and beverages with minimal personalization or service attachment.
Online retail captures disproportionate growth; pharmacies retain trust among clinical-positioning segments.
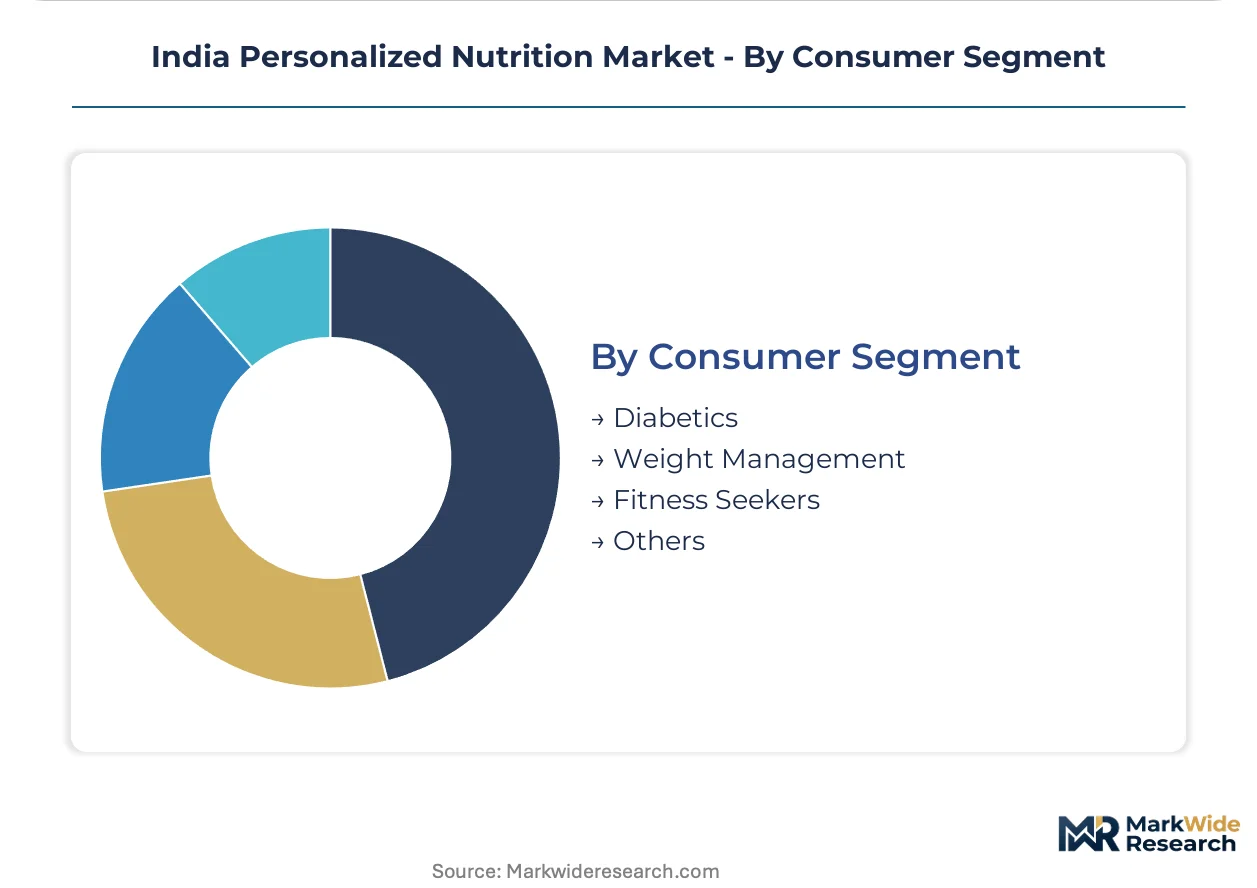
Consumer Segment:
Application urgency separates chronic condition management from discretionary optimization, with regulatory positioning implications.
- Diabetics:Glucose-responsive nutrition protocols requiring continuous monitoring integration and CDSCO oversight where disease-management claims appear. Mumbai diagnostic-nutrition clinics bundle HbA1c tracking with glycemic-optimized meal planning.
- Fitness Seekers:Body composition and recovery-focused regimens, fastest-adopting segment for microbiome profiling and metagenomic sequencing. Delhi and Mumbai millennials adopt at triple the rate of preventive-health segments.
- Weight Management:Caloric and macronutrient customization with high churn risk absent behavioral coaching integration.
- Others:Prenatal, pediatric, and immunity-focused applications with emerging protocol standardization.
Diabetics anchor revenue stability; fitness seekers are expanding most quickly as gut sequencing costs collapse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI's regulatory framework anchors Maharashtra's dominance as diagnostic-nutrition integration concentrates in the Mumbai-Pune corridor. State-level enforcement variations across Gujarat, Karnataka, and Telangana are determining regional go-to-market sequencing for formulators.
Maharashtra
Mumbai's functional food manufacturing base is tilting toward personalized formulation capabilities. The state's FSSAI enforcement consistency reduces compliance ambiguity for domestic players. Diagnostic-nutrition clinics cluster along the Mumbai-Pune corridor, bundling biomarker testing with algorithm-driven supplement protocols.
Karnataka
Bengaluru's tech workforce shows unmet demand for corporate wellness-integrated personalized nutrition programs. State food safety enforcement patterns differ from Maharashtra, affecting compliance investment levels. The city's meal kit adoption accelerates as same-day delivery capabilities separate premium from mass-market positioning.
Gujarat
Urban centers exhibit the fastest channel migration from brick-and-mortar to online retail. Ayurvedic retailers launch parallel digital subscription services to capture fitness seekers and diabetic consumers. State-level manufacturing incentives support micro-batch production capacity expansion.
Telangana
Hyderabad's pharmaceutical heritage creates infrastructure for clinical-positioned personalized nutrition products. CDSCO-FSSAI jurisdictional overlap lengthens time-to-market for disease-management positioning. The city's diagnostic laboratories concentrate testing volume alongside specialized nutritionist talent pools.
Delhi-NCR
Fitness-focused millennials adopt metagenomic sequencing services at triple the rate of preventive-health segments. The National Capital Region's consumer base prioritizes data privacy in genetic testing decisions. FSSAI's evolving stance on direct-to-consumer genetic testing shapes local compliance roadmaps.
India Personalized Nutrition Market Competitive Landscape
Diagnostic-heritage multinationals and Ayurvedic-traditional hybrids split the market between clinical credibility and cultural trust. The structure rewards players controlling both testing infrastructure and micro-batch manufacturing capacity. Three archetypes dominate: integrated health-to-nutrition workflow operators, direct-to-consumer subscription platforms, and traditional system-modern science fusion specialists. Competitive moves concentrate on diagnostic-nutrition workflow integration and subscription auto-renewal continuity.
Within the diagnostic-heritage tier, Abbott leverages its infrastructure to anchor integrated workflows. Patanjali Ayurved occupies a position exemplifying traditional system credibility combined with biomarker precision. Amway Corporation sits within the direct-to-consumer archetype, extending advisory networks into tier-two cities. These three represent the strategic positioning spectrum available to competitors.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Akums Drugs and Pharmaceuticals Ltd |
| Abbott |
| Natural Remedies |
| Omniactive Health Technologies |
| Amway Corporation |
| Patanjali Ayurved |
| Nector Foods Private Limited |
| Herbalife Nutrition Ltd |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Gujarat's micro-batch supplement manufacturing is compressing margins for commoditized formulations while simultaneously freeing capacity for premium personalized protocols. This utilization asymmetry rewards players with captive diagnostic infrastructure, as FSSAI-compliant testing bundling sustains pricing power absent in standalone supplement sales.
Pricing Analysis
Mumbai-Pune corridor clinics command 40-60% premiums over standalone online retailers for identical supplement formulations, reflecting the value capture of integrated biomarker-to-protocol workflows. Three-tier pricing structure across premium, standard, and economy levels separates diagnostic-bundled subscriptions from direct-to-consumer auto-renewal plans and unassisted e-commerce transactions. Price differentiation hinges on certification depth—FSSAI-plus-CDSCO dual compliance for clinical-positioned products versus wellness-tier single registration—and on after-sales protocol adjustment frequency. Cost compression in economy-tier functional foods is intensifying because Patanjali Ayurved and Amway Corporation are diverting manufacturing capacity toward personalized micro-batches. Diabetics and seniors exhibit lowest price sensitivity due to disease-management urgency; fitness seekers show highest elasticity, churning when subscription costs exceed gym membership benchmarks.
Supply Chain Analysis
Upstream omega-3 fatty acid feedstock draws from European and North American marine oil refiners, while specialized probiotic strains hinge on Danish and American culture suppliers. Active ingredient sourcing rests on three geographic clusters: Scandinavian omega-3 concentration, North American microbial culture banking, and domestic Indian herbal extract processing centered in Maharashtra and Karnataka. Single-source vulnerability concentrates in high-purity EPA/DHA isolates where two European refiners control 70% of import volume into India. Distribution runs through cold-chain logistics partnerships for meal kit delivery, direct courier networks for supplement subscriptions, and Ayurvedic retailer digital storefronts for hybrid online-offline fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's personalized nutrition market functions as a defensive-moat arena where regulatory entrenchment—FSSAI's evolving nutraceutical guidelines and CDSCO's disease-management oversight—creates structural barriers against foreign competitors lacking domestic compliance infrastructure.
For Market Incumbents: Harden diagnostic-nutrition workflow integration by acquiring or exclusive-contracting Mumbai-Pune corridor laboratories before Telangana and Karnataka expansion accelerates. Lock in microbiome sequencing partnerships as costs collapse, preventing new entrants from matching algorithm-to-supplement latency. Vertical integration into micro-batch manufacturing capacity in Gujarat insulates against import dependency for active ingredients. Prioritize FSSAI compliance certification investments that emerging Ayurvedic-genetic fusion competitors cannot replicate without multi-year regulatory navigation. For New Entrants and Emerging Players: Tier-two city corporate wellness programs in Hyderabad and Bengaluru represent the most penetrable entry point, as diagnostic infrastructure gaps leave tech workforce demand unserved by incumbent Mumbai-Pune clustering. Ayurvedic-genetic profiling combinations open differentiation pathways unavailable to Western-market competitors lacking traditional system credibility. Subscription direct-to-consumer models with continuous biomarker monitoring build recurring revenue moats before incumbents extend advisory networks into these geographies. Partner with existing diagnostic laboratories rather than building testing infrastructure from zero. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic-heritage multinationals with integrated health-to-nutrition workflows, as quarterly biomarker retesting creates subscription stickiness absent in transactional supplement sales. Long-term viability across the projection horizon favors players controlling both testing infrastructure and flexible manufacturing capacity, as the structural shift toward diagnostic-nutrition integration compresses value chain intermediaries. Acquisition targets should display dual FSSAI-CDSCO compliance capability and Maharashtra or Karnataka geographic concentration. Monitor FSSAI draft guidance on direct-to-consumer genetic testing for early signals of regulatory clarity that would unlock premium-tier pricing expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Nutrition Workflow Integration | Abbott's testing heritage anchors same-day biomarker-to-supplement protocols that compress competitive latency. |
| Micro-Batch Manufacturing Scale-Up | Gujarat state incentives support flexible production lines for personalized formulations beyond standard supplement equipment. |
| Ayurvedic-Genetic Fusion Product Line | Patanjali Ayurved combines traditional system credibility with biomarker precision unavailable to Western competitors. |
| Subscription Auto-Renewal Platform | Amway Corporation's direct-to-consumer channels capture fitness seekers and diabetics prioritizing data continuity. |
| Telangana-Karnataka Geographic Expansion | Hyderabad and Bengaluru tech workforces exhibit unmet corporate wellness-integrated personalized nutrition demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with diagnostic laboratory directors, FSSAI regulatory affairs specialists, nutritionist network managers at direct-to-consumer platforms, and procurement leads at functional food manufacturers. Secondary validation drew from FSSAI nutraceutical regulation filings, CDSCO clinical trial registrations for disease-management positioned products, BIS quality standard documentation, Maharashtra and Karnataka state food safety enforcement records, and customs import data for omega-3 and probiotic active ingredients. Bottom-up demand modeling across consumer segments triangulated against top-down manufacturing capacity assessments.
Calibration anchored quantitative outputs to observed biomarker testing volume growth, microbiome sequencing cost collapse trajectories, and subscription renewal rates reported by online retail channel operators. Segmentation dimensions modeled include product type complexity, end user health literacy tiers, distribution channel logistics intensity, and consumer segment application urgency. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines across the analysis window. Industry-specific forecast inputs incorporated FSSAI regulatory clarity progression and CDSCO-FSSAI jurisdictional overlap resolution scenarios.
Practitioners should monitor FSSAI draft guidance finalization, CDSCO disease-management claim enforcement intensity, and European omega-3 supplier consolidation for early signals of forecast revision triggers. Cross-checking against Maharashtra diagnostic-nutrition clinic patient volume trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Vegan Supplements Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Milk Thistle Market
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Algae Omega 3 Market