
 Global General Well-Being Dietary Supplements Market | 2026-2036
Global General Well-Being Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global General Well-Being Dietary Supplements Market Foresight
Registered dietitian shortages across North America and Western Europe are reorganizing how supplement brands build credibility and consumer trust. Amway Corporation leverages its direct-selling infrastructure to sustain personalized nutrition consultations in markets where professional guidance remains scarce. Nestlé Health Science anchors its portfolio in medical-grade formulations, while Herbalife Ltd. competes through community-based distributor networks that replicate advisory relationships.
General well-being dietary supplements encompass vitamins, minerals, botanical extracts, and microbial cultures formulated in standardized doses to address nutritional gaps and support physiological function beyond disease treatment; products typically specify active compound concentrations, dissolution profiles, and excipient matrices to ensure bioavailability and shelf stability. The vitamins segment dominates volume due to established consumer familiarity and lower per-unit pricing, yet probiotics commands expanding shelf space as gut-brain axis research deepens. Gummies as a form category captures disproportionate growth among adult consumers who reject traditional pill formats, while immune support applications maintain baseline demand through seasonal purchasing cycles.
FDA enforcement of Current Good Manufacturing Practices and EFSA health-claim substantiation requirements create divergent compliance burdens that favor multinationals with dedicated regulatory affairs teams. India's FSSAI and China's SAMR impose additional localization mandates on imported formulations, reshaping supply chain footprints for brands seeking market access. Stakeholders must monitor evolving novel food classifications in the EU and emerging microbiome-specific claim pathways, as regulatory clarity will determine which ingredient technologies achieve scalable commercialization.
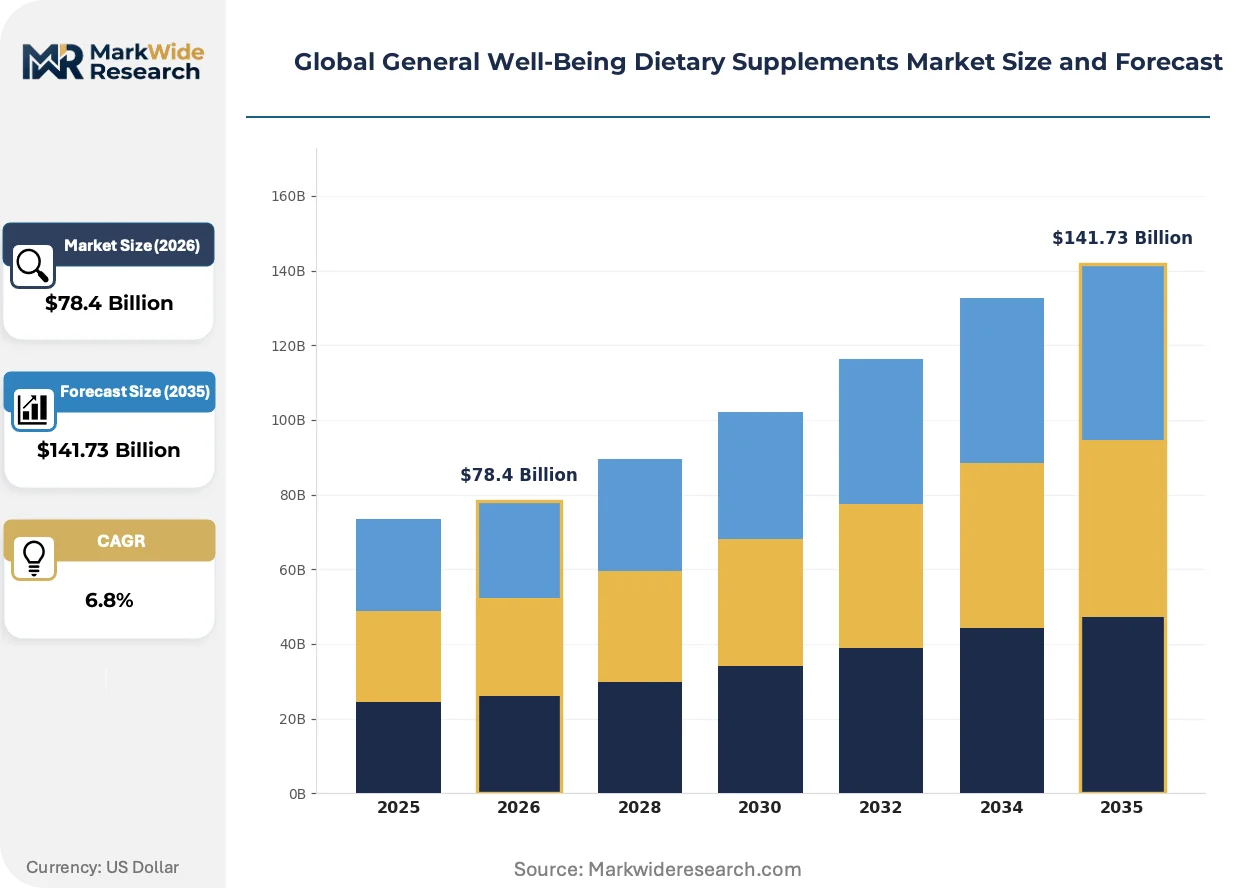
Market Dynamics
Preventive health prioritization among aging demographics is restructuring demand composition across the general well-being dietary supplements sector, with formulation science and distribution credibility emerging as the primary battlegrounds for competitive differentiation.
Growth Catalysts
- FDA Current Good Manufacturing Practice enforcement:Elevated compliance standards filter out subscale manufacturers, concentrating market share among entities with dedicated quality infrastructure and reinforcing consumer confidence in verified product claims.
- Senior citizen preventive health expenditure:Aging populations in Japan, Germany, and the United States allocate disproportionate discretionary spending toward micronutrient supplementation and bone health formulations, expanding addressable market volume.
- Microbiome-targeted delivery technologies:Encapsulation advances protecting probiotic viability through gastric transit unlock therapeutic dosing previously unattainable with conventional formulations, broadening clinical credibility.
Market Restraints
- Raw material supply concentration:Specialty botanical extracts and marine-derived omega-3 fatty acids depend on concentrated harvesting regions in Peru and Morocco, exposing formulation costs to climate-induced harvest volatility and export quota restrictions.
- EFSA health-claim substantiation requirements:The European Food Safety Authority's demand for randomized controlled trial evidence blocks commercialization of novel ingredients lacking extensive clinical dossiers, extending time-to-market for European launches.
- Substitute competition from functional foods:Fortified beverages and nutrient-dense snack formats capture overlapping wellness-oriented consumers, compressing supplement category growth in convenience-oriented retail channels.
Strategic Opportunities
- India's FSSAI localization pathway:India's Food Safety and Standards Authority of India mandates domestic manufacturing or joint venture structures for imported formulations, creating first-mover advantages for brands establishing local production ahead of enforcement tightening.
- Personalized nutrition subscription models:At-home microbiome testing integration with algorithmic supplement curation transforms one-time purchasers into recurring revenue relationships, elevating lifetime value metrics.
- China's SAMR dual carbon alignment:China's State Administration for Market Regulation incentivizes sustainable packaging and domestic sourcing credentials, rewarding supply chain reconfiguration with preferential retail placement in state-affiliated pharmacy networks.
Industry Challenges
- Regulatory affairs specialist scarcity:The intersection of pharmaceutical-grade manufacturing knowledge and food-law compliance expertise remains underdeveloped in emerging markets, constraining expansion velocity for multinational brands.
- Stability testing protocol divergence:Dissolution profile requirements vary between FDA, EFSA, and China's National Medical Products Administration standards, necessitating parallel validation studies that extend product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global General Well-Being Dietary Supplements Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Omega Fatty Acids, Probiotics Form: Tablets, Capsules, Powders, Liquid Concentrates, Gummies Application: Immune Support, Digestive Health, Stress Relief, Energy Boost, Skin Care End User: Adult Consumers, Senior Citizens, Athletes, Pregnant Women, Children |
| Companies Covered | Amway Corporation, Herbalife Ltd., Nestlé Health Science, Abbott Laboratories, Bayer AG, Haleon plc, Glanbia plc, Otsuka Holdings Co. Ltd., NOW Health Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global General Well-Being Dietary Supplements Market Shifts & Advancements
Biotechnology-enabled ingredient sourcing and regulatory technology integration are compressing traditional development cycles while fragmenting competitive advantage sources away from manufacturing scale toward data-driven personalization capabilities.
Precision fermentation is decomposing conventional agricultural extraction dependencies for high-value compounds including astaxanthin and resveratrol. Biotech startups in Singapore and the Netherlands deploy engineered yeast strains to produce bio-identical molecules at pharmaceutical purity grades, attracting venture funding that outpaces traditional ingredient supplier R&D budgets. This biotechnology transition is decomposing the historical moat of vertically integrated botanical extractors who controlled rare plant varietal access.
EFSA's evolving novel food classification framework reclassifies postbiotic formulations and engineered microbial cultures, requiring comprehensive toxicological dossiers that favor entities with existing pharmaceutical regulatory experience. The classification uncertainty delays shelf placement for innovative gut health products across German, French, and Italian retail pharmacies. Brands with established medical affairs departments redirect development toward ingredients with grandfathered status under earlier regulatory determinations.
Subscription-based replenishment models displace pharmacy-centric purchasing for routine micronutrient categories, with direct-to-consumer platforms capturing recurring revenue relationships previously controlled by retail intermediaries. This channel shift concentrates customer data ownership with formulation brands, enabling predictive inventory positioning and dynamic dosing adjustments based on consumption pattern analytics. The behavioral transition is most pronounced in United States and United Kingdom urban markets where convenience prioritization overrides traditional retail loyalty.
Global General Well-Being Dietary Supplements Market Segmentation
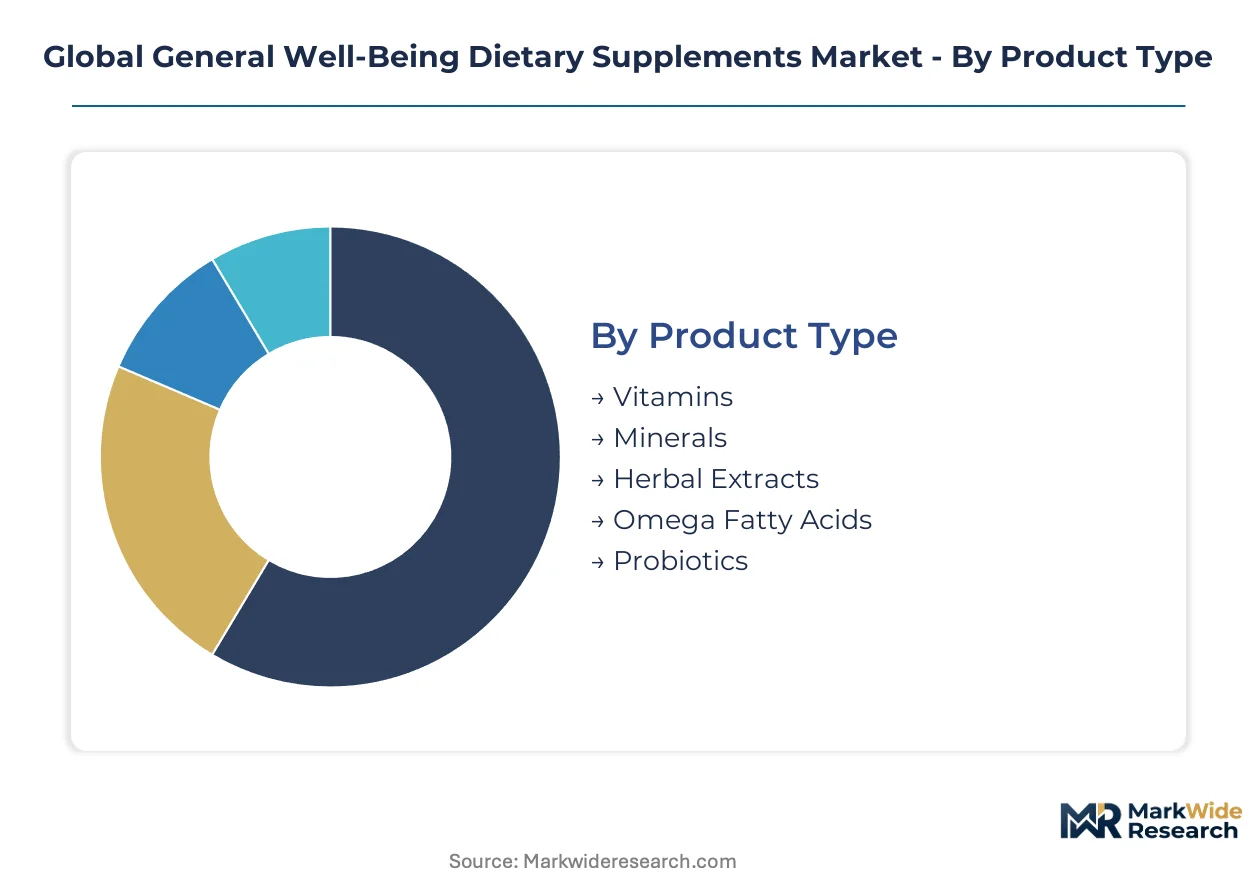
Segmentation in the dietary supplements sector determines formulation priorities, regulatory pathways, and channel economics. Product chemistry, delivery format, and consumer life-stage each impose distinct manufacturing constraints and margin structures that reshape competitive positioning across the value chain.
Product Type:
Substitute pressure from functional foods and fortified beverages concentrates most intensely on commodity micronutrient categories, while bioactive extracts and live cultures maintain stronger differentiation through clinical positioning.
- Vitamins:Synthetic and natural isolates standardized to USP or EP monographs, spanning fat-soluble and water-soluble compounds. Demand concentrates in Germany and the United States among senior citizens seeking bone health and cognitive maintenance, though pricing compression from private-label competition erodes branded margins.
- Probiotics:Live microbial cultures delivered at therapeutic colony-forming unit counts, requiring cold-chain or advanced encapsulation for viability. Expansion concentrates in China and Japan where gut-brain axis research drives premium positioning, with SAMR registration requirements filtering subclinical formulations from pharmacy shelves.
- Minerals:Chelated and inorganic salts formulated for bioavailability optimization, including calcium, magnesium, zinc, and iron variants.
- Herbal Extracts:Botanical concentrates standardized to marker compound percentages, spanning adaptogens, polyphenols, and alkaloid classes.
- Omega Fatty Acids:Marine and algal-derived EPA/DHA concentrates, plus plant-sourced ALA formulations.
Vitamins anchor the volume base while probiotics gains share at the steepest rate.
Form:
Manufacturing cost tiers separate high-speed tablet production from specialized gummy processing equipment, with capital intensity determining regional supply concentration and private-label accessibility.
- Gummies:Gelatin and pectin-based matrices delivering actives through flavored confectionery formats, requiring humidity-controlled production environments and shorter shelf-life specifications. Adoption concentrates in United States urban markets among adult consumers rejecting pill fatigue, with convenience prioritization overriding per-dose cost premiums.
- Capsules:Hard-shell gelatin and HPMC variants enabling powder, granule, or oil fills with modified-release capabilities. Demand clusters in Germany and Japan for probiotics and enzyme formulations where enteric protection commands clinical credibility, with EFSA dissolution standards filtering subscale suppliers.
- Tablets:Compressed powders with disintegration and hardness specifications, produced on high-speed rotary presses.
- Powders:Bulk active blends for scoop-dosed consumption, popular in sports nutrition and customizable stacking.
- Liquid Concentrates:Aqueous or oil-based solutions with emulsion stability requirements, targeting pediatric and geriatric swallowing difficulties.
Tablets dominate production tonnage while gummies expands most quickly among format categories.
Application:
Application-driven purchasing patterns fragment between seasonal immune cycles and daily maintenance routines, with subscription economics favoring chronic-use categories over acute-response positioning.
- Immune Support:Zinc, vitamin C, vitamin D, and elderberry formulations targeting respiratory defense and seasonal demand spikes. Purchasing concentrates in United States retail pharmacy channels with Q4 inventory build preceding influenza season, though post-pandemic normalization compresses baseline growth rates.
- Digestive Health:Probiotic, prebiotic, fiber, and enzyme formulations addressing microbiome modulation and regularity. Demand clusters in China and Japan where traditional fermented food cultures align with supplement adoption, with SAMR and PMDA registration pathways favoring strains with established safety dossiers.
- Stress Relief:Adaptogenic botanicals, magnesium, and B-complex variants targeting cortisol modulation and sleep quality.
- Energy Boost:Caffeine, B-vitamin, coenzyme Q10, and iron formulations addressing fatigue and metabolic support.
- Skin Care:Collagen peptides, hyaluronic acid, and antioxidant complexes positioned for dermal hydration and aging.
Immune support maintains the largest revenue footprint while digestive health climbs the fastest on microbiome research momentum.
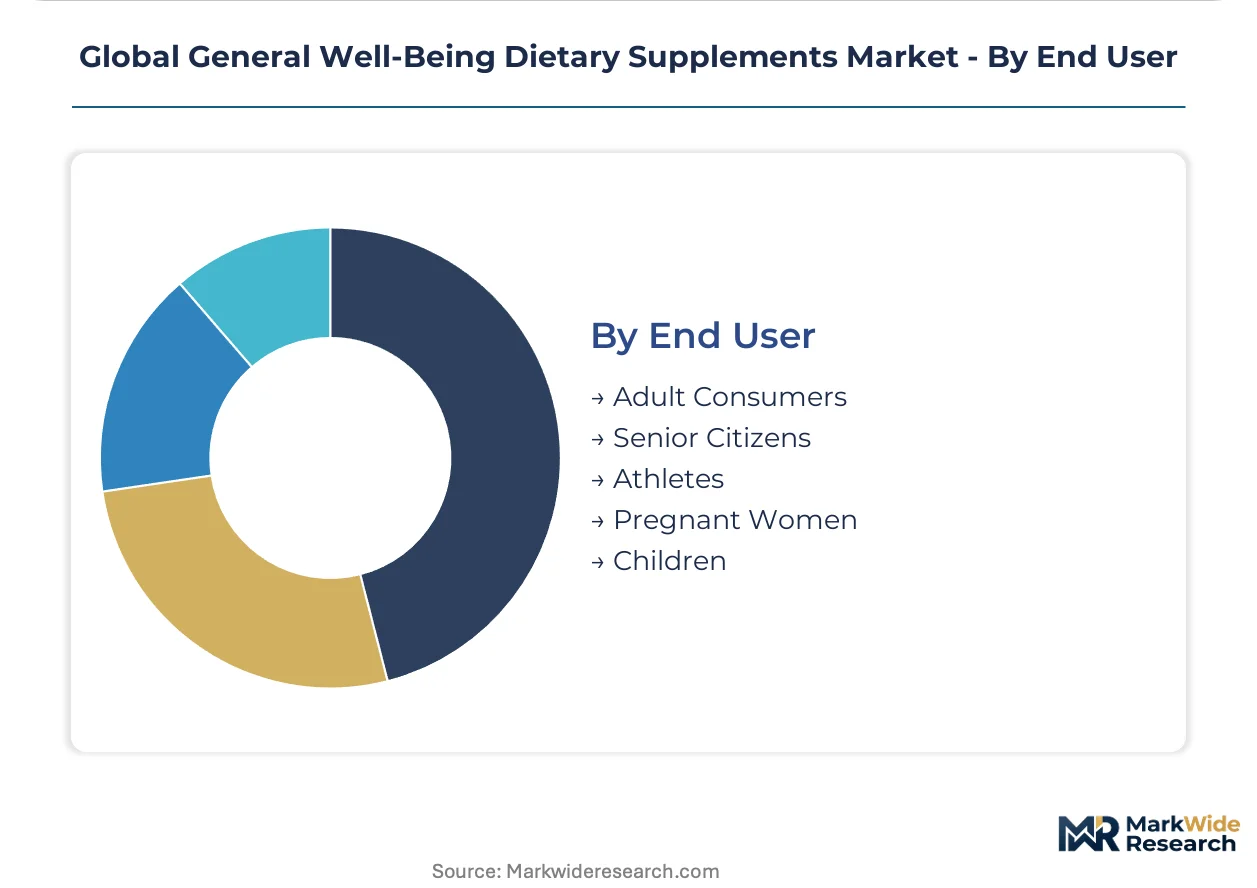
End User:
Life-stage targeting determines dosing precision requirements, with pediatric and pregnancy categories imposing the strictest purity and contamination thresholds.
- Senior Citizens:Formulations addressing sarcopenia, cognitive decline, bone density loss, and medication-nutrient interactions, typically requiring higher elemental mineral loads and simplified dosing schedules. Expenditure concentrates in Japan, Germany, and the United States where aging demographics and discretionary health spending align, with FDA CGMP enforcement filtering adulterated products from Medicare-eligible consumers.
- Adult Consumers:Broad-spectrum maintenance formulations spanning multivitamins, stress adaptogens, and metabolic support, representing the default positioning for mass-market SKUs. Demand clusters in United States direct-to-consumer channels where subscription models capture recurring replenishment, with algorithmic personalization elevating retention metrics above pharmacy-centric purchasing.
- Athletes:Performance and recovery formulations with NSF or Informed Sport certification requirements for banned-substance testing.
- Pregnant Women:Prenatal vitamin and mineral complexes with teratogenic risk screening and iron/folate prioritization.
- Children:Palatable formats with age-appropriate dosing and strict heavy metal limits, often gummy or liquid delivery.
Adult consumers anchor the volume base while senior citizens gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of Current Good Manufacturing Practices anchors the United States as the regulatory benchmark shaping compliance investments worldwide. Senior citizen expenditure and direct-to-consumer subscription models concentrate demand in specific national markets with aging demographics and digital commerce maturity.
United States
Senior citizens allocate disproportionate discretionary spending toward micronutrient supplementation and bone health formulations. FDA CGMP enforcement filters subscale manufacturers, concentrating market share among entities with dedicated quality infrastructure. The direct-to-consumer channel in urban coastal markets captures recurring revenue relationships through algorithmic personalization and subscription replenishment models.
China
Gut-brain axis research drives premium probiotic positioning among health-conscious middle-class consumers in tier-one cities. SAMR registration requirements filter subclinical formulations from pharmacy shelves, favoring strains with established safety dossiers. Yangtze River Delta manufacturing clusters reconfigure supply chains to meet dual carbon alignment incentives for sustainable packaging credentials.
Germany
Aging demographics prioritize preventive health maintenance through clinically positioned digestive health and cognitive support formulations. EFSA dissolution standards and health-claim substantiation requirements filter subscale suppliers from pharmacy retail channels. Bavaria-based pharmaceutical-grade manufacturing facilities anchor production for medical-positioned supplement exports across European markets.
Japan
Traditional fermented food cultures align with probiotic supplement adoption among senior citizens seeking microbiome modulation. PMDA registration pathways favor strains with established clinical evidence, creating barriers for novel microbial formulations. Kanto region retail pharmacies concentrate shelf placement for grandfathered ingredients under earlier regulatory determinations.
India
Health-conscious middle-class consumers in metropolitan centers drive multivitamin and mineral supplementation adoption. FSSAI mandates domestic manufacturing or joint venture structures for imported formulations, creating first-mover advantages for localized production. Maharashtra and Gujarat pharmaceutical clusters attract contract manufacturing investments from multinational brands seeking market access ahead of enforcement tightening.
Global General Well-Being Dietary Supplements Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational nutrition conglomerates and direct-selling networks occupying distinct competitive positions. The market structure fragments across pharmaceutical-grade manufacturers, community-based distributor models, and mass-market retail suppliers. Three archetypes dominate: vertically integrated nutrition conglomerates with medical-grade portfolios, direct-selling organizations leveraging personalized consultation infrastructure, and specialist ingredient suppliers with fermentation or extraction capabilities. Competitive moves concentrate on regulatory compliance infrastructure expansion and subscription-based customer relationship models.
Within the integrated conglomerate tier, Nestlé Health Science and Abbott Laboratories exemplify pharmaceutical-grade positioning through medical affairs departments and clinical evidence portfolios. Amway Corporation anchors the direct-selling archetype, leveraging personalized nutrition consultations in markets where registered dietitian shortages limit professional guidance access. Bayer AG and Haleon plc occupy mass-market retail positions, with heritage consumer health brands providing distribution scale across pharmacy and grocery channels.
| Leading Market Players |
|---|
| Amway Corporation |
| Herbalife Ltd. |
| Nestlé Health Science |
| Abbott Laboratories |
| Bayer AG |
| Haleon plc |
| Glanbia plc |
| Otsuka Holdings Co. Ltd. |
| NOW Health Group Inc. |
| Others |
Supply & Pricing Matrix
Precision fermentation replacing agricultural extraction for astaxanthin and resveratrol simultaneously relocates production to Singapore and Netherlands biotech clusters while collapsing historical botanical scarcity premiums that Peruvian and Moroccan extractors commanded.
Pricing Analysis
Contract structures bifurcate between long-term offtake agreements for pharmaceutical-grade probiotic strains and spot-market purchasing for commodity vitamin isolates. Three-tier pricing structure across premium, standard, and economy levels separates medical-positioned formulations with USP certification from private-label grocery SKUs. Pricing pressure stems from fortified functional foods capturing wellness-oriented consumers in United States convenience channels. Adult subscription purchasers show lowest price sensitivity while senior citizens in Medicare-eligible demographics prioritize verified quality over per-dose cost.
Supply Chain Analysis
Peru and Morocco anchor marine-derived omega-3 and specialty botanical extraction, while China and India concentrate synthetic vitamin and mineral production. Raw material flows draw from Antarctic krill fisheries, Moroccan argan cooperatives, and Yangtze River Delta fermentation facilities. Single-source vulnerability runs through Peruvian anchovy harvest quotas governing EPA/DHA concentrate availability. Distribution runs through direct-to-consumer subscription platforms displacing pharmacy-centric replenishment in United States and United Kingdom urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as fortified beverages and nutrient-dense snack formats capture overlapping wellness consumers in convenience-oriented retail channels.
For Market Incumbents: Fortify regulatory affairs infrastructure against EFSA novel food reclassifications and FDA CGMP enforcement tightening that filters subscale competitors. Deepen backward integration into precision fermentation capabilities to neutralize agricultural extraction cost volatility from climate-pressured harvest regions. Prioritize microbiome-specific claim substantiation dossiers ahead of regulatory clarity windows.
For New Entrants and Emerging Players: Differentiate on personalized nutrition subscription models integrating at-home microbiome testing with algorithmic supplement curation. Target India's FSSAI localization pathway ahead of enforcement tightening, establishing domestic manufacturing or joint venture structures in Maharashtra and Gujarat pharmaceutical clusters. Deploy community-based distributor networks replicating advisory relationships in markets with registered dietitian shortages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with direct-selling organizations possessing personalized consultation infrastructure and recurring revenue subscription bases. Five-to-ten year viability hinges on regulatory technology integration compressing development cycles and data-driven personalization capabilities fragmenting competitive advantage sources. Monitor EFSA health-claim substantiation determinations as inflection indicators for novel ingredient commercialization scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Integration | Automated EFSA and FDA compliance monitoring accelerates novel ingredient time-to-market across European and United States jurisdictions. |
| Precision Fermentation Scale-Up | Engineered yeast strain production of bio-identical compounds at pharmaceutical purity grades decomposes botanical extraction dependencies. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models capture recurring revenue relationships and customer data ownership previously held by retail intermediaries. |
| India FSSAI Localization Partnership | Domestic manufacturing or joint venture structures create first-mover advantages ahead of imported formulation enforcement tightening. |
| Microbiome Testing Integration | At-home gut health diagnostics paired with algorithmic curation transforms one-time purchasers into elevated lifetime value relationships. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with regulatory affairs directors, formulation scientists, pharmacy category buyers, and direct-selling network operators; and secondary validation against FDA warning letters, EFSA novel food opinions, SAMR registration databases, and customs trade records. Bottom-up triangulation across product-level volume estimates and top-down macroeconomic anchoring ensured convergence. Primary fieldwork spanned United States, Germany, China, and India market participants.
Across the analysis window, forecasts model product type segmentation spanning vitamins, probiotics, minerals, herbal extracts, and omega fatty acids; form factors including gummies, capsules, tablets, powders, and liquid concentrates; and end-user categories from senior citizens through pediatric populations. CAGRs derive from regression-based trajectory fitting against historical regulatory approval timelines and demographic expenditure elasticities. Forecast inputs incorporate dissolution profile standard divergence between FDA, EFSA, and NMPA jurisdictions.
Material uncertainties — regulatory reclassification of postbiotics, climate-induced harvest volatility in concentrated sourcing regions, and functional food substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding enforcement consistency and consumer format preference stability. Recalibration cycles align with material shifts in novel food classification determinations and microbiome claim pathway clarity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Mediterranean Metabolic Syndrome Support Ingredient Packs Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Water Soluble Vitamin and Mineral Feed Supplements Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
Omega-3 Fatty Acids Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Mood Support Supplements Market