
 North America Ink Market | 2026-2036
North America Ink Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ink Market Intelligence
Specialty ink distribution through regional master distributors is reconfiguring as direct manufacturer-to-converter relationships strengthen. Sun Chemical leverages its pigment manufacturing base to control raw material flows into North American packaging plants. INX International Ink Co anchors flexible packaging ink supply across the Midwest through dedicated technical service teams. Flint Group North America competes in publication gravure segments while extending UV product lines for narrow-web label converters.
Ink comprises a fluid or paste suspension of pigments, dyes, resins, solvents, and additives engineered to transfer visual information onto substrates through printing processes, with viscosity typically ranging from 10 to 100,000 centipoise depending on application method. Its primary purpose spans commercial communication, product identification, decorative finishing, and functional coating across paper, plastic, metal, and textile surfaces. Water-based formulations lead volume in corrugated packaging due to environmental compliance pressures, while UV-curable systems command premium positioning in digital label and narrow-web applications where instant drying and scratch resistance justify higher formulation costs. Specialty additive blends for security printing and conductive electronics represent emerging margin pools as functional ink requirements expand beyond conventional color reproduction.
EPA VOC emissions standards and California Air Resources Board (CARB) consumer product regulations constrain solvent-based formulation sales while creating compliance-driven replacement cycles. OSHA workplace exposure limits for glycol ethers and heavy metals shape manufacturing plant investments and reformulation timelines across U.S. production facilities. Stakeholders must monitor state-level extended producer responsibility legislation in New York and California, as packaging ink recyclability requirements will determine formulation investment priorities and customer qualification timelines.
Market Dynamics
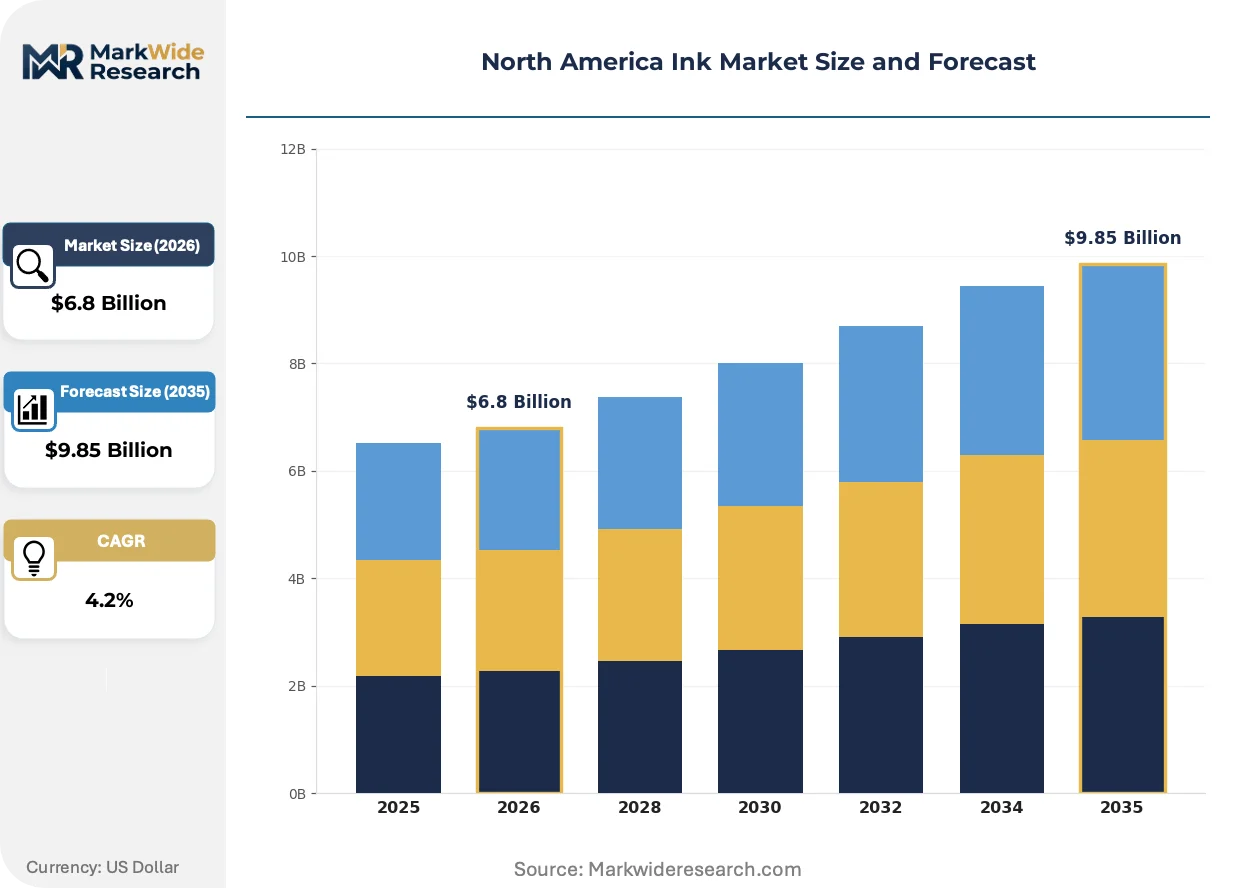
Packaging converters across the United States and Canada are accelerating UV-curable ink adoption for food-contact substrates, while EPA VOC regulations and state-level air quality mandates compress solvent-based formulation cycles and redirect capital toward water-based and low-emission alternatives.
Growth Catalysts
- EPA VOC Emissions Standards:Federal limits on volatile organic compounds from printing operations force solvent-based ink replacement cycles, creating sustained demand for compliant water-based and UV-curable alternatives across corrugated and flexible packaging plants.
- E-commerce fulfillment expansion:Amazon, Walmart, and regional logistics hubs require high-speed digital printing for variable data labels and corrugated secondary packaging, pulling UV ink volumes into Midwest distribution centers.
- Photoinitiator chemistry advances:Migration-compliant UV formulations now achieve food-contact safety certification for direct substrate printing, opening dairy, meat, and produce packaging segments previously blocked by regulatory barriers.
Market Restraints
- Petroleum-derived resin volatility:Acrylic and polyurethane resin feedstocks track crude oil and natural gas price swings, compressing formulation margins when energy markets spike and complicating annual contract pricing with packaging converters.
- Pigment supply concentration:Specialty organic pigments for high-performance inks concentrate among Asian chemical manufacturers, exposing North American ink producers to freight cost surges and customs processing delays.
- UV equipment capex barriers:Narrow-web label converters face capital requirements for LED curing systems and press retrofits that delay technology transitions beyond formulation availability.
Strategic Opportunities
- Extended producer responsibility laws:New York and California packaging recyclability mandates will require ink formulations compatible with mechanical recycling streams, creating first-mover advantage for deinkable and wash-off coating technologies.
- Conductive and functional inks:Printed electronics for smart packaging, RFID antennae, and touch-sensitive surfaces represent margin expansion beyond commodity color reproduction into pharmaceutical authentication and cold-chain monitoring.
- Direct-to-object digital printing:Bottle, tube, and container decoration bypasses label converters entirely, enabling ink suppliers to capture value previously lost to pressure-sensitive substrate manufacturers.
Industry Challenges
- Formulation chemist scarcity:UV-curable and water-based ink development requires specialized expertise in photoinitiator stability, rheology control, and substrate adhesion that outpaces university polymer science program output.
- Food-contact notification timelines:FDA food-contact substance notifications require months of migration testing and toxicology review, delaying new product launches and locking in incumbent formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ink Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-Based, Water-Based, UV-Curable, Eco-Friendly Application: Packaging, Commercial Printing, Digital Printing, Industrial Use Formulation: Conventional, High-Performance, Specialty, Additive End User: Printers, Packaging Companies, Manufacturers, Retailers |
| Companies Covered | Sun Chemical, INX International Ink Co, Flint Group North America, FUJIFILM, CR/T, Siegwerk Druckfarben AG & Co. KGaA, DuPont, EFI, Kao Collins Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ink Market Strategic Shifts & Innovations
Digital printing systems are compressing run-length economics and reshaping how packaging converters specify ink procurement, with technology vendors and chemical formulators racing to align product development cycles with shorter print job turnover.
Single-pass inkjet printheads with native UV-curable ink compatibility are digitizing corrugated post-print and folding carton segments previously dominated by flexographic and offset equipment. Amazon's regional fulfillment network and independent e-commerce packaging specialists are installing these systems at accelerating pace. The technology is digitizing job quoting, artwork versioning, and inventory management workflows that previously required days of prepress preparation.
California Air Resources Board consumer product regulations are tightening residual solvent limits in packaging inks, forcing reformulation of legacy gravure and flexo products for snack food and confectionery applications. CARB's 2027 compliance deadlines compress development timelines for low-VOC alternatives. Flexible packaging converters in the Central Valley and Los Angeles basin are qualifying water-based laminating adhesives and ink systems ahead of enforcement windows.
Converter procurement teams are consolidating supplier relationships and demanding technical service integration that bundles ink supply with color management, press optimization, and waste reduction consulting. This vendor consolidation displaces traditional master distributor networks in the Midwest and Southeast. The shift concentrates most visibly among mid-sized folding carton and label converters seeking to reduce formulation qualification overhead.
North America Ink Market Segmentation
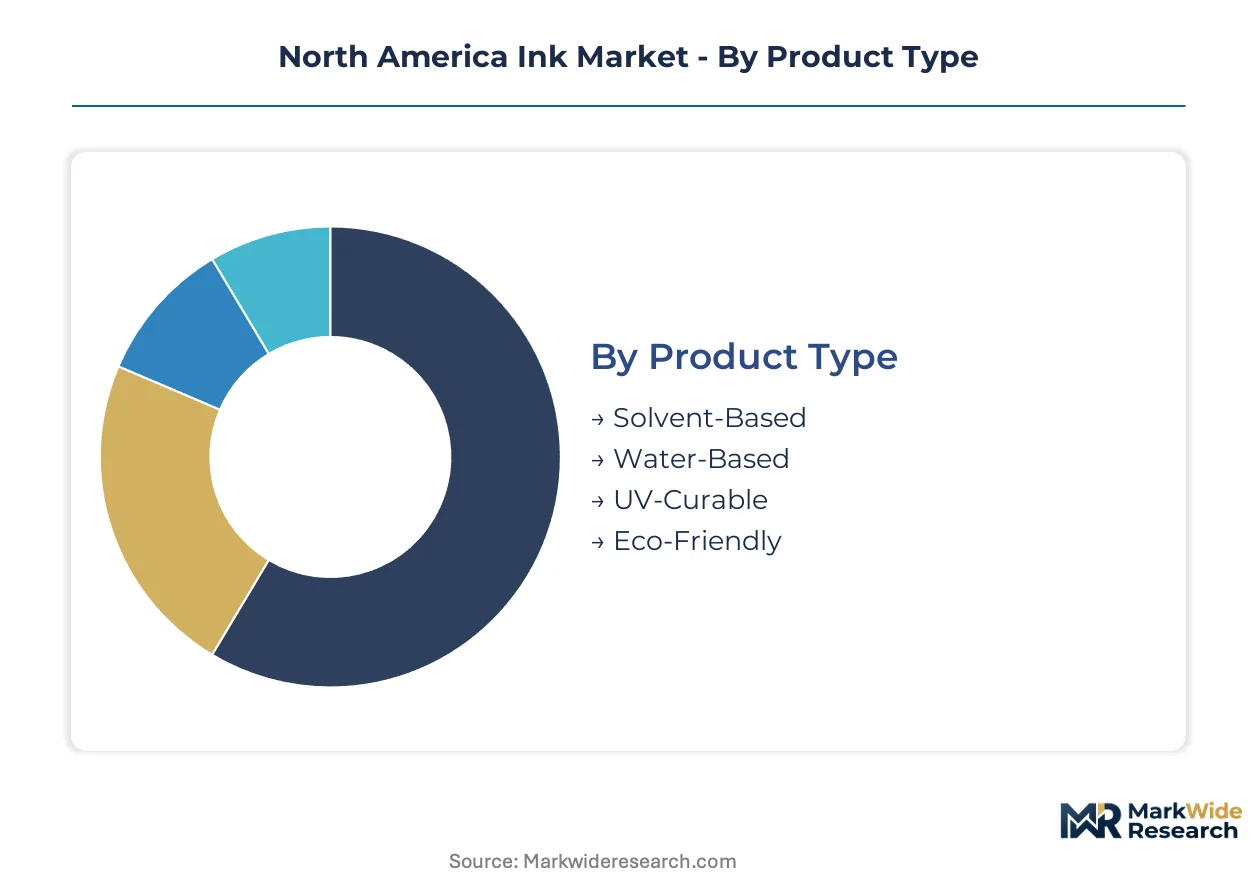
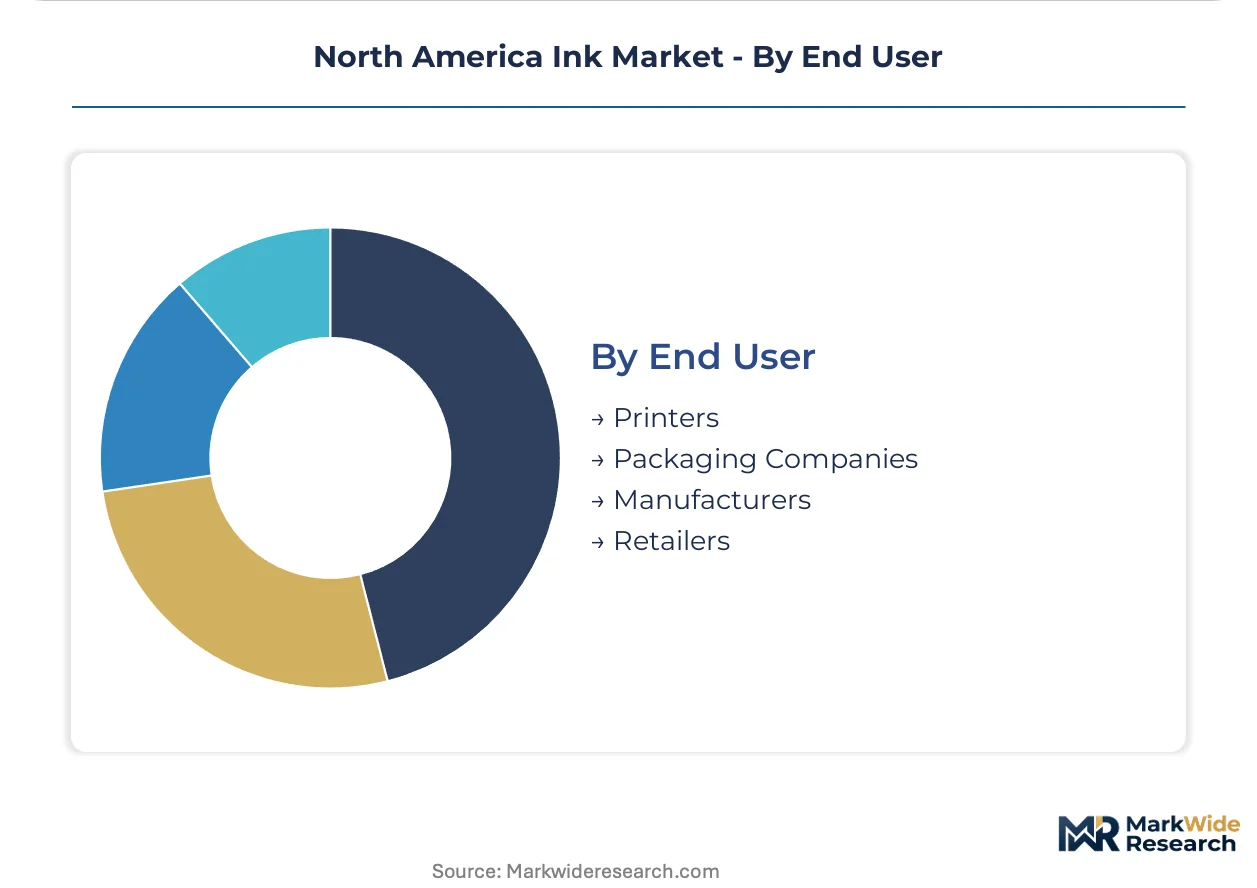
Segmentation in North American ink markets reveals how formulation chemistry, application requirements, and end-user procurement power create distinct competitive arenas. Understanding these boundaries exposes where margin pools concentrate and where technology transitions accelerate replacement cycles.
Product Type:
Reformulation cycles vary dramatically across chemistries, with regulatory pressure compressing some segments to 18-month refresh timelines while legacy systems endure decade-long equipment amortization.
- Water-Based:Acrylic and polyurethane resin dispersions in aqueous carriers dominate corrugated packaging across the Great Lakes manufacturing corridor. EPA VOC enforcement and California CARB mandates are forcing snack food and beverage converters to complete system conversions ahead of 2027 compliance deadlines.
- UV-Curable:Photoinitiator-activated oligomer systems cure instantly under LED or mercury arc lamps, enabling high-speed digital production without thermal substrate damage. Migration-compliant formulations now achieve FDA food-contact certification for direct dairy and meat packaging printing, opening segments previously blocked by safety barriers.
- Solvent-Based:Nitrocellulose and polyamide resin solutions in hydrocarbon carriers retain grip in legacy gravure publication printing and some flexible packaging laminating adhesives where substrate adhesion requirements resist water-based alternatives.
- Eco-Friendly:Bio-derived resin systems and vegetable oil-based vehicles target brand sustainability commitments and emerging extended producer responsibility legislation in New York and California packaging recyclability frameworks.
Water-based formulations dominate installed base across corrugated and folding carton plants. UV-curable systems are where expansion concentrates as narrow-web label and single-pass corrugated digital presses multiply.
Application:
Print job length economics and substrate versatility requirements divide procurement specifications and technical service bundling approaches.
- Packaging:Flexible film, folding carton, and corrugated secondary packaging consume the majority of North American ink volume. Amazon and Walmart fulfillment networks are pulling UV ink volumes into Midwest distribution centers for variable-data secondary packaging.
- Digital Printing:Single-pass inkjet and toner-based systems for labels, direct mail, and transactional documents command premium formulation pricing for particle size control, jettability, and fusing compatibility.
- Commercial Printing:Offset lithographic and sheetfed applications for catalogs, directories, and marketing collateral face secular decline as media consumption shifts, compressing formulation volumes outside specialty niche markets.
- Industrial Use:Decorative coatings for building products, automotive components, and electronics housings require durability specifications including UV resistance, chemical tolerance, and abrasion hardness beyond graphic arts requirements.
Packaging commands the largest share of formulation volume. Digital printing applications are climbing the fastest as run lengths compress and versioning requirements multiply.
Formulation:
Development intensity and intellectual property protection separate commodity production from specialty margin capture.
- High-Performance:Engineered for extreme durability, chemical resistance, or optical density specifications in outdoor signage, automotive component decoration, and pharmaceutical blister packaging where failure costs exceed formulation premiums.
- Specialty:Security inks with taggant authentication, thermochromic color change, or conductive functionality for smart packaging and printed electronics applications represent emerging margin pools beyond commodity color reproduction.
- Conventional:Standard pigment dispersions and dye solutions for general commercial printing where price competition dominates procurement decisions and technical service differentiation remains minimal.
- Additive:Defoamers, wetting agents, rheology modifiers, and adhesion promoters sold as separate formulation components for converter in-house blending and press-side customization.
Conventional formulations dominate transaction volume. High-performance and specialty categories are where formulation investment and patent protection concentrate.
End User:
Procurement sophistication and technical service requirements shape how ink suppliers structure customer relationships and pricing architecture.
- Packaging Companies:Integrated converters with in-house prepress, printing, and finishing operations demand bundled supply contracts combining ink, technical service, color management, and waste reduction consulting.
- Printers:Commercial and publication printing houses with legacy equipment fleets prioritize formulation consistency and press-side troubleshooting support over chemistry innovation.
- Manufacturers:Industrial coating operations for building products, appliances, and transportation equipment specify ink systems as part of broader surface finishing process engineering.
- Retailers:Private-label brand owners and e-commerce fulfillment operators are increasingly specifying ink requirements for contract packaging suppliers, particularly for food-contact safety and sustainability certifications.
Packaging companies dominate formulation volume procurement. Retailers are gaining specification influence fastest as brand sustainability requirements flow through supply chain compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States packaging converters command formulation pricing power through direct manufacturer relationships, while Canadian operations absorb freight premiums on pigment imports from Asian chemical suppliers.
United States
EPA VOC emissions standards and California Air Resources Board mandates force solvent-based ink replacement cycles across corrugated and flexible packaging plants. FDA food-contact substance notification requirements delay new UV-curable product launches for dairy and meat packaging segments. The Great Lakes manufacturing corridor anchors integrated packaging hubs supplying beverage, pharmaceutical, and Amazon fulfillment networks.
Canada
Health Canada food-contact regulations align with FDA safety frameworks while maintaining separate notification requirements for novel photoinitiator chemistries. Provincial air quality mandates in Ontario and Quebec accelerate water-based formulation transitions among flexible packaging converters. The Toronto-Waterloo industrial corridor concentrates technical service teams supporting narrow-web label and folding carton operations.
Mexico
Nearshoring investments by US brand owners expand folding carton and flexible film capacity for cross-border supply chains. Mexican environmental regulations under SEMARNAT tighten residual solvent limits in packaging inks serving export markets. The Mexico City metropolitan area and Nuevo León industrial corridor attract ink technical service operations supporting converted packaging exports.
North America Ink Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream controlling pigment dispersion and photoinitiator supply. The North American ink market structures around three tiers: multinational chemical conglomerates with captive raw material positions, mid-sized regional formulators with technical service bundling, and niche specialists in security or conductive functionalities. Consolidation pressures concentrate among mid-tier players as direct manufacturer-to-converter relationships displace traditional master distributor networks. Competitive moves center on backward integration into pigment manufacturing and geographic expansion of technical service teams.
Among multinational chemical suppliers, Sun Chemical and INX International Ink Co exemplify platform integrators with upstream pigment control and regional technical service density. Flint Group North America occupies a position bridging publication gravure heritage with UV-curable expansion for narrow-web label converters.
| Leading Market Players |
|---|
| Sun Chemical |
| INX International Ink Co |
| Flint Group North America |
| FUJIFILM |
| CR/T |
| Siegwerk Druckfarben AG & Co. KGaA |
| DuPont |
| EFI |
| Kao Collins Corporation |
| Others |
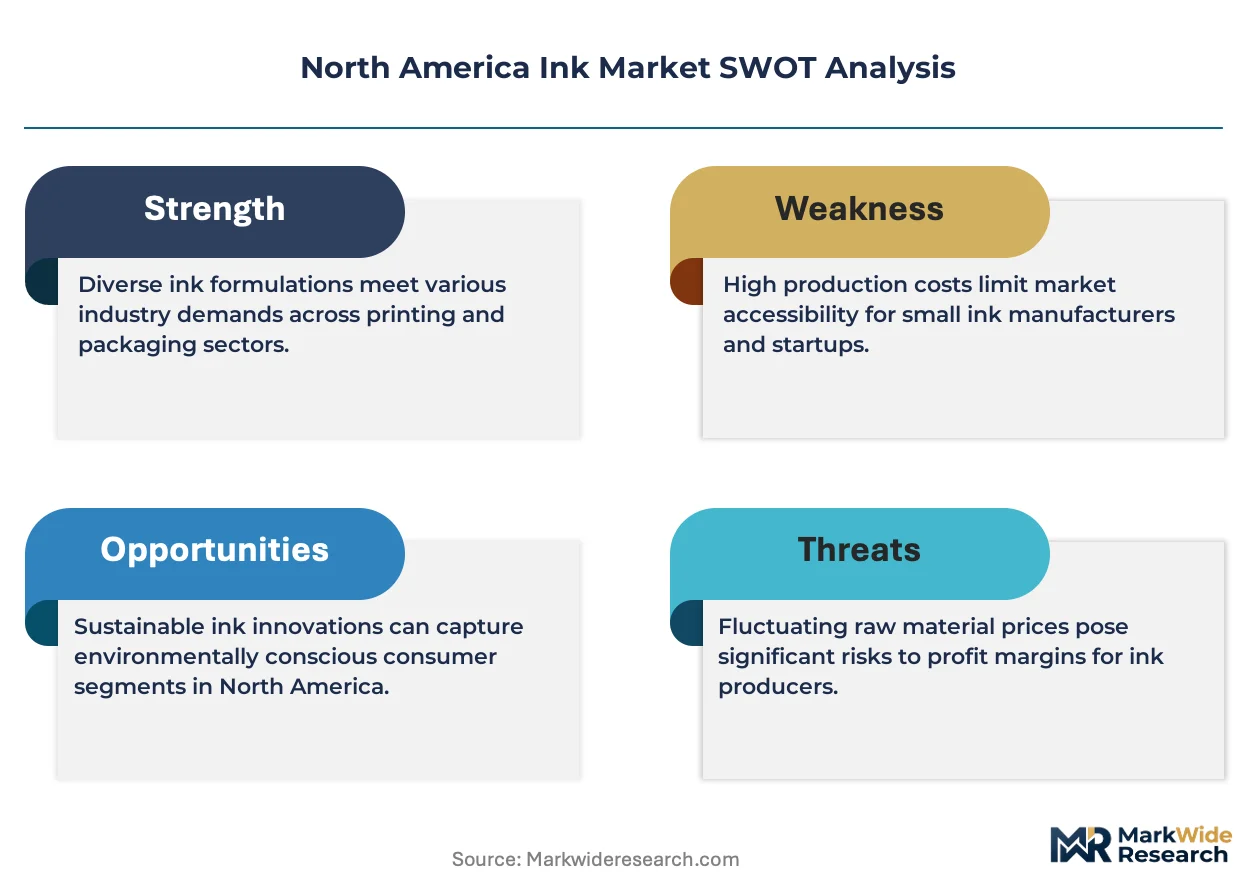
Cost & Logistics Intelligence
Petroleum-derived resin volatility determines both formulation margin compression and procurement contract structures across North American ink markets. Acrylic and polyurethane feedstock exposure to crude oil and natural gas price swings compresses spreads between commodity water-based formulations and premium UV-curable systems, while simultaneously forcing converters toward longer-term supply agreements that lock in pigment access from Asian chemical manufacturers.
Pricing Analysis
Configured-to-order pricing for migration-compliant UV formulations commands substantial premiums over standard water-based commodity grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with FDA food-contact notification status and California CARB compliance acting as the primary price escalators. Cost compression in solvent-based segments is intensifying because EPA VOC enforcement accelerates replacement cycles. Mid-sized folding carton converters exhibit highest price sensitivity, while pharmaceutical and dairy packaging specialists prioritize safety certification over unit economics.
Supply Chain Analysis
Contract manufacturing concentration for specialty organic pigments rests with Chinese and Indian chemical producers, with South Korean manufacturers holding secondary positions in photoinitiator synthesis. Raw material dependencies center on petroleum-derived acrylic resins, titanium dioxide white pigments, and photoinitiator chemistries subject to freight cost surges and customs processing delays. Single-source vulnerability concentrates in high-performance organic pigments for narrow-web label applications. Distribution runs through direct manufacturer-to-converter relationships displacing traditional master distributor networks across the Great Lakes and Southeast regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-curable formulation advances represent a high-growth disruption as FDA food-contact certification opens dairy and meat packaging segments previously blocked by migration safety barriers.
For Market Incumbents: Build regulatory certification moats by accelerating FDA food-contact substance notifications for novel photoinitiator chemistries ahead of competitor filing timelines. Deepen backward integration into pigment dispersion capabilities to control raw material flows threatened by Asian supply concentration. Expand technical service team density across the Great Lakes manufacturing corridor to defend against direct relationship erosion from emerging formulators. For New Entrants and Emerging Players: Canadian flexible packaging converters outside the Toronto-Waterloo corridor present geographic underpenetration with lower incumbent technical service saturation. Target conductive and functional ink segments for smart packaging applications where formulation expertise scarcity limits rapid incumbent response. Pursue private-label brand owner specification influence as retailers increasingly mandate sustainability certifications for contract packaging suppliers. For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors specialty formulators with food-contact certification capabilities and deinkable coating intellectual property. Long-term viability over the next decade hinges on extended producer responsibility law alignment in New York and California packaging recyclability frameworks. Watch for LED curing equipment capex acceleration among narrow-web label converters as inflection indicator for UV ink volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Manufacturing | Sun Chemical's captive raw material control insulates margin structures from Asian supply disruptions. |
| Migration-Compliant UV Formulation Development | FDA food-contact certification unlocks dairy and meat packaging segments with premium pricing power. |
| Technical Service Team Geographic Expansion | INX International's Midwest density captures converter procurement consolidation toward bundled supply contracts. |
| Deinkable Coating Technology Investment | New York and California extended producer responsibility laws create first-mover advantage for recyclability-compatible formulations. |
| Direct-to-Converter Relationship Building | Flint Group's narrow-web label focus bypasses master distributor networks eroding across the Southeast. |
Research Approach
The analysis maps water-based, UV-curable, solvent-based, and eco-friendly formulation chemistries, each validated through packaging converter procurement directors, ink formulation chemists, and regulatory affairs specialists. Primary interviews with plant managers at corrugated and flexible packaging facilities combined with secondary validation from EPA enforcement records, FDA food-contact substance notifications, California CARB regulatory filings, and customs trade data. Bottom-up volume estimates triangulated against top-down industry aggregation across the North American production footprint.
Assumptions held fixed include EPA VOC emission standards and California CARB compliance deadlines, while variables modeled encompass e-commerce fulfillment expansion rates and LED curing equipment adoption curves. Segmentation dimensions span formulation chemistry, application method, performance tier, and end-user procurement sophistication. CAGRs derived from historical volume trajectories adjusted for regulatory replacement cycle acceleration and technology transition elasticities. Forecast inputs incorporate photoinitiator chemistry advance timelines and extended producer responsibility legislation implementation schedules.
Practitioners should monitor petroleum resin price volatility, FDA food-contact notification approval velocities, and state-level packaging recyclability mandate progression for early signals of forecast deviation. Forecasts reflect documented assumptions subject to revision from macroeconomic energy market shifts or regulatory enforcement intensity changes. Quarterly review of LED curing equipment installation rates and converter qualification timelines for migration-compliant formulations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Textile Printing Ink Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Specialty Ink Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Flexo-Ink Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Flexographic Printing Inks Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Anti-Counterfeit Printing Ink Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Molecular Ink Market
Printing Inks
Radiation Curable Inks Market