
 Global Digital Fabrication Inkjet Inks Market | 2026-2036
Global Digital Fabrication Inkjet Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Fabrication Inkjet Inks Market Analysis
Drop-on-demand piezoelectric printhead architectures with variable droplet control is reshaping how industrial manufacturers execute short-run customization and mass personalization workflows. DuPont leverages its materials science heritage to sustain pigment dispersion leadership across textile and graphic arts segments. HP anchors North American supply relationships through integrated print system ecosystems that bundle ink chemistry with hardware platforms. Fujifilm Sericol International specializes in UV-curable formulations that dominate high-speed packaging lines across Asian manufacturing hubs.
Digital fabrication inkjet inks comprise formulated fluid systems engineered for precise deposition through piezoelectric or thermal inkjet mechanisms, typically containing colorants, vehicle solvents, humectants, and rheology modifiers tuned to sub-picoliter droplet accuracy and substrate-specific adhesion. These formulations enable direct digital patterning onto textiles, corrugated boards, ceramics, and three-dimensional objects without intermediate plates or screens. UV-curable ink chemistry commands premium positioning in packaging applications where instant polymerization supports single-pass throughput demands, while aqueous systems retain cost advantages in graphic arts and textile segments where porous substrates dominate. Single-pass technology architectures are displacing multi-pass systems in high-volume industrial settings, though hybrid configurations preserve flexibility for job-shop print service providers managing diverse substrate portfolios.
EPA oversight of volatile organic compound emissions constrains solvent-based ink formulations in US manufacturing facilities, while REACH registration requirements in Europe mandate comprehensive chemical safety documentation for imported ink constituents. China's MEE enforces wastewater discharge standards that elevate aqueous ink treatment costs for Guangdong province converters. Japan's METI promotes JIS-compliant industrial ink standards that influence procurement specifications across Northeast Asian supply chains. Stakeholders must monitor evolving chemical restriction timelines and assess regional formulation registration burdens before committing capital to multi-country production footprints.
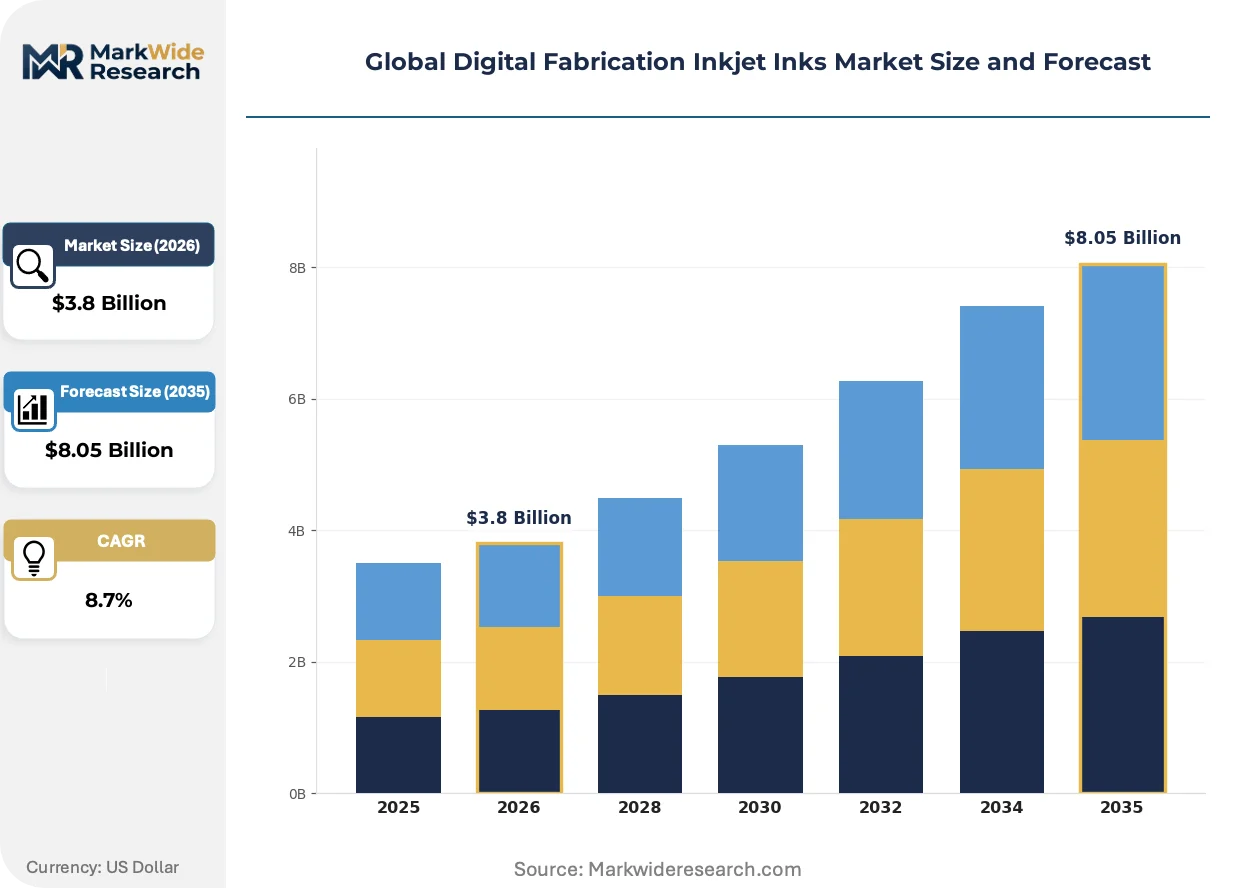
Market Dynamics
Single-pass inkjet architectures are compressing production cycle times for corrugated packaging converters, forcing formulation suppliers to engineer UV-curable chemistries that polymerize instantly at belt speeds exceeding 300 meters per minute.
Growth Catalysts
- REACH chemical registration thresholds:European ECHA mandates are accelerating substitution of legacy solvent-based systems with aqueous and UV-curable alternatives across textile printing clusters.
- Pigment dispersion advances:Nanoparticle stabilization technologies are unlocking direct-to-fabric printing on synthetic blends previously restricted to reactive dye workflows.
- Guangdong province industrial concentration:Export-oriented packaging converters in China's Pearl River Delta are aggregating demand for high-throughput single-pass systems serving cross-border e-commerce fulfillment.
Market Restraints
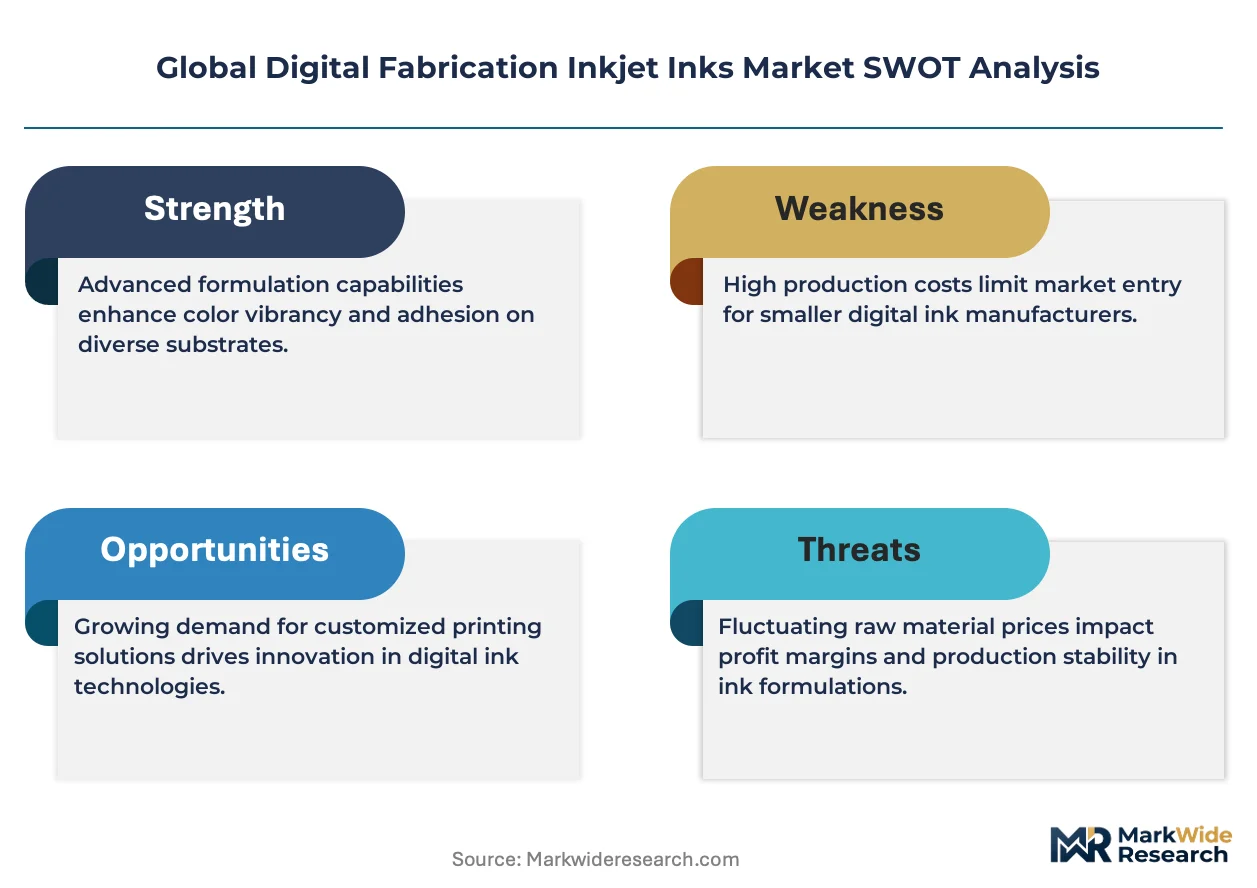
- Photoinitiator supply concentration:Specialty chemical production for UV-curable formulations clusters among German and Japanese suppliers, creating input vulnerability.
- Substrate adhesion limitations:Low-surface-energy polyolefin films require corona or plasma pretreatment, adding capital burden for converters.
- EPA VOC emission ceilings:Solvent-based inkjet formulations face escalating compliance costs in US manufacturing facilities.
Strategic Opportunities
- Vietnam textile printing expansion:Relocating apparel manufacturing is creating greenfield demand for pigment ink systems in Ho Chi Minh City industrial zones.
- CE marking convergence:Harmonized EU safety standards are reducing multi-country registration burdens for ink suppliers targeting European packaging converters.
- Ceramic tile decoration:Digital inkjet is penetrating fired ceramic surfaces previously dominated by rotary screen printing in Italian and Spanish manufacturing hubs.
Industry Challenges
- Color management expertise gaps:Industrial converters lack ICC profiling specialists capable of calibrating multi-head arrays across heterogeneous substrate inventories.
- Printhead-chemistry matching complexity:Piezoelectric actuator materials degrade when exposed to incompatible solvent packages, forcing iterative formulation testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Fabrication Inkjet Inks Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Textile Printing, Packaging, Industrial Marking, Graphic Arts Ink Type: UV-Curable, Aqueous, Solvent-Based, Dye-Based End User: Manufacturers, Retailers, Designers, Print Service Providers Technology: Single Pass, Multi Pass, 3D Printing, Hybrid Systems |
| Companies Covered | DuPont, Sensient Imaging Technologies, HP, Wikoff Color, Van Son Holland Ink, EPSON, Nazdar, TRIDENT, Fujifilm Sericol International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Fabrication Inkjet Inks Market Emerging Trajectories
Water-based pigment systems are capturing share from reactive dyes in textile applications, while regulatory pressure on chemical constituents is forcing reformulation investments across all ink categories.
Single-pass UV-curable inkjet is digitizing corrugated board production for e-commerce shipping boxes. Amazon-qualifying packaging suppliers in the US Midwest are retrofitting flexographic lines with inkjet arrays. This technology is compressing make-ready times from hours to minutes for short-run custom box orders.
Japan's METI is tightening JIS standards for industrial ink formulations used in food-contact packaging applications. Exporters to Northeast Asian markets must document complete constituent disclosure. Japanese converters are demanding third-party certified inks to preempt downstream liability exposure.
Brand owners are consolidating print procurement through managed print service contracts rather than spot purchasing from job shops. European cosmetic and personal care companies are bundling packaging print requirements under multi-year agreements with integrated hardware-ink suppliers. This concentration is visible most acutely in German and French manufacturing corridors where sustainability scorecards drive vendor selection.
Global Digital Fabrication Inkjet Inks Market Segmentation
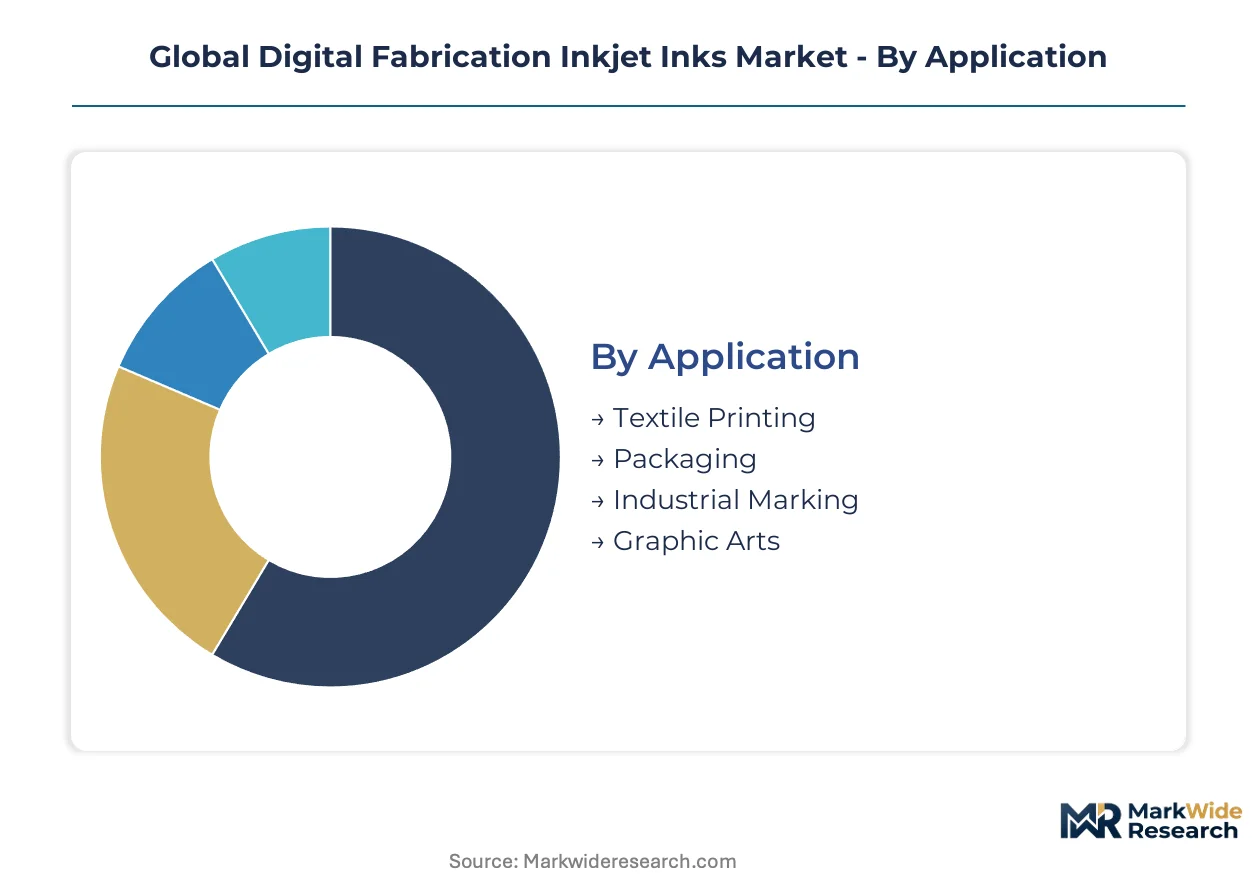
Digital fabrication inkjet inks exhibit divergent formulation requirements across application contexts, with cycle times ranging from instant UV polymerization on packaging lines to extended drying protocols for textile absorption. Segmentation clarity enables suppliers to align R&D investments with specific viscosity, surface tension, and adhesion demands rather than pursuing universal formulations.
Application:
Textile printing cycles stretch across minutes for fixation and washing, while packaging lines demand sub-second ink-to-handling intervals.
- Textile Printing:Pigment dispersions stabilized through polymeric dispersants enable direct-to-fabric deposition on polyester-cotton blends without steaming or washing stages. Bangladesh and Vietnam converters are migrating from reactive dye workflows to pigment systems to compress water-intensive processing.
- Packaging:UV-curable oligomer formulations polymerize instantly under LED arrays at belt speeds exceeding 300 meters per minute. Guangdong province converters serving cross-border e-commerce fulfillment aggregate demand for single-pass corrugated board systems.
- Industrial Marking:Solvent-based formulations with aggressive adhesion promoters mark low-surface-energy plastics and metal substrates.
- Graphic Arts:Aqueous dye and pigment systems dominate wide-format display graphics on coated and uncoated papers.
Graphic Arts dominates installed base. Packaging is where expansion concentrates.
Ink Type:
Cost tiers stratify sharply, with UV-curable systems commanding formulation premiums against commodity aqueous alternatives.
- UV-Curable:Acrylate monomer and oligomer blends incorporating Type I and Type II photoinitiators deliver instant polymerization for non-porous substrates. REACH chemical registration thresholds are accelerating substitution of legacy solvent systems across European textile clusters.
- Aqueous:Water-based vehicles with humectant packages control evaporation rates for piezoelectric printhead compatibility. China's MEE wastewater discharge standards elevate treatment costs for Guangdong province converters running high-volume aqueous lines.
- Solvent-Based:VOC-laden formulations face escalating EPA emission ceiling compliance costs in US manufacturing facilities.
- Dye-Based:Molecular colorants penetrate fiber structures for maximum chroma on cellulosic textiles.
Aqueous systems anchor volume leadership. UV-curable chemistry is climbing the fastest.
End User:
Procurement sophistication varies dramatically, from captive formulation development by multinational manufacturers to spot purchasing by fragmented job shops.
- Manufacturers:Vertically integrated apparel and packaging producers specify custom ink chemistries matched to proprietary substrate portfolios.
- Retailers:E-commerce platforms and big-box chains are consolidating packaging print procurement through multi-year managed service contracts.
- Designers:Creative agencies and brand studios drive short-run customization demand with rapid turnaround requirements.
- Print Service Providers:Hybrid system configurations preserve substrate flexibility for job-shop operators managing heterogeneous order portfolios.
Print Service Providers dominate transaction volume. Manufacturers represent the steepest expansion trajectory.
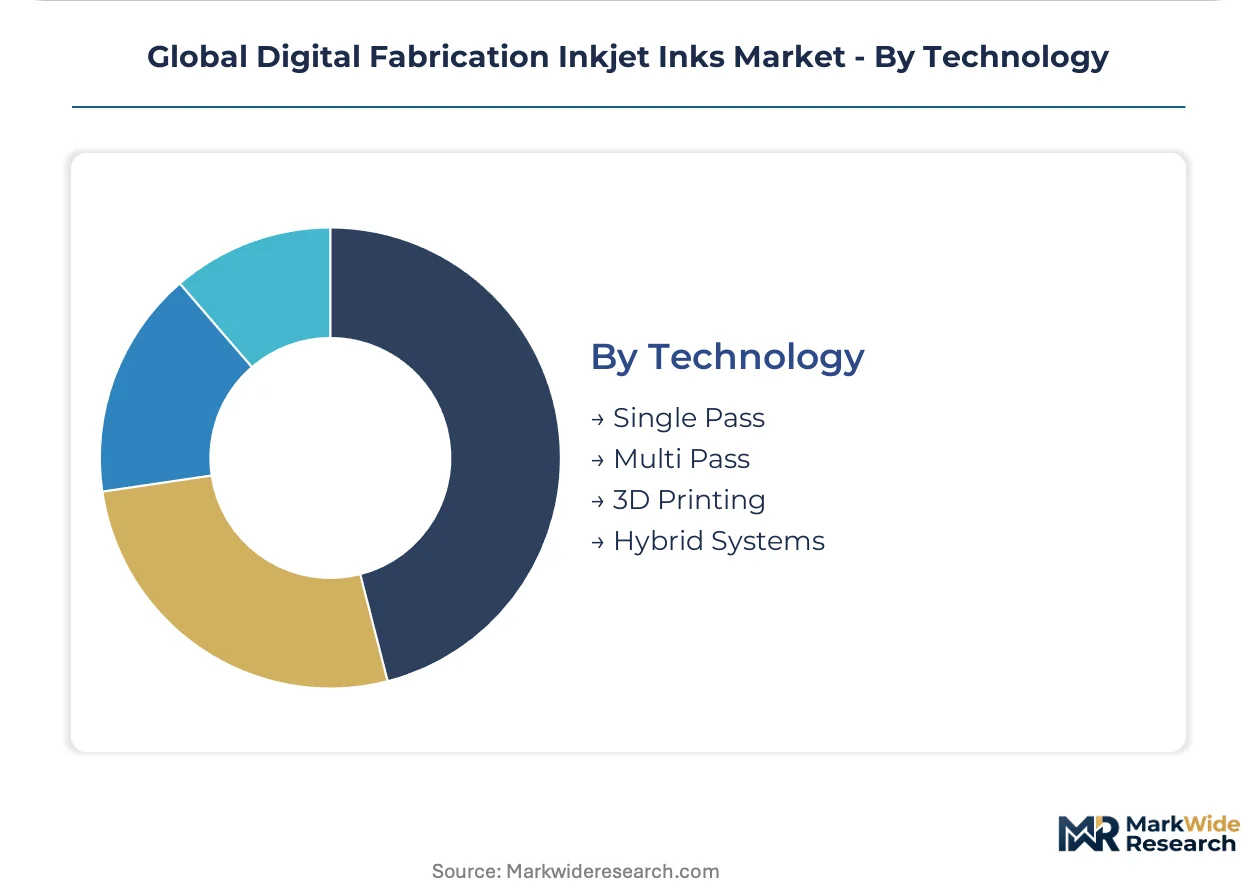
Technology:
Single-pass architectures displace multi-pass systems where throughput economics justify capital intensity, while hybrid configurations defend flexibility.
- Single Pass:Page-wide printhead arrays eliminate scanning motion, compressing make-ready times from hours to minutes for corrugated packaging converters.
- Multi Pass:Scanning carriage systems retain cost accessibility for entry-level textile and graphic arts installations.
- 3D Printing:Photopolymer and binder jetting formulations enable additive manufacturing of functional prototypes and end-use components.
- Hybrid Systems:Configurations combining single-pass and multi-pass modules serve print service providers managing diverse substrate portfolios.
Multi Pass systems dominate legacy installed base. Single Pass is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters and textile printers concentrate procurement decisions in industrial clusters where regulatory pressure and export logistics intersect. Buyers in China's Pearl River Delta, Germany's Rhine-Ruhr corridor, and the US Midwest dominate volume contracting. Local chemical registration regimes and wastewater discharge standards shape supplier qualification timelines.
China
Guangdong province converters serving cross-border e-commerce fulfillment aggregate demand for single-pass corrugated systems. MEE wastewater discharge standards elevate aqueous ink treatment costs for high-volume operations. Shenzhen and Dongguan industrial zones host packaging print clusters migrating from flexographic to digital inkjet lines.
Germany
REACH registration thresholds through ECHA accelerate substitution of solvent-based textile printing systems. Baden-Württemberg and North Rhine-Westphalia house packaging converters demanding UV-curable chemistries for food-contact applications. Düsseldorf-area suppliers document complete constituent disclosure to preempt downstream liability exposure.
United States
EPA VOC emission ceilings constrain solvent-based formulations in Midwest manufacturing facilities. Amazon-qualifying packaging suppliers in Ohio and Illinois retrofit flexographic lines with inkjet arrays. Chicago industrial corridors concentrate demand for short-run custom box production with compressed make-ready times.
Japan
METI tightens JIS standards for industrial inks used in food-contact packaging applications. Nagoya and Osaka manufacturing hubs demand third-party certified formulations. Kanto region converters consolidate procurement through multi-year managed service contracts with integrated hardware-ink suppliers.
Vietnam
Relocating apparel manufacturing creates greenfield demand for pigment ink systems in Ho Chi Minh City industrial zones. Textile printers migrate from reactive dye workflows to pigment systems to compress water-intensive processing. Binh Duong province hosts emerging print service providers managing heterogeneous substrate portfolios.
Global Digital Fabrication Inkjet Inks Market Vendor Landscape
Channel-controlling players compete with product-specialist players across formulation chemistry and hardware integration vectors. The vendor base stratifies into three tiers: multinational chemical conglomerates with materials science heritage, integrated print system bundlers, and niche UV-curable specialists. Consolidation pressure concentrates among photoinitiator suppliers and pigment dispersion technologists. Dominant competitive moves include strategic partnerships between ink formulators and printhead manufacturers, plus backward integration into specialty chemical production.
Among diversified chemical conglomerates, DuPont and Fujifilm Sericol International exemplify archetypes leveraging materials science platforms to sustain formulation leadership. HP anchors North American supply relationships through integrated ecosystems bundling ink chemistry with hardware platforms. Sensient Imaging Technologies occupies a specialist position in colorant and pigment dispersion technologies serving textile and graphic arts segments.
| Leading Market Players |
|---|
| DuPont |
| Sensient Imaging Technologies |
| HP |
| Wikoff Color |
| Van Son Holland Ink |
| EPSON |
| Nazdar |
| TRIDENT |
| Fujifilm Sericol International |
| Others |
Supply Flow & Price Mechanics
Photoinitiator production clusters among German and Japanese specialty chemical suppliers concentrate margin capture upstream, while ink formulators downstream face compressed spreads on commodity aqueous systems. This asymmetry shapes contract structures and sourcing strategies across formulation tiers.
Pricing Analysis
Cost-plus contracts with acrylic monomer indexation dominate UV-curable ink procurement. Three-tier pricing structure separates food-contact certified formulations from industrial grades and uncertified commodity blends. Cost compression in aqueous textile systems is intensifying because Bangladesh and Vietnam converters prioritize water-efficiency metrics over chroma performance. Print service providers exhibit highest price sensitivity due to spot purchasing patterns, while Amazon-qualifying packaging suppliers accept premiums for single-pass compatibility guarantees.
Supply Chain Analysis
Export-control regimes on piezoelectric actuator materials constrain printhead supply flows from Japan to non-aligned manufacturing destinations. Photoinitiator synthesis draws from German and Japanese chemical complexes, while pigment dispersion technology rests on US and European specialty additive suppliers. Single-source vulnerability concentrates in Type II photoinitiator feedstocks. Distribution runs through integrated hardware-ink bundlers in North America and formulation specialists serving job-shop networks in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital fabrication inkjet inks face sustained substitution pressure from analog screen and flexographic systems in high-volume textile and packaging workflows. Incumbents must defend digitization gains by neutralizing total-cost-of-ownership advantages that legacy technologies retain in specific substrate categories.
For Market Incumbents: Insulate pigment dispersion leadership through backward integration into polymeric dispersant synthesis, neutralizing supply vulnerability from third-party additive suppliers. Anchor single-pass system bundling relationships with Guangdong province corrugated converters before Chinese domestic formulators achieve REACH-equivalent certification tiers. Prioritize JIS-compliant food-contact formulation pipelines to preempt METI enforcement expansion. For New Entrants and Emerging Players: Build out ceramic tile decoration capabilities in Italian and Spanish manufacturing hubs where rotary screen infrastructure ages and digital retrofit demand concentrates. Target Vietnam textile printing clusters with pigment systems optimized for polyester-cotton blends, exploiting water-scarcity pressures that render reactive dye workflows uneconomical. Pursue equipment-leasing partnerships rather than capital-sale models to lower converter adoption barriers. For Investors and Strategic Acquirers: Capital is best deployed toward photoinitiator specialists with captive arylketone synthesis capabilities, given supply concentration risks and formulation reformulation cycles triggered by REACH chemical registration thresholds. Monitor ECHA substance restriction timelines as inflection indicators for acquisition timing, as accelerated substitution mandates would revalue UV-curable formulation portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Synthesis | Captures margin pools concentrated among German and Japanese specialty chemical suppliers. |
| Single-Pass System Bundling Partnerships | Locks in corrugated packaging converters migrating from flexographic lines in Guangdong province. |
| JIS-Compliant Food-Contact Certification | Preempts METI enforcement expansion and downstream liability exposure in Japanese export markets. |
| Ceramic Tile Decoration Capability Buildout | Penetrates Italian and Spanish manufacturing hubs where rotary screen infrastructure ages. |
| Pigment System Optimization for Synthetic Blends | Exploits water-scarcity pressures driving Bangladesh and Vietnam converters from reactive dyes. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, EPA emission compliance filings, and ECHA substance registration databases. Interviews with textile plant managers, packaging converter procurement leads, piezoelectric printhead engineers, and specialty chemical R&D directors inform demand-side validation. SEC 10-K disclosures from integrated hardware-ink suppliers and pigment dispersion technology filings supplement supply-side triangulation. Bottom-up volume modeling across ink type and application segments converges with top-down market sizing from trade flow analysis.
Forecast inputs include piezoelectric printhead installation rates, REACH chemical substitution timelines, and corrugated packaging e-commerce fulfillment growth across the analysis window. Segmentation dimensions span ink chemistry, application substrate, technology architecture, and regional regulatory cluster. CAGRs derive from elasticity modeling against industrial print capacity expansion and analog-to-digital substitution curves. Specific inputs capture Guangdong province wastewater treatment cost trajectories and Bangladesh textile water-efficiency regulatory thresholds.
Sensitivities concentrate around photoinitiator supply disruptions, ECHA substance restriction acceleration, and single-pass system adoption rates in corrugated packaging. Forecasts reflect documented assumptions on chemical registration burden timelines and converter capital commitment patterns. Material shifts in REACH enforcement intensity or piezoelectric actuator export-control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Screen Printing Mesh Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Lithography Inks Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Global Printing Toners Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Specialty Ink Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Functional Printing Market
Printing Inks
Molecular Ink Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Brazil Commercial Printing Market
Printing Inks
UV Fluorescing Ink Market