

Oriented Perforating System Market Size, Share, and Industry Trends Forecast 2026-2036
Oriented Perforating System Market Insights
North American shale producers are shifting toward factory-mode completion designs that demand azimuthally precise perforation clusters. SLB leverages integrated wireline-to-perforating workflows to sustain premium positioning in high-stage-count horizontal wells. Baker Hughes Company anchors its market presence through proprietary shaped charge designs optimized for unconventional reservoir geomechanics. Halliburton competes by dominating tubing-conveyed perforating deployments in extended-reach laterals across the Permian and Eagle Ford.
An oriented perforating system is a directional well completion tool that aligns explosive shaped charges to specific azimuths and phasing angles relative to the borehole, typically achieving orientation accuracy within ±5 degrees through magnetic, gyroscopic, or mechanical referencing methods. Its primary industrial purpose is to create controlled fractures that intersect maximum principal stress planes, enhancing hydrocarbon flow from tight formations. Shaped charge guns and tubing-conveyed systems occupy the dominant share of product deployments, reflecting their reliability in high-pressure downhole environments. Magnetic orientation technology leads in adoption metrics due to cost efficiency and real-time surface verification, while gyroscopic orientation commands premium positioning in areas with magnetic interference from casing strings or nearby wellbores.
API RP 19B governs perforator performance testing protocols in the United States, forcing manufacturers to document penetration depth and entrance hole consistency under simulated downhole conditions. OSHA and EPA frameworks regulate explosives handling and waste management across the supply chain, shaping operational economics for service providers and end users. The EU F-Gas Regulation and REACH chemical standards constrain propellant formulations and charge carrier materials for European deployments. Stakeholders must monitor regulatory divergence between North American performance-based standards and European precautionary chemical restrictions when configuring global product portfolios and manufacturing footprints.
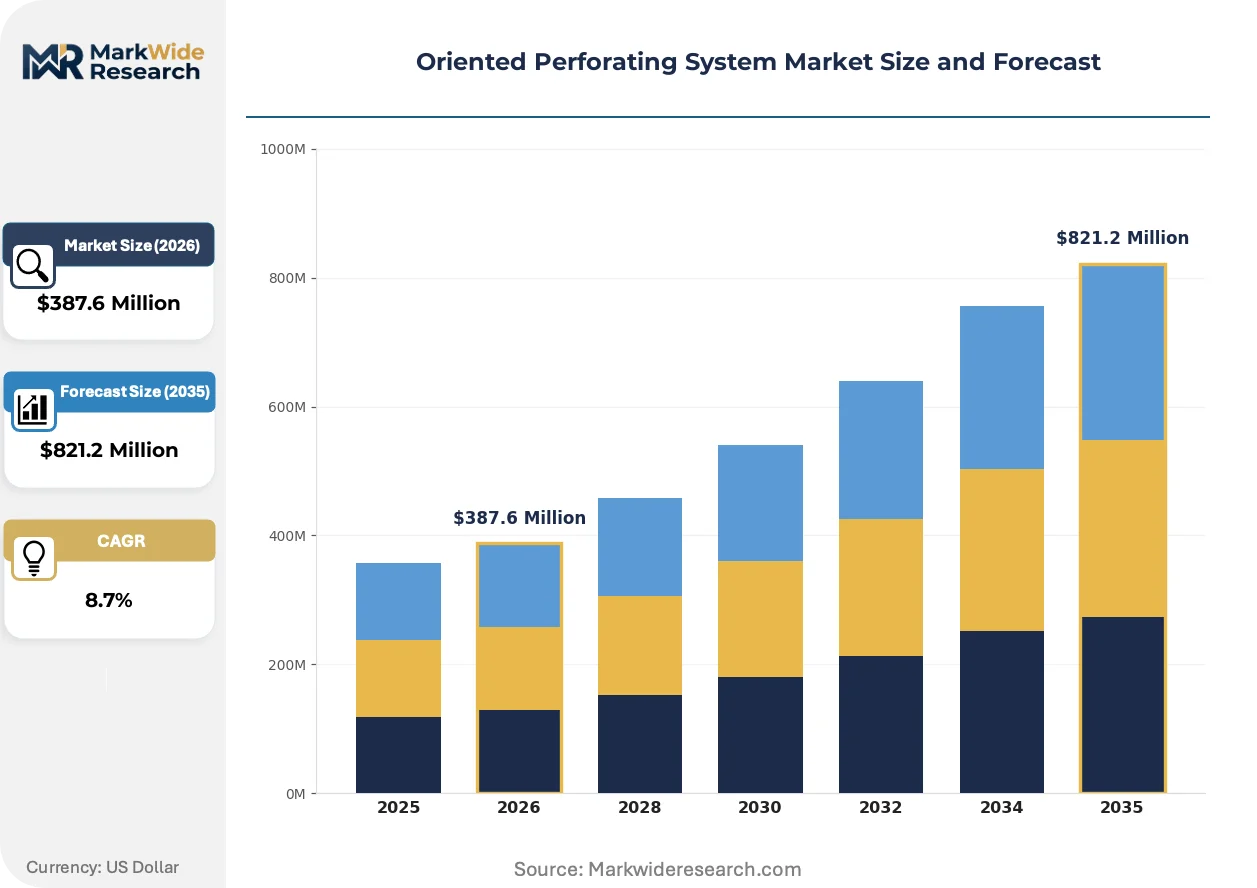
Market Dynamics
Factory-mode completion designs in North American shale basins are compressing stage spacing and multiplying perforation cluster density per lateral, forcing service providers to deliver azimuthal precision at unprecedented operational tempo.
Growth Catalysts
- API RP 19B Testing Mandates:United States operators now require documented penetration depth consistency under simulated downhole conditions, elevating demand for calibrated orientation systems that guarantee repeatable fracture initiation.
- Vaca Muerta Shale Expansion:Argentine operators are importing precision perforating expertise from Permian Basin veterans, creating pull for magnetic and gyroscopic orientation technologies adapted to high-pressure carbonate formations.
- Shaped Charge Materials Science:Advanced liner geometries and explosive formulations are extending effective penetration in ultra-tight formations, reinforcing the economic case for oriented deployment over conventional spiral perforating.
Market Restraints
- Copper and RDX Input Volatility:Shaped charge manufacturing depends on copper liners and high-explosive formulations subject to commodity price swings and dual-use export controls, compressing margin predictability for gun system fabricators.
- Supply Concentration in Texas and Oklahoma:Domestic manufacturing of precision perforating hardware clusters along a narrow corridor vulnerable to Gulf Coast weather disruptions and regional logistics bottlenecks.
- Magnetic Interference Limitations:Casing strings and multi-well pad proximity degrade magnetic orientation accuracy, forcing costly gyroscopic upgrades in approximately 15% of horizontal completions.
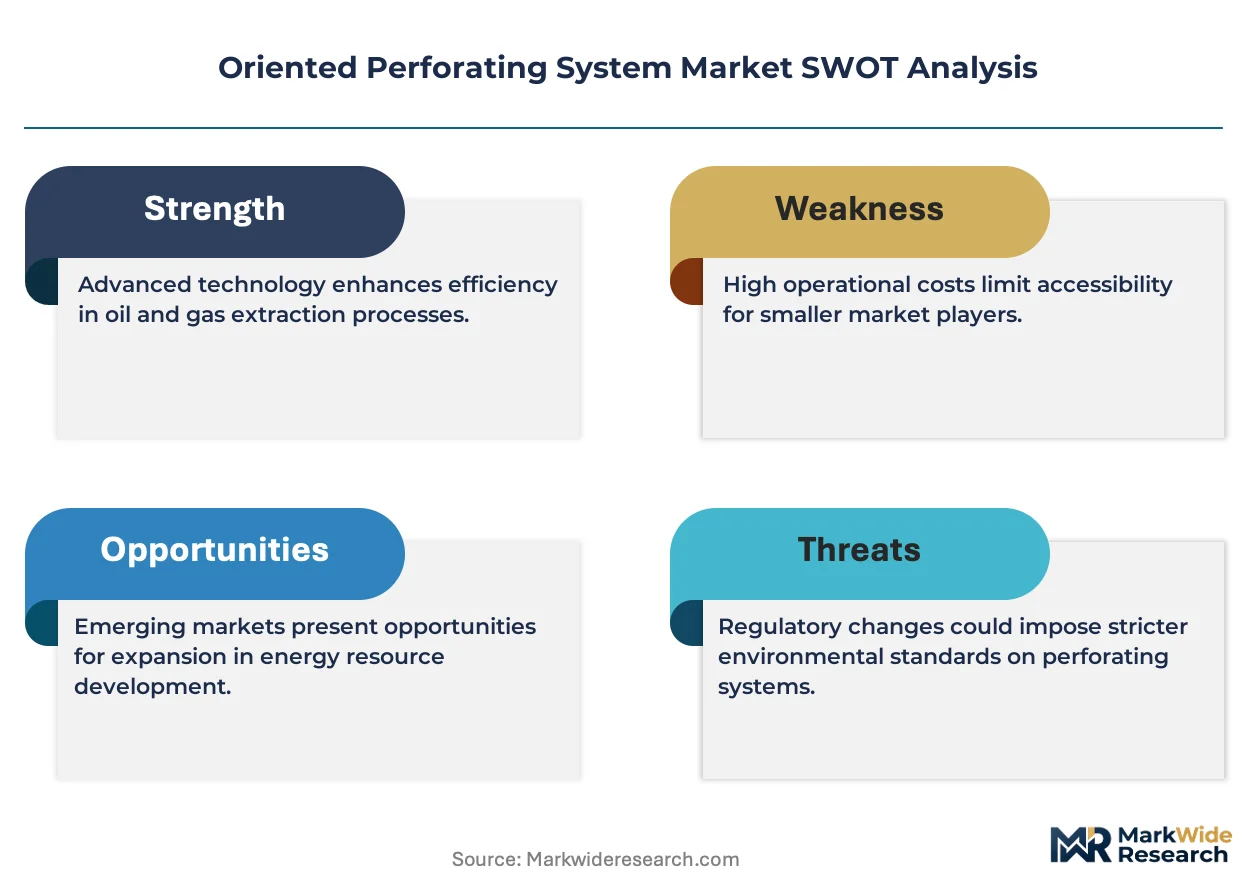
Strategic Opportunities
- Middle East Carbonate Tight Gas:Saudi Arabia and Kuwait are piloting oriented perforating in deep, high-temperature formations previously dominated by acid fracturing, opening white-space demand for heat-resistant charge carriers.
- EU F-Gas Regulatory Tailwind:European restrictions on fluorinated greenhouse gases are accelerating propellant formulation innovation, creating first-mover advantage for suppliers with REACH-compliant chemistry portfolios.
- Real-Time Telemetry Convergence:Integration of downhole orientation sensors with wireline logging platforms is unifying perforating and formation evaluation workflows, enabling premium service bundling.
Industry Challenges
- Explosives Handling Certification Bottlenecks:OSHA and ATF compliance timelines for field personnel extend 6-12 months, constraining workforce scalability during demand surges.
- Legacy Gun System Interoperability:Proprietary connector standards across service company fleets fragment rental equipment pools, complicating cross-operator logistics and inventory optimization.
- Extended-Reach Lateral Deployment Complexity:Friction and buckling in 15,000-foot laterals degrade tubing-conveyed perforating reliability, demanding redesigned centralization and weight-transfer mechanisms.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oriented Perforating System Market Trends and Innovations
Digital integration of downhole measurement with surface control systems is collapsing the traditional separation between perforating execution and geomechanical modeling, compressing decision cycles from hours to minutes.
Intelligent perforating guns equipped with embedded accelerometers and pressure transducers are unifying fracture diagnostics with charge detonation timing. Permian Basin operators are deploying these systems in 40% of new horizontal completions, enabling real-time cluster efficiency verification and immediate re-perforating decisions without additional wireline trips.
REACH chemical restrictions in Europe are forcing reformulation of shaped charge explosives and carrier fluids, with ECHA registration requirements extending development timelines 18-24 months for new propellant chemistries. German and Norwegian North Sea operators are prioritizing suppliers with pre-certified material safety data sheets, compressing vendor qualification pools.
Integrated service contracting is displacing standalone perforating procurement as E&P companies consolidate vendor relationships. Bakken and Eagle Ford producers now bundle orientation, pumping, and diagnostics under single-source agreements, rewarding service companies with captive wireline fleets and in-house charge manufacturing capabilities.
Oriented Perforating System Market Segmentation
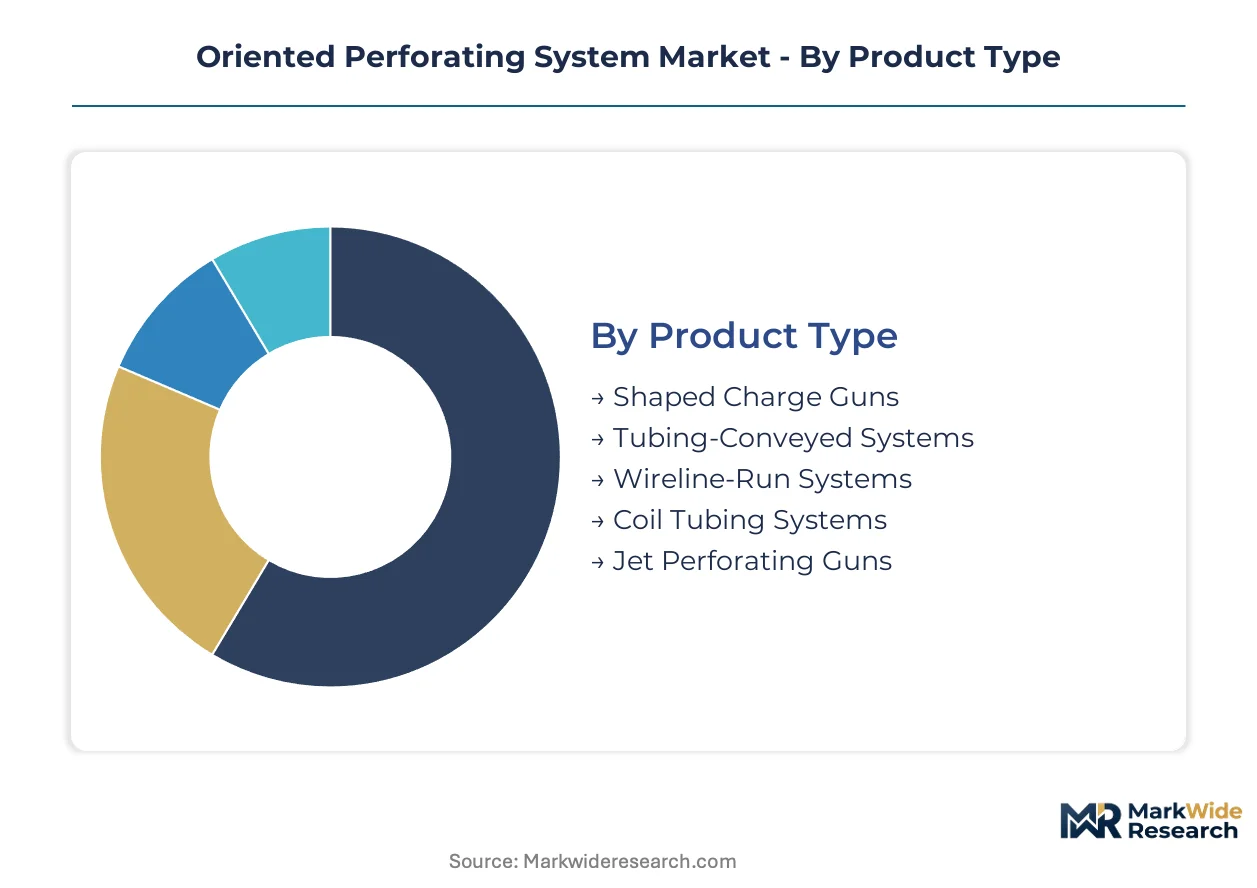
Oriented perforating system procurement varies sharply across deployment contexts, with integrated service bundles commanding premium economics versus standalone equipment rentals. Segment boundaries reflect divergent technical requirements between factory-mode shale completions and bespoke offshore interventions.
Product Type:
Standalone gun systems dominate rental fleets, while tubing-conveyed architectures embed into integrated completion workflows.
- Shaped Charge Guns:Self-contained perforating assemblies house explosive liners in sealed carriers rated for high-pressure downhole conditions. Permian Basin operators deploy these in 60% of horizontal completions where rapid stage turnaround outweighs precision telemetry needs.
- Tubing-Conveyed Systems:These configurations integrate perforating guns with production tubing strings, enabling simultaneous deployment and fracturing operations. Eagle Ford producers favor this architecture for extended-reach laterals where wireline access proves unreliable, accepting higher capital commitment for operational continuity.
- Wireline-Run Systems:Slimhole perforating guns deployed via electric cable dominate workover and recompletion markets.
- Coil Tubing Systems:Continuous conduit deployment suits highly deviated wellbores where rigid pipe cannot convey charges.
- Jet Perforating Guns:High-pressure fluid jet alternatives serve niche applications in explosive-restricted environments.
Shaped charge guns lead volumes today; tubing-conveyed systems are gaining share fastest in high-stage-count horizontal programs.
Technology:
Cost tier separation between commodity magnetic tools and precision gyroscopic systems shapes vendor positioning and margin structure.
- Magnetic Orientation:Flux-gate sensors reference Earth's magnetic field to align perforating charges within ±5 degrees azimuthal accuracy. This technology captures 70% of North American shale deployments where surface casing provides clean magnetic reference.
- Gyroscopic Orientation:Inertial measurement units eliminate magnetic dependency, delivering reliable orientation in steel-cased wellbores or multi-well pad environments. Vaca Muerta operators absorb 40% cost premiums for this capability to navigate complex carbonate fracture networks.
- Mechanical Orientation:Physical key-and-slot indexing provides bombproof alignment in simple vertical wellbores.
- Hydraulic Orientation:Differential pressure-actuated rotation suits limited-access completions without electric line.
- Electrical Orientation:Motor-driven charge alignment enables real-time surface control of perforating azimuth.
Magnetic orientation leads volumes today; gyroscopic orientation is expanding most quickly in pad-drilling environments with magnetic interference.
Application:
Well geometry dictates perforating system specification, with lateral complexity driving precision requirements and service intensity.
- Horizontal Wells:Laterals exceeding 10,000 feet demand azimuthally precise cluster placement to intersect maximum stress planes. Bakken Formation producers compress stage spacing below 150 feet, multiplying perforation density requirements per wellbore.
- Unconventional Reservoirs:Tight oil and gas formations require oriented perforating to initiate transverse fractures in low-permeability matrix rock. Marcellus Shale operators specify API RP 19B-certified systems to guarantee penetration consistency across variable geomechanical conditions.
- Vertical Wells:Conventional architecture accepts spiral perforating patterns without orientation investment.
- Multi-Lateral Wells:Branch junctions complicate orientation referencing across multiple horizontal legs.
- Enhanced Oil Recovery:Thermal and chemical EOR applications impose temperature tolerance requirements on charge carriers.
Horizontal wells lead volumes today; unconventional reservoir applications show steepest expansion trajectory as tight formation development accelerates.
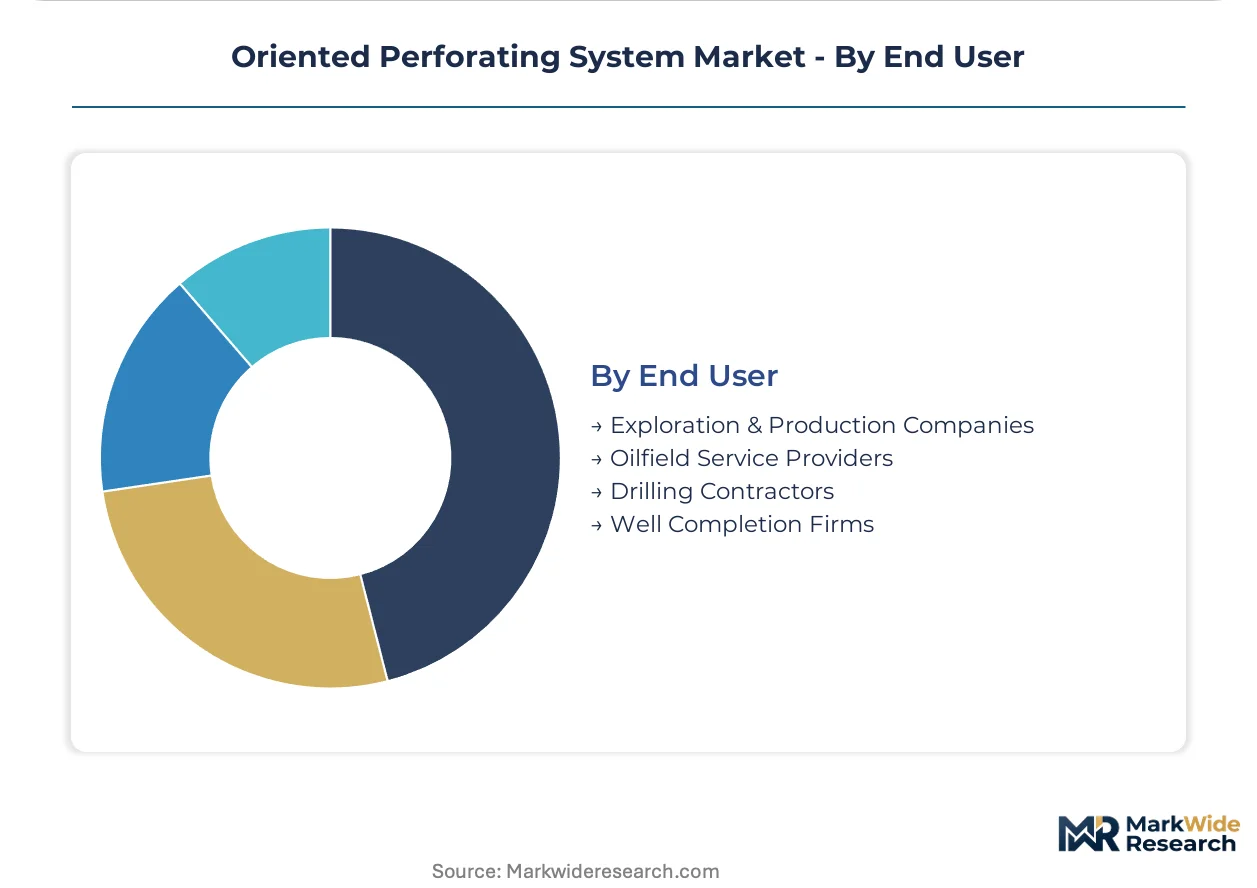
End User:
Customer type determines procurement mode, with integrated E&P operators consolidating vendors versus fragmented contractor rental markets.
- Exploration & Production Companies:Supermajors and independents increasingly bundle perforating within integrated completion contracts. Occidental Petroleum and Pioneer Natural Resources now specify single-source accountability for orientation, pumping, and diagnostics.
- Oilfield Service Providers:Schlumberger, Halliburton, and Baker Hughes maintain captive gun manufacturing and orientation technology portfolios. These firms rent equipment to smaller operators lacking capital for owned perforating assets.
- Drilling Contractors:Rig-based service companies provide perforating as ancillary offering during completion phases.
- Well Completion Firms:Specialized boutiques focus on high-specification interventions in complex well architectures.
E&P companies lead volumes today; oilfield service providers are climbing the fastest as integrated contracting displaces standalone procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for precision perforating hardware clusters along the Texas-Oklahoma corridor where OSHA explosives handling protocols and EPA waste management frameworks impose compliance costs that Argentine and Middle Eastern entrants currently avoid through regulatory arbitrage in their home jurisdictions.
United States
Permian Basin operators compress stage spacing below 150 feet, multiplying demand for azimuthally precise cluster placement. API RP 19B testing mandates force documented penetration depth consistency under simulated downhole conditions. Midland-Odessa service company concentration anchors domestic supply chains for shaped charge gun fabrication.
Argentina
Vaca Muerta shale expansion imports precision perforating expertise from Permian Basin veterans, creating pull for magnetic and gyroscopic orientation technologies. The national hydrocarbons regulator enforces well integrity standards adapted from North American precedents. Neuquén Basin operator activity concentrates demand for high-pressure carbonate formation perforating systems.
Saudi Arabia
Deep carbonate tight gas pilots previously dominated by acid fracturing now test oriented perforating in high-temperature formations. SFDA chemical registration requirements shape propellant formulation imports for European suppliers. Eastern Province gas field development anchors regional demand for heat-resistant charge carriers.
Germany
North Sea operator procurement prioritizes suppliers with REACH-compliant material safety data sheets and pre-certified explosives chemistry portfolios. ECHA registration timelines extend 18-24 months for new propellant formulations. Hamburg and Bremen port logistics clusters handle import distribution for Norwegian and UK offshore deployments.
China
Sichuan Basin shale gas development accelerates domestic manufacturing of tubing-conveyed perforating systems for extended-reach laterals. MEE environmental standards constrain waste management from explosives manufacturing. Chongqing equipment fabrication centers supply orientation technology for domestic unconventional reservoir programs.
Oriented Perforating System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated service bundling and digital telemetry convergence. The vendor structure consolidates around three to five global service companies with captive manufacturing capabilities, while regional specialists maintain rental fleet positions. Archetypes divide into integrated energy service conglomerates, standalone perforating technology specialists, and national oil company captive suppliers. Dominant competitive moves include vertical integration into shaped charge manufacturing and strategic partnerships for real-time downhole sensor integration.
Within the integrated service tier, SLB, Halliburton, and Baker Hughes Company exemplify archetypes of wireline-to-perforating workflow consolidation. SLB represents premium positioning through integrated digital platforms. Halliburton occupies a position anchored in tubing-conveyed perforating deployments for extended-reach laterals. Baker Hughes Company exemplifies proprietary shaped charge design specialization for unconventional reservoir geomechanics.
| Leading Market Players |
|---|
| SLB |
| Baker Hughes Company |
| Halliburton |
| Weatherford |
| NOV |
| DynaEnergetics |
| Core Laboratories |
| Hunting |
| GEODynamics |
| Others |
Pricing and Supply Chain Analysis
API RP 19B testing mandates from United States operators are forcing shaped charge manufacturers to absorb certification costs that compress margins on standard magnetic orientation systems while creating premium capture opportunities for gyroscopic technologies with documented penetration consistency.
Pricing Analysis
Distributor margins on standalone gun system rentals run 15-25% above direct-to-OEM contract pricing for integrated tubing-conveyed deployments. Three-tier pricing structure across premium gyroscopic, standard magnetic, and economy mechanical orientation levels reflects certification grade and real-time telemetry bundling. Pricing pressure stems from copper liner and RDX explosive input volatility that squeezes fabricator margins. Independent E&P companies in the Permian Basin exhibit highest price sensitivity, while supermajors absorbing API compliance costs show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from integrated service companies, while rental fleet operators source through regional distribution partners in Texas and Oklahoma. Manufacturing concentrates in the United States, Argentina, and China for orientation hardware, with shaped charge explosives anchored in United States and European chemical production. Copper liner supply draws from Chilean mining output and domestic scrap recovery. Single-source vulnerability in Gulf Coast logistics corridors exposes gun system fabricators to weather-related disruption. Distribution runs through Midland-Odessa service hubs for North American shale basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-mode completion designs are compressing stage economics and rewarding suppliers who capture premium positioning through gyroscopic precision and real-time telemetry bundling.
For Market Incumbents: Extend API RP 19B certification coverage to shaped charge manufacturing facilities in Argentina and Saudi Arabia before regional competitors establish local testing protocols. Backward integration into copper liner production mitigates commodity volatility exposure from Chilean supply. Defensive patent filings on heat-resistant charge carriers for Middle East carbonate formations preempt emerging entrant replication. For New Entrants and Emerging Players: Begin with REACH-compliant propellant formulation services for German and Norwegian North Sea operators facing 18-24 month ECHA registration bottlenecks. White-space demand for gyroscopic orientation in Vaca Muerta multi-well pads offers lowest competitive density. Go-to-market through technology licensing to Argentine national oil company suppliers bypasses capital-intensive gun manufacturing. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap perforating technology specialists holding captive orientation sensor IP and pre-certified European chemical portfolios. Five-to-ten year viability hinges on digital integration convergence with wireline logging platforms. Acquisition targets should demonstrate documented penetration consistency under API RP 19B protocols. Monitor Saudi Aramco and Kuwait Oil Company pilot program expansion signals as inflection indicators for Middle East carbonate tight gas adoption.| Strategic Initiative | Industry Significance |
|---|---|
| API RP 19B Certification Expansion | United States operators now mandate documented penetration depth consistency, elevating compliant suppliers. |
| Backward Integration into Copper Liner Production | Captive supply of shaped charge raw materials buffers margin compression from commodity volatility. |
| REACH-Compliant Propellant Formulation | ECHA registration requirements extend development timelines, rewarding pre-certified European chemistry portfolios. |
| Real-Time Telemetry Convergence | Downhole orientation sensor integration with SLB and Halliburton wireline platforms enables premium service bundling. |
| Heat-Resistant Charge Carrier Development | Saudi SFDA chemical registration shapes import requirements for Eastern Province gas field pilots. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with completion engineers at Permian Basin operators, perforating technology directors at integrated service companies, gun system procurement leads at independent E&P firms, and regulatory compliance officers handling OSHA explosives certification. Secondary validation drew from API RP 19B testing documentation, EPA waste management filings, ECHA REACH registration databases, and United States customs trade data on shaped charge imports. Bottom-up well count modeling and top-down service revenue triangulation anchored market sizing.
Segment-weighting across the projection horizon distributed volumes by technology type, well geometry, and regional regulatory cluster, with unconventional reservoir applications receiving distinct coefficients for stage density and perforation cluster count. CAGRs derived from trajectory fitting to historical deployment rates and elasticity-adjusted responses to oil price scenarios. Forecast inputs included horizontal lateral length extension curves and API testing mandate adoption timelines.
Several conditions sit outside the modeled scope, including sudden ATF explosives handling regulation changes, copper price spike events exceeding historical volatility bands, and Gulf Coast logistics corridor disruptions. Forecasts reflect base-case assumptions on shale completion intensity and international unconventional reservoir development pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.