
 Chile Data Center Processor Market | 2026-2036
Chile Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Data Center Processor Market Insights
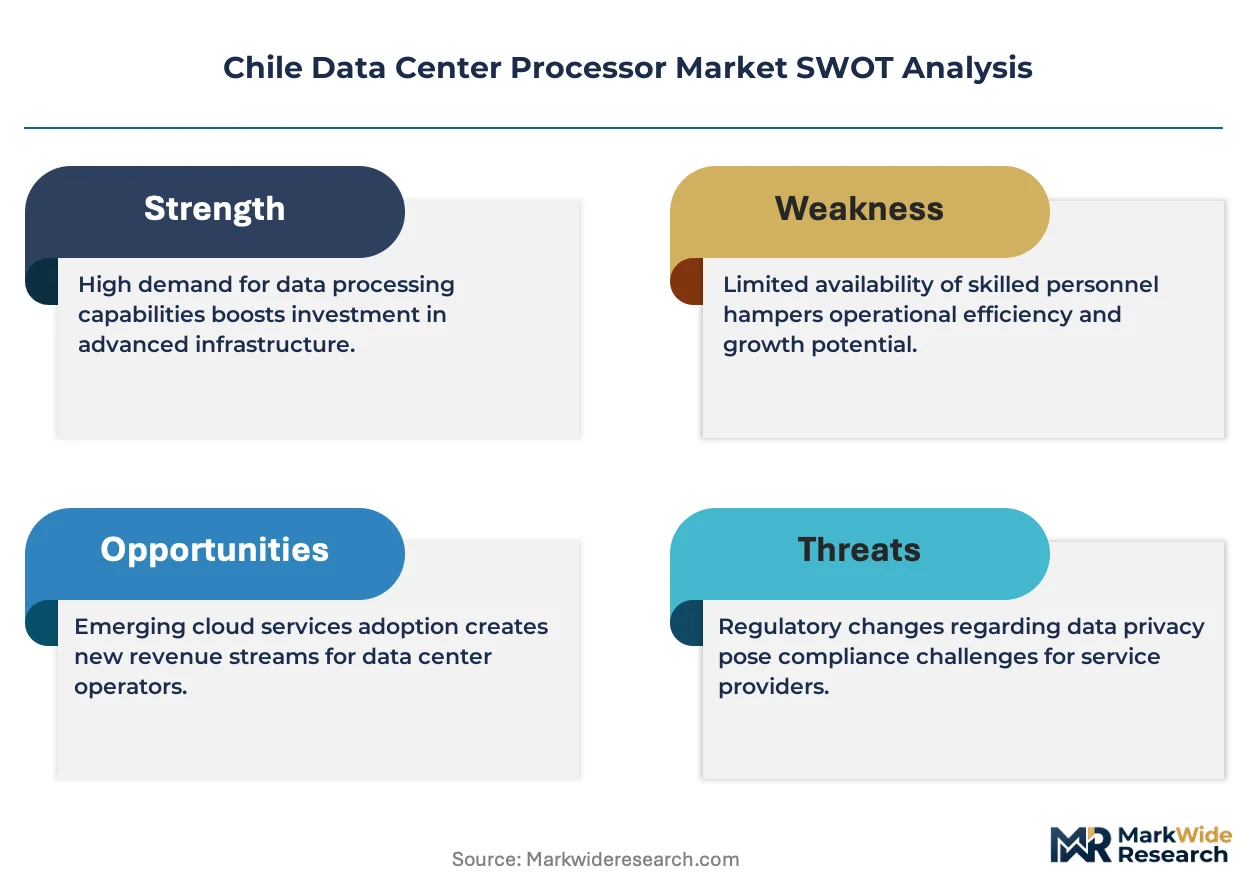
Chile's updated data center energy efficiency standards are repositioning facility certification as a prerequisite for large-scale procurement contracts. Dell Technologies leverages its integrated server-processor portfolios to anchor enterprise refresh cycles across Santiago's banking district. Huawei Technologies competes on price-performance metrics for hyperscale deployments tied to renewable power purchase agreements. International Business Machines Corporation specializes in PowerPC-based systems serving government and research workloads requiring sovereign compute capacity.
A data center processor is a silicon semiconductor device designed to execute computational workloads within server infrastructure, typically fabricated on process nodes of 7nm or smaller and operating at thermal design powers ranging from 150W to 400W for high-performance parts. CPU architectures continue to dominate installed base value across Chile's enterprise and colocation facilities, though GPU segments are capturing disproportionate growth as local financial institutions deploy AI inference clusters for fraud detection. The ARM technology category is gaining traction among hyperscale providers seeking power efficiency gains in Santiago's renewable-powered zones, while X86 installations sustain the bulk of on-premises government and legacy enterprise footprints.
Chile's Ministry of Energy enforces efficiency benchmarks that filter processor procurement toward lower-wattage-per-compute-unit designs, while the country's national standards body certifies electromagnetic compatibility for imported server equipment. The Superintendency of Electricity and Fuels monitors grid stability commitments that data center operators must maintain when scaling processor density. Stakeholders must weigh technology roadmaps against evolving carbon-intensity thresholds that will determine which architectures qualify for future capacity expansion permits.
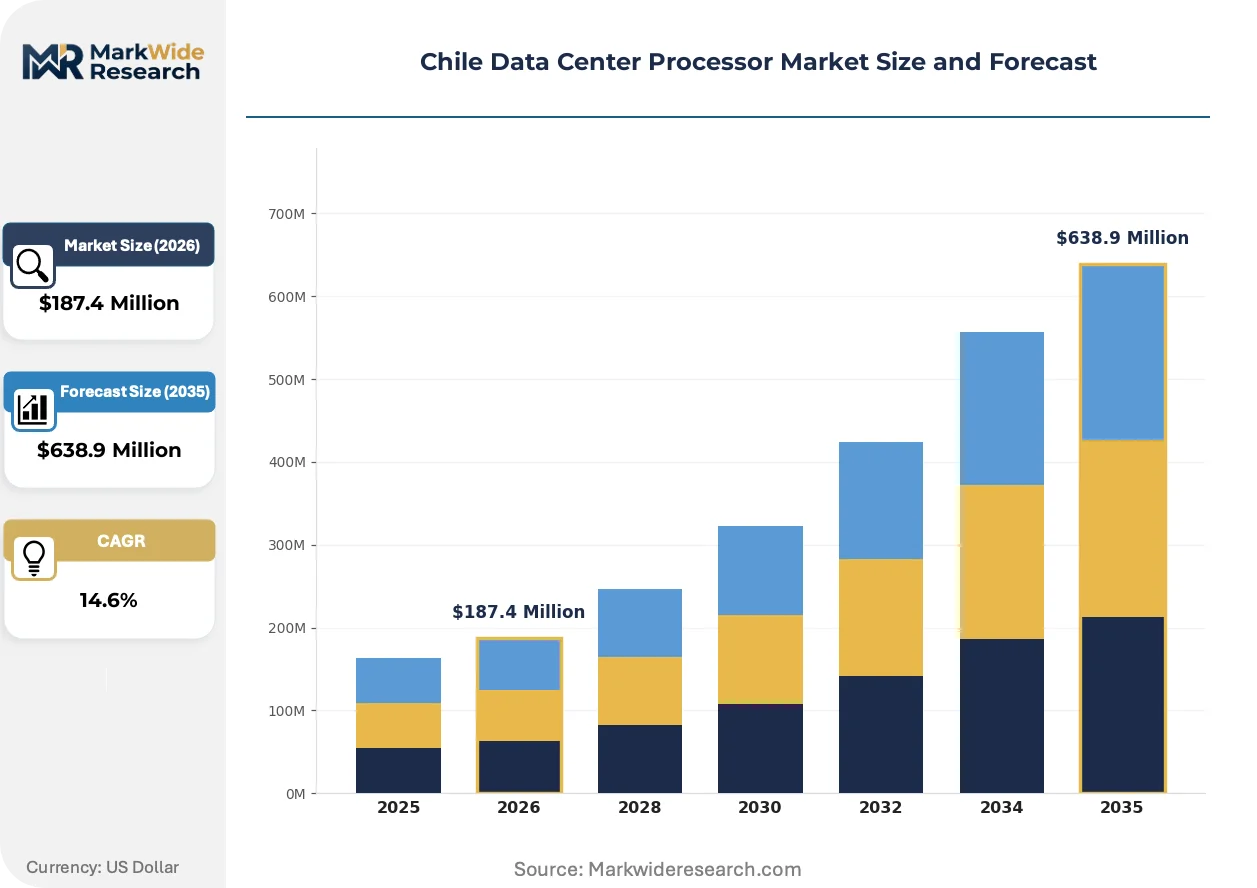
Market Dynamics
Chile's renewable energy mandates under its national decarbonization plan are forcing processor procurement toward power-efficient architectures, while Santiago's hyperscale buildouts concentrate demand in specific thermal and connectivity corridors.
Growth Catalysts
- Decarbonization mandates:Chile's Ministry of Energy enforces efficiency benchmarks that filter procurement toward lower-wattage-per-compute-unit designs, accelerating ARM and advanced node adoption in new facilities.
- Financial services AI deployment:Santiago's banking district drives GPU cluster expansion for real-time fraud detection, creating sustained demand for high-throughput inference silicon.
- Submarine cable convergence:Landing stations in Valparaíso and Santiago Metropolitan Region position Chile as a latency gateway for Latin American cloud workloads, pulling hyperscale processor commitments.
Market Restraints
- Import dependency:Chile lacks domestic semiconductor fabrication, exposing procurement to Taiwan and South Korea supply concentration and shipping bottlenecks through the Panama Canal.
- Grid interconnection queues:The Superintendency of Electricity and Fuels monitors stability commitments that delay processor density scaling when renewable generation cannot match compute load curves.
- Copper and lithium input volatility:Chile's own mining sector fluctuations transmit to data center construction costs, compressing capital available for server refresh cycles.
Strategic Opportunities
- Atacama solar-wind hybrid zones:Northern Chile's renewable parks offer carbon-negative compute positioning for sustainability-conscious multinational clients.
- Sovereign cloud mandates:Government and research workloads requiring domestic data residency create captive demand for PowerPC and secure enclave architectures.
- Liquid cooling convergence:Direct-to-chip and immersion technologies align with Santiago's water-scarcity constraints while enabling higher thermal design power processors.
Industry Challenges
- Certification timeline compression:Chile's national standards body electromagnetic compatibility testing creates six-to-nine month import delays for new server generations, forcing operators to commit to older processor vintages.
- Power systems integration:Uninterruptible power supply and switchgear procurement from European suppliers cannot scale with hyperscale construction velocity, stranding processor capacity pending electrical infrastructure completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Data Center Processor Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPU, GPU, FPGA, ASIC Technology: X86, ARM, PowerPC, RISC-V End User: Hyperscale Providers, Enterprises, Colocation, Government Installation: On-Premises, Hybrid, Cloud-Based, Edge |
| Companies Covered | Dell Technologies, International Business Machines Corporation, Hewlett Packard Enterprise, Super Micro Computer, Cisco Systems, Lenovo Group, Huawei Technologies, Inspur Group, Quanta Computer, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Data Center Processor Market Trends and Innovations
Processor architecture selection in Chile is decoupling from raw performance benchmarks toward carbon-intensity-adjusted metrics, rewiring vendor evaluation criteria and facility certification requirements simultaneously.
ARM-based server processors is overtaking x86 dominance in Santiago's renewable-powered hyperscale zones. Cloud providers deploying in solar-wind hybrid parks prioritize the architecture's wattage-per-instruction efficiency. This shift is compressing Intel and AMD share in new-build contracts while expanding Qualcomm and Ampere supply relationships.
Chile's Ministry of Energy efficiency benchmarks now require disclosure of embodied carbon in processor manufacturing, not just operational power draw. The regulation forces importers to document foundry energy sources and water usage. European and Asian server vendors are responding by pre-certifying equipment against Chilean standards before shipment.
Financial institutions in Santiago's banking district now specify inference-optimized silicon in procurement contracts rather than general-purpose GPUs. Colocation providers must maintain mixed x86-GPU-ARM fleets to serve these contracts. The pattern concentrates in fraud detection and algorithmic trading verticals where latency and power constraints conflict.
Chile Data Center Processor Market Segmentation
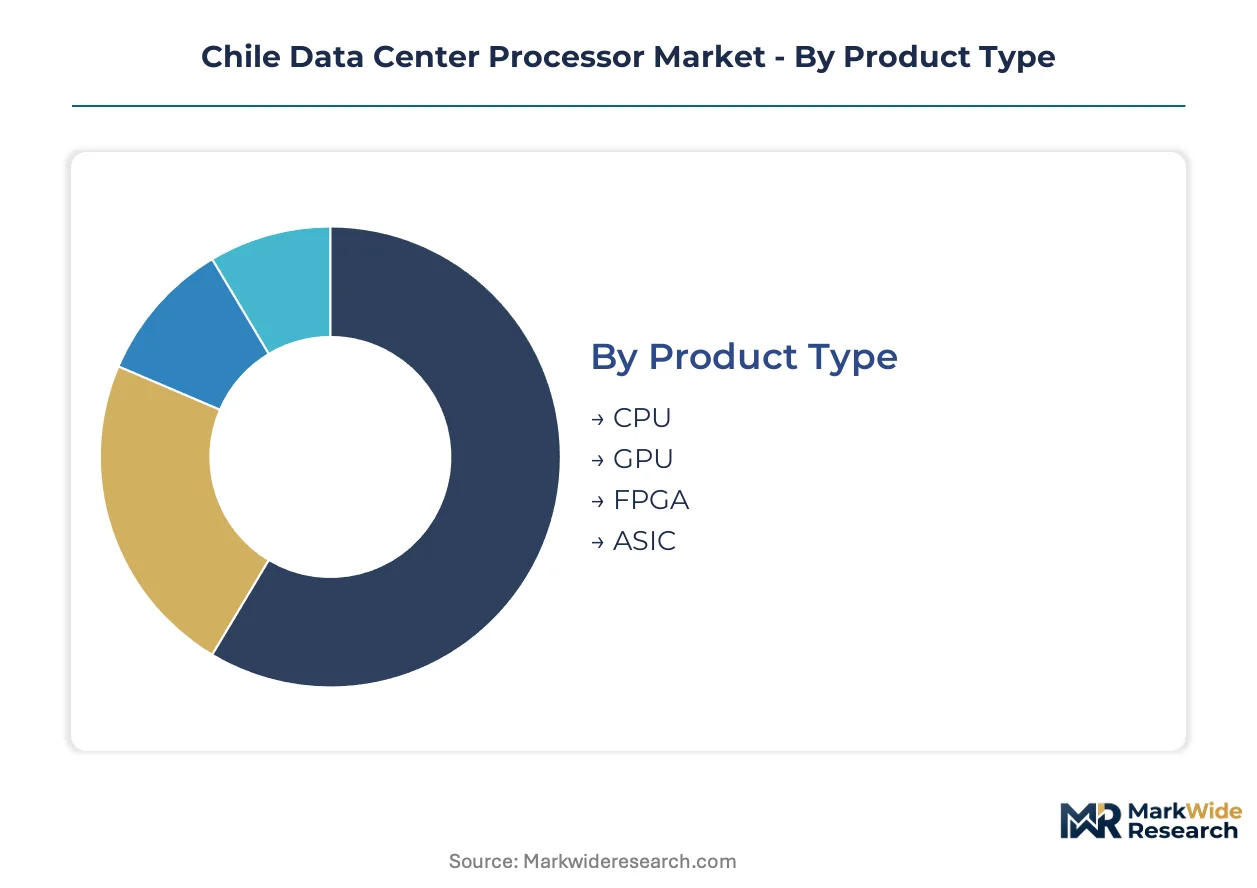
Processor segmentation in Chile reflects divergent procurement logics across deployment environments. Refresh cycles vary dramatically between hyperscale cloud expansions and legacy enterprise maintenance, creating tiered demand patterns that vendors must navigate simultaneously.
Product Type:
Upgrade urgency differs sharply across silicon categories, with some segments facing immediate replacement pressure while others extend depreciation schedules.
- CPU:General-purpose processors fabricated on 7nm to 5nm nodes handle the majority of Chile's enterprise transactional workloads. Santiago's banking district sustains steady refresh demand as institutions modernize core banking infrastructure to meet latency requirements for real-time payments.
- GPU:Parallel compute architectures optimized for matrix operations dominate AI inference deployments in fraud detection and algorithmic trading. Financial services procurement contracts now specify inference-optimized silicon tiers, forcing colocation providers to maintain dedicated GPU clusters alongside general-purpose fleets.
- FPGA:Reconfigurable logic devices serve niche workloads requiring hardware-level customization without ASIC development cycles.
- ASIC:Application-specific integrated circuits target cryptocurrency mining and specialized inference at mass scale.
Volume placements concentrate in CPU architectures; the faster expansion belongs to GPU.
Technology:
Architecture selection in Chile increasingly tracks power sourcing rather than raw performance benchmarks.
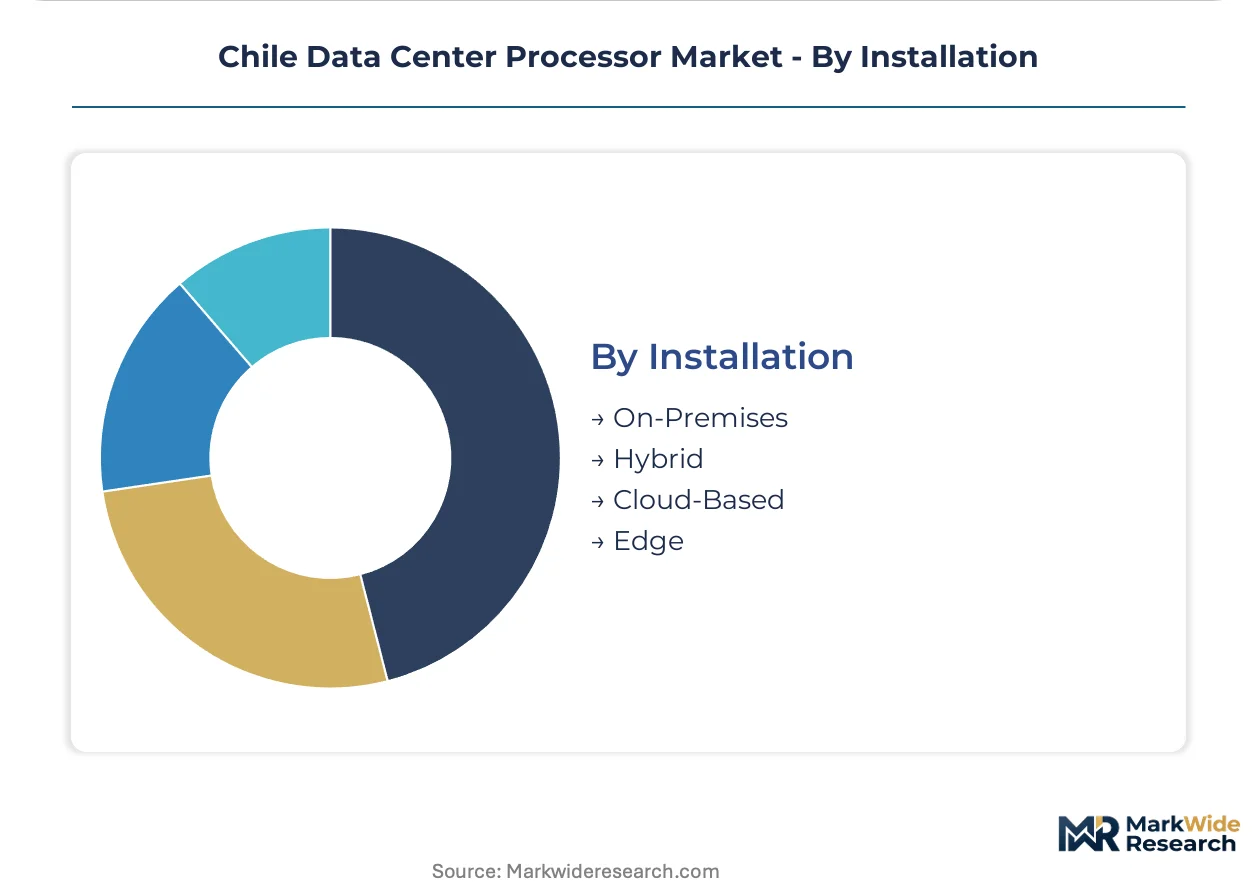
- X86:Intel and AMD instruction set architectures sustain the bulk of on-premises government and legacy enterprise footprints across Santiago Metropolitan Region. Decades of software optimization and compatibility requirements lock in refresh cycles for mission-critical systems in tax administration and pension fund management.
- ARM:Reduced instruction set computing designs gain hyperscale commitments in solar-wind hybrid zones where wattage-per-instruction efficiency determines facility economics. Cloud providers deploying in Atacama renewable parks prioritize ARM-based servers to maximize compute density within carbon-negative positioning.
- PowerPC:IBM architectures serve sovereign compute requirements for defense and research workloads requiring domestic data residency.
- RISC-V:Open instruction set architectures attract experimental deployments in academic and startup environments testing customization capabilities.
Installed base value concentrates in X86 platforms; ARM is climbing the fastest.
End User:
Procurement authority and technical specification control vary dramatically across customer types, reshaping vendor engagement models.
- Hyperscale Providers:Cloud operators with direct server design relationships drive ARM adoption and custom silicon development. These buyers specify thermal and power envelopes before processor selection, reversing traditional vendor-led sales patterns.
- Enterprises:Santiago-based financial institutions and mining conglomerates maintain hybrid procurement with internal IT teams managing on-premises refresh and cloud workload placement.
- Colocation:Multi-tenant facility operators must maintain mixed-architecture fleets to serve diverse tenant requirements without overcommitting to any single vendor roadmap.
- Government:Public sector procurement emphasizes sovereign compute capacity and electromagnetic compatibility certification, creating captive demand for specific architecture categories.
Procurement volume concentrates in Hyperscale Providers; Government represents the most constrained expansion trajectory.
Installation:
Physical deployment location determines processor thermal constraints and power sourcing options.
- On-Premises:Enterprise-owned facilities in Santiago's banking district face space and cooling limitations that favor lower-wattage processor selections despite performance trade-offs.
- Hybrid:Workload-splitting architectures combine local inference with cloud training, requiring processor consistency across environments to minimize refactoring costs.
- Cloud-Based:Hyperscale deployments in renewable-powered zones exploit liquid cooling and high-density configurations unavailable to enterprise-owned facilities.
- Edge:Distributed compute nodes in mining regions and remote government offices prioritize ruggedized processors with wide temperature operating ranges.
Processor shipments concentrate in Cloud-Based installations; Edge deployments show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's data center processor demand concentrates in the Santiago Metropolitan Region, where submarine cable landings and renewable energy parks converge to create a unique deployment corridor.
Santiago Metropolitan Region
The Superintendency of Electricity and Fuels monitors grid stability commitments that operators must maintain when scaling processor density. Chile's Ministry of Energy enforces efficiency benchmarks filtering procurement toward lower-wattage-per-compute-unit designs. Financial institutions in Santiago's banking district drive GPU cluster expansion for real-time fraud detection workloads.
Valparaíso Region
Submarine cable landing stations position this coastal zone as a latency gateway for Latin American cloud workloads. The national standards body certifies electromagnetic compatibility for imported server equipment entering through Pacific ports. Hyperscale providers deploy ARM-based servers in facilities tied to nearby solar generation assets.
Antofagasta Region
Atacama solar-wind hybrid parks offer carbon-negative compute positioning for sustainability-conscious multinational clients. The Ministry of Energy's decarbonization mandates accelerate adoption of power-efficient processor architectures in this zone. Mining sector data residency requirements create edge compute demand for ruggedized processors with wide temperature ranges.
Bío Bío Region
Industrial conglomerates in Concepción maintain hybrid procurement with internal IT teams managing on-premises refresh cycles. Chile's national decarbonization plan reshapes power sourcing requirements for new facilities in this manufacturing hub. Government research workloads requiring sovereign compute capacity anchor PowerPC-based system deployments.
Chile Data Center Processor Market Competitive Landscape
United States producers anchor one tier; Chinese specialists hold price-performance positions in renewable-powered zones. The vendor base spans integrated server-processor portfolios, PowerPC-based sovereign systems, and ARM-focused hyperscale suppliers. Three strategic archetypes dominate: full-stack infrastructure vendors, architecture-specific specialists, and ODM-scale fabricators. Competitive moves center on strategic partnerships with renewable energy developers and geographic expansion into Santiago's connectivity corridors.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise occupy positions serving enterprise refresh cycles across Santiago's banking district. Huawei Technologies exemplifies the price-performance specialist archetype competing for hyperscale deployments tied to renewable power purchase agreements. International Business Machines Corporation represents the sovereign compute category, anchoring PowerPC-based systems for government and research workloads requiring domestic data residency.
| Leading Market Players |
|---|
| Dell Technologies |
| International Business Machines Corporation |
| Hewlett Packard Enterprise |
| Super Micro Computer |
| Cisco Systems |
| Lenovo Group |
| Huawei Technologies |
| Inspur Group |
| Quanta Computer |
| Others |
Pricing and Supply Chain Analysis
Performance-wattage certification tiers split Chile's processor procurement into divergent cost structures, with Ministry of Energy efficiency benchmarks forcing premium pricing for compliant silicon while non-certified inventory clears at distressed levels through secondary channels. This bifurcation concentrates supply chain leverage among vendors with pre-certified product lines, compressing margins for importers caught in six-to-nine month electromagnetic compatibility testing queues.
Pricing Analysis
Volume placements of x86 CPUs in legacy enterprise footprints generate thin margins, while GPU and ARM shipments to hyperscale renewable zones command pricing premiums tied to carbon-intensity disclosure requirements. Price differentiation separates Ministry of Energy-certified processors from uncertified alternatives, with efficiency-grade tiering and foundry energy-source documentation as primary drivers. Cost compression in commodity x86 segments intensifies as hyperscale buyers consolidate procurement around direct server-design relationships. Financial institutions in Santiago's banking district exhibit lowest price sensitivity, prioritizing inference-optimized silicon for fraud detection latency requirements over per-unit cost.
Supply Chain Analysis
Advanced node wafer supply rests on Taiwanese foundry concentration and South Korean memory fabrication, with Chile's import dependency exposing procurement to Panama Canal shipping bottlenecks and Taiwan Strait geopolitical exposure. Silicon wafers, EUV photoresist, and high-bandwidth memory modules constitute critical input dependencies. Single-source vulnerability concentrates in leading-edge process nodes below 5nm, where TSMC anchors global capacity. Distribution runs through Valparaíso port entry and Santiago Metropolitan Region logistics corridors, with national standards body certification creating inventory staging requirements before final delivery to hyperscale construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's data center processor market functions as a consolidation play where import certification timelines and renewable energy compliance costs force sub-scale assemblers toward exit or acquisition.
For Market Incumbents: Cement dominance through backward integration into liquid cooling infrastructure partnerships, capturing stranded processor capacity awaiting electrical completion. Lock in multi-year power purchase agreements with Atacama solar-wind hybrid operators to secure carbon-negative positioning for hyperscale contracts. Intel and AMD face ARM displacement in new-build renewable zones; accelerate custom silicon development for Santiago's banking district latency requirements. For New Entrants and Emerging Players: Mid-tier colocation providers with mixed-architecture fleet requirements represent the most penetrable buyer archetype, as incumbent server vendors over-optimize for hyperscale direct relationships. Target Concepción industrial conglomerates in Bío Bío Region with hybrid on-premises refresh needs underserved by Santiago-centric distribution. Lead with pre-certification against Chilean electromagnetic compatibility standards, converting six-to-nine month import delays into competitive lead time advantage. For Investors and Strategic Acquirers: Re-rating potential sits with ARM-focused ODM-scale fabricators given hyperscale cloud provider procurement consolidation around power-efficient architectures. Sovereign compute mandates for government and research workloads extend PowerPC-based system viability across a decade-long horizon. Watch Ministry of Energy efficiency benchmark tightening as inflection indicator for accelerated ARM adoption and x86 inventory obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Investment | Pre-certification against Chilean electromagnetic compatibility standards compresses import timelines from nine months to six weeks for new server generations. |
| Renewable Power Purchase Agreement | Long-term PPAs with Atacama solar-wind hybrid parks secure carbon-negative compute positioning for sustainability-conscious multinational clients. |
| Liquid Cooling Infrastructure Partnership | Direct-to-chip and immersion technology partnerships align with Santiago's water-scarcity constraints while enabling higher thermal design power processors. |
| Custom Silicon Development | Inference-optimized processor design for Santiago banking district fraud detection workloads captures financial services procurement contract specifications. |
| Edge Compute Ruggedization | Wide temperature-range processor packaging for Antofagasta mining region deployments addresses data residency requirements in remote extraction operations. |
Research Methodology
Multi-period observation of hyperscale construction permits, Ministry of Energy efficiency certification grants, and Superintendency of Electricity and Fuels grid interconnection approvals anchored the trend analysis, supplemented by interviews with data center facility operators, server procurement managers at financial institutions, renewable energy project developers, and national standards body certification officers. Secondary validation drew from customs import records, submarine cable capacity announcements, hyperscaler capital expenditure disclosures, and Chilean government decarbonization plan implementation reports. Bottom-up processor shipment estimates triangulated against top-down facility power capacity expansion data.
Input-output matrices mapped thermal design power requirements against renewable generation load curves, with segmentation across CPU-GPU-FPGA-ASIC product types, X86-ARM-PowerPC-RISC-V technology architectures, and on-premises-hybrid-cloud-edge installation modes. CAGRs were derived from facility construction pipeline analysis correlated with processor procurement lead times. Forecast inputs included Ministry of Energy efficiency benchmark revision schedules and Panama Canal shipping capacity utilization rates.
Revisions become necessary when Ministry of Energy decarbonization mandates accelerate beyond modeled timelines, when Taiwan Strait logistics disruptions exceed thirty-day shipping delays, or when hyperscale provider procurement consolidation shifts faster than certification pipeline capacity. A small set of triggers—renewable energy benchmark tightening, foundry node transition timing, and sovereign cloud mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Middle East Data Center Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
New Zealand Data Center Rack Market
Data Center Infrastructure
Colocation Edge Data Center Market
Data Center Infrastructure
Data Center in Japan Market