
 North America Home Textile Market | 2026-2036
North America Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
North America Home Textile Market Analytics
Digital textile printing is rewriting supply chain economics across the North America home textile sector, compressing design-to-shelf cycles from months to weeks. Welspun Group leverages its integrated spinning-weaving-finishing infrastructure to control quality at scale across bed linen programs. Ralph Lauren anchors its position through brand licensing architecture that extends into exclusive distribution partnerships with specialty retailers. Standard Textiles competes on institutional volume, sustaining long-term supply contracts with hospital and hotel operators throughout the Midwest and Southeast.
North America home textiles encompass woven and non-woven fabric goods designed for interior residential and commercial environments, typically constructed from natural or synthetic fibers with thread counts ranging from 200 to 800 for bed linen applications, and treated with finishes for flame resistance, moisture wicking, or antimicrobial protection to meet performance specifications in hospitality and healthcare settings. Cotton bed linen dominates residential volume due to consumer familiarity and breathability, while polyester blends capture institutional share where durability and laundering tolerance outweigh tactile preferences. Online retail channels represent the fastest-growing distribution pathway, though specialty stores retain margin concentration through curated designer collections and private-label exclusives that resist direct price comparison.
The EPA regulates formaldehyde emissions in finished textiles under TSCA Section 6, while California's Proposition 65 mandates disclosure of phthalates and heavy metals in dyed and coated fabrics sold to consumers. The Consumer Product Safety Commission enforces flammability standards for mattresses and bedding, compelling manufacturers to maintain certified testing protocols or risk market exclusion. Stakeholders must monitor evolving state chemical restriction bills and hospitality sustainability procurement mandates, as these will determine which material platforms and certification investments yield durable competitive position.
Market Dynamics
Post-pandemic hospitality normalization is compressing linen replacement cycles across the United States and Canada, while EPA Safer Choice certification and California chemical disclosure mandates force capital retooling toward low-impact dye systems. This dual pressure on volume and compliance is restructuring competitive position.
Growth Catalysts
- Travel sector rebound:Hotel occupancy recovery across the United States and Canada is accelerating institutional linen procurement from depressed 2020-2021 baselines, particularly in the southeastern manufacturing corridor.
- REACH-aligned state chemistry rules:California's Proposition 65 disclosure mandates and pending state-level PFAS restrictions are pulling mills toward certified supply chains that command hospitality procurement preference.
- Digital print adoption:On-demand pattern production is collapsing design-to-shelf timelines from seasonal to weekly cycles, enabling micro-collection strategies for specialty retail channels.
Market Restraints
- Raw cotton price volatility:Input cost swings tied to Texas and Georgia growing conditions compress margin predictability for undiversified spinners lacking polyester blend flexibility.
- Southeast Asian polyester concentration:Reliance on imported staple fiber from Vietnam and Indonesia exposes converters to freight rate spikes and tariff uncertainty.
- Flammability testing bottlenecks:CPSC mattress and bedding standards create certification backlogs that delay new product launches by 8-14 weeks.
Strategic Opportunities
- Canadian hospitality underpenetration:Toronto and Vancouver hotel construction pipelines lag US recovery, creating whitespace for linen service operators establishing direct mill relationships.
- Circular textile mandates:Extended producer responsibility frameworks emerging in California and New York will reward take-back program infrastructure with preferential procurement status.
- AI-driven demand forecasting:Machine learning integration with digital print workflows enables zero-inventory micro-fulfillment for direct-to-consumer bedding brands.
Industry Challenges
- Color chemist scarcity:Formulation expertise for low-impact dye systems concentrates among retiring specialists, forcing competitive bidding for talent across Carolina-based mills.
- Legacy ERP integration:Digital print workflow adoption requires costly middleware development to synchronize with existing weaving floor control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Home Textile Market |
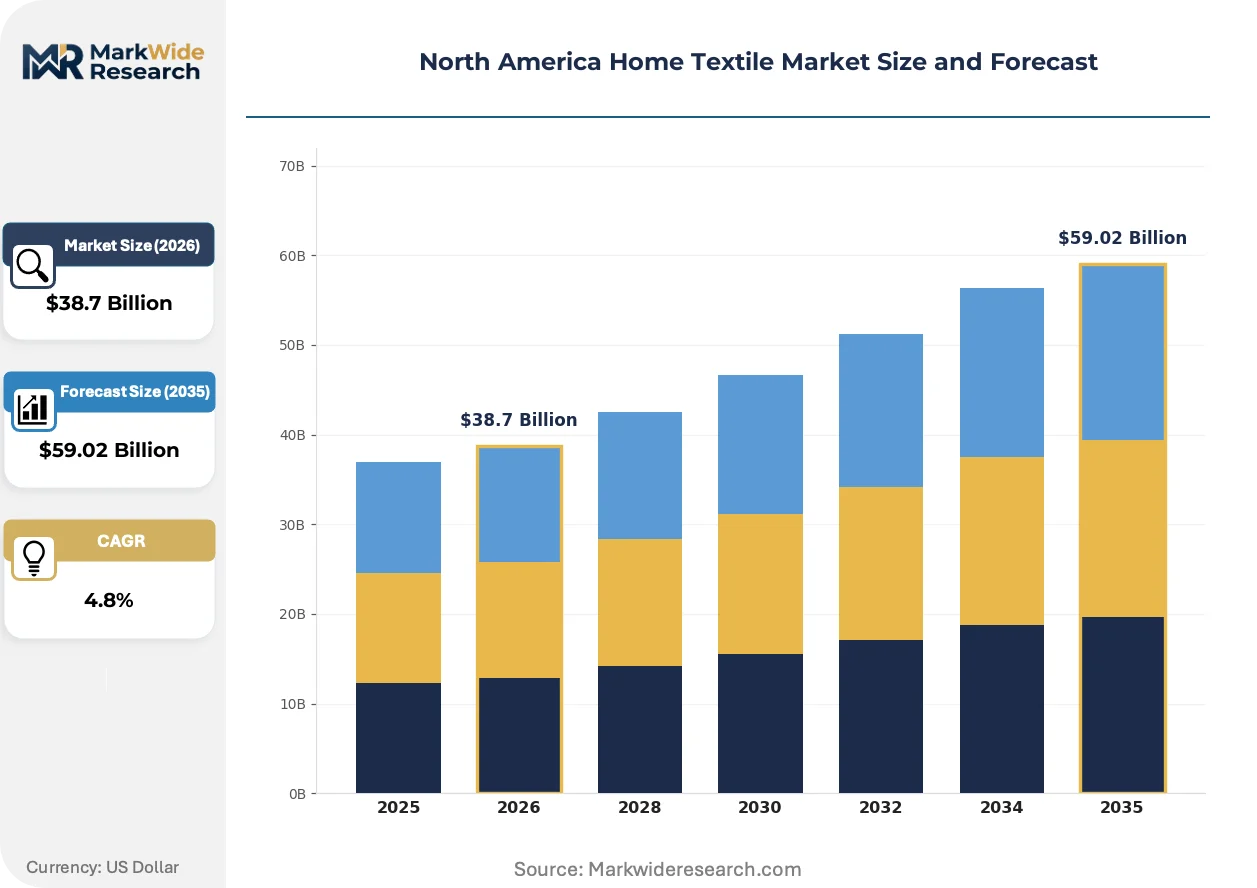
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Linen, Curtains, Table Covers, Cushions Material: Cotton, Polyester, Linen, Velvet End User: Residential, Hotels, Hospitals, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Welspun Group, Ralph Lauren, New Sega Home Textiles, Standard Textiles, H&M Group, American Textile Company, DivaTex, Calvin Klein Home, WestPoint Home, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Home Textile Market Evolving Landscape
Three intersecting forces are restructuring North American home textiles: digital production workflows compressing cycle times, chemical transparency mandates rewiring supplier qualification, and channel fragmentation rewarding agile fulfillment architectures over seasonal bulk production.
Single-pass digital textile printing is digitizing pattern development and sample production, eliminating engraved roller lead times. Hospitality procurement teams across the Midwest and Southeast are piloting weekly replenishment programs against traditional quarterly bulk orders. This compression is digitizing the entire design-to-shelf value chain, collapsing competitive advantage from scale economies to responsiveness.
EPA enforcement of TSCA Section 6 formaldehyde limits is tightening testing documentation requirements for imported finished goods. Mills serving California retailers now maintain dual certification stacks for both federal and state chemical disclosure regimes. The institutional segment—hospitals and extended-stay hotels—faces the steepest compliance cost escalation as procurement teams demand third-party verified supply chain documentation.
Direct-to-consumer bedding brands are unbundling traditional retail markups by launching subscription-based refresh programs. Specialty stores respond with exclusive designer collaborations that resist price comparison, while mass merchants consolidate private-label sourcing around fewer, larger mill partners. This channel bifurcation is most pronounced in Texas and Florida, where population growth supports both premium showroom expansion and value-oriented big-box penetration.
North America Home Textile Market Segmentation
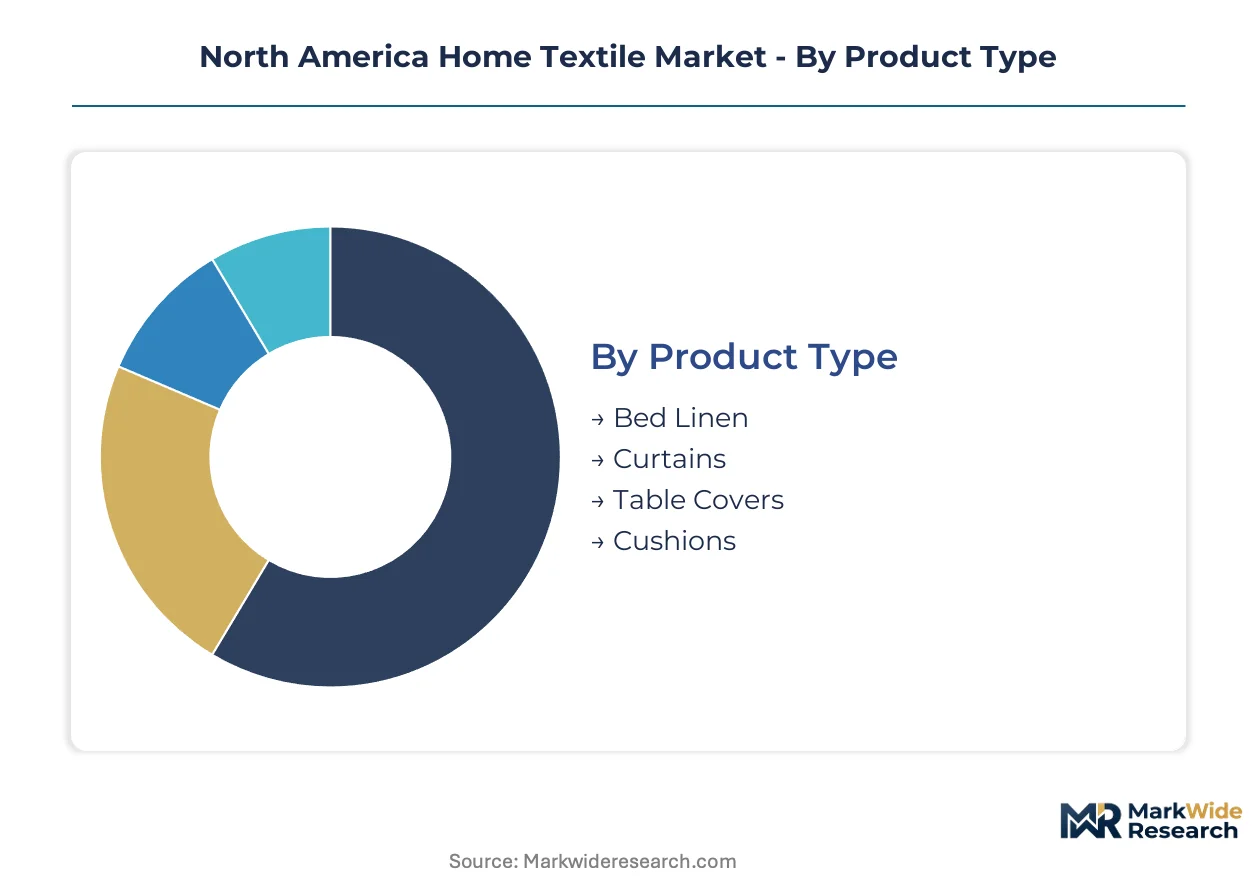
Segmentation in North American home textiles determines procurement cadence, margin structure, and compliance exposure across distinct customer ecosystems. Each dimension carries unique inventory velocity profiles and regulatory touchpoints that reshape supplier priorities.
Product Type:
Bed linen commands the shortest replacement cycles in hospitality settings, turning over every 90-180 days under institutional laundering protocols, while curtains and decorative categories stretch toward multi-year residential refresh timelines.
- Bed Linen:Woven sheeting and pillowcase constructions with thread counts from 200 to 800, finished for institutional durability or residential softness. Hotel procurement teams in the Southeast United States compress replacement cycles to quarterly intervals as occupancy normalizes, driving volume concentration in Carolina-based manufacturing corridors.
- Curtains:Window treatments spanning sheer, blackout, and thermal-lined constructions with header styles for rod-pocket or grommet installation. Demand clusters in Texas and Florida residential construction markets where new housing permits outpace national averages, though hospitality specification work lags bed linen velocity.
- Table Covers:Dining surface textiles including placemats, runners, and banquet-sized cloths treated for stain resistance.
- Cushions:Decorative and functional pillow forms with removable covers, spanning indoor and outdoor performance specifications.
Bed linen anchors the volume base while curtains gain share at the steepest rate among residential renovation spend.
Material:
Raw material selection governs laundering tolerance, chemical certification pathways, and price positioning across residential and institutional channels.
- Cotton:Cellulosic staple fiber prized for breathability and hand-feel, sourced predominantly from Texas and Georgia growing regions. Residential consumers in the Southeast United States favor cotton bed linen for climate-appropriate sleep comfort, though drought-induced price volatility forces blend flexibility among spinners.
- Polyester:Synthetic polymer staple and filament constructions engineered for dimensional stability and rapid drying. Hospital linen services across the Midwest specify polyester-dominant blends for industrial laundering tolerance, accepting tactile trade-offs for lifecycle cost efficiency.
- Linen:Bast fiber from flax plants, offering superior moisture wicking and temperature regulation at premium price points.
- Velvet:Pile-weave constructions with cut or looped surface texture, concentrated in decorative applications.
Cotton dominates absolute shipment volumes while polyester climbs fastest under institutional sustainability mandates favoring extended replacement intervals.
End User:
Customer type dictates performance certification requirements, order granularity, and contract structure across the value chain.
- Residential:Individual household purchasers selecting for aesthetic preference, tactile comfort, and price accessibility. Online retail channels capture the steepest expansion in this segment as direct-to-consumer bedding brands collapse traditional retail markups through subscription refresh programs.
- Hotels:Lodging operators procuring institutional-grade linens under volume contracts with specified replacement schedules. Post-pandemic occupancy recovery across the United States and Canada accelerates procurement from depressed baselines, particularly in the southeastern manufacturing corridor.
- Hospitals:Healthcare facilities requiring antimicrobial finishes, flame resistance certification, and industrial laundering compatibility.
- Restaurants:Food service establishments sourcing table linens and napkins with stain-resistant treatments for commercial laundering.
Hotels anchor the institutional volume base while residential channels expand most quickly through digital distribution disruption.
Distribution Channel:
Channel selection determines margin capture, brand control, and inventory risk allocation between manufacturers and retail intermediaries.
- Online Retail:Direct-to-consumer and marketplace platforms enabling bypass of traditional wholesale markups. Specialty bedding brands leverage AI-driven demand forecasting with digital print workflows to enable zero-inventory micro-fulfillment, compressing design-to-shelf cycles from months to weeks.
- Supermarkets:Mass merchant retail chains consolidating private-label sourcing around fewer, larger mill partners. Value-oriented penetration concentrates in Texas and Florida population growth corridors where big-box expansion outpaces specialty store development.
- Specialty Stores:Curated retail environments offering designer collections and private-label exclusives resistant to direct price comparison.
- Wholesalers:Intermediary distributors serving smaller hospitality operators and regional retail accounts.
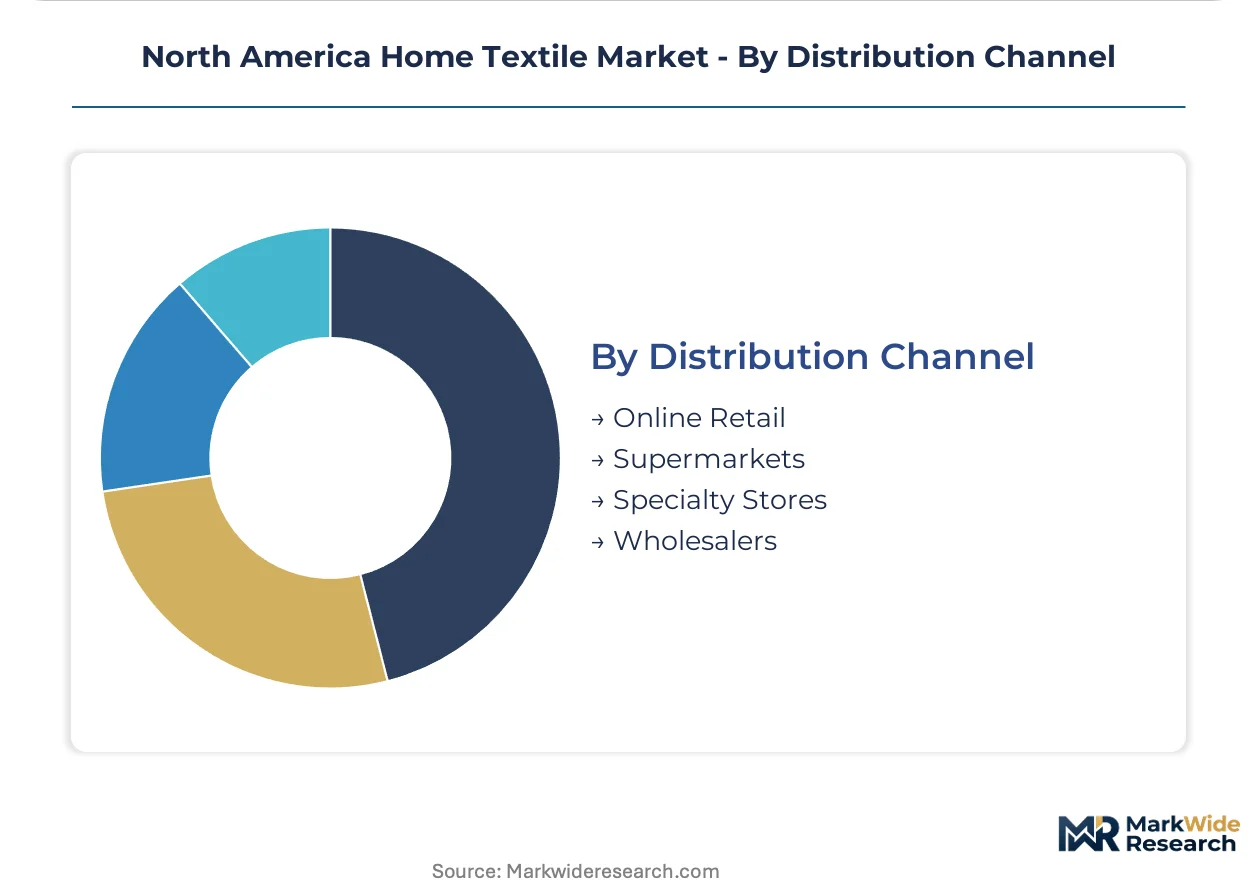
Supermarkets anchor the volume base while online retail gains share at the steepest rate through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American home textile trade maintains a modest export surplus in specialized technical fabrics while importing commodity sheeting from South Asian mills. Cross-border supply chains between the United States, Canada, and Mexico concentrate finishing and distribution activities near major consumer markets rather than fiber origins. Regional procurement patterns diverge sharply between institutional bulk contracting and direct-to-consumer digital channels.
United States
Southeastern states anchor domestic manufacturing volume, with Carolina-based mills serving hospitality procurement teams from Atlanta to Miami. EPA enforcement of TSCA Section 6 formaldehyde limits tightens documentation requirements for imported finished goods, pushing retailers toward certified domestic suppliers. Georgia and Texas cotton-growing regions supply staple fiber to regional spinners, though drought-induced volatility forces blend flexibility with polyester imports.
Canada
Toronto and Vancouver hotel construction pipelines lag US recovery benchmarks, creating whitespace for linen service operators establishing direct mill relationships. Health Canada maintains flammability standards aligned with CPSC protocols, enabling cross-border product certification reciprocity for mattress and bedding categories. Quebec-based distributors increasingly source finished goods from US southeastern mills rather than overseas to compress lead times.
Mexico
Nuevo León and the Bajío Region attract cut-and-sew operations serving US retail private-label programs under USMCA tariff preferences. Mexico's textile sector faces mounting pressure from California-style chemical disclosure rules as US buyers extend compliance requirements southward. Guanajuato-based converters specialize in quick-turn decorative categories for Texas and Arizona residential markets.
North America Home Textile Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated mill groups and brand licensing architectures that control distribution access. Mid-scale converters face margin compression from both raw material volatility and digital print workflow investments. Three archetypes dominate: integrated fiber-to-finish manufacturers, brand licensing platforms, and institutional volume specialists. Competitive moves concentrate on M&A to secure Carolina manufacturing assets and strategic partnerships to access AI-driven demand forecasting capabilities.
Among India-based integrated manufacturers, Welspun Group occupies a position exemplifying captive control over spinning-weaving-finishing infrastructure. Ralph Lauren represents the brand licensing archetype, extending trademark value through exclusive retail distribution arrangements. Standard Textiles anchors the institutional specialist tier, sustaining long-term supply relationships with hospital and hotel operators across the Midwest and Southeast.
| Leading Market Players |
|---|
| Welspun Group |
| Ralph Lauren |
| New Sega Home Textiles |
| Standard Textiles |
| H&M Group |
| American Textile Company |
| DivaTex |
| Calvin Klein Home |
| WestPoint Home |
| Others |
Value Network & Pricing Analysis
Port of Charleston freight corridors connecting Carolina-based mills to southeastern distribution hubs transmit raw cotton volatility directly into bed linen price differentiation, while EPA compliance costs for low-impact dye systems widen spreads between certified and conventional supply tiers.
Pricing Analysis
Digital print workflow investments versus legacy roller engraving systems versus next-generation AI-integrated micro-fulfillment platforms create a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—EPA Safer Choice and California Proposition 65 compliance—and volume scale under institutional contracting. Cost compression in standard-tier polyester blends is intensifying because of Southeast Asian staple fiber freight rate spikes. Hospital procurement teams exhibit lowest price sensitivity due to lifecycle cost modeling, while residential direct-to-consumer buyers show highest elasticity.
Supply Chain Analysis
Tariff exposure between Vietnam and the United States dominates supply chain risk calculus for polyester staple converters serving institutional buyers. Raw material sourcing draws from Texas and Georgia cotton regions, Indonesian and Vietnamese polyester staple, and Carolina-based spinning infrastructure. Single-source vulnerability concentrates in imported dye chemicals subject to REACH-aligned state disclosure mandates. Distribution runs through southeastern manufacturing corridors feeding retail consolidation centers and direct-to-consumer fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-pandemic hospitality occupancy normalization positions this market in cyclical recovery, with hotel linen replacement cycle compression as the operative demand driver.
For Market Incumbents: Insulate margin position through captive dye formulation capability and dual certification stacks for federal and state chemical regimes. Threats concentrate in digital-native entrants bypassing traditional wholesale markups through subscription refresh programs. Priority lever rests on backward integration into spinning assets in Georgia and the Carolinas to control cotton blend flexibility. For New Entrants and Emerging Players: Build out direct mill relationships with Toronto and Vancouver hotel construction pipelines, the most penetrable whitespace in institutional procurement. Canadian hospitality underpenetration relative to US benchmarks offers volume traction without incumbent contract lock-in. Go-to-market angle centers on weekly replenishment programs against quarterly bulk ordering norms. For Investors and Strategic Acquirers: Carolina-based mills with integrated weaving-finishing infrastructure and established EPA certification documentation represent the acquisition target archetype with durable competitive position. Long-term viability frames around chemical transparency mandate expansion and circular textile EPR framework adoption. Signal to watch is California and New York extended producer responsibility legislation progression as procurement preference determinant.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Print Workflow Integration | Collapses design-to-shelf cycles from seasonal to weekly intervals for specialty retail. |
| EPA Safer Choice Certification Investment | Unlocks hospitality procurement preference as chemical disclosure rules tighten. |
| Carolina Manufacturing Asset Acquisition | Secures spinning-weaving-finishing infrastructure with proximity to southeastern distribution hubs. |
| AI-Driven Demand Forecasting Deployment | Enables zero-inventory micro-fulfillment for direct-to-consumer bedding brands. |
| Take-Back Program Infrastructure Buildout | Positions for preferential procurement status under emerging circular textile mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with textile mill operations directors, hospitality procurement managers, chemical compliance officers, and specialty retail category buyers; and secondary validation through EPA enforcement records, California Proposition 65 filings, customs trade data, and hospital GPO contract databases. Bottom-up shipment estimates triangulated against top-down spending flow analysis.
Forecast inputs span product type, material composition, end-user segment, and distribution channel dimensions across the projection horizon. CAGRs were derived from regression analysis against hospitality occupancy indices and residential construction permit data. Industry-specific inputs incorporate cotton futures volatility patterns and state-level chemical restriction bill tracking.
Stress conditions across raw cotton price bands, freight rate spikes, and certification timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospitality recovery trajectory and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Fabric Wash and Care Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Blanket Market
Home Textiles
Plush Blanket Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
UAE Home Textiles Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
United States Home Textile Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
Towel Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Cotton Towel Market
Home Textiles
Home Textile Products Market
Home Textiles
Germany Home Textile Market