
 Asia-Pacific Home Textile Market | 2026-2036
Asia-Pacific Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Home Textile Market Outlook
Subscription-based linen replacement programs for hotels and long-term care facilities is broadening how home textile value gets captured in the Asia-Pacific region. Welspun Living Ltd leverages its integrated spinning-to-retail infrastructure to control quality across cotton towel and bed linen output. Trident Group anchors its position through massive terry towel capacity serving hospitality buyers across India and export markets. Shenzhen Fuanna Bedding and Furnishing Co Ltd differentiates via design-led direct-to-consumer channels targeting urban residential segments in tier-one Chinese cities.
Asia-Pacific home textiles encompass woven, knitted, and non-woven fabric articles designed for domestic interior environments, typically manufactured through ring spinning, air-jet weaving, and finishing processes involving mercerization, calendering, or antimicrobial treatment to achieve specified thread counts and durability standards. Cotton bed linen and polyester-cotton blended towels dominate volume production, while silk curtains and linen upholstery command premium positioning in residential and luxury hospitality channels. The hospitality end-user segment represents the fastest-growing demand pool as hotel chains expand across Southeast Asia, whereas wholesale distribution channels still capture the largest transaction value despite online platforms gaining share in residential markets.
China's SAMR enforces GB standards for textile labeling and chemical content, while India's BIS mandates ISI certification for cotton products, and Japan's METI oversees JIS quality benchmarks for imported home textiles entering its retail channels. These frameworks elevate compliance costs for smaller mills but create market access advantages for certified producers supplying institutional buyers. Stakeholders must monitor evolving eco-label requirements and digital traceability mandates as procurement teams at major hospitality groups prioritize verified sustainable sourcing credentials in supplier selection.
Market Dynamics
Hospitality procurement teams across Southeast Asia are consolidating supplier bases as branded hotel chains expand room inventories, compressing vendor selection cycles and elevating certification requirements for institutional bed linen and towel contracts.
Growth Catalysts
- India's BIS certification mandate:The Bureau of Indian Standards ISI mark for cotton textiles is disqualifying uncertified mills from institutional procurement channels, concentrating volume with compliant producers.
- Subscription linen replacement:Hotels and aged-care facilities are adopting recurring replacement programs rather than spot purchasing, locking in multi-year supplier relationships and predictable revenue streams.
- China's Yangtze River Delta cluster:Integrated spinning-weaving-finishing infrastructure in this manufacturing belt delivers compressed lead times for export-grade hospitality textiles.
Market Restraints
- Raw cotton price volatility:Input cost swings for natural fiber destabilize margin structures for mills without backward integration into captive cotton sourcing.
- Concentrated dye-chemical supply:Reliance on Zhejiang and Jiangsu province chemical processors creates single-point vulnerability for eco-compliant finishing capabilities.
- Japan's METI import standards:JIS quality benchmarks for thread count and colorfastness add testing overhead that smaller exporters struggle to absorb.
Strategic Opportunities
- Vietnam hospitality construction pipeline:New resort and business hotel developments in Da Nang and Ho Chi Minh City are generating first-mover procurement contracts for certified linen suppliers.
- China's GB eco-labeling expansion:SAMR mandates for digital traceability and carbon disclosure are creating premium positioning for mills with verified sustainable sourcing systems.
- Direct-to-residential platforms:Design-led bedding brands are bypassing wholesale distribution to capture margin through owned e-commerce channels in tier-one Chinese cities.
Industry Challenges
- Antimicrobial finishing expertise gap:Formulation chemistry and application engineering talent for hospitality-grade durable treatments remains scarce outside established technical textile centers.
- Dual certification timelines:Simultaneous pursuit of India's BIS marks and China's GB standards extends product launch cycles by 8-14 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Home Textile Market |
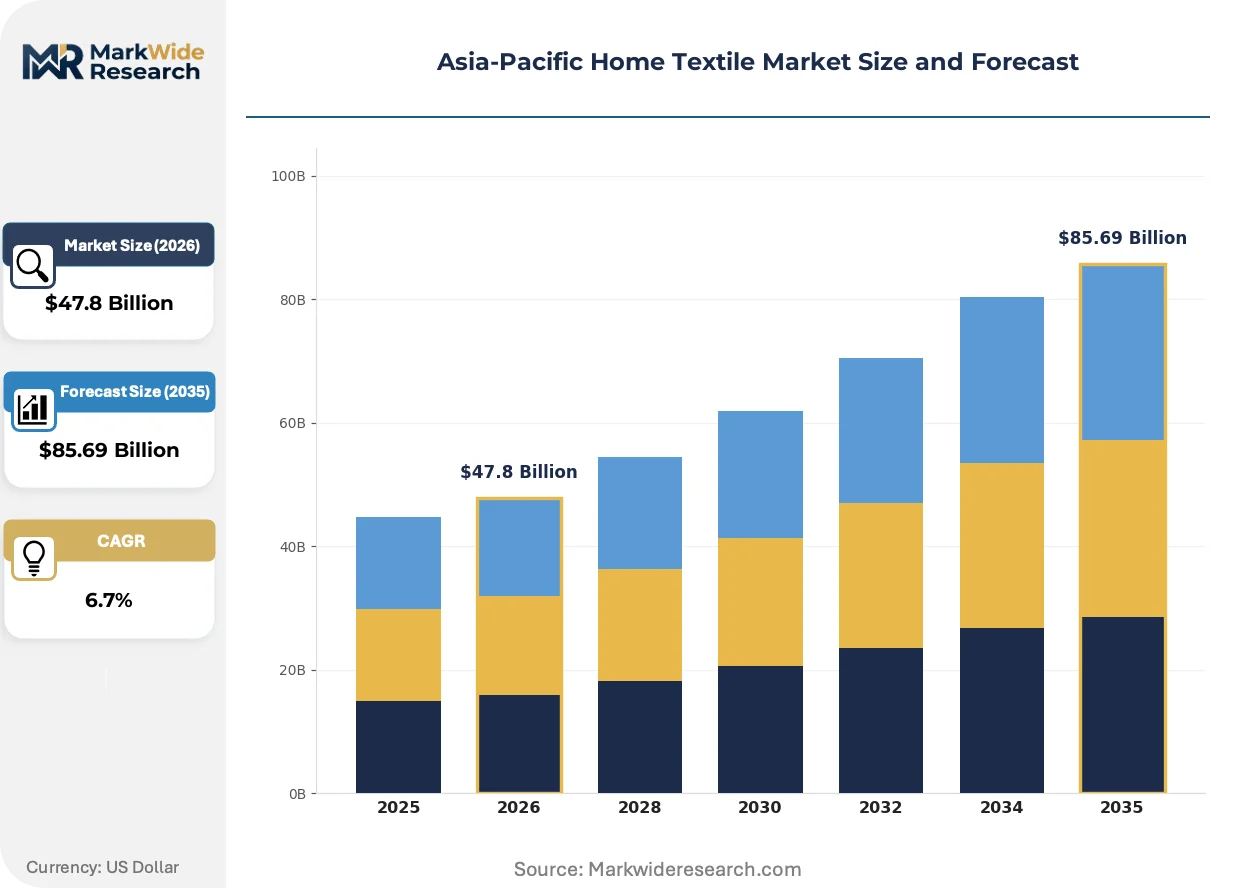
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $85.69 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cushions, Bed Linen, Towels, Curtains Material: Cotton, Polyester, Linen, Silk End User: Residential, Hospitality, Institutional, Healthcare Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Welspun Living Ltd, Trident Group, Shenzhen Fuanna Bedding and Furnishing Co Ltd, LUOLAI Lifestyle Technology Co. Ltd, Toray Industries, Hunan Mendale Hometextile, Arvind Limited, Himatsingka Seide Ltd, Loftex Marvic Textiles, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Home Textile Market Strategic Shifts
Digital traceability platforms and bio-based finishing chemistry are converging to reshape how procurement teams verify supply chain credentials and product safety claims across institutional and residential channels.
Recycled polyester-cotton blended yarn is expanding into premium towel production as hospitality buyers seek lower-carbon alternatives without sacrificing absorbency or durability standards. Major hotel chains in Thailand and Indonesia are piloting these blends for pool and spa linens. The shift is expanding into mid-tier property segments previously locked into virgin cotton specifications.
China's SAMR enforcement of expanded GB standards for textile chemical content and labeling accuracy is forcing reformulation of dyes and softeners across the Yangtze River Delta manufacturing base. Mills serving export markets are accelerating third-party testing investments to preempt detention at customs. Japanese and South Korean import channels are experiencing the tightest compliance scrutiny as METI and MFDS align with stricter disclosure requirements.
Long-term linen leasing and managed replacement services are displacing outright purchase models among aged-care operators and mid-scale hotel groups. Australian and New Zealand facility managers are contracting full-service textile programs that bundle inventory, laundering logistics, and scheduled refresh cycles. Procurement teams in these markets now prioritize total cost-of-ownership metrics over unit pricing in vendor selection.
Asia-Pacific Home Textile Market Segmentation
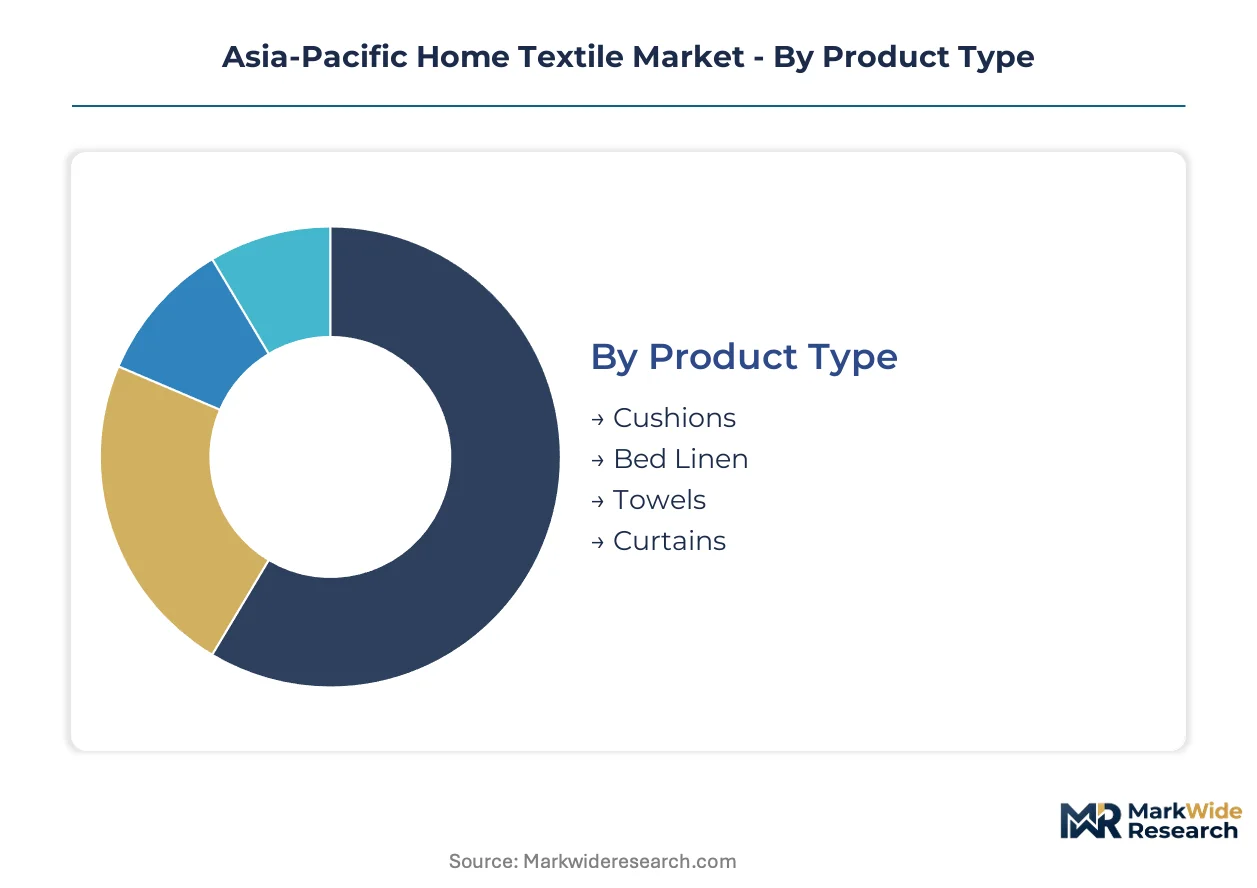
Asia-Pacific home textile procurement teams segment demand across four intersecting dimensions: product specifications determine technical compliance requirements, material composition drives sustainability credentials, end-user category dictates volume scale and replacement cadence, and channel structure governs margin capture and brand positioning.
Product Type:
Buyer specifications vary sharply between replacement-driven consumables and long-cycle decorative investments.
- Bed Linen:Thread count specifications and finishing treatments dominate institutional procurement decisions. India's BIS-certified producers capture hospitality volume in Mumbai and Bangalore hotel supply chains.
- Towels:Terry construction density and antimicrobial finishing determine hospitality grading. China's Yangtze River Delta mills supply branded hotel chains across Thailand and Vietnam with compressed lead times.
- Curtains:Flame-retardant treatments and light-blocking coefficients serve commercial and residential segments. Japanese METI import standards elevate testing overhead for cross-border suppliers.
- Cushions:Fill power and cover durability specifications vary by application. Australian aged-care facilities prioritize pressure-relief engineering in procurement.
Volume sits with bed linen and towels; growth tilts toward antimicrobial-finished hospitality specifications.
Material:
Raw fiber selection determines compliance pathway, carbon footprint claims, and price positioning across procurement tiers.
- Cotton:Natural fiber dominates institutional specifications for breathability and absorbency. India's Tamil Nadu belt supplies ring-spun yarn to domestic hospitality buyers and export channels.
- Polyester:Recycled PET feedstock is expanding into premium towel blends as Thai and Indonesian hotel chains pilot lower-carbon alternatives without durability sacrifice.
- Linen:Belgian and French flax supply chains serve luxury residential segments in Shanghai and Tokyo. Premium positioning commands three-to-four-fold pricing over cotton equivalents.
- Silk:Mulberry cultivation regions in China supply high-end curtain and upholstery applications. Japanese retail channels maintain strict JIS quality benchmarks for imported silk textiles.
Cotton holds volume dominance; recycled polyester blends are climbing the fastest on sustainability-driven hospitality procurement.
End User:
Replacement frequency and specification rigor separate cyclical residential demand from contract-driven institutional procurement.
- Hospitality:Branded hotel chains across Southeast Asia consolidate supplier bases as room inventories expand. Subscription-based linen replacement programs lock in multi-year supplier relationships with predictable revenue structures.
- Residential:Tier-one Chinese cities drive design-led direct-to-consumer channels. Shenzhen Fuanna and comparable brands bypass wholesale distribution to capture margin through owned e-commerce platforms.
- Healthcare:Antimicrobial finishing and barrier protection specifications govern procurement. Australian and New Zealand facility managers contract full-service textile programs bundling inventory, laundering logistics, and scheduled refresh cycles.
- Institutional:Educational and government facilities prioritize durability metrics and total cost-of-ownership over unit pricing. India's BIS certification mandate disqualifies uncertified mills from public procurement channels.
Residential channels transact the highest volume; hospitality procurement is expanding most quickly on Southeast Asia construction pipelines.
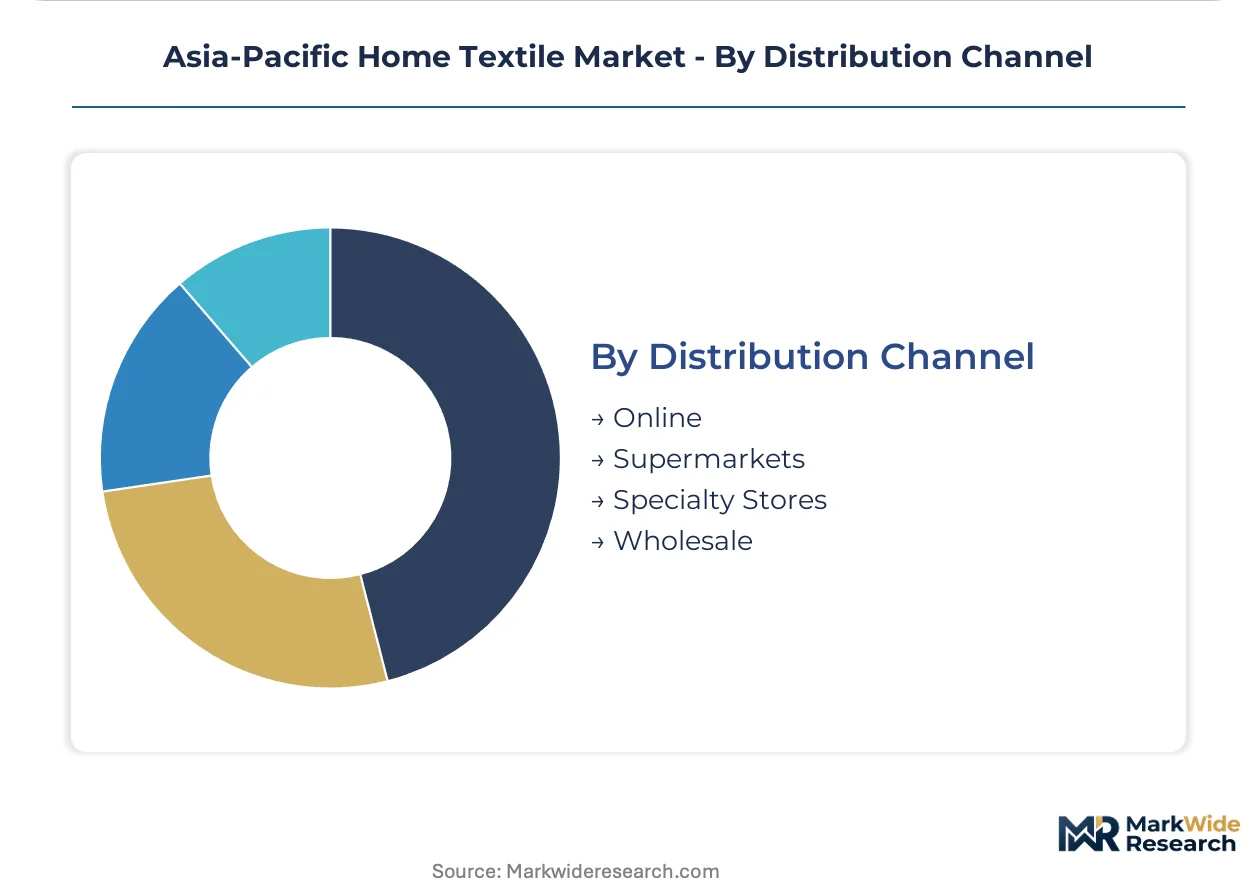
Distribution Channel:
Channel selection determines margin structure, brand control, and customer data access across market tiers.
- Wholesale:Bulk procurement relationships dominate hospitality and institutional supply. China's Yangtze River Delta manufacturing cluster ships export-grade volumes through consolidated distributor networks serving regional hotel chains.
- Online:Direct-to-residential platforms gain share in tier-one Chinese cities. Design-led bedding brands leverage digital channels for margin capture and rapid style turnover.
- Specialty Stores:Curated assortment and tactile evaluation support premium residential positioning. Japanese department store channels enforce strict JIS compliance for imported home textiles.
- Supermarkets:Mass-market volume moves through price-competitive retail formats. India's organized retail expansion distributes BIS-certified cotton products to urban residential segments.
Wholesale channels retain the largest transaction value; online platforms are gaining share fastest on urban residential digital adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of Asia-Pacific home textile exports while India and Southeast Asian markets absorb expanding hospitality and residential demand. Production concentrates in coastal manufacturing belts with integrated spinning-to-finishing infrastructure. Consumption patterns diverge sharply between institutional procurement in hotel development corridors and design-led retail in wealthy urban centers.
China
Hospitality construction across Thailand and Vietnam drives export orders for Yangtze River Delta mills with compressed lead times. SAMR enforces expanding GB standards for eco-labeling and digital traceability that elevate compliance investments. The manufacturing cluster around Shanghai and Ningbo ships terry towels and bed linen to Southeast Asian hotel chains under multi-year supply contracts.
India
Domestic hotel expansion in Mumbai and Bangalore consumes BIS-certified cotton bed linen from Tamil Nadu textile belt producers. The Bureau of Indian Standards ISI mark mandate disqualifies uncertified mills from institutional procurement channels. Ring-spun yarn facilities in Coimbatore and Tiruppur supply both hospitality buyers and export markets with compliant finished goods.
Japan
Import-dependent retail channels enforce strict JIS quality benchmarks for thread count and colorfastness on Chinese and Indian suppliers. METI oversight of textile labeling creates testing overhead that smaller exporters struggle to absorb. Tokyo and Osaka department stores source premium silk curtains and linen upholstery through verified supply chains with documented chemical compliance.
Vietnam
Resort and business hotel developments in Da Nang and Ho Chi Minh City generate first-mover procurement contracts for certified linen suppliers. The country's construction pipeline lacks domestic manufacturing capacity, creating import dependency on Chinese and Indian mills. Procurement teams prioritize suppliers with dual BIS and GB certification to preempt customs delays and quality disputes.
Australia
Aged-care facility managers contract full-service textile programs bundling inventory, laundering logistics, and scheduled refresh cycles. The shift from outright purchase to subscription-based linen replacement locks in multi-year supplier relationships. Sydney and Melbourne procurement teams now prioritize total cost-of-ownership metrics over unit pricing in vendor selection frameworks.
Asia-Pacific Home Textile Market Competitive Environment
Capital-heavy producers compete with asset-light designers across tiered competitive positions in the Asia-Pacific home textile market. Integrated spinning-weaving-finishing operations anchor volume supply to hospitality chains while direct-to-consumer brands capture margin through owned digital channels. Three archetypes dominate: backward-integrated mill groups with captive cotton sourcing, design-led residential specialists with e-commerce infrastructure, and regional trading houses consolidating fragmented supplier bases. Competitive intensity centers on certification acquisition speed and multi-year contract lock-in with expanding hotel groups.
Within the integrated manufacturing tier, Welspun Living Ltd and Trident Group exemplify capital-intensive positions with upstream control over raw material flows. Shenzhen Fuanna Bedding and Furnishing Co Ltd occupies the design-led residential archetype, leveraging direct channels to bypass wholesale margin compression. These three entities represent contrasting strategic bets on institutional versus consumer end-markets across the region's diverging demand pools.
| Leading Market Players |
|---|
| Welspun Living Ltd |
| Trident Group |
| Shenzhen Fuanna Bedding and Furnishing Co Ltd |
| LUOLAI Lifestyle Technology Co. Ltd |
| Toray Industries |
| Hunan Mendale Hometextile |
| Arvind Limited |
| Himatsingka Seide Ltd |
| Loftex Marvic Textiles |
| Others |
Value Chain & Pricing Dynamics
Branded hotel chains across Southeast Asia concentrate procurement volume through consolidated supplier bases, compressing vendor selection cycles and forcing contract-based long-term offtake pricing with multi-year lock-ins and predictable refresh schedules.
Pricing Analysis
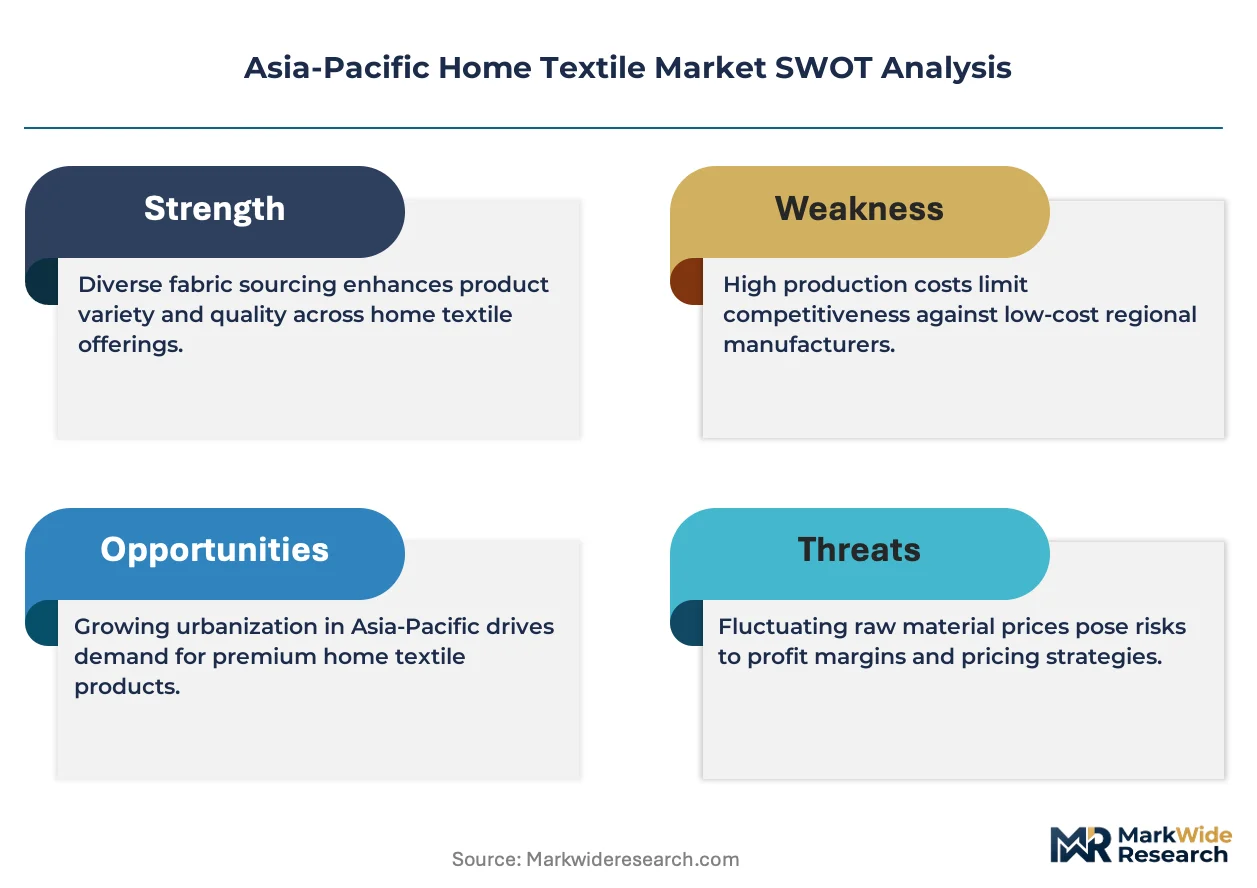
Margin tightening in mid-tier hospitality textiles reflects raw cotton price volatility and concentrated dye-chemical supply from Zhejiang and Jiangsu processors. Three-tier pricing structure across premium antimicrobial-finished, standard institutional-grade, and economy unbranded tiers separates certified BIS-marked producers from uncertified mills. Cost-down pressure on standard-grade bed linen accelerates because India's BIS certification mandate disqualifies non-compliant suppliers from public procurement channels. Budget hotel operators exhibit highest price sensitivity, while luxury resort procurement teams prioritize total cost-of-ownership over unit pricing.
Supply Chain Analysis
Subscription-based linen replacement programs create reverse-logistics flows as aged-care operators and hotel groups return end-of-life textiles for managed refresh cycles rather than outright disposal. Primary manufacturing concentrates in China's Yangtze River Delta, India's Tamil Nadu textile belt, and Vietnam's emerging cut-and-sew corridors. Raw material sourcing draws from ring-spun cotton cultivation in Gujarat and Maharashtra, recycled PET feedstock processing in Jiangsu, and Belgian flax for luxury linen segments. Single-source vulnerability in Zhejiang chemical finishing creates supply chain risk for eco-compliant dye formulations. Distribution runs through consolidated wholesale networks serving hospitality chains and direct-to-consumer platforms in tier-one Chinese cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification mandate and China's expanding GB eco-labeling standards erect compliance barriers that concentrate market access with certified producers, creating sustainable moats for institutional suppliers.
For Market Incumbents: Anchor multi-year supplier relationships through subscription linen replacement programs that bundle inventory, laundering logistics, and scheduled refresh cycles. Deepen backward integration into captive cotton sourcing to buffer margin structures against raw fiber price volatility. Defend against emerging design-led direct-to-consumer brands by accelerating third-party testing investments for dual BIS and GB certification. For New Entrants and Emerging Players: E-commerce platform operators present the most penetrable channel for bypassing wholesale margin compression in tier-one Chinese cities. Target Vietnam's resort construction pipeline in Da Nang and Ho Chi Minh City where domestic manufacturing capacity gaps create first-mover procurement opportunities. Pursue white-label partnerships with Australian aged-care facility managers seeking full-service textile program bundling. For Investors and Strategic Acquirers: The window for entry favors integrated spinning-weaving-finishing operations with verified sustainable sourcing credentials and existing hospitality chain contracts. Long-term viability hinges on acquisition of mills with dual certification capability and compressed lead time infrastructure in the Yangtze River Delta or Tamil Nadu belt. Monitor antimicrobial finishing expertise gaps as inflection indicator for technical textile center consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous BIS and GB standard pursuit unlocks cross-border procurement contracts with Vietnamese hospitality developers. |
| Subscription Service Launch | Recurring replacement programs lock in multi-year revenue streams with Australian aged-care facility managers. |
| Backward Integration | Captive cotton sourcing in Gujarat buffers margin structures against commodity price volatility for Tamil Nadu mills. |
| Direct-to-Consumer Platform | Owned e-commerce channels capture margin from design-led bedding demand in Shanghai and Shenzhen urban segments. |
| Antimicrobial Finishing Partnership | Technical textile center alliances address formulation chemistry scarcity for hospitality-grade durable treatments. |
Study Parameters
Multi-period observation of hospitality construction permits, certification acquisition timelines, and subscription service adoption rates anchored the trend analysis, supplemented by interviews with procurement directors at branded hotel chains, textile mill operations managers, BIS certification auditors, and SAMR compliance officers. Secondary validation drew from customs export records, Bureau of Indian Standards certification databases, China GB standards enforcement bulletins, and METI import inspection reports. Bottom-up volume modeling across product-material-end-user-channel intersections triangulated with top-down macroeconomic demand projections.
Segment-weighting applied product type, material composition, end-user category, and distribution channel dimensions across the modeling period, with additional granularity for antimicrobial finishing specification tiers. CAGRs derived from logistic curve fitting to hospitality room inventory expansion data and residential digital commerce penetration rates. Forecast inputs incorporated raw cotton futures volatility indices and evolving eco-label compliance cost trajectories.
Caveats apply where raw material price spikes, regulatory enforcement delays, or logistics disruptions could materially shift the outlook. Practitioners should monitor BIS certification backlog durations and SAMR digital traceability mandate implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Bath Towel Market
Home Textiles
North America Home Textile Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Plush Blanket Market
Home Textiles
Home Textile Products Market
Home Textiles
Home Textiles Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Canada Home Textile Market
Home Textiles
Russia Home Textile Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Global Theater Linen Market
Home Textiles
India Home Textile Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
UAE Home Textiles Market
Home Textiles
Europe Home Textile Market