
 Germany Home Textile Market | 2026-2036
Germany Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Home Textile Market Foresight
Online retail channels is reconfiguring how German consumers access home textiles, compressing traditional wholesale and department store pathways. Westwing Group SE leverages curated digital storefronts to dominate premium direct-to-consumer positioning. Home24 SE anchors its growth in logistics density across mid-market furniture-textile bundles. IKEA Deutschland sustains market presence through in-house production of cotton-dominant bedding lines and captive supply of flat-pack compatible textiles.
Germany home textiles encompass woven, knitted, and non-woven fabric products designed for interior domestic environments, typically specified by thread count, fiber composition, and Oeko-Tex Standard 100 certification for chemical safety. These products serve functional purposes spanning sleep hygiene, thermal insulation, acoustic dampening, and aesthetic coordination within residential and commercial interiors. Bedding leads volume demand due to replacement cycles driven by hygiene consciousness, while upholstery commands margin concentration through premium leather-alternative and high-performance synthetic fabrics. Online retailers represent the fastest-growing distribution vector as German consumers prioritize convenience and extended assortment breadth over physical inspection.
KBA and the EU Green Deal framework shape product compliance through mandatory textile waste collection targets and extended producer responsibility schemes taking effect across Germany. REACH and Oeko-Tex Standard 100 constrain chemical inputs in dyeing and finishing processes, elevating compliance costs for imported polyester and microfiber goods. Stakeholders must monitor how the EU AI Act and digital product passport requirements will force supply chain data disclosure across cotton, linen, and wool sourcing networks.
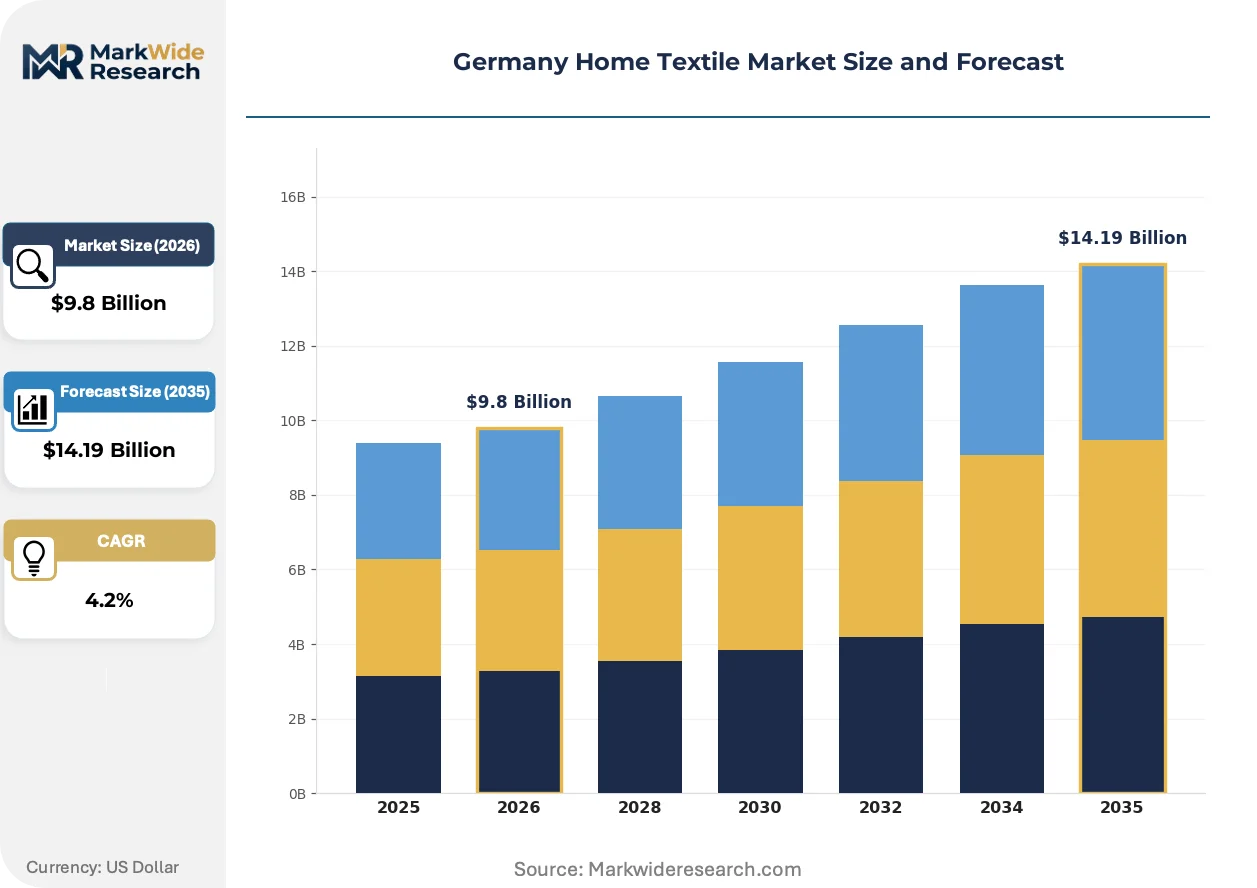
Market Dynamics
The EU Green Deal and Germany's national circular economy directives are forcing fiber traceability and extended producer responsibility schemes onto domestic manufacturers and importers, restructuring supply chain economics and compliance burdens across bedding and upholstery categories.
Growth Catalysts
- REACH chemical compliance:Stricter dyeing and finishing standards under ECHA frameworks are accelerating Oeko-Tex Standard 100 adoption among German bedding producers seeking retail shelf access.
- Metropolitan demand concentration:Bavaria and North Rhine-Westphalia residential consumers are expanding replacement frequency of linen sets driven by hygiene consciousness and disposable income density.
- Digital product passports:The EU AI Act's supply chain disclosure mandates are pulling cotton, linen, and wool sourcing networks toward blockchain-traceable certification systems.
Market Restraints
- Imported polyester cost volatility:Microfiber bedding inputs face elevated compliance costs from REACH and Oeko-Tex Standard 100 testing, compressing margins on economy-tier imports.
- Supply concentration in Asian spinning:German weavers remain dependent on concentrated overseas cotton yarn suppliers, exposing finished goods to logistics disruption and currency fluctuation.
- Technical limitation in mechanical recycling:Blended fiber upholstery fabrics lack scalable chemical separation processes, constraining circular economy targets under KBA textile waste collection mandates.
Strategic Opportunities
- Baden-Württemberg underpenetration:Stuttgart and Karlsruhe metropolitan zones show lower bedding replacement rates than Bavaria, offering white space for premium sustainable linen positioning.
- EU Green Deal regulatory tailwind:Mandatory textile waste collection targets create service revenue streams for German retailers offering take-back and refurbishment programs.
- Smart textile convergence:Integration of phase-change materials with traditional woven bedding is opening temperature-regulating product lines for sleep hygiene applications.
Industry Challenges
- Digital product passport integration:Legacy ERP systems at mid-size German textile mills require capital-intensive retrofitting to capture farm-to-finished-goods traceability data for EU AI Act compliance.
- Certification timeline compression:Oeko-Tex Standard 100 renewal cycles and REACH chemical inventory updates are stretching technical staffing capacity at smaller weaving operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Home Textile Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding, Curtains, Upholstery, Towels, Table Linen, Carpet Material: Cotton, Polyester, Linen, Silk, Microfiber, Wool Application: Residential, Hospitality, Corporate Offices, Luxury Villas, Holiday Homes Distribution Channel: Specialty Stores, Online Retailers, Department Stores, Wholesale Traders, Direct Sales |
| Companies Covered | Westwing Group SE, Home24 SE, IKEA Deutschland, Lidl (Stiftung), XXXLutz Deutschland, Otto Group, Jysk Germany, H&M Home Germany, ALDI (Süd & Nord), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Home Textile Market Shifts & Advancements
Digital retail infrastructure and regulatory data requirements are simultaneously compressing traditional wholesale pathways and forcing supply chain transparency investments across German home textile manufacturing.
Blockchain-enabled fiber provenance systems are rendering obsolete paper-based chain-of-custody documentation that dominated cotton and linen sourcing. German premium bedding brands and their retail partners are adopting these platforms at accelerating pace to preempt EU AI Act enforcement. This shift is rendering obsolete the opaque subcontracting networks that previously shielded cost structures from consumer scrutiny.
KBA textile waste collection mandates under the EU Green Deal framework are forcing upholstery manufacturers to redesign products for disassembly and material recovery. Industrial consequence includes mandatory take-back logistics investments and reformulation of synthetic leather-alternative fabrics to exclude non-recyclable bonding agents. The upholstery segment faces the steepest compliance curve, with Stuttgart-area furniture-textile bundlers restructuring supplier contracts to share end-of-life liability.
Direct-to-consumer digital storefronts are displacing department store bedding departments as the primary discovery channel for German residential buyers. Convenience prioritization and extended assortment breadth are compressing physical inspection behavior, particularly among urban millennials in Hamburg and Munich. This channel rotation is most visible in metropolitan regions where same-day delivery density from centralized logistics hubs enables impulse replacement of hygiene-critical bedding items.
Germany Home Textile Market Segmentation
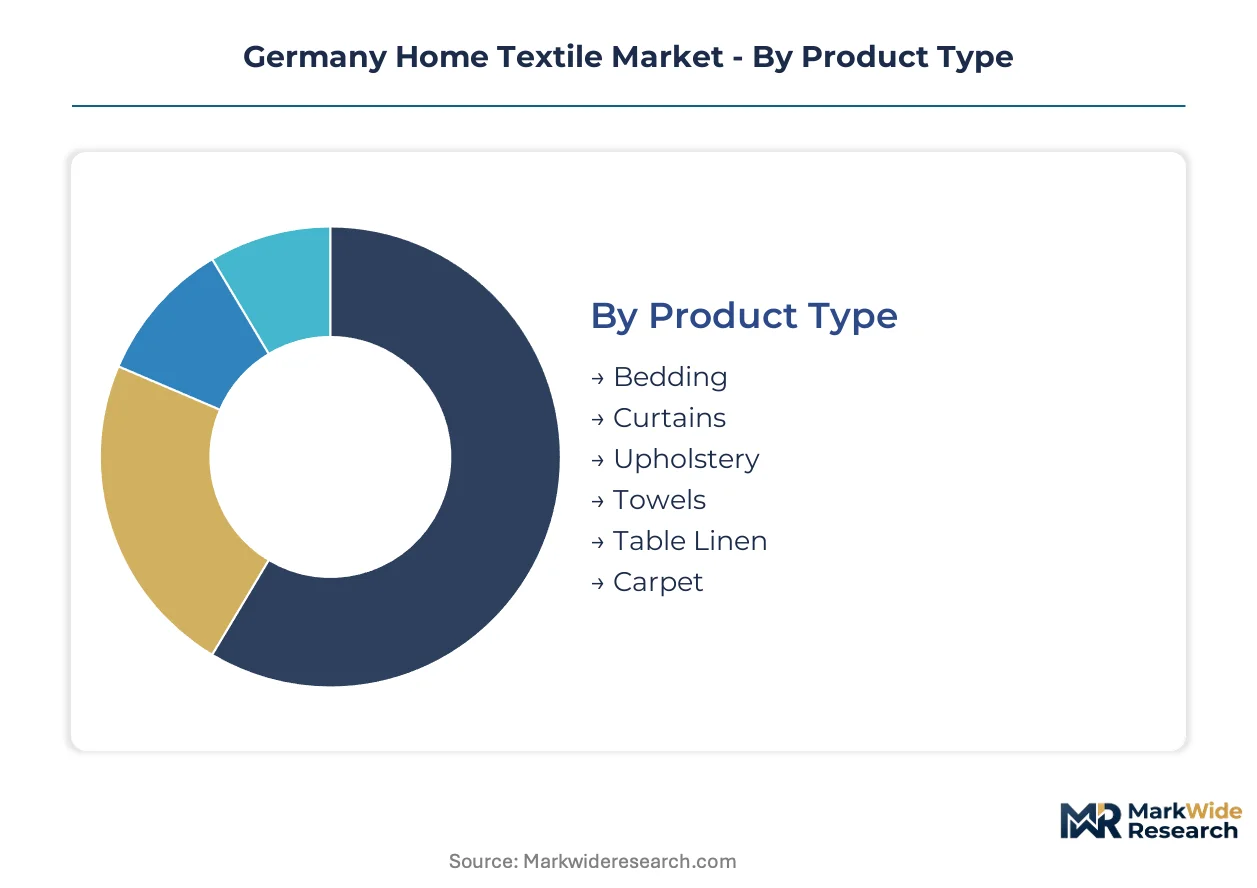
German home textile purchasing patterns fragment across product lifecycles, fiber provenance requirements, and channel convenience preferences. KBA textile waste mandates and EU Green Deal traceability rules are compressing supplier economics differently across each segment boundary.
Product Type:
Volume concentration across product categories tracks replacement frequency, hygiene sensitivity, and bundling economics with adjacent furniture purchases.
- Bedding:Thread-count-specified woven and knitted sheets, duvet covers, and pillowcases dominate unit volume through 2-3 year replacement cycles driven by hygiene consciousness. Bavaria and North Rhine-Westphalia residential consumers are expanding linen set purchases fastest, pulled by disposable income density and Oeko-Tex Standard 100 certification awareness.
- Upholstery:High-performance synthetic fabrics and leather-alternatives for furniture covering command margin concentration through premium positioning. Stuttgart-area furniture-textile bundlers are restructuring supplier contracts to share end-of-life liability under KBA collection mandates.
- Curtains:Acoustic dampening and thermal insulation fabrics specified by weight and light-blocking coefficient.
- Towels:GSM-rated cotton and microfiber absorbent products for bathroom environments.
- Table Linen:Formal and casual dining textiles with stain-resistant finishing treatments.
- Carpet:Wall-to-wall and area rug textiles facing mechanical recycling limitations under circular economy targets.
Bedding holds installed capacity. Upholstery is rotating up the share rankings.
Material:
Fiber composition determines compliance burden intensity under REACH chemical frameworks and digital passport traceability requirements.
- Cotton:Natural cellulosic fiber specified by staple length and origin certification, dominant in premium bedding lines. German weavers remain dependent on concentrated overseas yarn suppliers, exposing finished goods to logistics disruption and currency fluctuation.
- Polyester:Petroleum-derived synthetic fiber offering cost efficiency and durability in economy-tier bedding. Microfiber bedding inputs face elevated compliance costs from REACH and Oeko-Tex Standard 100 testing, compressing margins on imports.
- Linen:Bast fiber from flax cultivation with high moisture-wicking properties for temperature regulation.
- Silk:Protein fiber for luxury positioning with limited volume penetration.
- Microfiber:Fine-denier polyester variants specified for softness and quick-dry performance.
- Wool:Animal fiber for thermal insulation applications with traceability requirements under EU AI Act disclosure mandates.
Cotton maintains supply chain anchoring. Linen is climbing the fastest through sustainability positioning.
Application:
End-use environments dictate performance specifications, replacement authority, and procurement channel preferences.
- Residential:Individual household purchases across owner-occupied and rental units, characterized by discretionary replacement timing. Metropolitan regions such as Hamburg and Munich are compressing physical inspection behavior through same-day delivery density from centralized logistics hubs.
- Hospitality:Hotel and accommodation sector procurement with standardized bulk purchasing and brand compliance requirements.
- Corporate Offices:Workplace textile specifications for acoustic and aesthetic coordination in commercial interiors.
- Luxury Villas:High-end residential segment with bespoke customization and premium fiber requirements.
- Holiday Homes:Seasonal rental properties with durability-focused purchasing and accelerated replacement cycles.
Residential commands volume concentration. Hospitality is gaining share fastest through standardization and bulk procurement scale.
Distribution Channel:
Channel economics are restructuring around logistics density, assortment breadth, and regulatory data capture capabilities.
- Online Retailers:Digital storefronts with curated assortment and direct-to-consumer logistics. Convenience prioritization and extended assortment breadth are compressing traditional wholesale and department store pathways, particularly among urban millennials.
- Specialty Stores:Focused bedding and linen retailers with tactile inspection and consultation services.
- Department Stores:Traditional multi-category retail with declining bedding department relevance.
- Wholesale Traders:B2B intermediaries serving hospitality and corporate procurement with volume pricing.
- Direct Sales:Manufacturer-owned channels with captive supply chain control and digital passport integration.
Online retailers are expanding most quickly through logistics density investments. Specialty stores defend position through tactile service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria commands premium pricing power through disposable income density, while Baden-Württemberg trails on bedding replacement frequency. This asymmetry shapes manufacturer channel investments across German sub-regions.
Bavaria
Munich and Nuremberg residential consumers drive linen set purchases through hygiene consciousness and Oeko-Tex Standard 100 certification awareness. KBA textile waste collection mandates under the EU Green Deal force Munich-area retailers to deploy take-back logistics. Ingolstadt furniture-textile bundlers are restructuring supplier contracts to share end-of-life liability.
North Rhine-Westphalia
Düsseldorf and Cologne metropolitan zones concentrate demand for sustainable bedding through dense urban millennial populations. REACH chemical compliance under ECHA frameworks elevates testing costs for Duisburg-area importers of polyester microfiber goods. Dortmund logistics hubs enable same-day delivery density that compresses traditional department store pathways.
Baden-Württemberg
Stuttgart and Karlsruhe show underpenetration in premium sustainable linen relative to Bavarian benchmarks. EU AI Act digital product passport requirements pull Stuttgart-area weaving operations toward blockchain-traceable cotton sourcing. Heilbronn textile mills face capital-intensive ERP retrofitting to capture farm-to-finished-goods traceability data.
Hesse
Frankfurt's corporate office sector sustains acoustic dampening curtain procurement for commercial interior specifications. Extended producer responsibility schemes under Germany's circular economy directives reshape upholstery supplier economics in Offenbach manufacturing clusters. Wiesbaden hospitality buyers standardize bulk linen purchasing through Oeko-Tex compliance requirements.
Hamburg
Urban millennial populations in Hamburg prioritize convenience-driven online retail for hygiene-critical bedding replacement. ECHA dyeing and finishing standards constrain chemical inputs for port-dependent importers of Asian-spun cotton yarn. Lübeck-area logistics providers invest in centralized hub capacity to enable impulse purchase fulfillment.
Germany Home Textile Market Competitive Landscape
Digital-native retailers and legacy furniture-textile bundlers split the market along convenience-versus-tactile inspection lines. Consolidation pressure concentrates among mid-market players lacking captive supply chains. Three archetypes dominate: curated direct-to-consumer platforms, vertically integrated Scandinavian-origin mass retailers, and discount grocery channels with private-label textile lines. Competitive moves center on logistics density investments and circular economy service layering.
Within the digital-native tier, Westwing Group SE and Home24 SE occupy positions as convenience-anchored challengers to physical retail. IKEA Deutschland exemplifies vertically integrated mass-market positioning through in-house cotton bedding production. Among grocery-channel private-label specialists, Lidl (Stiftung) and ALDI (Süd & Nord) represent economy-tier volume concentration. These three groupings illustrate how regulatory compliance costs under REACH and EU Green Deal mandates favor scale-driven players with captive certification resources.
| Leading Market Players |
|---|
| Westwing Group SE |
| Home24 SE |
| IKEA Deutschland |
| Lidl (Stiftung) |
| XXXLutz Deutschland |
| Otto Group |
| Jysk Germany |
| H&M Home Germany |
| ALDI (Süd & Nord) |
| Others |
Supply & Pricing Matrix
Dortmund logistics hub density compresses delivery timelines for online bedding retailers, concentrating pricing power among digital-native platforms with captive warehouse networks. Bavarian premium linen producers extract margin through Oeko-Tex Standard 100 certification tiering, while polyester microfiber imports from Asian spinning clusters face REACH compliance cost absorption.
Pricing Analysis
The customization-premium spread separates configured-to-order bedding from standard SKUs by 40-60% at retail. Three-tier pricing structure across premium certified linen, mid-market cotton blends, and economy polyester microfiber dominates transactional flow. Cost compression in economy imports intensifies because ECHA dyeing standards elevate testing burdens. Hospitality procurement teams show lowest price sensitivity due to brand compliance requirements, while individual residential buyers in Baden-Württemberg exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between Vietnam and Germany disrupts cotton yarn cost structures for Heilbronn weaving operations. German mills draw from concentrated Pakistan, India, and Uzbekistan cotton suppliers, exposing finished goods to currency fluctuation. Single-source vulnerability in Asian spinning clusters threatens just-in-time replenishment for Munich-area retailers. Distribution runs through centralized Ruhr Valley logistics hubs enabling same-day fulfillment density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
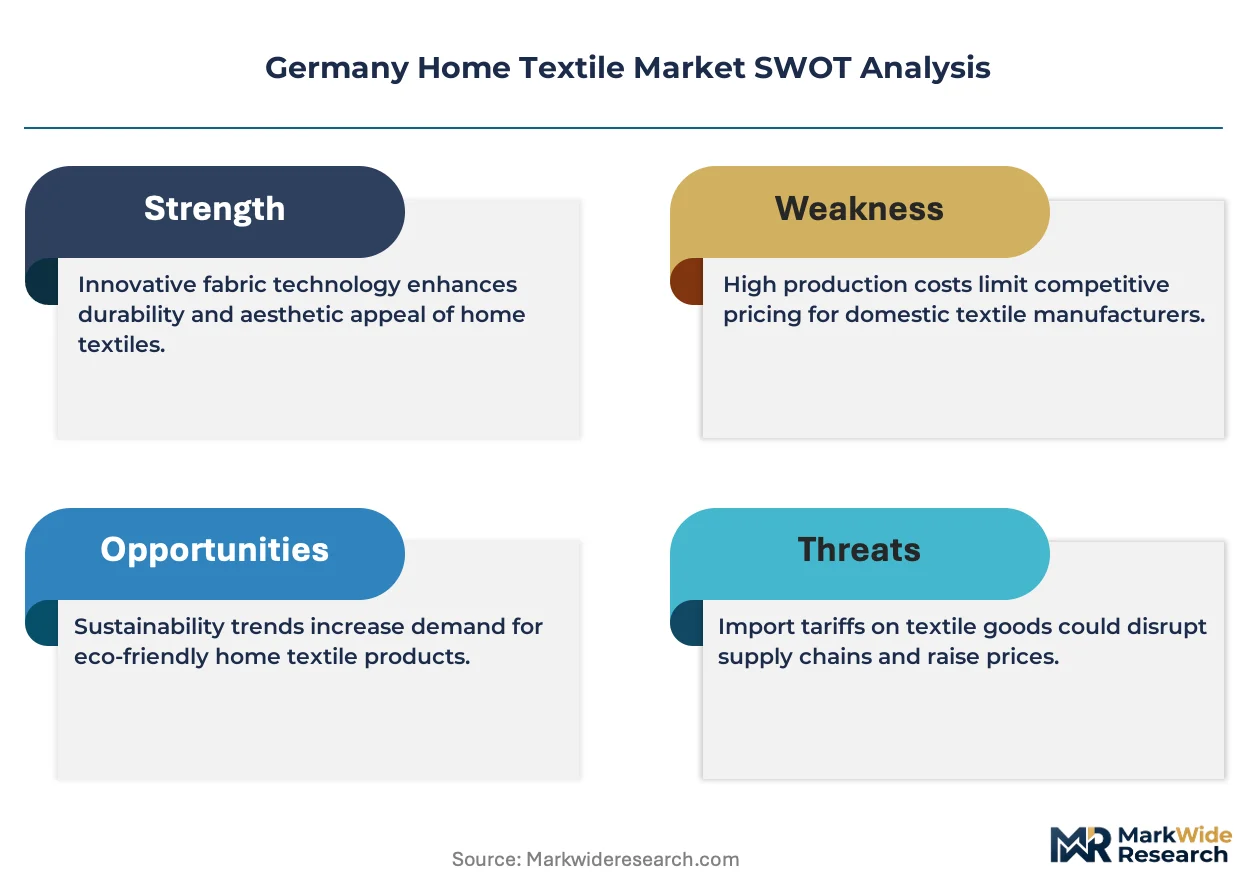
The Germany home textile market sits as a high-growth disruption because EU AI Act digital passport mandates force blockchain-traceable fiber provenance investments across legacy ERP systems.
For Market Incumbents: Harden supply chain control through backward integration into Oeko-Tex certified cotton sourcing networks. Lock in Baden-Württemberg weaving capacity before EU Green Deal waste collection mandates reshape end-of-life liability economics. Digitize product passport data capture to preempt mid-market competitors lacking captive certification resources. For New Entrants and Emerging Players: Stuttgart and Karlsruhe metropolitan zones represent the most penetrable entry point given underpenetration in premium sustainable linen relative to Bavarian benchmarks. Smart textile convergence with phase-change temperature regulation opens white space in sleep hygiene applications. Launch through curated direct-to-consumer storefronts with same-day delivery partnerships to bypass established wholesale channels. For Investors and Strategic Acquirers: Long-term, this sits as a circular economy infrastructure play because mandatory textile waste collection creates recurring service revenue streams. Target mid-size German mills with retrofit-ready ERP systems and existing Oeko-Tex certification pipelines. Watch for KBA enforcement timeline acceleration as the inflection signal triggering consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Traceable Sourcing Integration | EU AI Act compliance forces farm-to-finished-goods data capture across cotton and linen networks. |
| Take-Back Logistics Infrastructure | KBA textile waste mandates create service revenue layers for retailers with reverse supply chain density. |
| Smart Textile R&D Partnership | Phase-change material integration opens temperature-regulating product lines for sleep hygiene applications. |
| Regional Logistics Hub Expansion | Dortmund and Lübeck centralized capacity enables impulse bedding replacement through same-day delivery. |
| Certification Pipeline Investment | Oeko-Tex Standard 100 renewal automation reduces technical staffing strain at smaller weaving operations. |
Research Methodology
A standing panel of textile mill operations directors, online retail category managers, hospitality procurement leads, and ECHA compliance officers provided ongoing calibration across primary fieldwork. Secondary validation drew from Bundesamt für Wirtschaft und Ausfuhrkontrolle trade data, Destatis consumer expenditure surveys, EU Circular Economy Action Plan implementation tracking, and Oeko-Tex association certification databases. Bottom-up unit economics from 50+ product SKUs triangulated against top-down regional consumption models.
Scenario-bracketing around regulatory enforcement timelines and logistics density investments shaped volume and value outputs across the projection horizon. Segmentation dimensions modeled include product lifecycle category, fiber composition tier, distribution channel format, and metropolitan demand cluster. CAGRs derived from replacement frequency elasticity and disposable income correlation coefficients. Industry-specific inputs encompassed REACH chemical inventory update cycles and digital passport implementation readiness scores.
Macroeconomic conditions sit as an overlay; deviation in euro-zone inflation trajectories and Asian cotton futures volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement pacing and consumer convenience preference stickiness. Material shifts in EU AI Act digital passport technical specifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Plush Blanket Market
Home Textiles
Blanket Market
Home Textiles
Global Theater Linen Market
Home Textiles
Japan Home Textile Market
Home Textiles
India Home Textile Market
Home Textiles
North America Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
Europe Home Textile Market
Home Textiles
China Home Textiles Market
Home Textiles
Home Textile Products Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
GCC Home Textile Market
Home Textiles
Russia Home Textile Market
Home Textiles
Vietnam Home Textile Market