
 Home Textile Products Market | 2026-2036
Home Textile Products Market Size, Share, and Industry Trends Forecast 2026-2036
Home Textile Products Market Outlook
Multi-source procurement toward captive cotton ginning and spinning operations is repositioning how large-format bedding suppliers manage cost volatility. Welspun India Limited leverages backward integration into Egyptian and American long-staple cotton to secure yarn consistency for premium hotel contracts. Trident Limited anchors its competitiveness through in-house terry towel manufacturing at scale, while WestPoint Home LLC differentiates via specialized distribution control across North American retail channels.
Home textile products encompass woven, knitted, and non-woven fabric goods designed for interior residential and commercial environments, typically specified by thread count, GSM weight, or fiber composition for performance attributes such as moisture wicking, flame resistance, or colorfastness. Bedding commands the largest value pool within product type segmentation, driven by replacement cycles in hospitality and premium residential channels. Cotton retains structural dominance across material categories, though linen is gaining share in climate-adaptive and luxury positioning. The online market channel is expanding fastest among distribution pathways, compressing traditional wholesale margins while enabling direct-to-consumer customization.
EPA wastewater discharge standards and OEKO-TEX certification requirements constrain dyehouse operations in the United States, while REACH chemical restrictions in Europe limit certain formaldehyde-based finishing agents used in wrinkle-resistant bedding. India's BIS quality mandates and the Bureau of Energy Efficiency's textile sector protocols are tightening compliance costs for export-oriented mills around Ahmedabad and Karur. Stakeholders must monitor how diverging regional chemical standards reshape supplier qualification criteria and capital allocation across finishing lines.
Market Dynamics
Post-pandemic hospitality linen refresh cycles and the EU Green Deal's closed-loop water mandates are restructuring capital deployment across dyeing and finishing operations, forcing mills to choose between compliance investment and contract loss.
Growth Catalysts
- EU Green Deal textile sustainability requirements:Closed-loop water system mandates in dyeing operations are accelerating equipment replacement cycles among European finishers seeking export qualification.
- Hospitality linen refresh normalization:Hotel operators are compressing replacement intervals for bedding and towels as occupancy rates stabilize, pulling volume through contract manufacturers.
- Integrated spinning-weaving concentration in India:Gujarat and Tamil Nadu units are capturing cost-advantaged cotton bedding demand through captive ginning-to-fabric production.
Market Restraints
- Long-staple cotton price volatility:Egyptian and American Pima cotton input costs swing with climate-induced yield uncertainty, compressing margin predictability for premium hotel contract bidders.
- Dyehouse supply concentration in Ahmedabad and Karur:Export-oriented finishing capacity clusters in these Indian hubs create bottleneck risk during BIS quality mandate compliance surges.
- REACH chemical restrictions on formaldehyde-based finishing:European wrinkle-resistant bedding producers face reformulation costs or market exclusion as ECHA tightens approved substance lists.
Strategic Opportunities
- Direct-to-consumer online channel expansion:North American bedding brands are bypassing wholesale markups through owned e-commerce platforms enabling thread-count customization.
- Bureau of Energy Efficiency textile sector protocols:Indian mills achieving BEE compliance ratings unlock preferential financing for thermal efficiency upgrades in spinning operations.
- Linen fiber climate-adaptive positioning:Moisture-wicking and thermoregulation properties are opening hospitality specification opportunities in Mediterranean and Middle Eastern hotel markets.
Industry Challenges
- OEKO-TEX certification timeline compression:Lead times for Standard 100 and MADE IN GREEN approvals are extending as testing laboratory capacity strains under backlog.
- EPA wastewater discharge standard retrofit costs:US-based dyehouses face capital intensity for biological treatment upgrades to meet NPDES permit limits.
- Legacy ERP integration with traceability platforms:Cotton origin tracking requirements from gin to finished goods are forcing middleware investments at mid-scale weaving operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Textile Products Market |
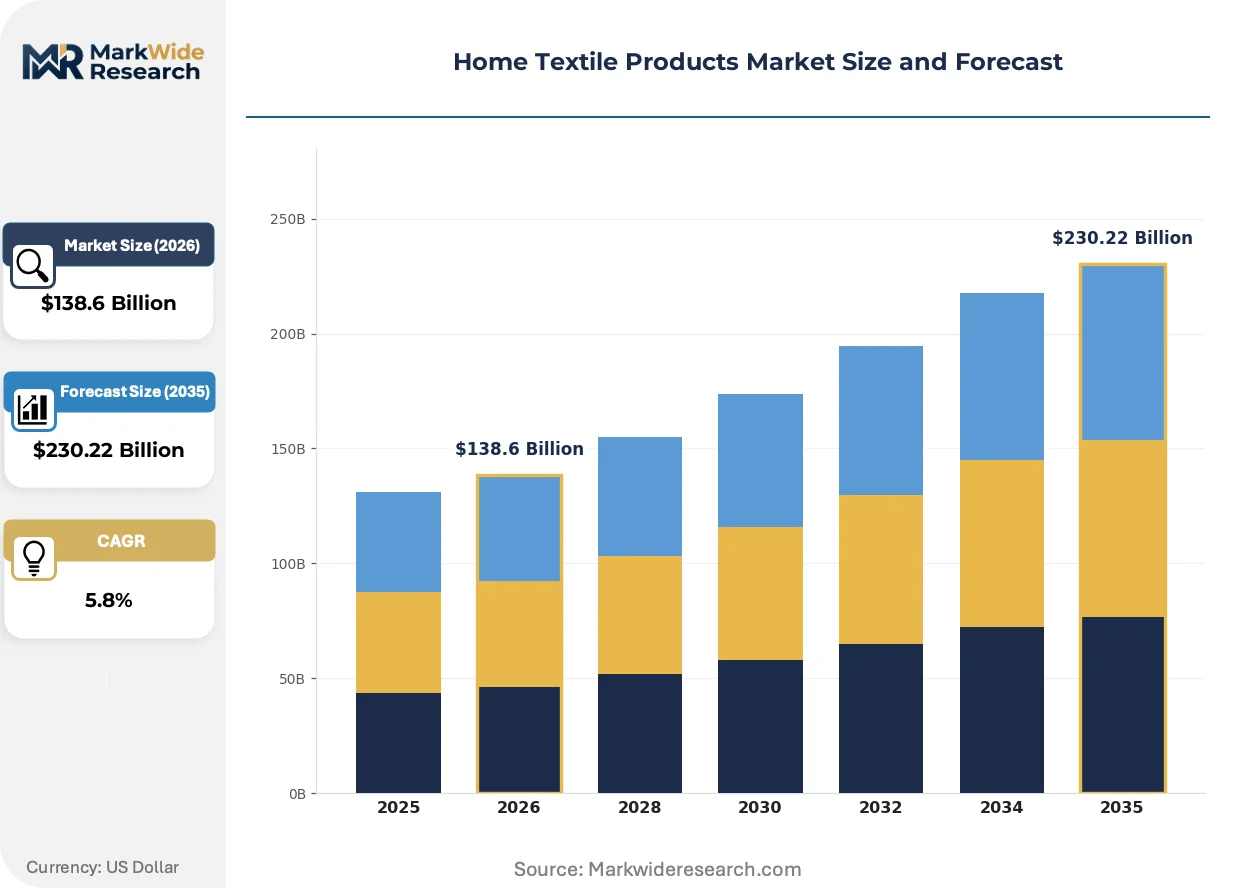
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $230.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding, Curtains, Towels, Throws Material: Cotton, Polyester, Linen, Silk End User: Residential, Commercial, Institutional, Hospitality Market Channel: Online, Offline, Wholesale, Retail |
| Companies Covered | Welspun India Limited, Trident Limited, WestPoint Home LLC, Springs Global US Inc., Standard Textile Co., Inc., GHCL Limited, Arvind Limited, Bombay Dyeing & Manufacturing Company Limited, Gul Ahmed Textile Mills Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Textile Products Market Strategic Shifts
Digital finishing controls and fiber-level traceability systems are compressing quality variance while regulatory chemical restrictions force formulation pivots across dyehouse operations.
Digital dyeing recipe management systems are automating color consistency across batch runs by integrating spectrophotometer feedback with automated chemical dosing. Hospitality contract manufacturers in Portugal and Turkey are deploying these systems to reduce re-dye rates and meet tight delivery windows. This automation is compressing the penalty cost structure for off-shade production while enabling just-in-time finishing for seasonal collection launches.
REACH restrictions on formaldehyde-releasing agents are forcing wrinkle-resistant bedding producers toward citric acid cross-linking and polycarboxylic acid alternatives. The industrial consequence is reformulation R&D spend concentration among European finishers and their Turkish outsourcing partners. North American hospitality suppliers serving EU-flagged hotel chains are most affected, responding by dual-sourcing finished goods from OEKO-TEX certified facilities in India and Pakistan.
Buyer concentration among large-format hospitality procurement consortia is consolidating specification power into fewer sourcing managers managing multi-property portfolios. Traditional wholesale distributors serving independent hotels are losing share to direct mill relationships and private-label programs. This consolidation is most visible in the Gulf Cooperation Council hospitality construction pipeline, where sovereign wealth-backed hotel operators are standardizing linen specifications across 500-plus room properties.
Home Textile Products Market Segmentation
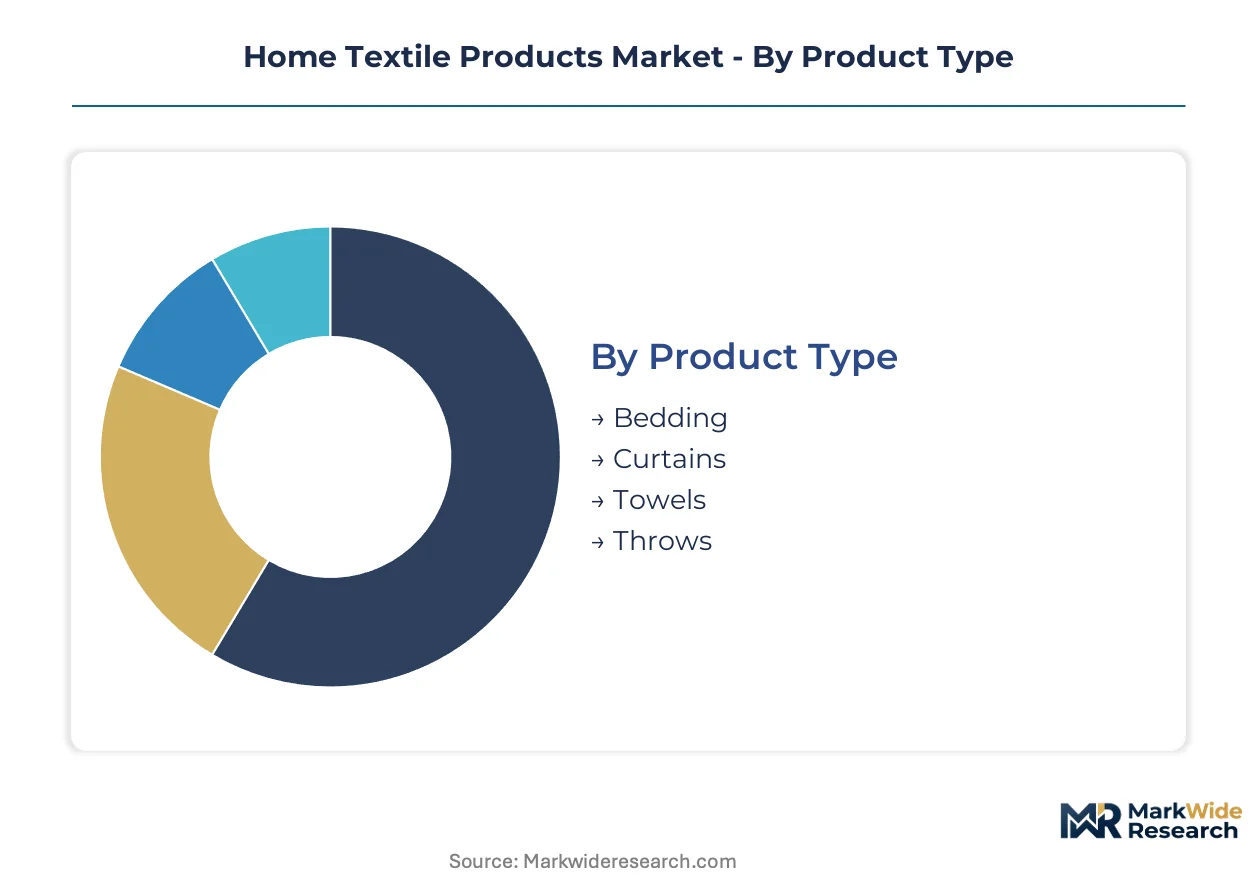
Home textile procurement splits sharply between specification-driven hospitality contracts and discretionary residential purchases. Thread count, GSM weight, and fiber provenance determine price positioning across each segment boundary. Suppliers configure production lines differently for bulk contract manufacturing versus SKU-dense retail distribution.
Product Type:
Customization intensity varies from engineered hospitality specifications to mass-market standardized SKUs across this category.
- Bedding:Sheet sets and duvet covers dominate contract value in hospitality procurement. Hotel operators in the GCC and Mediterranean markets specify Egyptian or American long-staple cotton at 300-plus thread counts for durability through commercial laundering cycles.
- Towels:Terry cloth manufacturing at scale anchors competitiveness through in-house loop formation and dyeing. Trident Limited and similar integrated producers in Tamil Nadu capture hospitality volume via captive ginning-to-finished-goods operations.
- Curtains:Flame-resistant drapery specifications drive contract wins in commercial and institutional channels. OEKO-TEX certification requirements constrain supplier pools for EU-facing projects.
- Throws:Decorative accent pieces with lower technical barriers attract private-label programs. Seasonal collection velocity favors agile cut-and-sew operations over integrated mills.
Most installed capacity flows through Bedding. Expansion is steepest in Towels.
Material:
Cost tier stratification from commodity synthetics to premium natural fibers shapes margin architecture across this category.
- Cotton:Structural dominance persists across all price tiers, with long-staple varieties commanding premium positioning in hotel contracts. Climate-induced yield volatility in Egyptian and American growing regions compresses margin predictability for spinners.
- Linen:Moisture-wicking and thermoregulation properties open climate-adaptive positioning in Mediterranean and Middle Eastern hospitality markets. Flax cultivation concentration in Belgium and France limits supply elasticity.
- Polyester:Recycled PET feedstocks gain share in sustainability-positioned retail channels. Price stability versus natural fibers attracts value-tier hospitality procurement.
- Silk:Luxury residential applications sustain niche demand through specialty weaving houses. Mulberry cultivation constraints in China and India limit volume scalability.
Volume concentrates in Cotton. Share gains are fastest in Linen.
End User:
Application maturity separates replacement-cycle predictability from construction-dependent demand volatility across this category.
- Hospitality:Post-pandemic refresh normalization compresses replacement intervals for bedding and towels. Procurement consortia managing multi-property portfolios consolidate specification power into fewer sourcing managers.
- Residential:Direct-to-consumer online channels enable thread-count customization and bypass wholesale markups. Premium positioning depends on origin storytelling and certification badges.
- Commercial:Office and retail fit-out demand correlates with construction pipelines. Flame resistance and durability specifications dominate technical requirements.
- Institutional:Healthcare and education procurement runs on extended tender cycles with total-cost-of-ownership evaluation. Antimicrobial finishing requirements constrain qualified supplier pools.
Contract value concentrates in Hospitality. Digital channel penetration is climbing fastest in Residential.
Market Channel:
Customer type separation between bulk procurement professionals and individual consumers determines service intensity across this category.
- Online:Owned e-commerce platforms enable North American bedding brands to capture margin otherwise lost to wholesale intermediaries. Customization tools for thread count and dimensions extend average order values.
- Wholesale:Traditional distributors serving independent hotels lose share to direct mill relationships. Inventory carrying costs and credit terms pressure working capital efficiency.
- Retail:Big-box and specialty store placement requires SKU density and seasonal collection velocity. Co-marketing investments strain smaller weaving operations.
- Offline:Direct sales forces serve hospitality procurement consortia with specification engineering and sample development. Relationship tenure determines contract renewal rates.
Transaction volume flows predominantly through Wholesale. Digital investment intensity is highest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat and Tamil Nadu command integrated spinning-weaving concentration that reshapes cotton bedding cost structures across export markets. Regulatory divergence between EPA discharge standards, REACH chemical restrictions, and India's BIS quality mandates fragments compliance investment across finishing operations.
United States
Hospitality procurement consortia compress replacement cycles for premium hotel bedding as occupancy normalizes. EPA NPDES wastewater discharge permits force biological treatment retrofits at dyehouse operations in North Carolina and Georgia. Carolinas-based terry towel manufacturing clusters face capital intensity for effluent compliance.
Germany
EU Green Deal textile sustainability requirements accelerate closed-loop water system deployment among finishing operations. ECHA REACH restrictions on formaldehyde-based finishing agents force citric acid cross-linking reformulation for wrinkle-resistant bedding. North Rhine-Westphalia dyehouses invest in automated recipe management to maintain export qualification.
India
Integrated ginning-to-fabric units in Gujarat and Tamil Nadu capture cost-advantaged cotton bedding demand from hospitality buyers. BIS quality mandates and Bureau of Energy Efficiency textile sector protocols tighten compliance costs for export-oriented mills around Ahmedabad and Karur. Tamil Nadu terry towel manufacturing anchors competitiveness through captive spinning operations.
Turkey
Proximity to EU hospitality markets positions Turkish finishers as outsourcing partners for REACH-compliant production. ECHA chemical restrictions drive reformulation R&D concentration among European-facing bedding suppliers. Bursa and Denizli textile clusters deploy digital dyeing controls to reduce re-dye rates for just-in-time delivery.
United Arab Emirates
Sovereign wealth-backed hotel operators standardize linen specifications across 500-plus room properties in Gulf Cooperation Council construction pipelines. MOHAP and local hospitality procurement frameworks emphasize durability through commercial laundering cycles. Dubai-based procurement consortia consolidate specification power into fewer sourcing managers.
Home Textile Products Market Competitive Environment
Global majors compete with regional champions across integrated production depth and distribution control dimensions. The vendor base separates into scale-driven integrated producers, specialized hospitality contractors, and retail-channel distributors. Three archetypes dominate: backward-integrated cotton spinners commanding yarn consistency, in-house terry towel manufacturers leveraging captive ginning, and North American brands capturing margin through owned e-commerce. Competitive moves concentrate on M&A for geographic expansion and portfolio diversification into climate-adaptive fibers.
Among India-based integrated producers, Welspun India Limited and Trident Limited exemplify the backward-integration archetype, while WestPoint Home LLC occupies a position within North American distribution-focused competitors. These three entities represent contrasting strategic postures: captive long-staple cotton sourcing, in-house terry manufacturing at scale, and specialized channel control across retail networks.
| Leading Market Players |
|---|
| Welspun India Limited |
| Trident Limited |
| WestPoint Home LLC |
| Springs Global US Inc. |
| Standard Textile Co., Inc. |
| GHCL Limited |
| Arvind Limited |
| Bombay Dyeing & Manufacturing Company Limited |
| Gul Ahmed Textile Mills Limited |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap weaving operations in Tamil Nadu and Gujarat anchor supply discipline through captive ginning assets, translating raw cotton volatility into contract pricing power against hospitality procurement consortia. Sovereign wealth-backed hotel operators in the Gulf Cooperation Council leverage multi-property volume commitments to compress supplier margins across Egyptian and American long-staple cotton tiers.
Pricing Analysis
Long-staple cotton input costs pass through to hospitality contract bids with lagged adjustments, compressing margin predictability for premium hotel linen suppliers. Three-tier pricing structure across premium, standard, and economy levels separates OEKO-TEX certified European finishers from BIS-compliant Indian exporters and uncertified regional suppliers. Pricing pressure stems from REACH chemical restrictions forcing reformulation R&D spend among wrinkle-resistant bedding producers. Hospitality procurement consortia exhibit lowest price sensitivity due to durability-through-laundering specifications, while independent hotels and residential direct-to-consumer channels face acute cost compression.
Supply Chain Analysis
Workforce availability constraints in Ahmedabad and Karur dyehouse clusters limit capacity expansion despite BIS quality mandate compliance surges. Supply concentrates in India, Turkey, and Portugal, with integrated spinning-weaving units in Gujarat and Tamil Nadu commanding cost advantages in cotton bedding. Raw material dependencies center on Egyptian and American Pima cotton, Belgian and French flax for linen, and recycled PET feedstocks for sustainability-positioned polyester. Single-source vulnerability runs through Egyptian long-staple cotton exposure to climate-induced yield uncertainty. Distribution runs through hospitality procurement consortia consolidating specification power, alongside direct mill relationships displacing traditional wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Home Textile Products Market functions as a stable compounder anchored by replacement-cycle predictability in hospitality linen refresh programs. Post-pandemic occupancy normalization sustains volume throughput without speculative demand spikes.
For Market Incumbents: Extend backward integration into captive cotton ginning to secure yarn consistency against climate-induced input volatility. Consolidate finishing capacity around BIS and OEKO-TEX certified facilities to defend contract renewals from REACH-compliant Turkish outsourcing partners. Prioritize thermal efficiency upgrades qualifying for Bureau of Energy Efficiency preferential financing.
For New Entrants and Emerging Players: Enter via climate-adaptive linen positioning in Mediterranean and Middle Eastern hospitality markets where moisture-wicking specifications remain underpenetrated. Target direct-to-consumer online channels with thread-count customization tools bypassing wholesale markups. Pursue private-label programs for seasonal throws and decorative accents requiring agile cut-and-sew rather than integrated mill investment.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale weaving operations lacking traceability platform integration yet holding BIS export qualification. Long-term viability frames around 5-10 year windows of hospitality construction pipeline concentration in Gulf Cooperation Council markets. Watch OEKO-TEX certification timeline compression as inflection indicator for laboratory capacity constraints forcing supplier qualification bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cotton Ginning | Welspun India Limited secures yarn consistency for premium hotel contracts through Egyptian and American long-staple captive sourcing. |
| Closed-Loop Water System Deployment | EU Green Deal mandates force North Rhine-Westphalia dyehouses into equipment replacement cycles to maintain export qualification. |
| Direct-to-Consumer Platform Launch | North American bedding brands capture margin otherwise lost to wholesale intermediaries through owned e-commerce customization tools. |
| Digital Dyeing Recipe Management | Portuguese and Turkish hospitality contractors reduce re-dye rates through spectrophotometer-integrated automated chemical dosing. |
| Linen Fiber Climate-Adaptive Positioning | Belgian and French flax cultivation constraints create scarcity premium for moisture-wicking specifications in Mediterranean hotel markets. |
Study Parameters
Direct dialogue with hospitality procurement managers, textile mill operations directors, dyehouse compliance officers, and retail channel buyers grounded qualitative findings in operational reality. Secondary validation drew from Bureau of Energy Efficiency textile sector protocols, BIS quality mandate documentation, EPA NPDES discharge permit filings, and REACH chemical restriction updates. Customs records tracking Egyptian and American cotton import flows, OEKO-TEX certification databases, and hospitality construction pipeline disclosures supplied quantitative anchors. Bottom-up contract volume aggregation and top-down macroeconomic triangulation cross-checked segment sizing.
Bottom-up modeling tracked bedding, towel, curtain, and throw shipments by material composition and end-user channel across the projection horizon. Segmentation dimensions spanned product type, material grade tier, end-user application maturity, and distribution pathway. CAGRs derived from replacement cycle normalization in hospitality, online channel penetration trajectories, and regulatory compliance investment curves. Forecast inputs incorporated climate-induced cotton yield variance, BIS mandate enforcement intensity, and EU Green Deal implementation pacing.
The model holds under stable hospitality occupancy recovery and incremental regulatory tightening; deviation in Egyptian cotton crop failures or ECHA substance list expansion would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Blanket Market
Home Textiles
United States Home Textile Market
Home Textiles
Russia Home Textile Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Textile Floorings Market
Home Textiles
France Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Plush Blanket Market
Home Textiles
Germany Home Textile Market
Home Textiles
GCC Home Textile Market
Home Textiles
Towel Market
Home Textiles
Linen Bed Sheets Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
Home Textiles Market