
 Fabric Wash and Care Market | 2026-2036
Fabric Wash and Care Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Wash and Care Market Analysis
Plant-based surfactants derived from coconut and palm kernel oils is repositioning cost structures across mid-tier and premium tiers. Procter & Gamble leverages its captive enzyme technology to sustain margin advantages in concentrated formats. Henkel anchors European private-label supply through backward integration into alkyl polyglucoside production. Unilever competes in emerging markets with sachet economics that dominate price-sensitive channels.
Fabric wash and care encompasses detergent formulations, softening agents, and stain-treatment products designed to remove soils, preserve fiber integrity, and maintain textile appearance across cotton, synthetic, and blended materials; these products typically contain 15-40% surfactant by weight, supplemented with builders, enzymes, and optical brighteners tuned to water hardness and wash temperature. Liquid detergent occupies the largest revenue pool in developed markets due to convenience premiums and cold-water dissolution advantages, while powder detergent retains volume leadership in price-sensitive regions with high-temperature washing norms. The concentrated formulation segment captures expanding shelf space as retailers prioritize logistics efficiency, though traditional dilute products still command share in discount-store channels.
The EPA's Safer Choice program and REACH registration requirements in Europe are elevating compliance costs for conventional petrochemical surfactants while opening shelf access for verified eco-friendly alternatives. India's BIS certification mandates for detergent active-matter content are tightening quality enforcement across domestic manufacturers and importers. Stakeholders must monitor enzyme-patent expirations and regional water-stress policies that will determine which formulation architectures gain regulatory preference.
Market Dynamics
Reformulation pressure from EU Green Deal chemical-sustainability mandates is forcing surfactant suppliers to rebuild cost structures around biodegradable feedstocks, compressing margins for conventional petrochemical architectures while opening shelf access for verified alternatives.
Growth Catalysts
- Hospitality linen-care protocol upgrades:Hotel chains are procuring commercial-grade concentrated formulations to reduce water and energy consumption per wash cycle.
- India's BIS certification enforcement:Mandatory active-matter content standards are consolidating domestic manufacturing quality and accelerating liquid detergent penetration in urban households.
- Cold-water dissolution technology:Enzyme-stabilized formulations tuned to sub-30°C washing are expanding addressable volume in European and North American energy-conscious segments.
Market Restraints
- Palm kernel oil price volatility:Plant-based surfactant feedstock costs fluctuate with Malaysian and Indonesian harvest cycles, destabilizing mid-tier pricing.
- REACH registration burden:European petrochemical surfactant compliance costs are rising as ECHA tightens dossier requirements for existing substances.
- High-temperature washing persistence:Powder detergent retains volume leadership in price-sensitive regions where washing machines lack cold-water cycles.
Strategic Opportunities
- Sachet economics in Southeast Asia:Single-use packaging formats dominate Indonesian and Vietnamese traditional trade channels where cash-flow constraints limit bulk purchasing.
- EPA Safer Choice shelf access:Verified eco-friendly alternatives are securing preferential placement in US mass retail as retailers face Scope 3 emissions disclosure pressure.
- Alkyl polyglucoside backward integration:Captive production of carbohydrate-derived surfactants is enabling margin defense against oleochemical price swings.
Industry Challenges
- Enzyme patent cliff navigation:Expiring intellectual property around protease and lipase stabilization is triggering licensing complexity and formulation redesign cycles.
- Optical brightener substitution timelines:Regulatory pressure on stilbene derivatives is forcing rapid reformulation without performance degradation in cotton fiber maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Wash and Care Market |
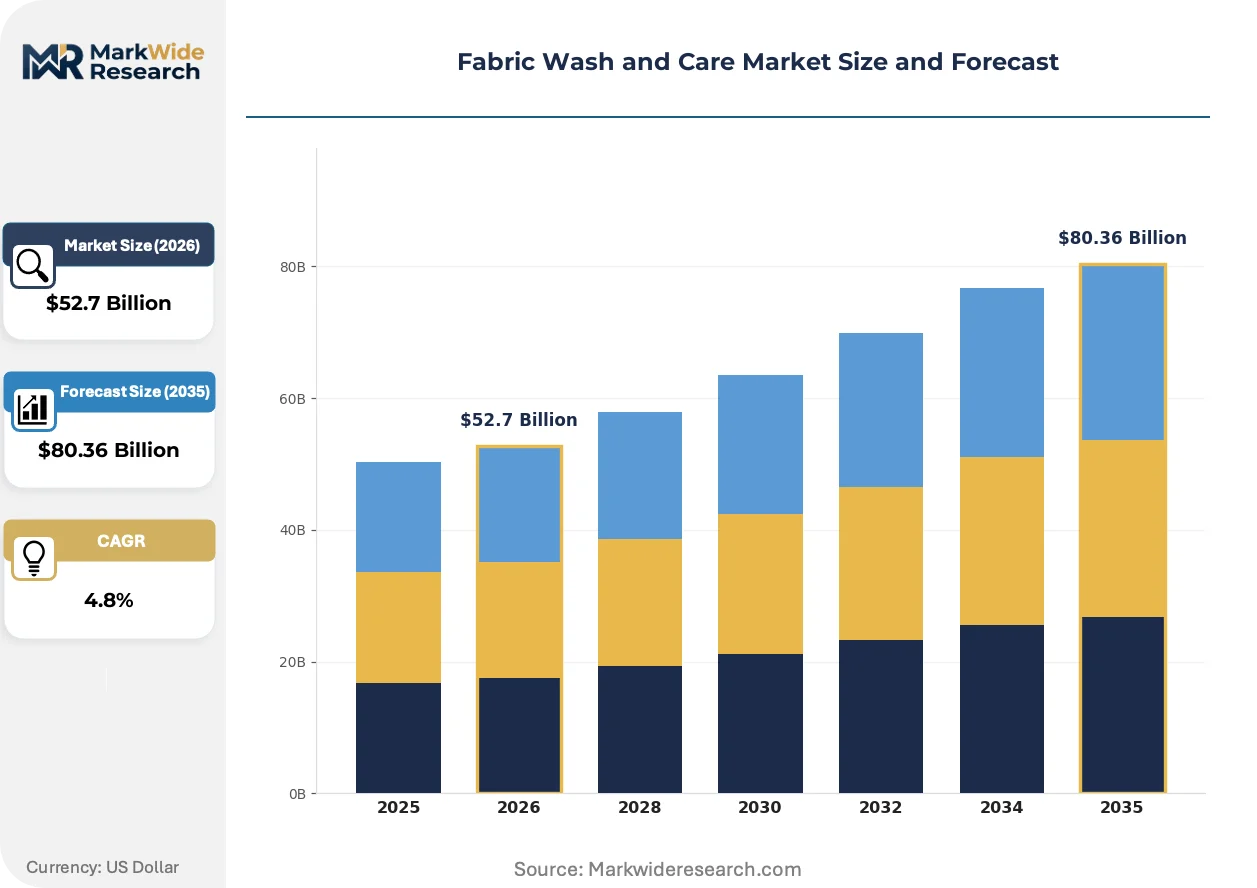
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Detergent, Powder Detergent, Fabric Softener, Stain Remover Formulation: Concentrated, Eco-friendly, Hypoallergenic, Traditional Application: Household, Commercial, Institutional, Industrial Distribution Channel: Online Retail, Supermarkets, Discount Stores, Specialty Stores |
| Companies Covered | Reckitt Benckiser, Church & Dwight, Procter & Gamble, LG Household & Health Care, Colgate-Palmolive, Unilever, Kao Corporation, The Clorox Company, Henkel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Wash and Care Market Emerging Trajectories
Biodegradable surfactant architectures and concentrated dosing systems are displacing legacy dilute formats across multiple price tiers, while regulatory disclosure requirements are reshaping supplier-retailer negotiation dynamics.
Alkyl polyglucoside technology derived from corn starch and coconut oil is expanding into European premium and mid-tier detergent lines. German and French retailers are accelerating shelf space allocation for these formulations ahead of EU Green Deal implementation deadlines. The technology is expanding into private-label supply chains as retailers seek defensible sustainability credentials for their own brands.
REACH registration requirements for petrochemical surfactants are elevating compliance costs and documentation burdens for conventional suppliers. ECHA's dossier evaluation backlog is creating approval delays that freeze formulation pipelines for 18-24 months. Small and mid-sized European manufacturers are responding by accelerating partnerships with biodegradable feedstock suppliers to bypass petrochemical regulatory friction entirely.
Urban Indian households are switching from powder to liquid detergent formats at rates exceeding historical category transitions. Modern trade and e-commerce channels are capturing this shift through subscription models and bulk delivery logistics that reduce per-unit packaging costs. Mumbai and Delhi NCR retail clusters are showing the fastest liquid penetration, with sachet formats simultaneously dominating rural traditional trade.
Fabric Wash and Care Market Segmentation
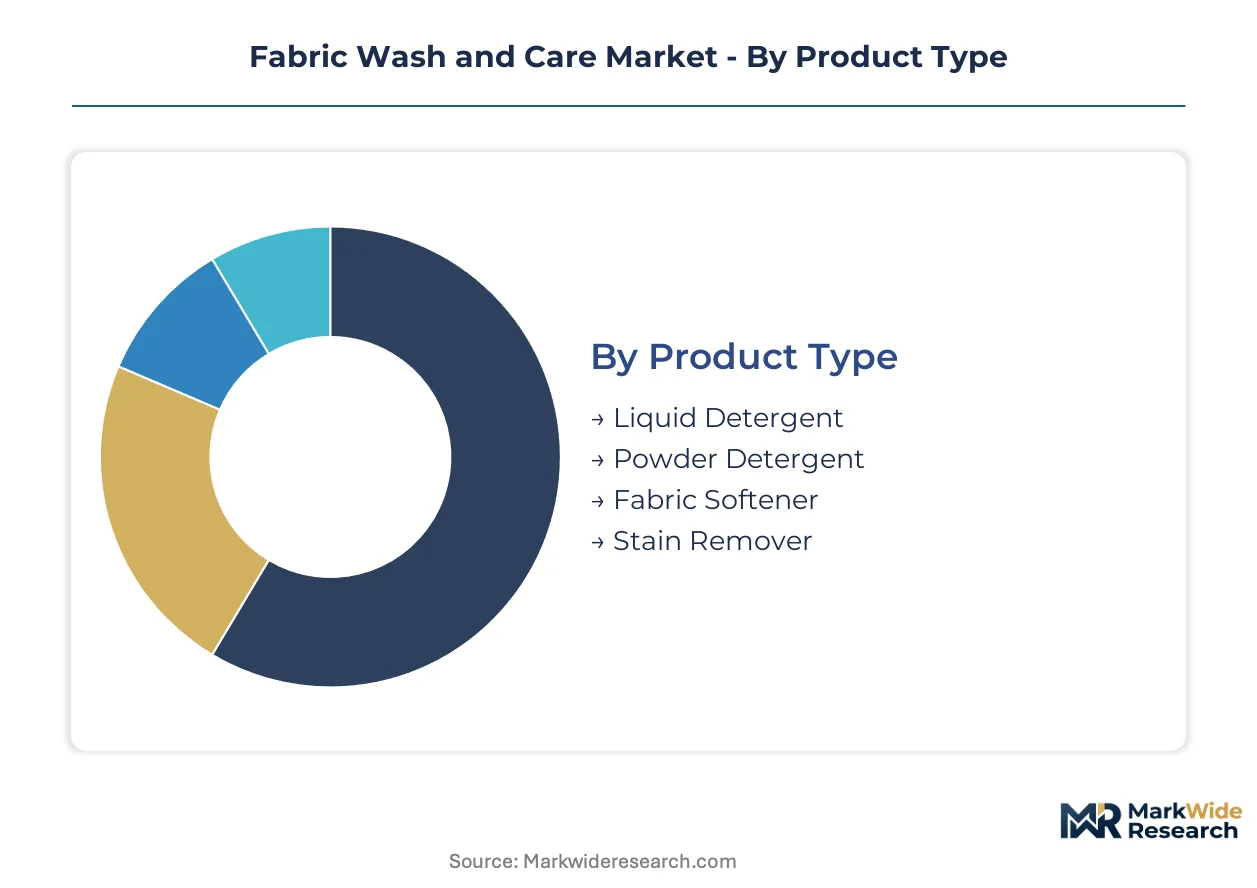
Segmentation in fabric wash and care reveals distinct capital requirements, formulation architectures, and channel economics that determine competitive positioning. Understanding where investment intensity concentrates helps stakeholders allocate resources across product development, manufacturing scale-up, and distribution infrastructure.
Product Type:
Liquid detergent and powder detergent demand the heaviest upfront manufacturing investment due to specialized blending equipment, packaging lines, and cold-chain logistics for temperature-sensitive enzymes.
- Liquid Detergent:Water-based formulations containing 15-40% surfactant by weight with enzyme stabilization systems for cold-water dissolution. Demand concentrates in German and French urban households where front-loading machines and sub-30°C washing norms dominate, though palm kernel oil feedstock volatility compresses mid-tier margins.
- Powder Detergent:Spray-dried granules with builder systems optimized for high-temperature washing and hard water conditions. Volume leadership persists in Indian and Indonesian price-sensitive regions where washing machines lack cold-water cycles and bulk purchasing patterns favor larger pack sizes.
- Fabric Softener:Cationic surfactant formulations that deposit conditioning agents on fiber surfaces during rinse cycles.
- Stain Remover:Targeted enzyme and solvent blends for pre-treatment applications, concentrated in specialty retail channels.
Most installed capacity flows through Powder Detergent. Expansion is steepest in Liquid Detergent.
Formulation:
Cost tier stratification separates premium biodegradable architectures from economy petrochemical systems, with mid-tier positioning requiring precise surfactant sourcing strategies.
- Concentrated:Reduced water content formulations delivering equivalent cleaning efficacy at 20-30% lower packaging volume and logistics cost. Retailers in US and UK mass-market channels are prioritizing shelf space allocation as Scope 3 emissions disclosure pressure intensifies, though consumer education requirements slow adoption in traditional trade.
- Eco-friendly:Alkyl polyglucoside and plant-derived surfactant systems certified under EPA Safer Choice or EU Ecolabel standards. German private-label supply chains are capturing this segment through backward integration into carbohydrate-derived surfactant production, bypassing oleochemical price volatility.
- Hypoallergenic:Fragrance-free and dye-free formulations with reduced enzyme loads for sensitive skin applications.
- Traditional:Petrochemical surfactant architectures with optical brighteners and synthetic fragrances, retaining volume in discount-store channels.
Traditional formulations still command the largest production base. Eco-friendly architectures are climbing the fastest as REACH registration burdens accumulate for petrochemical alternatives.
Application:
Customer type determines batch size, dosing precision requirements, and service-level expectations, with commercial and institutional buyers demanding technical support and inventory management systems that household channels rarely require.
- Household:Individual consumer purchases across single-family and multi-family residential units, segmented by washing machine ownership and water hardness profiles. Mumbai and Delhi NCR retail clusters are showing the fastest liquid penetration as modern trade and e-commerce subscription models reduce per-unit packaging costs.
- Commercial:Hotel chains, restaurants, and laundry services procuring concentrated formulations to reduce water and energy consumption per wash cycle. EU Green Deal chemical-sustainability mandates are forcing procurement officers to verify biodegradable surfactant content in linen-care protocols.
- Institutional:Healthcare facilities, educational institutions, and government operations with standardized procurement procedures and bulk purchasing requirements.
- Industrial:Textile processing and garment finishing operations requiring specialized cleaning chemistry for fiber preparation and dye removal.
Household applications absorb the majority of production volume. Commercial procurement is expanding most quickly as hospitality chains upgrade linen-care infrastructure.
Distribution Channel:
Geographic concentration of purchasing behavior creates distinct infrastructure requirements, with urban density favoring direct-to-consumer logistics and rural dispersion reinforcing traditional trade intermediaries.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators with subscription models and bulk delivery logistics. Urban Indian households are switching formats through these channels at rates exceeding historical category transitions, while sachet economics dominate rural Indonesian and Vietnamese traditional trade where cash-flow constraints limit bulk purchasing.
- Supermarkets:Full-assortment retail with shelf space allocation determined by logistics efficiency and sustainability credential verification. US mass retail is granting preferential placement to EPA Safer Choice verified alternatives as emissions disclosure pressure mounts.
- Discount Stores:Price-focused retail with traditional dilute product dominance and minimal service differentiation.
- Specialty Stores:Niche retail channels for hypoallergenic and premium eco-friendly formulations with educated sales assistance.
Supermarkets currently channel the most volume. Online retail is gaining share fastest as subscription logistics mature in dense urban clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and Delhi NCR retail clusters anchor liquid detergent expansion as Indian urban households abandon powder formats at rates exceeding historical category transitions. German and French retailers accelerate biodegradable surfactant shelf allocation ahead of EU Green Deal deadlines. Indonesian and Vietnamese traditional trade channels reinforce sachet economics where cash-flow constraints limit bulk purchasing.
United States
EPA Safer Choice verification secures preferential placement in mass retail as Scope 3 emissions disclosure pressure intensifies. Cold-water dissolution technology expands addressable volume in energy-conscious segments. Chicago and Los Angeles retail clusters concentrate concentrated formulation distribution through subscription logistics.
Germany
Private-label supply chains capture eco-friendly segment through backward integration into alkyl polyglucoside production. REACH registration dossier backlogs freeze conventional petrochemical formulation pipelines. North Rhine-Westphalia chemical manufacturing clusters pivot carbohydrate-derived surfactant capacity expansion.
India
BIS certification enforcement consolidates domestic manufacturing quality while accelerating liquid penetration in urban households. Modern trade and e-commerce subscription models reduce per-unit packaging costs. Mumbai and Delhi NCR retail clusters show fastest liquid format adoption alongside sachet dominance in rural traditional trade.
Indonesia
Single-use packaging formats dominate traditional trade channels where cash-flow constraints limit bulk purchasing. Palm kernel oil feedstock volatility destabilizes mid-tier plant-based surfactant pricing. Java-based manufacturing clusters supply sachet economics across archipelago distribution networks.
France
Retailers accelerate shelf space allocation for alkyl polyglucoside formulations ahead of EU Green Deal chemical-sustainability mandates. ECHA dossier evaluation delays create 18-24 month formulation pipeline freezes for conventional suppliers. Paris and Lyon retail clusters concentrate premium biodegradable detergent distribution.
Fabric Wash and Care Market Vendor Landscape
Global majors compete with regional champions across formulation technology and channel access dimensions. The vendor base stratifies into three tiers: multinational conglomerates with captive enzyme platforms, mid-tier European specialists with surfactant backward integration, and emerging-market sachet specialists with traditional trade penetration. Strategic moves concentrate on portfolio diversification toward biodegradable architectures and geographic expansion through private-label supply partnerships.
Within the multinational tier, Procter & Gamble, Unilever, and Henkel exemplify divergent competitive positioning. Procter & Gamble anchors North American concentrated format leadership through enzyme technology control. Unilever occupies emerging-market sachet economics dominance across Indonesian and Vietnamese traditional trade. Henkel represents European private-label supply chain integration into carbohydrate-derived surfactant production.
| Leading Market Players |
|---|
| Reckitt Benckiser |
| Church & Dwight |
| Procter & Gamble |
| LG Household & Health Care |
| Colgate-Palmolive |
| Unilever |
| Kao Corporation |
| The Clorox Company |
| Henkel |
| Others |
Supply Flow & Price Mechanics
Malaysian palm kernel oil futures volatility cascades through surfactant manufacturing tiers, compressing margins for mid-tier plant-based formulations while amplifying pricing power for backward-integrated European producers shielded from oleochemical swings.
Pricing Analysis
Input-cost pass-through dynamics operate through three-tier pricing structure across premium, standard, and economy levels. Certification under EPA Safer Choice or EU Ecolabel standards commands shelf placement premiums in mass retail channels, while bulk volume procurement in commercial hospitality segments reduces per-unit acquisition costs. Pricing pressure stems from REACH registration cost accumulation for petrochemical surfactant suppliers, forcing margin compression in traditional formulations. Price-sensitive rural households in Indonesia and Vietnam resist format premiums, whereas German urban consumers absorb biodegradable surcharges through subscription logistics.
Supply Chain Analysis
Workforce availability constraints in North Rhine-Westphalia chemical clusters and Java-based manufacturing zones are reshaping capacity expansion timelines for alkyl polyglucoside and sachet production lines. Supply concentration centers on Germany, India, and Indonesia, with surfactant feedstock dependencies spanning Malaysian palm kernel oil, Indonesian coconut oil, and Indian corn starch derivatives. Single-source vulnerability in Southeast Asian oleochemical supply creates exposure to harvest cycle disruptions. Distribution runs through modern trade and e-commerce platforms in dense urban clusters, while traditional trade intermediaries dominate rural archipelago networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fabric wash and care markets reward geographic arbitrage between EU Green Deal compliance costs and India's BIS certification enforcement timeline, with formulation architecture choices determining margin capture across regulatory jurisdictions.
For Market Incumbents: Extend captive enzyme technology control into concentrated format leadership through cold-water dissolution patent navigation, while accelerating backward integration into carbohydrate-derived surfactant production to neutralize palm kernel oil price volatility threats. Defend European private-label supply positions by expanding North Rhine-Westphalia alkyl polyglucoside capacity ahead of REACH dossier backlogs freezing competitor pipelines. For New Entrants and Emerging Players: Capture sachet economics white space in Vietnamese traditional trade channels where cash-flow constraints limit bulk purchasing penetration by incumbent multinationals. Target urban Indian liquid detergent conversion through e-commerce subscription models with reduced per-unit packaging cost structures, leveraging Mumbai and Delhi NCR retail cluster density for last-mile efficiency. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier European specialists possessing surfactant backward integration and biodegradable certification credentials. Long-term viability across the analysis window favors acquisition targets with captive alkyl polyglucoside production and established private-label retailer relationships. Watch enzyme patent expiration timelines as inflection indicators for licensing complexity and formulation redesign cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkyl Polyglucoside | Captive carbohydrate-derived surfactant production shields margins from Malaysian palm kernel oil volatility. |
| Cold-Water Dissolution Technology Investment | Enzyme-stabilized sub-30°C formulations expand addressable volume in energy-conscious German and US households. |
| Sachet Economics Scale-Up | Single-use packaging dominance in Indonesian traditional trade captures cash-constrained rural consumer segments. |
| EPA Safer Choice Certification | Verified eco-friendly credentials secure preferential shelf placement in US mass retail facing Scope 3 disclosure pressure. |
| E-Commerce Subscription Logistics | Bulk delivery models reduce per-unit packaging costs and accelerate urban Indian liquid detergent format conversion. |
Methodological Framework
Multiple input streams — procurement directors at hotel chains, surfactant R&D leads, retail category buyers, and distribution channel partners — were reconciled against customs trade records, BIS certification filings, and SEC 10-K disclosures to construct bottom-up volume estimates and top-down market validation for fabric wash and care segments.
Historical volume trajectories were cross-referenced against panel input from manufacturing and retail stakeholders to derive growth parameters across the projection horizon, with segmentation modeling across formulation type, packaging format, regional regulatory cluster, and channel architecture. CAGRs emerged from trend extrapolation adjusted for BIS enforcement intensity, EU Green Deal implementation pacing, and enzyme patent expiration clustering.
Feedstock price shocks, REACH dossier approval delays, and cold-water washing norm adoption velocity are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation of capacity investment and format portfolio priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
South Korea Home Textile Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
Canada Home Textile Market
Home Textiles
Germany Home Textile Market
Home Textiles
Textile Floorings Market
Home Textiles
Australia Home Textiles Market
Home Textiles
GCC Home Textile Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
Global Theater Linen Market
Home Textiles
United States Home Textile Market
Home Textiles
Towel Market
Home Textiles
Cotton Towel Market
Home Textiles
Japan Home Textile Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
Blanket Market
Home Textiles
North America Home Textile Market