
 Towel Market | 2026-2036
Towel Market Size, Share, and Industry Trends Forecast 2026-2036
Towel Market Outlook
Premium long-staple cotton specification tiers is collapsing the gap between mass-market and luxury towel offerings. Welspun India leverages integrated spinning-to-retail operations across Gujarat and Maharashtra. Trident Group anchors its position through captive energy and water recycling systems at its Barnala complex. Himatsingka Seide differentiates via specialized sheared-finish terry constructions for the North American hospitality channel.
A towel is an absorbent textile article woven from looped pile yarns, typically constructed with pile heights between 4 mm and 7 mm and grammage ranging from 300 gsm to 700 gsm, designed for moisture removal from skin or surfaces. Cotton material grades command the dominant margin pool due to consumer preference for ring-spun and combed Egyptian varieties, while microfiber segments compete on quick-dry performance metrics in the gym and travel categories. Beach towels represent a seasonal volume concentration with higher print customization requirements, whereas spa towels sustain premium pricing through certified organic cotton sourcing and specialized bleach-resistant finishes.
The US EPA oversees wastewater discharge limits under the Clean Water Act that constrain dyehouse operations, while OEKO-TEX Standard 100 certification shapes European retail access requirements for chemical residue thresholds. India's BIS mandatory certification for textile products is tightening quality benchmarks for domestic market entry. Stakeholders must monitor how evolving water-stress regulations across manufacturing clusters will reshape sourcing decisions and capital allocation for processing capacity.
Market Dynamics
Water-stress regulations across textile manufacturing clusters are forcing capital reallocation toward closed-loop processing systems, while hospitality procurement consolidation in North America compresses supplier margins through volume concentration.
Growth Catalysts
- EU Ecolabel criteria tightening:The EU Ecolabel's revised chemical discharge thresholds for textiles are accelerating certified organic cotton sourcing across European retail channels, creating premium positioning for compliant suppliers.
- North American hospitality procurement expansion:Hotel chains are consolidating linen programs under single-source agreements, pulling volume toward integrated manufacturers with captive dyehouse capacity.
- Tamil Nadu manufacturing belt concentration:India's towel production gravity in Tamil Nadu enables specialized terry weaving clusters with shared finishing infrastructure, reducing logistics costs for export orders.
Market Restraints
- Ring-spun cotton input volatility:Long-staple Egyptian and Pima cotton prices fluctuate with Nile Basin water allocation disputes and Texas High Plains drought cycles, squeezing margin predictability for premium tiers.
- Dyehouse concentration in water-stressed basins:Over 60% of global towel finishing capacity sits within India's Noyyal River basin and Pakistan's Punjab region, where groundwater depletion triggers production halts during dry seasons.
- Microfiber substitution in performance segments:Polyester-polyamide blends compete on quick-dry metrics for gym and travel applications, eroding cotton's share in sub-400 gsm categories.
Strategic Opportunities
- India's domestic market expansion:BIS mandatory certification is raising quality barriers for import competition, opening shelf space for organized domestic manufacturers in tier-2 and tier-3 cities.
- Spa and wellness channel specialization:Bleach-resistant organic cotton finishes command 40-60% price premiums in certified wellness resorts, a segment with lower price elasticity than mass retail.
- Direct-to-hospitality digital platforms:Procurement teams at mid-size hotel chains are bypassing traditional textile distributors through specialized B2B portals, shortening payment cycles and reducing sample lead times.
Industry Challenges
- OEKO-TEX Standard 100 certification timelines:Testing for restricted substance lists across dyestuffs and finishing chemicals extends product development cycles by 8-12 weeks, delaying seasonal collection launches.
- Captive energy and water recycling capex requirements:Zero-liquid-discharge mandates in Tamil Nadu and Gujarat require Rs 15-25 crore investments per facility, straining mid-scale weavers without access to green financing instruments.
- Sheared-finish terry construction skill scarcity:Specialized cutting and shearing technicians for hospitality-grade towels are concentrated in legacy Barnala and Panipat clusters, limiting geographic expansion of this capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Towel Market |
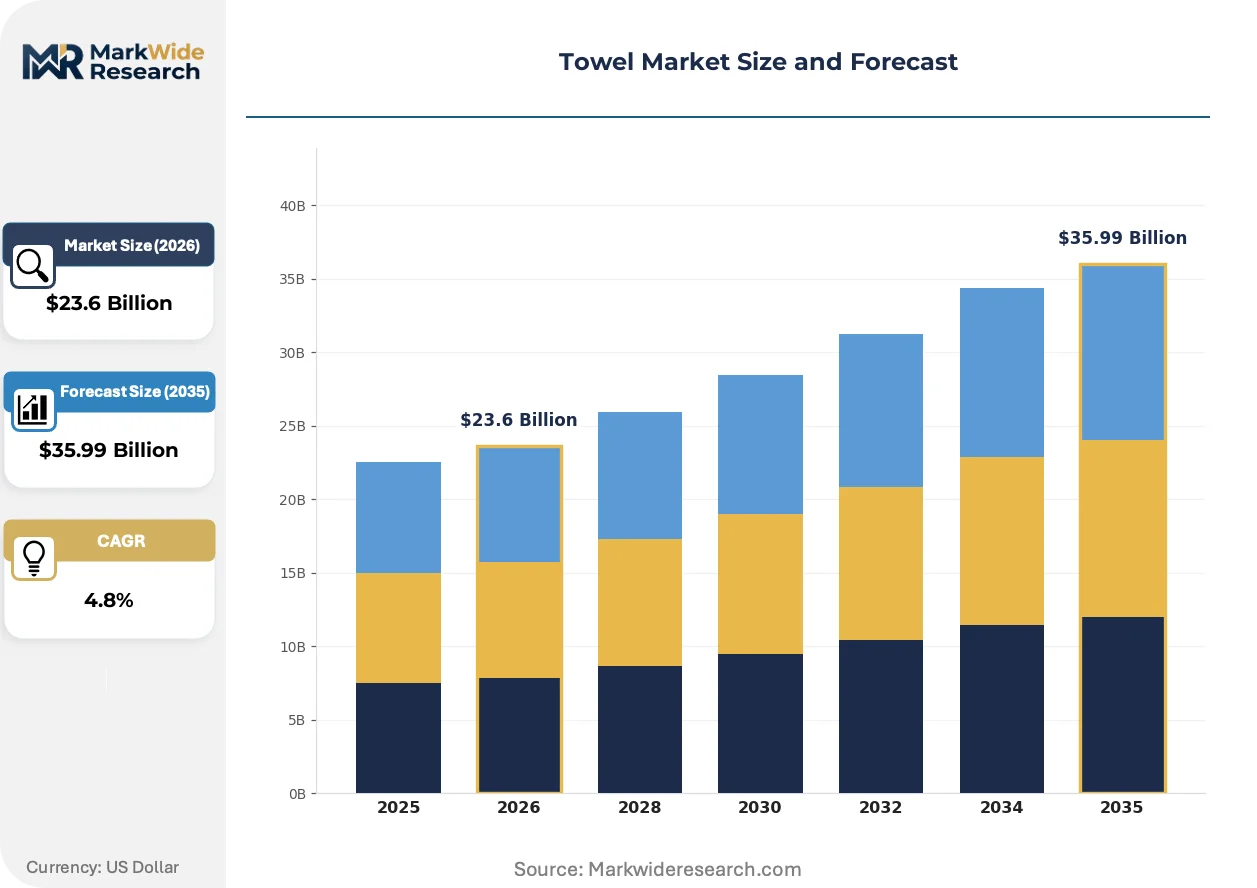
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $35.99 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bath Towels, Hand Towels, Beach Towels, Spa Towels Material: Cotton, Microfiber, Bamboo, Linen Form: Flat, Rolled, Folded, Hanging End User: Households, Hotels, Gyms, Spas |
| Companies Covered | Welspun India, Trident Group, Himatsingka Seide, 1888 Mills, Loftex, Sunvim Group, Zorlu Tekstil, Alok Industries, Indus Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Towel Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are splitting towel manufacturing into two distinct capability tiers: integrated giants with captive labs versus commodity assemblers dependent on outsourced finishing.
Recycled cotton and post-consumer textile fiber blends are bifurcating the raw material base. Hospitality procurement teams at Marriott and Hilton properties are piloting 30-50% recycled content specifications for non-guest-facing applications. This shift is compressing virgin cotton offtake in institutional channels while creating premium scarcity for certified organic long-staple grades in luxury retail.
REACH Annex XVII restrictions on azo dyes and formaldehyde-based finishes are reshaping chemical formulation strategies across European-bound production. The regulation forces dyehouses to validate alternative cross-linking agents and natural dye fixatives, adding 15-20% to processing costs. Turkish manufacturers near Bursa and Denizli are responding fastest due to proximity testing access at Istanbul textile institutes.
Certification-driven specification tightening is altering buyer-seller power dynamics. North American hospitality procurement departments now require simultaneous OEKO-TEX, GOTS, and BCI documentation before contract consideration, displacing price-only sourcing for linen programs. This behavior concentrates award volumes with vertically integrated suppliers maintaining in-house certification teams, most visible in RFP outcomes for 200-plus property hotel chains.
Towel Market Segmentation
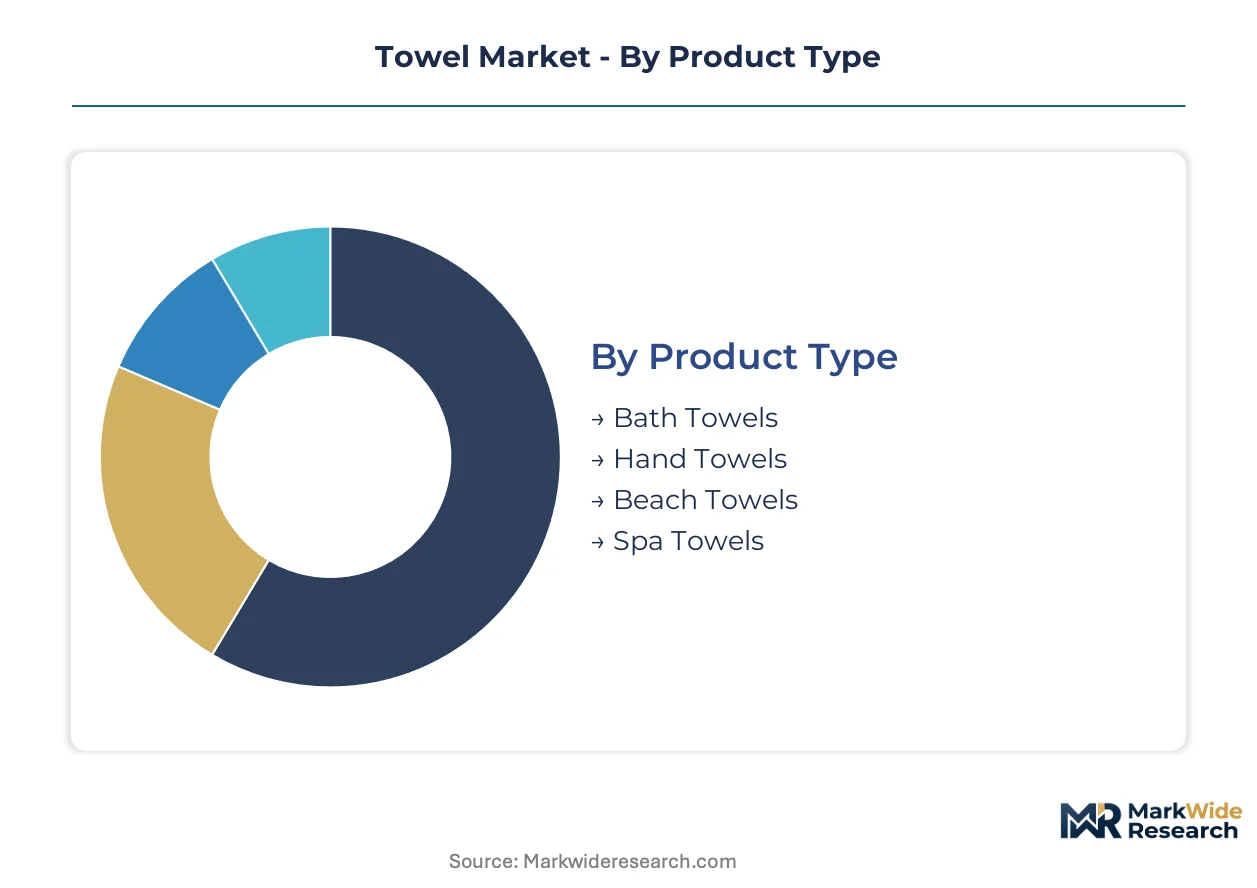
Towel procurement decisions split across technical specifications, material chemistry, and channel requirements. Understanding where margin pools concentrate within each dimension reveals which product configurations justify premium positioning versus commodity exposure.
Product Type:
Margin concentration sits with specialized hospitality and wellness applications rather than mass retail volume plays.
- Bath Towels:Ring-spun cotton constructions between 500-700 gsm dominate household replacement cycles and hotel linen programs. North American hospitality procurement teams specify sheared-finish terry for guest-facing inventory, pulling volume toward integrated manufacturers with captive dyehouse capacity.
- Spa Towels:Certified organic cotton with bleach-resistant finishes commands 40-60% price premiums in wellness resorts. Demand concentrates in European-certified facilities where EU Ecolabel compliance shapes vendor qualification.
- Hand Towels:Lower grammage specifications (300-450 gsm) serve high-frequency replacement cycles in commercial restrooms.
- Beach Towels:Seasonal volume spikes with higher print customization requirements and sub-400 gsm constructions for portability.
The dominant share belongs to Bath Towels, while Spa Towels are closing the gap fastest.
Material:
Raw material selection determines processing cost structure and certification pathway complexity.
- Cotton:Long-staple Egyptian and Pima varieties anchor premium tier positioning through ring-spun and combed constructions. Nile Basin water allocation disputes and Texas High Plains drought cycles inject price volatility into margin planning for specialty grades.
- Microfiber:Polyester-polyamide blends compete on quick-dry performance metrics below 400 gsm. Gym and travel channel procurement teams specify these for locker room and fitness applications where rapid moisture wicking outweighs tactile preference.
- Bamboo:Viscose-derived fibers marketed under sustainability positioning face OEKO-TEX Standard 100 scrutiny on chemical processing residues.
- Linen:Higher absorbency and faster drying characteristics serve boutique hospitality channels with lower volume scale.
Cotton retains the dominant share, though Microfiber is expanding most quickly in performance-oriented end uses.
Form:
Packaging and presentation specifications vary sharply between retail shelf requirements and commercial bulk procurement.
- Flat:Standard presentation for retail shelf placement and hospitality linen closet storage. Minimal packaging cost supports economy tier positioning.
- Rolled:Preferred configuration for spa treatment room presentation and amenity program aesthetics. Higher labor content in finishing compresses margins unless automated rolling equipment is deployed.
- Folded:Pre-folded specifications for cruise ship and airline amenity kits where space optimization dictates packaging geometry.
- Hanging:Integrated loop constructions for gym and poolside applications where drying infrastructure is limited.
Flat form dominates volume, while Rolled form carries the steepest expansion trajectory in wellness channel penetration.
End User:
Customer type determines specification stringency, certification burden, and contract structure.
- Hotels:Consolidated procurement under single-source agreements concentrates volume with vertically integrated suppliers. Simultaneous OEKO-TEX, GOTS, and BCI documentation requirements displace price-only sourcing for 200-plus property chains.
- Households:Replacement-driven demand with price sensitivity concentrated in mass retail channels. Private label penetration is high in North American big-box distribution.
- Spas:Certified organic sourcing mandates and specialized finish requirements create vendor stickiness once qualification is achieved.
- Gyms:Quick-dry performance specifications favor microfiber blends with lower per-unit cost tolerance for high-loss environments.
Hotels command the dominant share, while Spas are climbing the fastest on premium positioning and lower price elasticity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Towel manufacturing clusters concentrate where water access, cotton proximity, and finishing infrastructure intersect. Four countries anchor distinct competitive positions through regulatory differentiation and channel specialization.
United States
Hospitality procurement teams at Marriott and Hilton properties drive premium linen program consolidation. The EPA enforces Clean Water Act discharge limits that constrain domestic dyehouse operations. Texas High Plains cotton growing regions supply long-staple Pima varieties to specialized finishing facilities in Georgia and the Carolinas.
Germany
Retail buyers specify OEKO-TEX Standard 100 certification as a baseline requirement for shelf placement. REACH Annex XVII restrictions on azo dyes and formaldehyde-based finishes reshape chemical formulation strategies. The Hohenstein textile testing institutes near Stuttgart accelerate compliance validation for European-bound production.
India
Domestic market expansion in tier-2 and tier-3 cities creates shelf space for organized manufacturers. BIS mandatory certification raises quality barriers against import competition. Tamil Nadu's terry weaving belt around Karur and Erode hosts shared finishing infrastructure that reduces logistics costs for export orders.
Turkey
Proximity to European retail channels enables faster response to specification changes. The country's alignment with EU chemical regulations streamlines certification pathways for Ecolabel compliance. Manufacturers near Bursa and Denizli leverage Istanbul textile institutes for rapid testing turnaround on alternative dye formulations.
China
Microfiber production scale dominates quick-dry performance segments for gym and travel applications. GB standards and dual carbon goals tighten energy efficiency requirements for textile processing. Zhejiang and Jiangsu provinces host integrated polyester-polyamide spinning-to-conversion operations serving Asian fitness channel procurement.
Towel Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the towel manufacturing base. The market structure tiers between integrated giants with captive spinning, weaving, and finishing assets versus specialized weavers dependent on outsourced processing. Three archetypes dominate: vertically integrated conglomerates controlling upstream cotton supply, regional specialists with shared infrastructure access, and performance-focused innovators in synthetic fiber constructions. Competitive moves concentrate on zero-liquid-discharge compliance investments and direct-to-hospitality digital platform development.
Within the integrated conglomerate tier, Welspun India and Trident Group exemplify archetypes combining captive energy systems with in-house certification management. Himatsingka Seide occupies a position representing specialized finish capabilities for North American hospitality channels. These three anchors demonstrate how geographic concentration in Gujarat, Maharashtra, and Punjab clusters enables distinct competitive positioning through infrastructure control rather than scale alone.
| Leading Market Players |
|---|
| Welspun India |
| Trident Group |
| Himatsingka Seide |
| 1888 Mills |
| Loftex |
| Sunvim Group |
| Zorlu Tekstil |
| Alok Industries |
| Indus Home |
| Others |
Value Chain & Pricing Dynamics
Microfiber substitution in gym and travel applications is simultaneously shifting supply geography toward China's Zhejiang polyester-polyamide belt and compressing pricing power in sub-400 gsm cotton tiers. This displacement dynamic rewards manufacturers with captive synthetic fiber spinning while squeezing margin predictability for ring-spun cotton specialists dependent on Egyptian and Pima input volatility.
Pricing Analysis
EU Ecolabel criteria dictate the pricing tier structure across European retail channels, separating certified organic cotton premiums from uncertified commodity tiers. Three-tier pricing structure across premium, standard, and economy levels anchors on OEKO-TEX Standard 100 achievement, with GOTS and BCI documentation commanding additional positioning. Cost compression in mass retail channels is intensifying because private label penetration at North American big-box distributors concentrates volume with lowest-bid suppliers. Household replacement cycles exhibit highest price sensitivity, while wellness resort procurement teams demonstrate lowest elasticity for bleach-resistant organic finishes.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes are reshaping inventory positioning for Turkish manufacturers near Bursa and Denizli. Supply concentrates in India's Tamil Nadu terry weaving belt, China's Zhejiang microfiber corridor, and Turkey's Aegean finishing cluster. Raw material dependencies rest on long-staple Egyptian cotton, Texas Pima varieties, and polyester-polyamide chip feedstocks. Single-source vulnerability concentrates in the Noyyal River basin, where groundwater depletion triggers seasonal production halts. Distribution runs through hospitality procurement consolidation, direct-to-hospitality digital platforms, and traditional textile distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-hospitality digital platforms are creating platform-economics inflection, with specialized B2B portals collapsing sample lead times and payment cycles for mid-size hotel chains. This interoperability shift rewards suppliers bypassing traditional distributor markups.
For Market Incumbents: Consolidate captive dyehouse capacity and in-house certification management teams to defend against hospitality procurement consolidation pulling volume toward integrated manufacturers. Expand zero-liquid-discharge compliance investments in Tamil Nadu and Gujarat clusters before BIS mandatory certification tightens further. Channel control through direct-to-hospitality platforms represents the critical lever for margin defense. For New Entrants and Emerging Players: OEKO-TEX Standard 100 fast-track certification opens shelf space in European retail channels where REACH Annex XVII restrictions displace commodity assemblers. Target India's tier-2 and tier-3 domestic market expansion, where BIS quality barriers create protected terrain against import competition. Spa and wellness channel specialization offers the most penetrable segment, with go-to-market anchored on bleach-resistant organic cotton finish development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists in shared Tamil Nadu finishing infrastructure. Long-term viability over the next decade hinges on water-stress regulation adaptation and closed-loop processing capex deployment. Acquisition targets should display captive energy systems and sheared-finish terry construction capabilities. The signal to watch is hospitality RFP outcomes for 200-plus property chains, where simultaneous certification documentation requirements concentrate award volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Liquid-Discharge Compliance Investment | Tamil Nadu mandates force Rs 15-25 crore facility upgrades, straining mid-scale weavers without green financing access. |
| Direct-to-Hospitality Digital Platform Launch | Marriott and Hilton procurement teams pilot specialized B2B portals, shortening payment cycles and sample lead times. |
| Certified Organic Cotton Sourcing Expansion | EU Ecolabel tightening accelerates premium positioning for GOTS-compliant suppliers across European retail channels. |
| Sheared-Finish Terry Capability Acquisition | Specialized cutting and shearing technicians concentrate in Barnala and Panipat clusters, limiting geographic expansion. |
| Recycled Content Specification Pilot | Hospitality procurement teams at major chains test 30-50% recycled cotton blends for non-guest-facing linen applications. |
Study Parameters
Desk research of customs records, BIS certification filings, and hospitality procurement databases preceded structured interviews with textile plant managers, hotel linen program directors, dyehouse operations heads, and retail category buyers. Primary fieldwork across Tamil Nadu, Gujarat, and Turkish Aegean manufacturing clusters combined with secondary validation from OEKO-TEX and GOTS certification registries. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Variance decomposition across product type, material chemistry, end-user channel, and regional production cluster shaped the analytical framework. CAGRs derived from logistic adoption curves and replacement cycle dynamics throughout the forecast period. Industry-specific inputs included Nile Basin water allocation indices, Texas High Plains drought severity measures, and REACH Annex XVII chemical restriction timelines.
Underlying assumptions cover stable hospitality procurement consolidation patterns and continued EU Ecolabel tightening trajectory, with deviation risk concentrated in groundwater depletion acceleration across India's Noyyal River basin and microfiber substitution rates in performance segments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Indonesia Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Global Theater Linen Market
Home Textiles
Japan Home Textile Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
Europe Home Textile Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
Turkey Home Textile Market
Home Textiles
France Home Textile Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
Bath Towel Market
Home Textiles
South Korea Home Textile Market
Home Textiles
GCC Home Textile Market
Home Textiles
Blanket Market
Home Textiles
Germany Home Textile Market
Home Textiles
Wool Dryer Ball Market