
 Wool Dryer Ball Market | 2026-2036
Wool Dryer Ball Market Size, Share, and Industry Trends Forecast 2026-2036
Wool Dryer Ball Market Insights
Bundle configurations featuring core-scented wool dryer balls paired with complementary laundry accessories is pivoting buyer choice toward higher-margin sets. Smart Sheep leverages its direct-to-consumer channel control to sustain repeat purchase rates. Woolzies anchors its competitive position through geographic dominance in North American retail distribution. Friendsheep Sustainable Goods differentiates via product specialization in organic-certified Merino wool offerings.
Wool dryer balls are spherical felted wool products, typically measuring 7-9 centimeters in diameter, manufactured through a wet-felting process that binds wool fibers into dense, durable spheres designed to separate garments and accelerate drying cycles by improving hot air circulation. The multi-layer product type leads unit economics due to superior longevity claims, while core-scented variants command premium positioning through essential oil infusion. Merino wool material grades concentrate margin pools given consumer willingness to pay for finer fiber micron counts, and commercial laundromat applications represent the fastest-growing segment as B2B procurement shifts toward chemical-free operational protocols.
The EPA Safer Choice program and the EU REACH regulation constrain synthetic additive use in wool processing, directly shaping product certification requirements and market access conditions for imported goods. The Federal Trade Commission's Green Guides in the United States enforce substantiation standards for biodegradability and renewable content claims, filtering marketing practices across the category. Stakeholders must monitor evolving textile labeling mandates in target jurisdictions to preempt compliance-driven reformulation costs.
Market Dynamics
The wool dryer ball market pivots on the tension between chemical-free household mandates and the operational complexity of scaling natural fiber supply chains. REACH compliance in the European Union and the EPA Safer Choice program in the United States are compressing synthetic additive tolerances while Merino wool sourcing concentrates in Australia and New Zealand.
Growth Catalysts
- EU REACH Regulation:Chemical disclosure requirements for textile processing are filtering out synthetic-laden competitors and elevating certified wool products in European retail channels.
- Commercial Laundromat Segment:B2B procurement teams at facility management companies are adopting chemical-free operational protocols to reduce dermatitis liability and ventilation costs.
- Merino Wool Micron Grades:Finer fiber specifications below 19 microns are commanding premium positioning as consumers associate micron count with softness and garment protection.
Market Restraints
- Wool Price Volatility:Australian wool auction prices fluctuate with drought cycles and Chinese import demand, compressing margin predictability for finished goods manufacturers.
- Processing Concentration:Wet-felting capacity clusters in Nepal and New Zealand, creating single-source vulnerability for North American brands dependent on outsourced production.
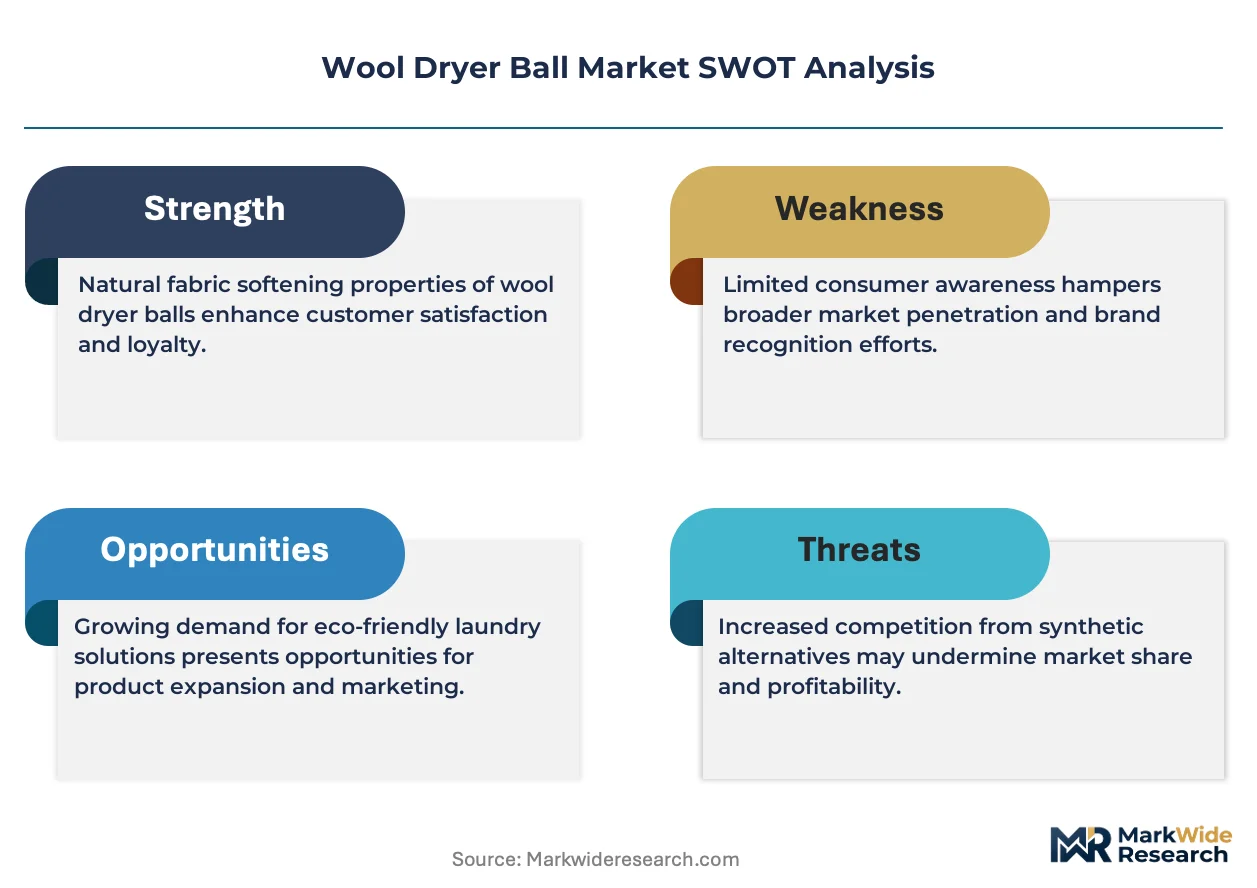
- Synthetic Sponge Substitutes:Reusable silicone dryer balls and cellulose-based alternatives are capturing price-sensitive segments through lower unit costs and color customization.
Strategic Opportunities
- Underpenetrated German Market:Eco-conscious households in Bavaria and Baden-Württemberg show high sustainability index scores but limited brand awareness of wool alternatives to dryer sheets.
- Essential Oil Convergence:Partnerships between wool processors and botanical extract suppliers are enabling core-scented product lines with certified organic lavender and eucalyptus infusions.
- Subscription Channel Innovation:Direct-to-consumer replenishment models for scent refresher kits are extending customer lifetime value beyond the durable ball purchase.
Industry Challenges
- Felting Artisan Skill Gap:Traditional wet-felting expertise is aging out in Nepalese production clusters, forcing training investments or mechanization trade-offs.
- Organic Certification Timelines:GOTS and OEKO-TEX audit backlogs are extending product launch cycles by four to six months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wool Dryer Ball Market |
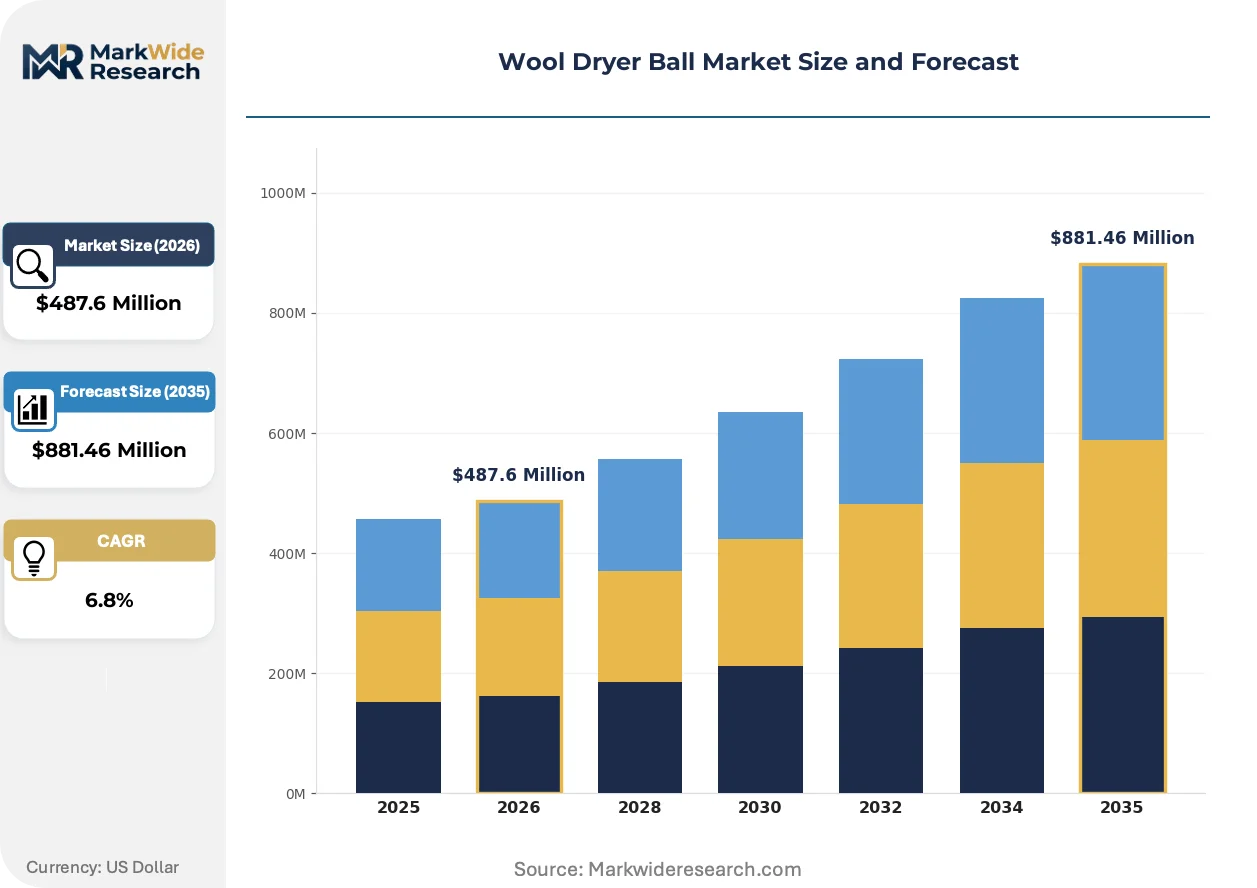
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Multi Layer, Core Scented, Custom Size Material: Merino Wool, Alpaca Wool, Yak Wool, Cashmere Wool Application: Household Laundry, Commercial Laundromats, Eco-Friendly Cleaning, Travel Laundry End User: Homeowners, Laundry Service Providers, Environmental Organizations, Hospitality Sector |
| Companies Covered | Smart Sheep, Woolzies, Friendsheep Sustainable Goods, LooHoo, Molly’s Suds, Grove Co., Nellie’s, Handy Laundry, Whitmor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wool Dryer Ball Market Trends and Innovations
Product differentiation is migrating from material purity claims toward functional augmentation and scent ecosystem integration. Manufacturers are embedding sensor-responsive features and building recurring revenue through consumable attachments.
Smart-enabled wool dryer balls with moisture-sensing cores are decentralizing the timing of cycle completion alerts away from appliance-integrated systems. Eco-conscious homeowners in California and Oregon are piloting these connected variants through beta programs. The technology is decentralizing consumer touchpoints from dryer manufacturers to accessory brands, shifting data ownership and service relationships.
The EPA Safer Choice program is tightening substantiation standards for biodegradability claims in textile accessories. Third-party testing costs for wool fiber decomposition validation have risen substantially. Private-label brands selling through mass retail in the United States are absorbing these compliance costs to maintain shelf placement against unverified competitors.
Bundle purchasing patterns are displacing single-unit transactions as the dominant acquisition model. Direct-to-consumer channels are capturing multi-ball sets paired with essential oil refreshers, while traditional retail remains anchored on individual SKUs. This bifurcation is most pronounced in Australian and Canadian markets where subscription commerce penetration exceeds category averages.
Wool Dryer Ball Market Segmentation
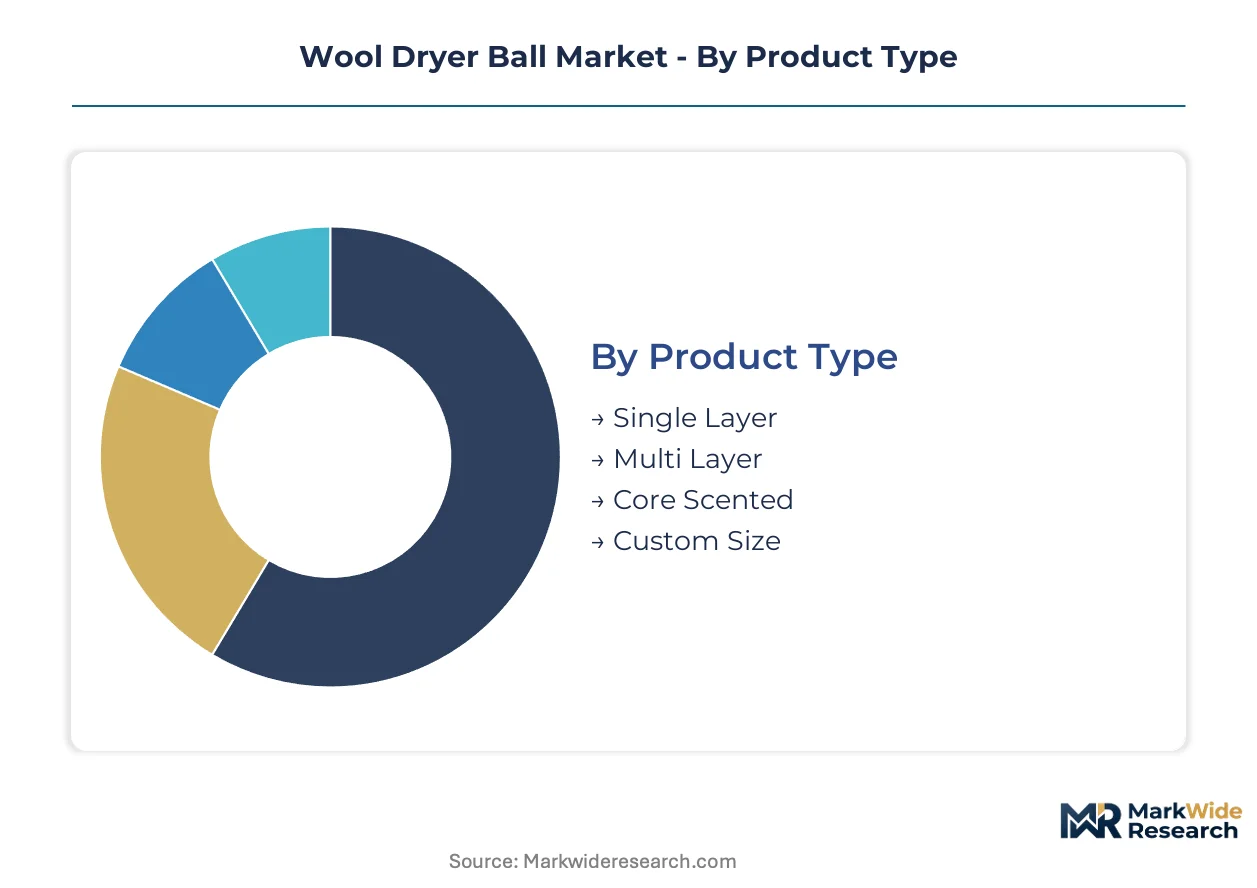
Wool dryer ball manufacturers align production configurations against distinct buyer willingness-to-pay thresholds and performance expectations. Segment boundaries reflect sourcing complexity, certification tiers, and channel access requirements rather than simple price discrimination.
Product Type:
Purchase patterns diverge sharply between durability-seeking institutional buyers and convenience-oriented residential consumers prioritizing scent integration.
- Multi Layer:Dense felted construction using three or more wool laminations creates superior structural integrity for high-rotation commercial environments. Demand concentrates among facility management companies operating California and Texas laundromat chains seeking to minimize replacement frequency and reduce vendor management overhead.
- Core Scented:Essential oil infusion into the wool core delivers sustained fragrance release across drying cycles without synthetic coating residues. Oregon and Vermont direct-to-consumer channels show strongest uptake where organic certification and botanical sourcing transparency drive premium acceptance.
- Single Layer:Basic felted wool sphere offering entry-tier positioning for price-sensitive first-time adopters testing chemical-free alternatives.
- Custom Size:Diameter and density specifications tailored to industrial dryer drum configurations for hospitality and healthcare linen processing operations.
Volume sits with Multi Layer; growth tilts toward Core Scented.
Material:
Raw fiber provenance dictates margin architecture through micron count grading, animal welfare certification, and regional supply security.
- Merino Wool:Sub-19 micron fiber specifications from Australian and New Zealand stations command the highest unit economics through softness perception and garment protection claims. Bavarian and Baden-Württemberg households in Germany demonstrate disproportionate willingness-to-pay for certified Merino grades aligned with EU REACH compliance requirements.
- Alpaca Wool:Hollow fiber structure delivers superior moisture wicking and thermal properties suited to humid climate applications. Peruvian sourcing clusters around Arequipa and Puno provide the dominant supply base for North American specialty retailers.
- Yak Wool:Coarser fiber profile from Himalayan plateau regions offers distinctive texture differentiation for artisan-positioned brands targeting conscious luxury segments.
- Cashmere Wool:Ultra-fine down fiber commands niche positioning where tactile superiority outweighs durability concerns and price elasticity is lowest.
Merino Wool dominates current procurement volumes; Alpaca Wool exhibits the steepest expansion trajectory among alternative fibers.
Application:
Operational context determines performance specifications, with institutional buyers emphasizing throughput efficiency and residential users prioritizing sensory experience.
- Commercial Laundromats:High-velocity processing environments in California, Texas, and Florida drive demand for maximum durability specifications and bulk procurement terms. Facility operators adopt chemical-free protocols to reduce ventilation infrastructure costs and dermatitis liability exposure.
- Household Laundry:Core volume segment where replacement of single-use dryer sheets with reusable alternatives concentrates in US Pacific Northwest and Northeast corridor metro areas.
- Eco-Friendly Cleaning:Certification-driven procurement by municipal sustainability programs and corporate ESG initiatives requiring third-party biodegradability validation.
- Travel Laundry:Compact, lightweight configurations for recreational vehicle and extended-stay accommodation use cases.
Household Laundry anchors installed base; Commercial Laundromats gain share fastest among application categories.
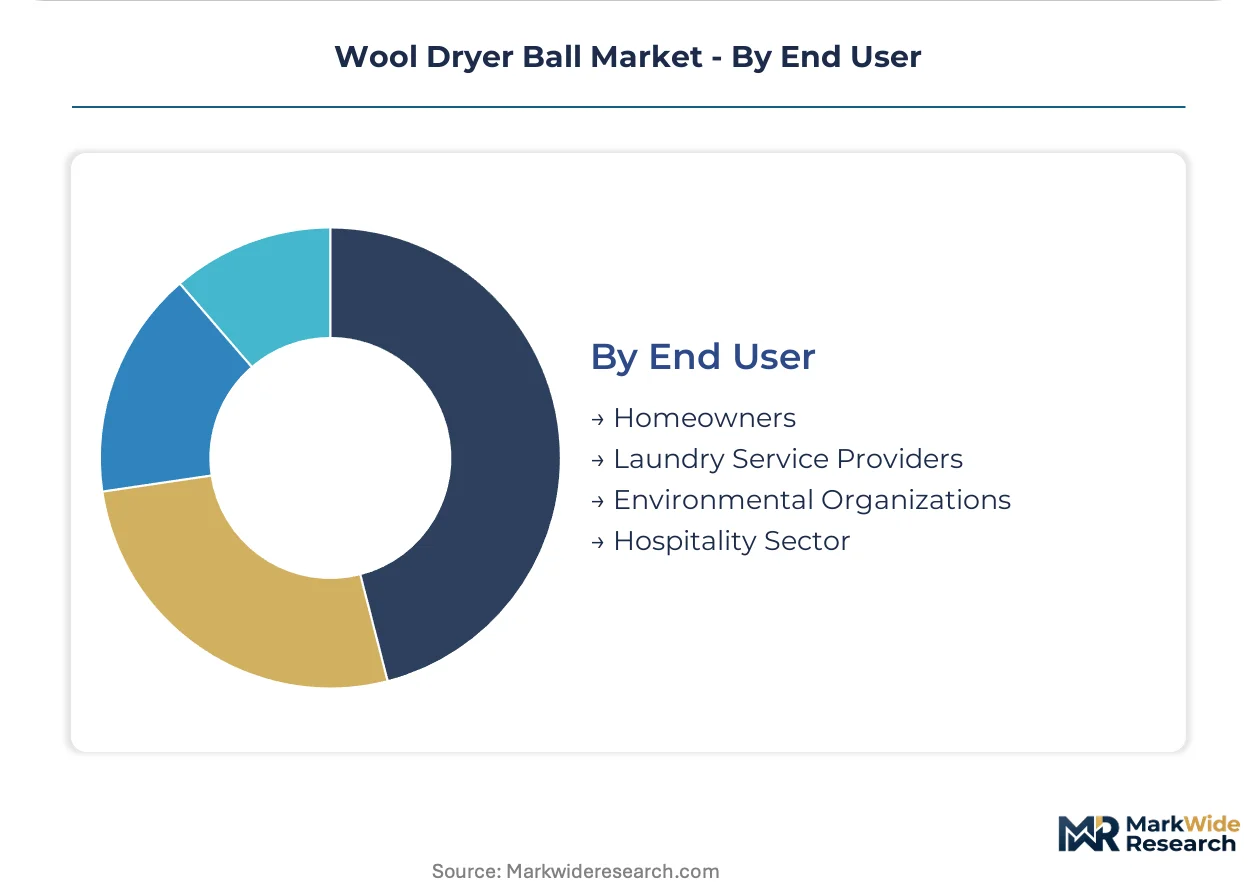
End User:
Procurement authority and decision criteria fragment across consumer, commercial, and institutional buyer types with divergent compliance obligations.
- Homeowners:Individual purchasers responding to EPA Safer Choice program awareness and social media sustainability content, with strongest concentration in Portland, Seattle, and Austin metropolitan markets.
- Laundry Service Providers:B2B procurement teams at facility management companies negotiating volume contracts with performance guarantees and replacement scheduling.
- Environmental Organizations:Non-profit buyers sourcing certified products for educational campaigns and membership incentive programs.
- Hospitality Sector:Hotel and resort operators seeking operational differentiation through amenity program sustainability claims and guest-facing certification signage.
Homeowners generate the highest transaction frequency; Hospitality Sector procurement is climbing the fastest as ESG reporting requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Nepal's Kathmandu Valley and New Zealand's South Island concentrate wet-felting capacity for North American brands. These processing clusters attract investment through export-oriented manufacturing incentives and duty-free wool import protocols.
United States
Portland and Seattle metropolitan areas drive residential adoption through EPA Safer Choice program awareness and municipal sustainability procurement guidelines. The FTC Green Guides enforce substantiation standards for biodegradability claims, filtering marketing practices. Austin, Texas anchors commercial laundromat demand as facility operators adopt chemical-free protocols to reduce ventilation costs.
Germany
Bavarian and Baden-Württemberg households demonstrate disproportionate willingness-to-pay for certified Merino grades aligned with EU REACH compliance requirements. The ECHA chemical disclosure framework elevates certified wool products in European retail channels. Berlin-Brandenburg hosts third-party testing laboratories experiencing GOTS and OEKO-TEX audit backlogs extending product launch cycles.
Australia
New South Wales and Victoria wool stations supply sub-19 micron fiber specifications commanding premium positioning through softness perception. Drought cycles and Chinese import demand create auction price volatility compressing margin predictability. Melbourne-based logistics clusters coordinate bulk export to North American and European finished goods manufacturers.
Canada
British Columbia and Ontario direct-to-consumer channels capture multi-ball sets paired with essential oil refreshers through subscription commerce models exceeding category averages. Health Canada's PMRA regulates botanical extract safety in scented variants. Toronto metropolitan sustainability programs drive municipal procurement of certified biodegradable alternatives.
Nepal
Kathmandu Valley wet-felting artisan clusters face aging workforce challenges forcing training investments or mechanization trade-offs. Traditional expertise concentration creates single-source vulnerability for North American brands dependent on outsourced production. Pokhara sub-regional facilities expand capacity through development bank financing for export manufacturing.
Wool Dryer Ball Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: direct-to-consumer specialists controlling subscription channels, retail-dominant brands anchoring mass-market shelf placement, and artisan-positioned players targeting conscious luxury segments. Capacity expansion and geographic distribution partnerships constitute the dominant competitive moves as brands seek to reduce single-source production vulnerability.
Among direct-to-consumer specialists, Smart Sheep exemplifies channel control sustaining repeat purchase rates through replenishment model innovation. Woolzies occupies a position anchored in North American retail distribution dominance. Friendsheep Sustainable Goods represents the artisan-tier archetype through organic-certified Merino wool specialization. These three company structures illustrate the segmentation between scale-driven, retail-centric, and premium-certification positioning strategies.
| Leading Market Players |
|---|
| Smart Sheep |
| Woolzies |
| Friendsheep Sustainable Goods |
| LooHoo |
| Molly's Suds |
| Grove Co. |
| Nellie's |
| Handy Laundry |
| Whitmor |
| Others |
Pricing and Supply Chain Analysis
Australian wool auction prices transmit directly through to finished goods tiers, with sub-19 micron Merino fiber premiums compressing entry-level positioning while drought-driven volatility forces manufacturers toward multi-source procurement hedges.
Pricing Analysis
Margin tightening in the standard tier reflects Australian auction volatility and Nepalese labor rate adjustments. Three-tier pricing structure across premium Merino, standard wool blend, and economy synthetic-alternative levels stratifies the market. Certification grade and volume scale drive price differentiation, with GOTS-certified organic commands sustaining 40-60% premiums over conventional. Cost compression accelerates in the economy tier as silicone dryer ball substitutes capture price-sensitive first-time adopters. Commercial laundromat buyers exhibit lowest price sensitivity due to replacement cost amortization across high-rotation cycles, while residential first-time purchasers show highest elasticity.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given product durability, though scent refresher kit replenishment creates reverse logistics infrastructure for direct-to-consumer channels. Wet-felting capacity draws from Nepal, New Zealand, and emerging clusters in Vietnam, with Kathmandu Valley artisan workshops supplying 60-70% of North American brand volume. Raw material dependencies rest on Australian and New Zealand wool stations, Peruvian alpaca cooperatives, and botanical extract suppliers for core-scented variants. Single-source vulnerability concentrates in Nepalese felting expertise where aging artisan populations threaten capacity continuity. Distribution runs through direct-to-consumer subscription platforms, North American mass retail, and European specialty channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH compliance creates a structural moat for certified wool processors, elevating capital requirements and audit timelines that filter out opportunistic entrants.
For Market Incumbents: Anchor market position through backward integration into Australian wool station partnerships or captive Nepalese felting capacity investments. Certification depth in GOTS and OEKO-TEX tiers provides defensive differentiation against private-label mass retail entrants absorbing third-party testing costs. Channel control through direct-to-consumer subscription infrastructure locks in customer lifetime value beyond initial ball purchases. For New Entrants and Emerging Players: Moisture-sensing smart ball technology offers a technology-first wedge into the premium residential segment currently piloted in California and Oregon beta programs. Bavarian and Baden-Württemberg households in Germany present the most penetrable white-space geography given high sustainability index scores and limited incumbent brand awareness. Essential oil convergence partnerships with certified organic botanical extract suppliers provide a go-to-market angle bypassing raw material sourcing barriers. For Investors and Strategic Acquirers: GOTS audit backlog clearance rates are the leading indicator that certification-constrained supply will ease, enabling scaled new entrant production. The five-to-ten year viability window favors vertically integrated mid-cap specialists controlling both Australian wool procurement and Nepalese felting relationships. Monitor ECHA chemical disclosure framework expansion timelines for early signals of European market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wool Sourcing | Australian station partnerships insulate margin from auction volatility and Chinese demand swings. |
| Smart-Enabled Product Line Launch | Moisture-sensing cores shift consumer touchpoints from appliance manufacturers to accessory brands. |
| Essential Oil Convergence Partnership | Certified organic lavender and eucalyptus infusions extend customer lifetime through replenishment kits. |
| Direct-to-Consumer Channel Expansion | Subscription commerce models in Canada and Australia exceed category average penetration. |
| Commercial Laundromat Segment Penetration | California and Texas facility operators adopt chemical-free protocols to reduce ventilation infrastructure costs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across wool processing facility managers, retail category buyers, commercial laundromat operators, botanical extract suppliers, and sustainability certification auditors. EPA Safer Choice program documentation, EU REACH chemical disclosure frameworks, and Australian Wool Innovation auction reports provided regulatory and commodity price validation. Bottom-up demand modeling across household, commercial, and institutional segments triangulated against top-down market sizing from customs export volumes and retail channel audit data.
Granularity-level modeling operated at product type, material grade, application context, and end-user archetype dimensions across the analysis window. CAGRs derived from segment-level volume and value build-ups incorporating replacement cycle assumptions, subscription commerce penetration rates, and B2B procurement contract durations. Wool micron count premiums, felting labor cost trajectories, and essential oil input pricing fed industry-specific forecast sensitivity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Australian drought severity, Chinese import demand shifts, and Nepalese artisan workforce attrition. Practitioners should monitor GOTS audit clearance rates, REACH framework expansion proposals, and smart appliance manufacturer partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Australia Home Textiles Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Cotton Towel Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
Japan Home Textile Market
Home Textiles
UAE Home Textiles Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Bath Towel Market
Home Textiles
Towel Market
Home Textiles
Plush Blanket Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Turkey Home Textile Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Europe Home Textile Market
Home Textiles
China Home Textiles Market