
 Cotton Towel Market | 2026-2036
Cotton Towel Market Size, Share, and Industry Trends Forecast 2026-2036
Cotton Towel Market Analysis
REACH compliance is realigning the cost-of-entry calculus for European-bound cotton towel exports, forcing dyehouses and finishing mills to retrofit wastewater and chemical management systems. Sunvim Group Co., Ltd. leverages vertical integration across spinning, weaving, and finishing to absorb these compliance costs internally. Welspun India Ltd. anchors its competitiveness through large-scale terry-towel manufacturing in Gujarat with OEKO-TEX and GOTS certifications. Trident Group specializes in premium jacquard and dobby constructions for hospitality and retail private-label programs.
Cotton towels are woven or knitted textile products constructed from absorbent cotton fibers, typically with pile loops on one or both surfaces to maximize moisture retention; GSM ratings from 300 to 900 determine absorbency, durability, and end-use suitability across consumer and institutional applications. Bath towels dominate residential volume but face margin compression from private-label competition, while beach towels command premium positioning through heavier GSM constructions and specialized dyeing techniques. The hospitality segment within commercial usage concentrates procurement among certified suppliers capable of batch consistency and fire-retardant finishing, creating a bifurcation between commodity residential supply and specification-driven institutional sourcing.
EMA chemical safety standards, OEKO-TEX Standard 100 certification requirements, and the EU Green Deal's textile sustainability targets collectively restrict market access for undifferentiated producers while rewarding certified supply chains. India's BIS quality mandates and the country's PLI scheme for textiles are simultaneously upgrading domestic manufacturing standards and subsidizing capacity expansion in integrated towel production. Stakeholders must monitor how divergent regulatory timelines between European chemical restrictions and Indian production subsidies reshape competitive cost structures and sourcing geography.
Market Dynamics
REACH compliance and the EU Ecodesign for Sustainable Products Regulation are forcing dyehouses to retrofit wastewater systems, compressing margins for undifferentiated exporters while rewarding certified supply chains with preferred supplier status in hospitality procurement.
Growth Catalysts
- EU Ecodesign Regulation:Mandates certified organic and recycled cotton feedstocks for European market access, redirecting sourcing toward OEKO-TEX and GOTS-certified mills.
- Hospitality procurement consolidation:Branded hotel chains are tightening supplier qualification standards, concentrating orders among batch-consistent manufacturers with fire-retardant finishing capabilities.
- Integrated production clusters:Tamil Nadu and Gujarat spinning-weaving-finishing hubs are capturing expanded export volumes through captive chemical management and compliance infrastructure.
Market Restraints
- Raw cotton price volatility:Weather-driven supply fluctuations in major producing regions compress margin predictability for non-integrated towel manufacturers lacking backward integration into ginning operations.
- REACH chemical compliance costs:European-bound exporters face capital-intensive wastewater retrofitting and restricted substance testing, creating a cost-of-entry barrier that disadvantages small-scale dyehouses.
- Synthetic microfiber substitution:Polyester-blend beach and gym towels compete on price and quick-dry performance in price-sensitive consumer segments.
Strategic Opportunities
- India PLI textile subsidies:Production-linked incentive schemes subsidize capacity expansion in integrated towel manufacturing, lowering capital barriers for certified organic production lines.
- Healthcare institutional contracts:Antimicrobial-finished cotton towels for hospital and long-term care facilities represent an underpenetrated application with recurring procurement cycles.
- Direct-to-hospitality digital platforms:B2B marketplaces connecting certified mills with boutique hotel and vacation rental operators bypass traditional distributor markups.
Industry Challenges
- Certification timeline compression:OEKO-TEX and GOTS audit backlogs delay market entry for new production lines, straining working capital during qualification periods.
- Skilled jacquard programming shortage:Premium dobby and jacquard construction capabilities require specialized CAD/CAM technicians, constraining capacity expansion for complex hospitality designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotton Towel Market |
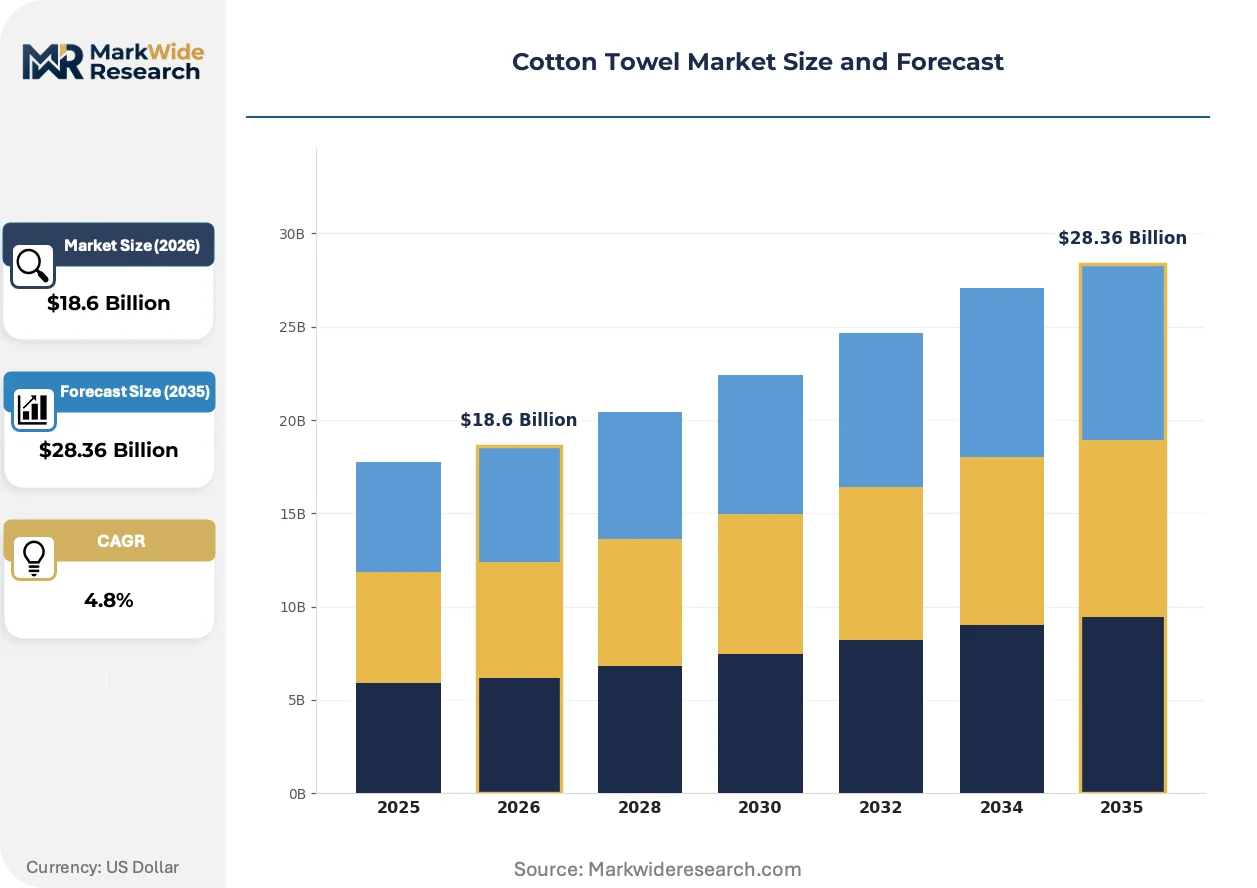
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $28.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bath Towels, Hand Towels, Beach Towels, Washcloths Usage: Residential, Commercial, Hospitality, Spa Weight: Lightweight, Medium, Heavyweight, Ultra-Heavyweight Finish Type: Plain, Jacquard, Velour, Combed |
| Companies Covered | Sunvim Group Co., Ltd., Monarch Brands, Welspun India Ltd., Boca Terry, Hede Textile, Trident Group, Loftex Australia, Guangzhou Bangze Textile, Springs Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotton Towel Market Emerging Trajectories
Digital traceability platforms and closed-loop recycling systems are restructuring how cotton towel supply chains demonstrate compliance and recover value from post-consumer textiles.
Blockchain-based fiber provenance tracking is consolidating audit and certification workflows into unified digital passports. Hospitality procurement teams at major hotel groups are mandating these traceability credentials for contract eligibility. The technology is consolidating previously fragmented documentation requirements into single-source verification, reducing administrative overhead for multi-certification compliance.
REACH substance restrictions are tightening allowable chemical residues in textile finishing, forcing dyehouses to reformulate softeners and dyes. The regulation is accelerating substitution of conventional quaternary ammonium compounds with bio-based alternatives. European-bound production lines are responding by segregating chemical inventories and installing closed-loop water recovery to prevent cross-contamination.
Certification-driven supplier preference is displacing price-only evaluation in institutional procurement. Hospital systems and hotel chains are consolidating vendor lists around mills with pre-validated OEKO-TEX and GOTS credentials, shortening qualification cycles. This concentration is most visible in Germany and Scandinavia, where public procurement guidelines mandate documented sustainability credentials for textile purchases.
Cotton Towel Market Segmentation
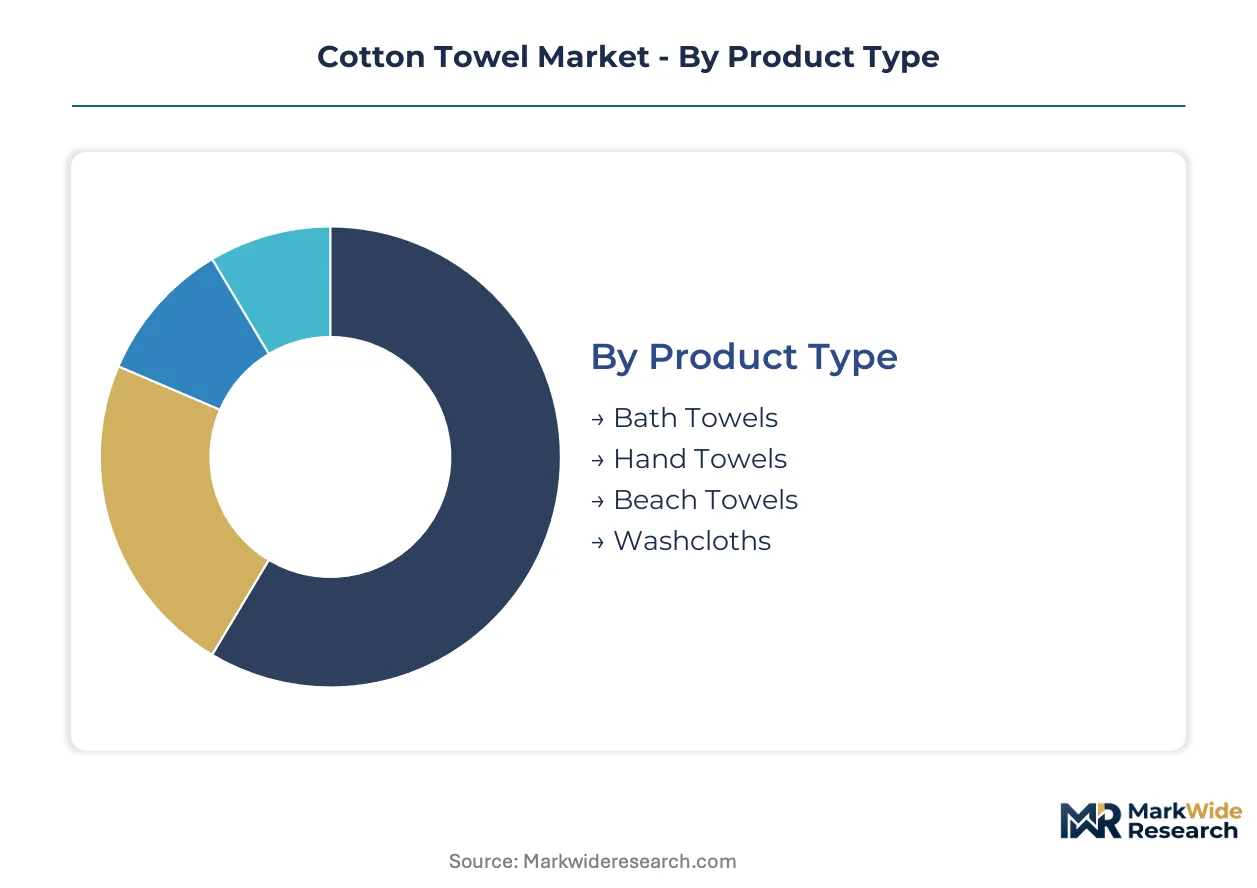
Cotton towel segmentation reveals how product specifications align with distinct procurement channels and end-use durability requirements. Technical differentiation across weight classes and finish types creates natural boundaries between commodity residential supply and specification-driven institutional contracts.
Product Type:
Standalone towel formats dominate residential replenishment cycles, while coordinated sets embed within hospitality linen programs through integrated procurement specifications.
- Bath Towels:Large-format terry construction with 400-700 GSM pile density absorbs maximum moisture for post-shower drying. Residential volume concentrates in India and Pakistan's export-oriented terry mills serving mass-market retailers, though margin compression from private-label competition limits brand differentiation.
- Hand Towels:Compact dimensions with reinforced selvedge edges withstand frequent laundering in high-traffic powder rooms. Hospitality procurement in Germany and Scandinavia mandates OEKO-TEX-certified hand towel sets as baseline contract eligibility, redirecting sourcing toward pre-validated Turkish and Indian suppliers.
- Beach Towels:Velour-finished or printed jacquard surfaces prioritize aesthetic differentiation over absorbency metrics.
- Washcloths:Small square formats with looped or flat-woven construction serve facial cleansing and infant care applications.
Volume placements concentrate in Bath Towels; the faster expansion belongs to Beach Towels.
Usage:
Cost tier stratification separates price-sensitive residential replenishment from premium commercial contracts with fire-retardant and antimicrobial finishing requirements.
- Residential:Mass-market replenishment through big-box retailers and e-commerce platforms prioritizes unit economics over technical specifications. Indian integrated manufacturers capture dominant share through captive ginning and spinning cost advantages.
- Commercial:Institutional procurement for healthcare, fitness, and industrial applications demands batch consistency and laundering durability. REACH compliance costs compress margins for non-integrated exporters serving European hospital systems.
- Hospitality:Branded hotel chains consolidate vendor lists around mills with validated fire-retardant finishing and jacquard programming capabilities. Tamil Nadu's integrated clusters capture expanded contract volumes through captive chemical management infrastructure.
- Spa:Premium positioning through Egyptian or Supima cotton content with specialized softener finishing commands wholesale price multiples over standard terry.
Volume placements concentrate in Residential; Hospitality climbs the fastest as procurement consolidation accelerates.
Weight:
Application durability requirements map directly to GSM specifications, with institutional buyers mandating heavyweight constructions for extended service life.
- Lightweight:300-400 GSM constructions serve gym, travel, and promotional applications where quick-dry performance outweighs plush hand feel. Polyester-cotton blends compete aggressively on price in this tier.
- Medium:400-600 GSM balances absorbency with laundering efficiency for standard residential bath towel programs.
- Heavyweight:600-800 GSM pile density delivers luxury hand feel and maximum moisture retention for premium hospitality and spa positioning.
- Ultra-Heavyweight:800+ GSM constructions with dense pile loops target luxury residential and boutique hospitality segments in Gulf markets.
Volume placements concentrate in Medium weight; Heavyweight gains share fastest as hospitality procurement upgrades specifications.
Finish Type:
Supply concentration in jacquard programming capabilities creates bottlenecks for complex hospitality designs requiring specialized CAD/CAM technicians.
- Plain:Basic terry loop construction without surface patterning dominates commodity volume through manufacturing simplicity and cost efficiency.
- Jacquard:Woven-in patterns and logos require specialized loom programming and extended setup times. Trident Group and similar specialists anchor competitiveness through dedicated jacquard capacity for hotel chain private-label programs.
- Velour:Sheared pile surface creates smooth printed substrates for beach towel and promotional applications.
- Combed:Pre-spinning fiber alignment removes short staples for enhanced softness and reduced pilling in premium positioning.
Volume placements concentrate in Plain finish; Jacquard shows the steepest expansion trajectory as hospitality branding requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates export manufacturing through integrated terry-towel clusters, while European procurement standards redirect sourcing toward certified supply chains. Hospitality and healthcare institutional demand in Germany and the United States tightens supplier qualification requirements. Regulatory divergence between REACH chemical restrictions and Indian production subsidies reshapes competitive geography.
India
Tamil Nadu and Gujarat spinning-weaving-finishing hubs capture expanded hospitality contract volumes through captive chemical management infrastructure. The country's PLI scheme for textiles subsidizes capacity expansion in integrated towel manufacturing, lowering capital barriers for certified organic production lines. BIS quality mandates upgrade domestic manufacturing standards while export-oriented mills secure OEKO-TEX and GOTS credentials for European market access.
Germany
Hospital systems and hotel chains consolidate vendor lists around mills with pre-validated sustainability credentials, shortening qualification cycles. Public procurement guidelines mandate documented sustainability credentials for textile purchases under EU Green Deal implementation. REACH substance restrictions tighten allowable chemical residues, forcing dyehouses serving German buyers to reformulate softeners and segregate chemical inventories.
United States
Branded hotel chains and healthcare systems tighten procurement standards, concentrating orders among batch-consistent manufacturers with fire-retardant finishing capabilities. FDA oversight of antimicrobial claims affects healthcare towel specifications, while EPA wastewater regulations influence domestic finishing operations. Direct-to-hospitality digital platforms connect certified mills with boutique hotel and vacation rental operators, bypassing traditional distributor markups.
Turkey
Pre-validated Turkish suppliers redirect sourcing from German and Scandinavian hospitality procurement as OEKO-TEX certification becomes baseline contract eligibility. The country's terry-towel manufacturing base leverages proximity to European markets with shorter lead times than Asian competitors. Izmir and Denizli industrial clusters maintain competitiveness through specialized jacquard programming capabilities for hotel chain private-label programs.
China
Sunvim Group and similar vertically integrated producers absorb REACH compliance costs internally through captive spinning, weaving, and finishing operations. MIIT industrial policy supports textile sector upgrading toward higher-value technical textiles and certified organic production lines. Shandong and Jiangsu manufacturing bases face margin pressure from Indian cost advantages while repositioning toward premium hospitality and spa segments.
Cotton Towel Market Vendor Landscape
Indian producers anchor the scale-driven tier; Turkish and Chinese specialists hold proximity and integration advantages respectively. The vendor base stratifies across certified institutional suppliers, commodity residential exporters, and premium hospitality specialists. Three archetypes dominate: vertically integrated terry-towel manufacturers with captive chemical management, certification-focused mid-scale mills serving European procurement, and jacquard programming specialists for branded hospitality programs. Competitive moves concentrate on capacity expansion in Indian integrated clusters and M&A activity consolidating European distribution networks.
Among India-based fabricators, Welspun India Ltd. and Trident Group occupy positions within the certified supply chain tier, with the former exemplifying large-scale terry-towel manufacturing and the latter representing specialized jacquard and dobby construction capabilities. Sunvim Group Co., Ltd. anchors the vertically integrated archetype, absorbing compliance costs through in-house production spanning spinning, weaving, and finishing operations. These three entities collectively illustrate how geographic concentration, certification credentials, and production integration define competitive positioning in institutional procurement channels.
| Leading Market Players |
|---|
| Sunvim Group Co., Ltd. |
| Monarch Brands |
| Welspun India Ltd. |
| Boca Terry |
| Hede Textile |
| Trident Group |
| Loftex Australia |
| Guangzhou Bangze Textile |
| Springs Global |
| Others |
Supply Flow & Price Mechanics
Blockchain-based fiber provenance tracking is compressing audit costs for certified mills while simultaneously concentrating procurement power among pre-validated suppliers with digital passport capabilities. This technology shift rewards integrated manufacturers in Tamil Nadu and Gujarat that have absorbed compliance infrastructure investments, widening the cost gap between certified institutional suppliers and undifferentiated commodity exporters.
Pricing Analysis
Volume placements concentrate in residential bath towels at economy-to-standard tiers, while hospitality procurement commands premium positioning through certification-bundled contracts. Price differentiation hinges on OEKO-TEX and GOTS certification tier plus fire-retardant finishing capability, with German and Scandinavian buyers least price-sensitive due to mandated sustainability credentials. Cost compression in economy residential tiers is intensifying because Indian integrated mills leverage PLI-subsidized capacity expansion.
Supply Chain Analysis
Direct-to-hospitality digital platforms bypass traditional distributor markups by connecting certified mills with boutique hotel operators. Geographic supply concentration centers on India, Turkey, and China, with raw cotton feedstock, specialized jacquard loom capacity, and REACH-compliant chemical inventories as critical inputs. Single-source vulnerability in skilled CAD/CAM programming for complex hospitality designs creates bottlenecks that constrain premium segment expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cotton towel market functions as a cost-of-compliance arena where REACH substance restrictions and EU Ecodesign mandates erect capital barriers that protect incumbent certified suppliers from commodity competition.
For Market Incumbents: Cement preferred supplier status with branded hotel chains by expanding captive fire-retardant finishing capacity in Tamil Nadu integrated clusters. Deepen backward integration into organic cotton ginning to absorb raw price volatility that threatens margin stability in standard-tier residential programs. For New Entrants and Emerging Players: The mid-tier pricing gap between OEKO-TEX-certified hospitality supply and undifferentiated economy residential production offers white-space entry through antimicrobial-finished healthcare institutional contracts. Target hospital systems in Germany with shorter qualification cycles than hotel chains, leveraging direct-to-facility digital platforms as the go-to-market channel. For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated terry-towel specialists with pre-validated certification credentials and captive chemical management infrastructure. Long-term viability favors acquisition targets with demonstrated batch consistency for institutional procurement and scalable jacquard programming capabilities; monitor OEKO-TEX audit backlog clearance rates as the inflection signal for qualification capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | REACH and EU Ecodesign compliance creates procurement moats for pre-audited mills serving German hospital systems. |
| Backward Integration into Organic Cotton | Captive ginning operations in Gujarat insulate margin stability from weather-driven raw cotton price swings. |
| Direct-to-Hospitality Digital Platform Launch | B2B marketplaces connecting Tamil Nadu mills with boutique hotels bypass traditional distributor markups. |
| Antimicrobial Finishing Capacity Addition | FDA-oversight-ready production lines unlock underpenetrated healthcare institutional recurring procurement cycles. |
| Jacquard Programming Specialist Acquisition | CAD/CAM technician teams constrain premium hospitality capacity; scarcity commands acquisition premiums. |
Methodological Framework
Multi-period observation of certification audit timelines, PLI subsidy disbursement patterns, and hospitality procurement consolidation trends anchored the trend analysis, supplemented by interviews with terry-towel plant managers, hotel linen procurement directors, chemical compliance officers at dyehouses, and distribution channel partners. Secondary validation drew from EU ECHA substance restriction updates, BIS quality mandate notifications, customs trade data for cotton towel exports, and SEC filings of listed textile manufacturers. Bottom-up capacity assessments across Tamil Nadu and Gujarat clusters were triangulated against top-down hospitality contract value estimates.
Input-output matrix modeling connected GSM specification tiers to end-use durability requirements and procurement channel economics across product type, usage, weight class, and finish complexity dimensions. CAGRs were derived from regression analysis of historical certification-driven supplier preference shifts and projected PLI-subsidized capacity expansion trajectories. Industry-specific forecast inputs included REACH substance restriction implementation timelines and OEKO-TEX audit queue clearance rates.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time hospitality contract award data introduce uncertainty bands around institutional segment projections. Forecasts reflect assumptions regarding sustained EU Ecodesign enforcement intensity and Indian subsidy program continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
United Kingdom Home Textile Market
Home Textiles
Europe Home Textile Market
Home Textiles
India Home Textile Market
Home Textiles
Japan Home Textile Market
Home Textiles
Linen Bed Sheets Market
Home Textiles
UAE Home Textiles Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
GCC Home Textile Market
Home Textiles
Textile Floorings Market
Home Textiles
Latin America Home Textiles Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Home Textiles Market