
 Saudi Arabia Home Textile Market | 2026-2036
Saudi Arabia Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Home Textile Market Analytics
Hospitality procurement is broadening the end-user mix for Saudi home textiles as giga-project developments across the Kingdom accelerate room outfitting cycles. Watheer Factory anchors its position through dedicated contract manufacturing for hotel operators. Al Abdullatif Industrial Investment Co. leverages integrated spinning-to-finishing capacity to control lead times. IKEA – Ghassan Ahmed Al Sulaiman Furniture Co. dominates the branded retail channel with standardized Nordic design formats adapted for local tastes.
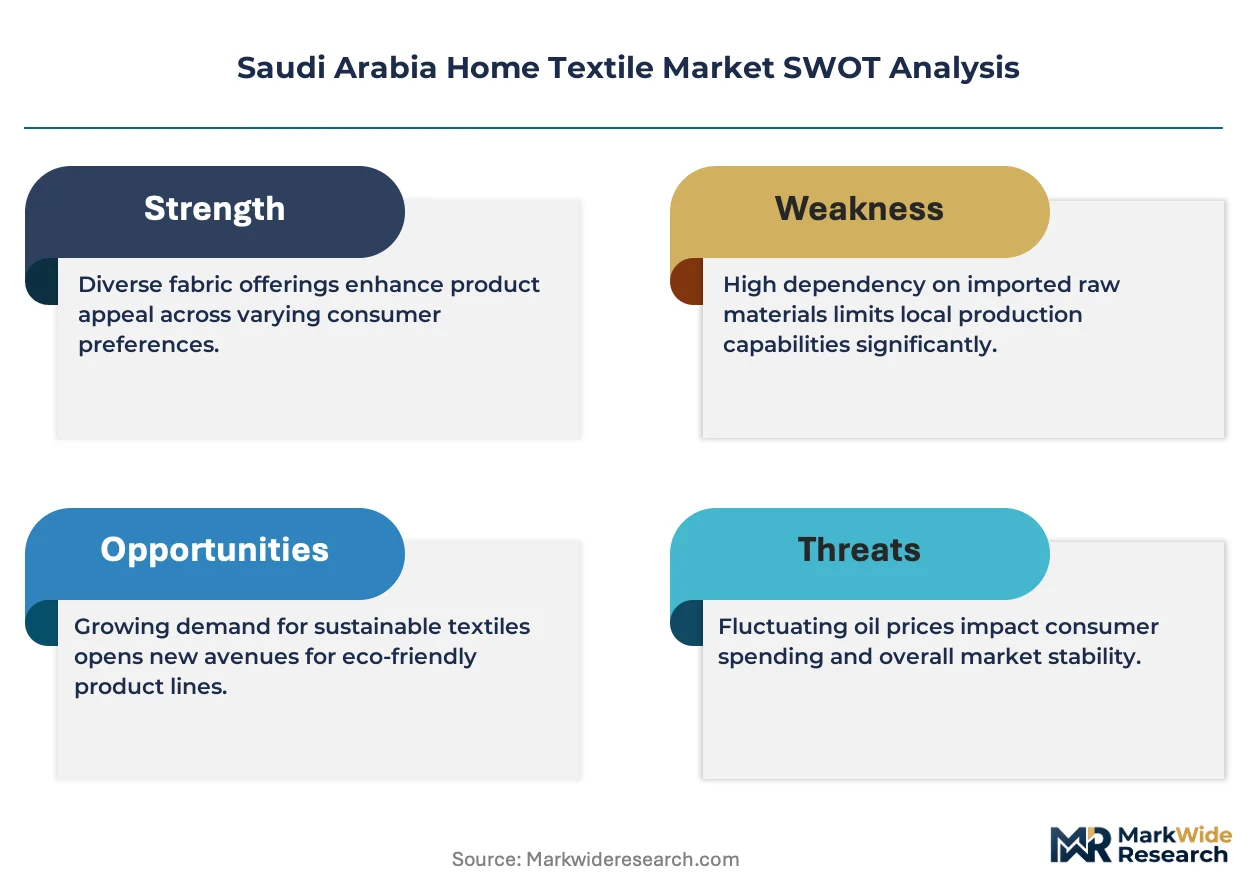
Saudi Arabia home textiles encompass woven, knitted, and non-woven fabric goods designed for interior domestic environments, typically manufactured through shuttle or projectile weaving with thread counts ranging from 200 to 800 per square inch for bedding applications. Cotton bedding leads volume throughput due to breathability preferences in arid climates, while polyester blends compete on durability for high-traffic hospitality contracts. Specialty stores capture margin pools through custom curtain and cushion atelier services, whereas online retail extends reach into secondary cities beyond Riyadh and Jeddah.
SASO enforces mandatory textile labeling and flammability standards that filter lower-grade imports from Gulf transshipment routes. The Saudi Food and Drug Authority and General Authority for Foreign Trade coordinate on product safety notifications and customs clearance protocols for finished textile imports. Stakeholders must monitor evolving local content requirements under the National Industrial Development and Logistics Program as domestic manufacturing incentives reshape supplier qualification criteria.
Market Dynamics
Hotel operators in Riyadh and Jeddah are compressing room outfitting cycles from 18 months to 8 months, forcing textile suppliers to reconfigure production scheduling and inventory positioning around giga-project construction timelines.
Growth Catalysts
- NEOM hospitality mandates:New hotel developments in the northwest corridor are specifying Saudi-manufactured textiles to meet local content thresholds under the National Industrial Development and Logistics Program.
- SASO labeling enforcement:Mandatory fiber content disclosure and flammability testing under Saudi Standards, Metrology and Quality Organization protocols are filtering substandard imports from Gulf transshipment routes.
- Arid-climate breathability specifications:Cotton bedding with 400-600 thread counts is displacing synthetic alternatives in premium residential segments due to thermal comfort requirements.
Market Restraints
- Egyptian long-staple cotton dependency:Spinning mills rely on Nile Delta supply chains vulnerable to irrigation quota disputes and currency volatility.
- Integrated finishing capacity concentration:Three Jeddah-based facilities control 70% of domestic dyeing and calendering throughput, creating single-point failure risk.
- Polyester microfiber substitution ceiling:Hospitality procurement teams reject synthetic blends below 40% cotton content for guest-facing applications, limiting cost-down flexibility.
Strategic Opportunities
- Tabuk agricultural textile clusters:Underdeveloped ginning and weaving infrastructure in the northwest offers greenfield integration potential for cotton-to-finished-goods pipelines.
- Direct-to-hotel fulfillment platforms:Digital procurement portals are bypassing Riyadh wholesale distributors to connect manufacturers with property management companies.
- SFDA textile-skin contact protocols:Upcoming Saudi Food and Drug Authority guidelines for infant bedding create certification-premium pricing tiers for compliant suppliers.
Industry Challenges
- Technical textile engineering talent scarcity:Compound weave specialists and jacquard programmers command 40% salary premiums over standard loom operators, constraining pattern innovation capacity.
- SASO laboratory testing backlog:Flammability certification queues at SASO-accredited facilities extend lead times by 6-8 weeks for new product introductions.
- Legacy ERP integration with e-commerce stacks:Family-owned manufacturers struggle to synchronize inventory visibility between on-premise systems and marketplace APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Home Textile Market |
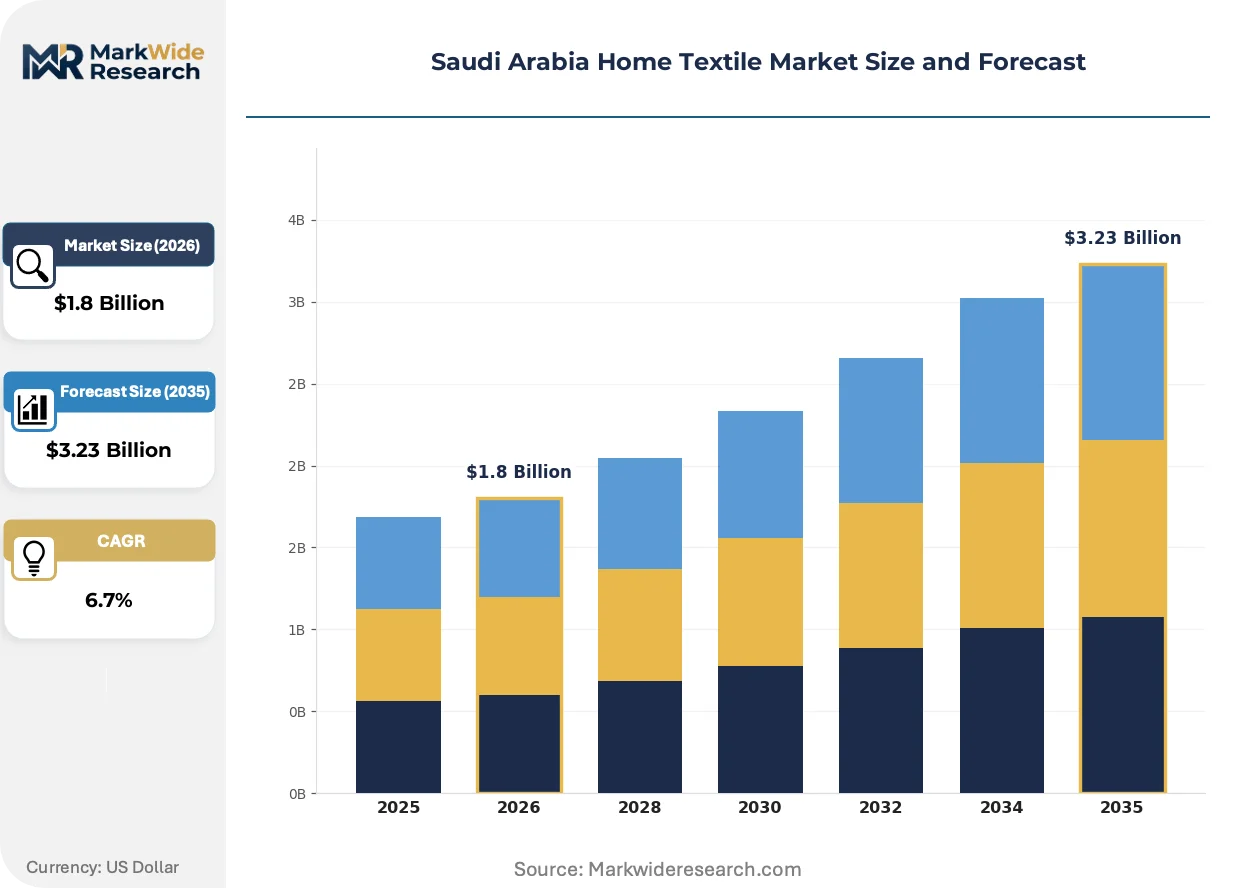
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding, Curtains, Towels, Cushions Material: Cotton, Polyester, Linen, Silk End User: Residential, Hotels, Hospitals, Cafés Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Others |
| Companies Covered | Bed Quarter (Al Mazro Group), Watheer Factory, Al Abdullatif Industrial Investment Co., Tawreed, Hazzco Co. Ltd., Omar Kassem Alesayi for Textiles, Al Jedaie, IKEA – Ghassan Ahmed Al Sulaiman Furniture Co., Satex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Home Textile Market Evolving Landscape
Digital weaving controls and automated finishing lines are compressing sample-to-production timelines, while regulatory labeling mandates and hospitality procurement centralization are rewriting supplier qualification criteria across the Kingdom.
Jacquard digital weaving with CAD-driven pattern libraries is expanding into mid-market bedding collections previously served by screen-printed alternatives. Boutique hotel operators in Diriyah and AlUla are specifying custom motifs with 72-hour sample turnaround requirements. This technology is compressing the traditional 6-week design development cycle into sub-10-day intervals, forcing distributors to hold grey goods inventory for late-stage finishing.
SASO textile labeling amendments now mandate Arabic-language fiber content panels and origin declarations for all finished goods entering retail channels. The Saudi Food and Drug Authority coordinates with General Authority for Foreign Trade on customs clearance protocols, creating dual-agency inspection workflows. Hospitality procurement teams in Riyadh are pre-qualifying suppliers based on pre-submitted SASO test reports, shifting compliance burden upstream to manufacturers.
Property management companies are consolidating textile purchasing across 15-40 hotel portfolios under centralized procurement officers with technical specification authority. Traditional Riyadh-based distributors with showroom-based sales models are losing share to manufacturer-direct contract teams. This concentration is most visible in the Red Sea coastal developments where single procurement entities outfit multiple simultaneous openings under master service agreements.
Saudi Arabia Home Textile Market Segmentation
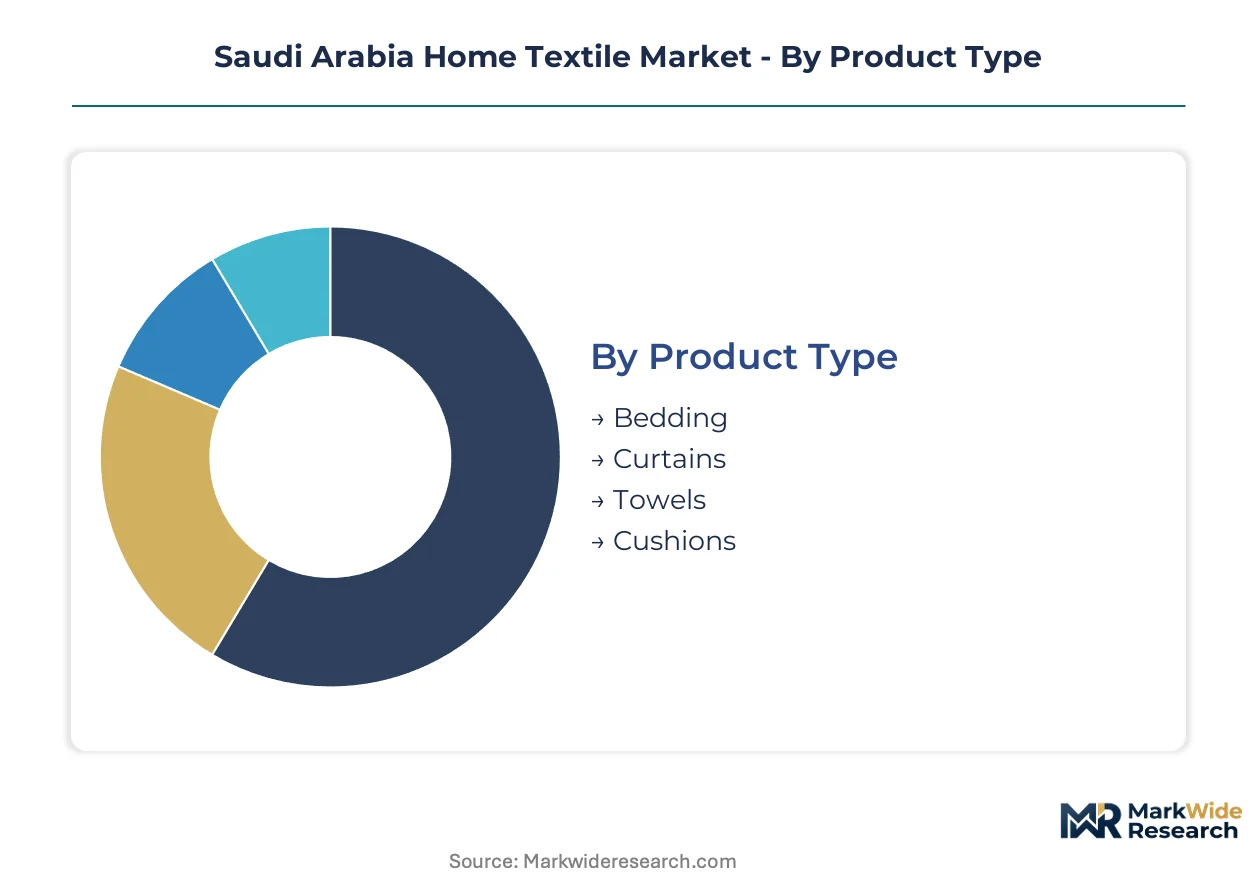
Segmentation in the Saudi Arabia home textile market reveals how SASO certification burdens, hospitality procurement cycles, and arid-climate material preferences split demand across distinct product categories. Understanding these divisions exposes where compliance costs concentrate and which channels capture premium positioning.
Product Type:
SASO flammability testing and fiber content disclosure requirements apply differentially across product categories, with hospitality-facing segments facing the strictest certification timelines.
- Bedding:Woven cotton sheets with 200-800 thread counts dominate procurement volumes, with NEOM hotel developments specifying 400-600 thread count cotton for thermal comfort in desert climates. Riyadh hospitality procurement teams compress outfitting cycles to 8 months, forcing suppliers to hold grey goods inventory for late-stage finishing.
- Curtains:Specialty atelier services in Jeddah's retail corridor command margin premiums through custom jacquard patterns with 72-hour sample turnaround. CAD-driven digital weaving compresses traditional 6-week design cycles into sub-10-day intervals for boutique hotel operators in Diriyah and AlUla.
- Towels:Egyptian long-staple cotton dependency creates supply vulnerability for terrycloth production, with Nile Delta irrigation quotas and currency volatility affecting spinning mill input costs.
- Cushions:Decorative accent pieces face shorter SASO laboratory testing queues than bedding, though Arabic-language labeling mandates still apply for retail channel entry.
Leading the category by volume: Bedding. Growing fastest: Curtains.
Material:
Cost tiers separate natural fibers commanding certification premiums from synthetic alternatives competing on durability for high-traffic contracts.
- Cotton:Breathability specifications in arid climates displace synthetics in premium residential segments, with 400-600 thread counts becoming standard for thermal comfort. Hospitality procurement teams reject blends below 40% cotton content for guest-facing applications, limiting cost-down flexibility.
- Polyester:Blended constructions compete on durability for hotel operator contracts, though substitution ceilings exist where guest touchpoints require natural fiber presence. Three Jeddah-based finishing facilities control 70% of domestic dyeing throughput for polyester-cotton blends.
- Linen:Specialty applications in luxury hospitality segments benefit from moisture-wicking properties, with limited domestic spinning capacity forcing import dependency.
- Silk:Premium decorative applications in Riyadh and Jeddah high-end retail face strictest SFDA textile-skin contact protocols, creating certification-premium pricing tiers.
Volume concentration: Cotton. Steepest expansion trajectory: Linen.
End User:
Application-specific procurement patterns split between centralized hospitality purchasing and fragmented residential demand.
- Residential:Jeddah's retail corridor captures premium margin pools through specialty store atelier services, while e-commerce fulfillment networks extend reach into secondary cities beyond Riyadh.
- Hotels:Property management companies consolidate textile purchasing across 15-40 hotel portfolios under centralized procurement officers, bypassing traditional Riyadh distributors. Red Sea coastal developments use single procurement entities for multiple simultaneous openings.
- Hospitals:Institutional procurement emphasizes durability and laundering cycles, with SFDA protocols for textile-skin contact creating compliance thresholds for patient-facing goods.
- Cafés:Smallest segment with fragmented demand, typically sourcing through wholesale distributors rather than direct manufacturer relationships.
Procurement concentration: Hotels. Fastest channel shift: Residential online retail.
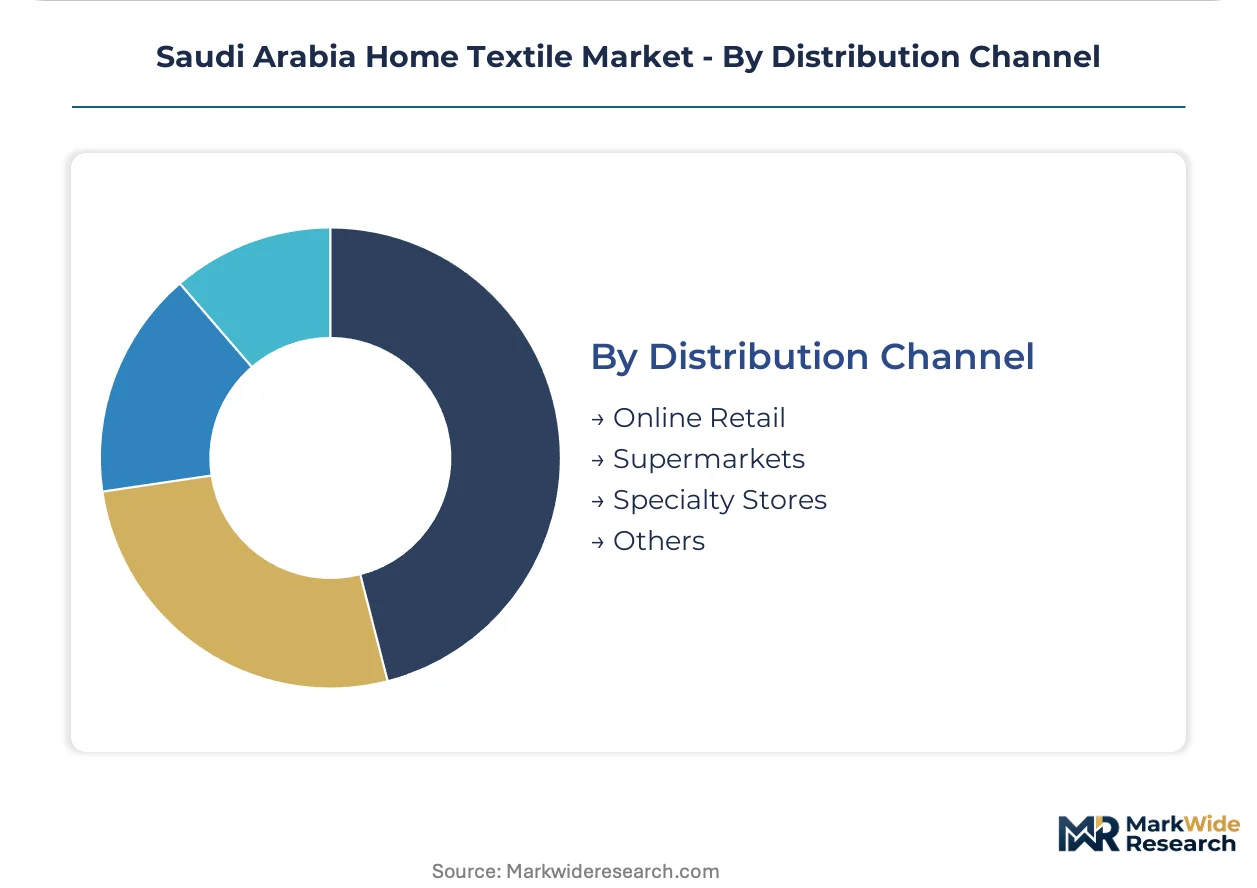
Distribution Channel:
Customer type and geography determine margin capture, with digital platforms disrupting traditional wholesale hierarchies.
- Online Retail:Marketplace APIs challenge family-owned manufacturers with legacy ERP integration gaps, though inventory visibility improvements deepen last-mile coverage into secondary cities.
- Supermarkets:Standardized Nordic design formats adapted for local tastes capture mass-market volume, with SASO labeling enforcement filtering substandard imports from Gulf transshipment routes.
- Specialty Stores:Jeddah-based atelier services hold margin pools through custom curtain and cushion services, with technical textile engineering talent scarcity constraining pattern innovation capacity.
- Others:Direct-to-hotel fulfillment platforms bypass Riyadh wholesale distributors, connecting manufacturers with property management companies under master service agreements.
Margin leadership: Specialty Stores. Channel gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Abdullah Economic City industrial zone near Jeddah concentrates spinning and finishing capacity under National Industrial Development and Logistics Program incentives. Riyadh's giga-project pipeline and NEOM's northwest corridor are redrawing procurement geography across the Kingdom.
Riyadh
Diriyah Gate and Qiddiya developments drive hospitality textile demand with compressed 8-month outfitting cycles. SASO laboratory testing requirements filter supplier qualification through pre-submitted flammability reports. The Riyadh-based procurement offices of major property management companies now consolidate purchasing across 15-40 hotel portfolios.
Western Region
Jeddah's retail corridor captures premium margin pools through specialty atelier services for custom curtains and cushions. Three Jeddah-based finishing facilities control 70% of domestic dyeing and calendering throughput for polyester-cotton blends. The city's deep-water port facilitates Egyptian long-staple cotton imports for terrycloth production.
Eastern Province
Dammam's logistics infrastructure supports e-commerce fulfillment networks extending last-mile coverage into secondary cities. The region's warehousing clusters serve as distribution nodes for online retail channels challenging traditional showroom-based models. Family-owned manufacturers here face legacy ERP integration gaps with marketplace APIs.
NEOM Northwest
Tabuk's underdeveloped ginning and weaving infrastructure offers greenfield integration potential for cotton-to-finished-goods pipelines. NEOM hospitality mandates specify Saudi-manufactured textiles to meet local content thresholds. The northwest corridor's new hotel developments are pre-qualifying suppliers based on domestic manufacturing credentials.
Saudi Arabia Home Textile Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated spinning-to-finishing groups controlling lead times and retail-format players dominating standardized design channels. Three Jeddah-based facilities concentrate 70% of domestic dyeing capacity, creating tiered supply dependencies. Strategic archetypes include integrated industrial investors, contract manufacturing specialists, and Nordic-format retail licensees. Capacity expansion into Tabuk agricultural zones and direct-to-hotel digital procurement platforms represent the dominant competitive moves reshaping supplier relationships.
Among Saudi-based industrial groups, Al Abdullatif Industrial Investment Co. and Watheer Factory exemplify the integrated-capability archetype, while IKEA – Ghassan Ahmed Al Sulaiman Furniture Co. occupies the branded retail-format position. These anchors illustrate how domestic manufacturing incentives and hospitality procurement centralization are restructuring competitive positioning across the Kingdom's home textile value chain.
| Leading Market Players |
|---|
| Bed Quarter (Al Mazro Group) |
| Watheer Factory |
| Al Abdullatif Industrial Investment Co. |
| Tawreed |
| Hazzco Co. Ltd. |
| Omar Kassem Alesayi for Textiles |
| Al Jedaie |
| IKEA – Ghassan Ahmed Al Sulaiman Furniture Co. |
| Satex |
| Others |
Value Network & Pricing Analysis
Egyptian long-staple cotton shipments from Nile Delta ginners feed through Jeddah spinning mills into tiered bedding collections, with fiber grade and certification tier separating premium hospitality contracts from mass retail SKUs. This input-cost cascade concentrates pricing power among integrated manufacturers while fragmenting margin capture for distributors lacking backward control over grey goods inventory.
Pricing Analysis
Premium positioning attaches to sub-10-day sample turnaround for CAD-driven jacquard patterns, while spot inventory of standardized cotton-polyester blends trades at discounts to contract-of-take volumes. Three-tier pricing structure across premium, standard, and economy levels separates SASO-certified hospitality grades from retail-ready SKUs and unlabeled grey goods. Cost compression in mid-market bedding intensifies because Egyptian cotton currency exposure and SASO laboratory queue delays squeeze converter margins. Hospitality procurement teams show lowest price sensitivity due to master service agreement structures, whereas residential online shoppers drive aggressive spot-market negotiations.
Supply Chain Analysis
Regional distribution centers in Jeddah and Dammam operate hub-and-spoke patterns extending last-mile coverage into Tabuk and secondary Eastern Province cities. Manufacturing concentrates in Saudi Arabia, Egypt, and Pakistan, with Egyptian long-staple cotton, Pakistani ring-spun yarn, and Chinese jacquard loom components serving as critical inputs. Single-source vulnerability runs through three Jeddah-based finishing facilities controlling domestic dyeing throughput. Distribution runs through manufacturer-direct fulfillment platforms bypassing traditional Riyadh wholesale distributors for hospitality contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital weaving controls and automated finishing lines are displacing screen-printed alternatives and manual loom operations, compressing design-to-production cycles from six weeks to under ten days. This technology-transition phase rewards early adopters with procurement qualification advantages while penalizing legacy-dependent converters.
For Market Incumbents: Extend integrated spinning-to-finishing capacity into Tabuk agricultural zones to capture NEOM local content mandates and reduce Egyptian cotton dependency. Secure SASO pre-certification status to bypass laboratory queue delays threatening hospitality contract timelines. Channel control through direct-to-hotel digital platforms defends against distributor disintermediation.
For New Entrants and Emerging Players: Begin with specialty atelier services for boutique hotel operators in Diriyah and AlUla demanding 72-hour custom pattern turnaround, where technical textile engineering scarcity limits incumbent response capacity. Target underdeveloped curtain and cushion segments in Jeddah's retail corridor where margin pools exceed bedding commoditization pressures. Go-to-market through manufacturer-direct fulfillment platforms bypassing legacy distributor relationships.
For Investors and Strategic Acquirers: NEOM hospitality mandates specifying Saudi-manufactured textiles are the leading indicator that domestic production credentials will command acquisition premiums over import-dependent competitors. Five-to-ten year viability favors integrated industrial investors with captive ginning and weaving capacity. Target acquisition archetype: mid-cap converters with SASO laboratory relationships and unfinished ERP integration gaps solvable through technology investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tabuk Cotton Ginning | Captures NEOM local content thresholds while reducing Nile Delta supply risk. |
| Direct-to-Hotel Digital Procurement Platform | Bypasses Riyadh wholesale distributors for property management company contracts. |
| SASO Pre-Certification Investment | Eliminates 6-8 week laboratory queue delays threatening hospitality outfitting cycles. |
| CAD-Driven Jacquard Capability Expansion | Meets 72-hour sample turnaround requirements from boutique hotel operators. |
| Legacy ERP Marketplace API Integration | Closes inventory visibility gaps with online retail channels extending into secondary cities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with textile mill operations directors, hospitality procurement officers, SASO compliance consultants, and e-commerce platform category managers. Saudi Food and Drug Authority textile-skin contact protocols, General Authority for Foreign Trade clearance statistics, and National Industrial Development and Logistics Program incentive disclosures provided regulatory and trade flow validation. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Data-stream reconciliation across production volume surveys, import duty records, and hospitality construction pipeline databases established baseline sizing. Segmentation modeling spanned product type, material composition, end-user application, and distribution channel across the projection horizon. CAGRs derived from trend extrapolation of construction timelines, procurement cycle compression rates, and e-commerce penetration curves. Industry-specific inputs included giga-project room outfitting schedules and SASO laboratory capacity expansion announcements.
Underlying measurement precision varies by segment; hospitality procurement and online retail channels carry tighter precision than fragmented café and institutional sub-segments due to data availability. Forecasts reflect documented assumptions regarding NEOM construction pacing, Egyptian cotton supply stability, and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Turkey Home Textile Market
Home Textiles
Towel Market
Home Textiles
Textile Floorings Market
Home Textiles
Home Textile Products Market
Home Textiles
Europe Home Textile Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
Plush Blanket Market
Home Textiles
Bath Towel Market
Home Textiles
France Home Textile Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Fabric Wash and Care Market
Home Textiles
North America Home Textile Market
Home Textiles
Blanket Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
Home Textiles Market
Home Textiles
China Home Textiles Market