
 United States Home Textile Market | 2026-2036
United States Home Textile Market Size, Share, and Industry Trends Forecast 2026-2036
United States Home Textile Market Analytics
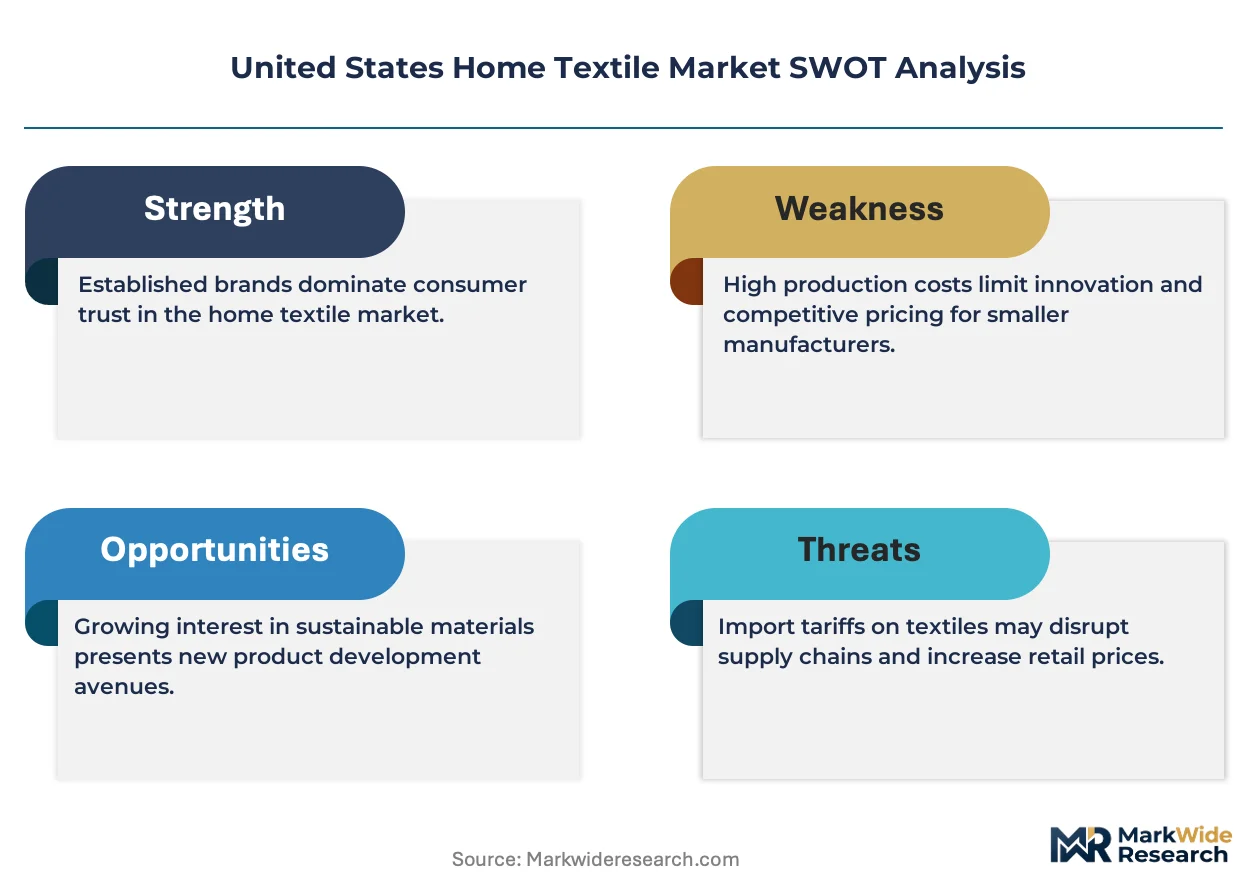
Asset-light leasing models for commercial linen is fragmenting competitive dynamics across the United States Home Textile Market. Standard Textile leverages hospital and hotel service contracts to sustain recurring revenue streams. Welspun Group anchors large-scale cotton bedding manufacturing with integrated spinning capacity. Ralph Lauren differentiates through brand-controlled distribution and premium positioning in department store channels.
United States home textiles encompass woven, knitted, and non-woven fabric goods designed for residential and institutional interior environments, typically specified by thread count, fiber denier, and finishing treatments such as mercerization or sanforization for dimensional stability. Bed linen commands the largest revenue pool among product type segments, while online retail distribution channels capture the fastest growth trajectory as direct-to-consumer fulfillment infrastructure matures. Cotton dominates material composition by volume, though polyester blends gain traction in institutional segments requiring industrial laundering durability.
The Federal Trade Commission enforces textile fiber labeling rules under the Textile Fiber Products Identification Act, while the Consumer Product Safety Commission governs flammability standards for mattresses and bedding. California's Proposition 65 chemical disclosure requirements add compliance layers for manufacturers distributing into that state. Stakeholders must monitor evolving state-level chemical restriction bills and their divergence from federal baselines.
Market Dynamics
Hospitality procurement teams are compressing linen replacement cycles while extending lease terms, creating bifurcated demand patterns that split capital expenditure from operational service relationships across the United States Home Textile Market.
Growth Catalysts
- California Proposition 65:Chemical disclosure mandates for home textiles sold in the state accelerate certified-organic fiber sourcing. Manufacturers reformulate finishing treatments to preempt litigation exposure.
- Hotel asset-light leasing:Commercial linen service contracts replace ownership models, generating recurring revenue streams for textile service operators. Hospitality chains outsource inventory management entirely.
- Thread count standardization:FTC enforcement of fiber labeling rules under the Textile Fiber Products Identification Act reduces consumer confusion. Verified claims support premium pricing for authentic high-count bedding.
Market Restraints
- Raw cotton price volatility:Weather-driven supply fluctuations from Texas and Georgia growing regions compress manufacturer margins. Hedging instruments add administrative cost without full protection.
- Polyester microfiber shedding:Technical limitations in filtration capture during industrial laundering create wastewater compliance liabilities. Municipal treatment facilities impose discharge surcharges.
- Prop 65 plaintiff bar activity:Private enforcement actions against bedding importers create settlement costs regardless of actual chemical exposure. Defense expenditures divert R&D budgets.
Strategic Opportunities
- Texas-Mexico nearshoring corridor:Cut-and-sew capacity expansion in Monterrey reduces transit times for US distribution. Integrated logistics hubs support just-in-time replenishment.
- Consumer Product Safety Commission flammability standards:Mandatory mattress and bedding testing creates certification service demand. Third-party laboratories capture recurring compliance revenue.
- Direct-to-consumer fulfillment infrastructure:Warehouse automation and last-mile density enable bypass of department store markup structures. Brand-controlled channels capture full retail margin.
Industry Challenges
- Industrial launderer skill gap:Equipment technicians proficient in heat-transfer finishing and pH-controlled washing command wage premiums. Training programs fail to match retirement outflows.
- Legacy ERP integration:Rental linen tracking systems require real-time inventory visibility across distributed hotel locations. Cloud migration timelines extend 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Home Textile Market |
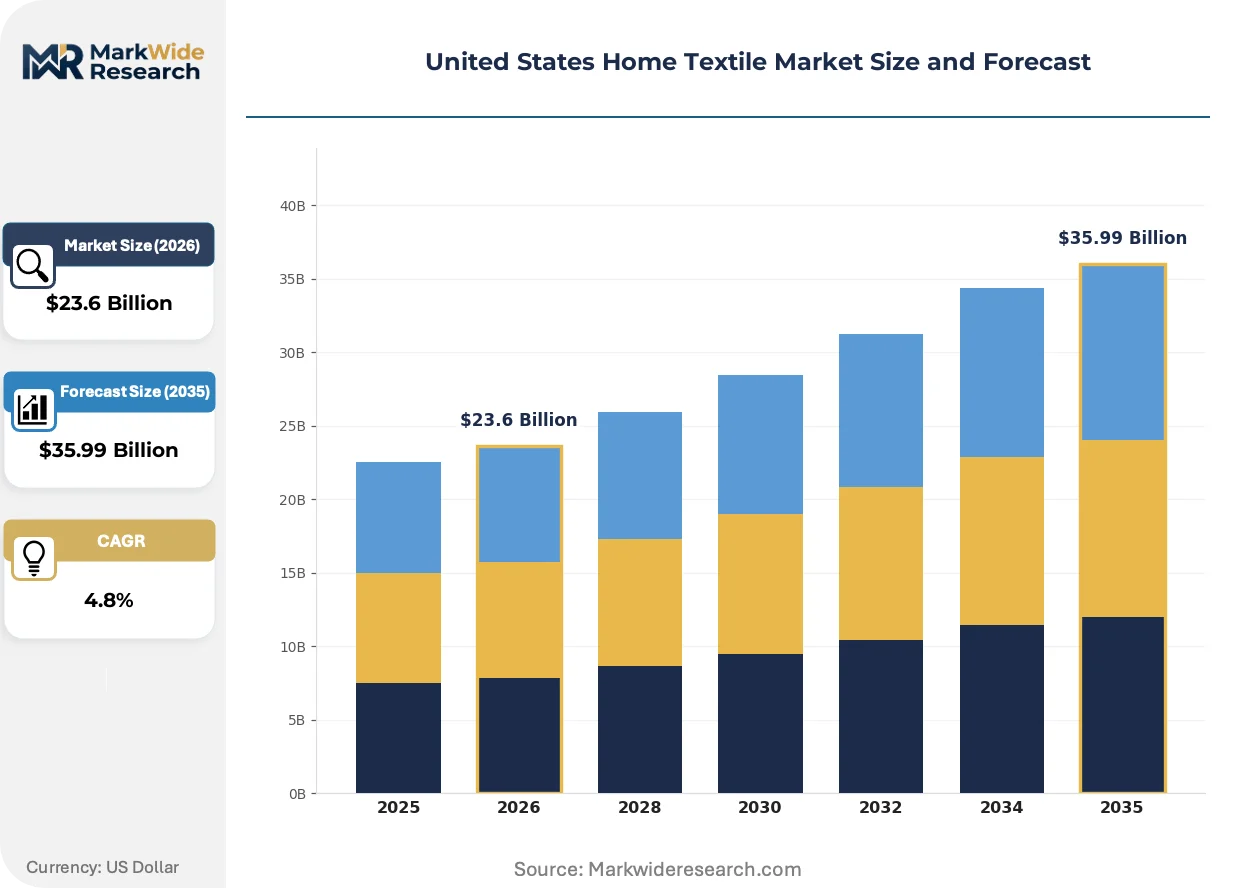
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $35.99 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Linen, Curtains, Towels, Tablecloths Material: Cotton, Polyester, Linen, Silk End User: Households, Hotels, Hospitals, Retail Stores Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Welspun Group, Ralph Lauren, Standard Textile, American Textile Company, Shaw Industries Group, Springs Global, Franco Manufacturing Company, Elevate Textiles, Milliken & Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Home Textile Market Evolving Landscape
Digital thread tracking and blockchain verification are penetrating fiber provenance documentation, while regulatory chemical restrictions and hospitality procurement restructuring reshape competitive requirements simultaneously.
Radio-frequency identification (RFID) tagging embedded in commercial linen is digitizing inventory reconciliation for hotel and hospital laundries. Housekeeping departments scan bulk loads rather than counting individual pieces. Chipped textiles enable automated par-level replenishment and loss detection, compressing working capital requirements for institutional buyers.
The Federal Trade Commission's Green Guides revision tightens environmental marketing claims for home textiles. Manufacturers must substantiate biodegradable, recyclable, and carbon-neutral assertions with third-party documentation. California retailers face the strictest enforcement exposure, driving statewide reformulation of product labels ahead of federal baseline requirements.
Buyers in the luxury residential segment now demand fiber-origin transparency exceeding regulatory minimums. Department store bedding departments stock certified-organic cotton SKUs alongside conventional alternatives. Southern California zip codes exhibit the highest concentration of traceability-premium purchases, with zip-code-level marketing targeting these households through regional digital channels.
United States Home Textile Market Segmentation
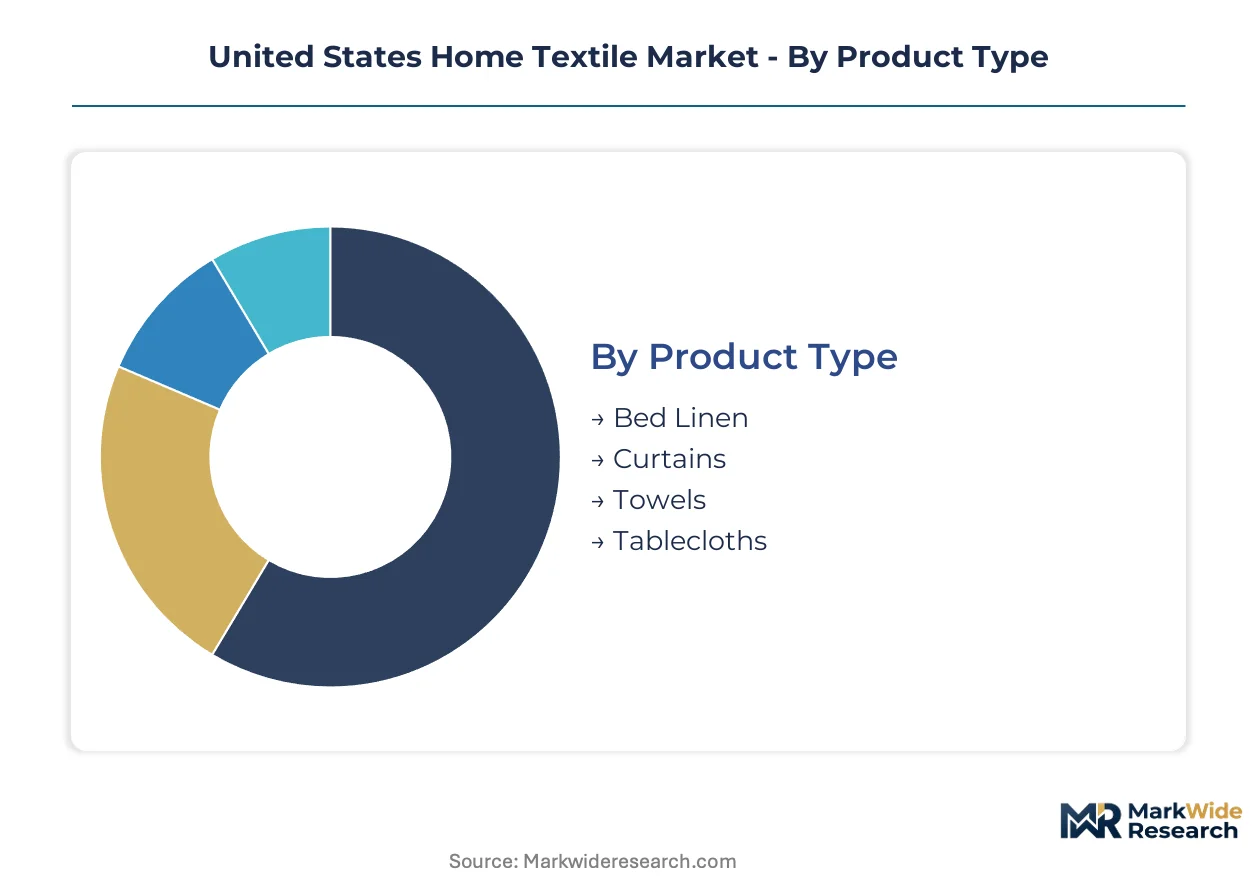
Segmentation in the United States Home Textile Market reveals distinct procurement patterns across residential and institutional buyers. Material specifications and distribution channel preferences diverge sharply between California luxury households and Texas-based hospitality operators.
Product Type:
Application context determines thread count requirements, finishing treatments, and replacement cycles across residential versus institutional environments.
- Bed Linen:Woven cotton percale and sateen constructions dominate, with thread counts ranging from 200 to 800. California's luxury residential corridor drives demand for certified-organic Egyptian cotton sheet sets. Hospital procurement teams specify industrial-launderable polyester-cotton blends for durability.
- Curtains:Window treatments incorporate blackout lining, thermal insulation layers, and flame-retardant finishes for commercial specifications. Texas hospitality developers source bulk quantities for new construction projects. Residential buyers prioritize aesthetic coordination with bedding collections.
- Towels:Terry cloth constructions specified by gram weight for absorbency performance.
- Tablecloths:Stain-resistant finishing treatments serve institutional food service requirements.
Bed linen holds installed capacity. Curtains are rotating up the share rankings.
Material:
Cost tier positioning and performance characteristics split procurement decisions between natural fiber premium positioning and synthetic durability.
- Cotton:Long-staple Pima and Egyptian varieties command premium pricing in department store channels. Texas and Georgia growing regions supply domestic spinning mills. Organic certification requirements under California Proposition 65 accelerate reformulation of finishing treatments.
- Polyester:Microfiber constructions deliver industrial laundering durability for hotel and hospital service contracts. Municipal wastewater discharge regulations constrain microfiber shedding during commercial washing cycles. Blended polyester-cotton fabrics balance cost and performance for mid-market retail.
- Linen:Belgian and French flax sourcing supports luxury positioning in specialty store channels.
- Silk:Mulberry silk pillowcases and duvet covers target premium beauty and wellness positioning.
Cotton holds installed capacity. Polyester is rotating up the share rankings.
End User:
Customer type dictates volume scale, specification complexity, and service relationship structure across the procurement lifecycle.
- Households:Direct-to-consumer fulfillment infrastructure enables bypass of traditional retail markups. Southern California zip codes exhibit concentrated demand for traceability-certified organic bedding. Online mattress-in-a-box brands bundle sheet sets with core product purchases.
- Hotels:Asset-light leasing models replace ownership, with commercial linen service operators managing inventory and replacement cycles. RFID-tagged textiles enable automated par-level replenishment across distributed properties. Marriott and Hilton procurement teams compress replacement cycles while extending lease terms.
- Hospitals:Infection control protocols mandate industrial laundering at elevated temperatures.
- Retail Stores:Department store bedding departments curate certified-organic SKUs alongside conventional alternatives.
Households hold installed capacity. Hotels are rotating up the share rankings.
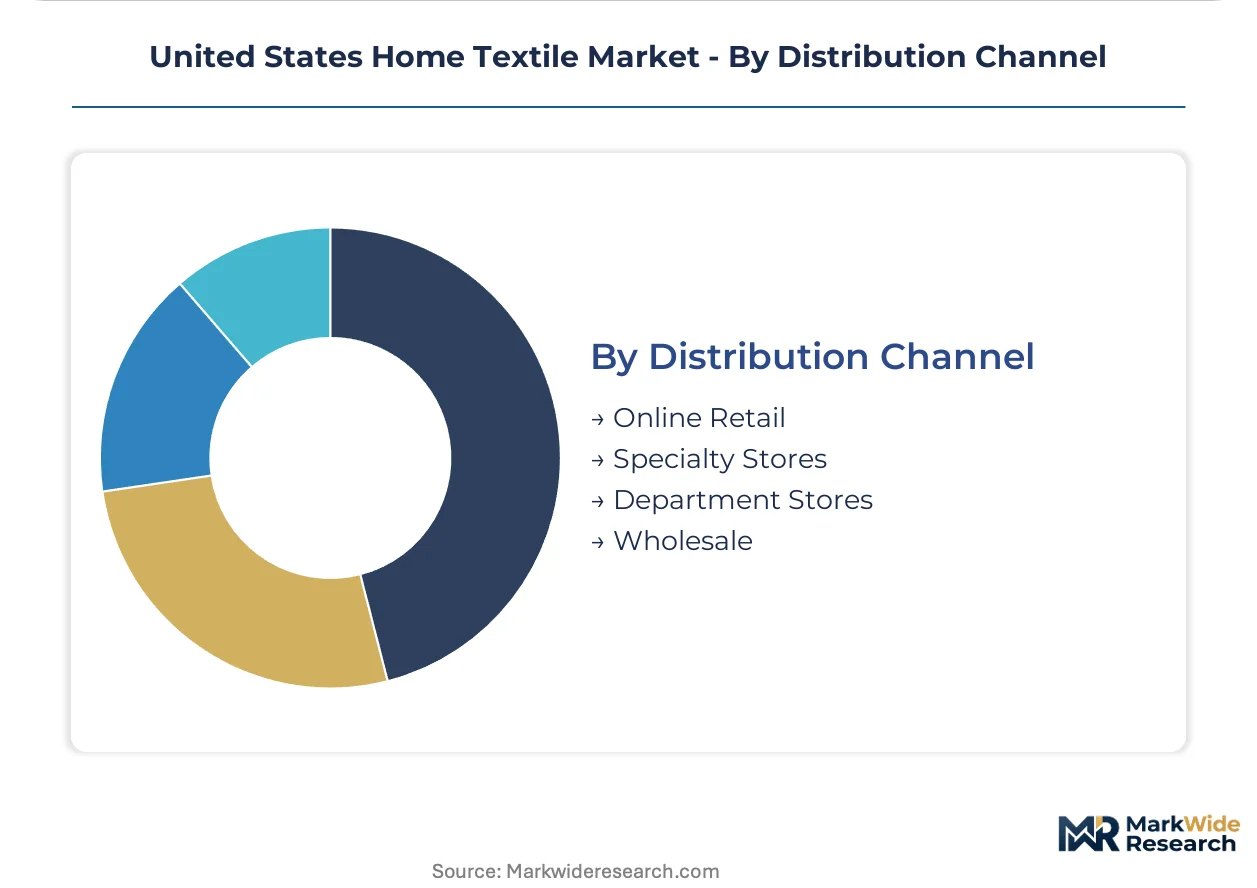
Distribution Channel:
Margin capture and customer relationship control separate brand-controlled channels from third-party retail dependency.
- Online Retail:Warehouse automation and last-mile density enable just-in-time replenishment. Ralph Lauren and Brooklinen operate direct-to-consumer platforms capturing full retail margin. California households drive highest per-capita spending through regional digital targeting.
- Specialty Stores:Curated assortments and design consultation services support premium positioning. Sleep-focused retailers bundle mattresses with coordinated textile collections.
- Department Stores:Macy's and Nordstrom bedding departments stock tiered price architectures across private label and national brands.
- Wholesale:Hospitality and healthcare procurement teams source through group purchasing organizations and contract textile distributors.
Department stores hold installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's luxury residential corridor while Texas hospitality procurement teams compress margins through volume aggregation. This geographic asymmetry shapes regional sourcing strategies across the United States Home Textile Market.
California
Certified-organic cotton sheet sets command premium positioning in Southern California zip codes with traceability-certified purchases. The state's Proposition 65 chemical disclosure mandates accelerate reformulation of finishing treatments among bedding importers. Los Angeles and San Francisco metropolitan areas anchor demand for Egyptian cotton varieties exceeding 600 thread count.
Texas
Hospital and hotel service contracts drive institutional-grade polyester-cotton blend procurement across Dallas-Fort Worth and Houston. The state's growing regions supply domestic spinning mills with weather-exposed cotton volumes. Austin hospitality developers source bulk curtain quantities for new construction projects.
New York Metro
Department store bedding departments in Manhattan and Brooklyn curate tiered price architectures across private label and national brands. The region's direct-to-consumer fulfillment infrastructure captures full retail margin through brand-controlled channels. New Jersey warehousing supports last-mile density into Connecticut and Pennsylvania.
Southeast
Georgia cotton growing regions supply fiber to domestic spinning operations serving institutional buyers. Florida hospitality chains outsource inventory management to commercial linen service operators. Atlanta distribution hubs enable just-in-time replenishment for Carolinas-based hotel developments.
Pacific Northwest
Seattle and Portland households exhibit elevated per-capita spending through regional digital targeting of organic bedding SKUs. The region's warehouse automation investments support bypass of traditional retail markup structures. Oregon-based sleep-focused retailers bundle mattresses with coordinated textile collections.
United States Home Textile Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The United States Home Textile Market structures around three distinct competitive tiers: integrated spinning-to-retail conglomerates, brand-controlled premium positioning specialists, and commercial linen service operators. Consolidation pressure concentrates among hospitality-facing segments while residential channels fragment across direct-to-consumer entrants. Dominant competitive moves include backward integration into cotton growing regions and strategic partnerships with industrial launderers.
Within the integrated manufacturing tier, Welspun Group anchors large-scale cotton bedding production with captive spinning capacity. Ralph Lauren occupies a position exemplifying brand-controlled distribution and premium department store channel positioning. Standard Textile represents the commercial service contract archetype, sustaining recurring revenue through hospital and hotel linen management relationships.
| Leading Market Players |
|---|
| Welspun Group |
| Ralph Lauren |
| Standard Textile |
| American Textile Company |
| Shaw Industries Group |
| Springs Global |
| Franco Manufacturing Company |
| Elevate Textiles |
| Milliken & Company |
| Others |
Value Network & Pricing Analysis
The Texas-Mexico nearshoring corridor's freight cost dynamics amplify pricing power for domestic spinning mills while compressing margins for importers dependent on Asian container routes. Supply concentration in Texas cotton growing regions and Monterrey cut-and-sew facilities enables configured-to-order premiums for hospitality buyers, whereas standard retail bedding faces cost-driven price compression from polyester blend alternatives.
Pricing Analysis
The customization-premium spread between configured-to-order hospitality contracts and standard retail SKUs reaches three-to-one multiples in California's luxury residential corridor. Three-tier pricing structure across premium Egyptian cotton, standard Pima blends, and economy polyester-cotton separates certified-organic certification grades from conventional finishing treatments. Pricing pressure stems from raw cotton price volatility in Texas and Georgia growing regions, compressing manufacturer margins without full hedge protection. Hospitality procurement teams exhibit lowest price sensitivity due to asset-light leasing models, while mass-market retail buyers demand volume-driven unit cost reductions.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities has become standard for hospitality linen service operators managing multi-property inventory pools. Geographic supply concentration centers on Texas cotton growing regions, Monterrey cut-and-sew capacity, and Georgia spinning mills serving institutional buyers. Raw material dependencies rest on long-staple Pima cotton, Egyptian cotton imports, and industrial-grade polyester fiber. Tariff exposure on finished bedding imports from South Asia creates single-source vulnerability for department store private labels. Distribution runs through direct-to-consumer fulfillment centers, commercial linen service depots, and wholesale group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable textile alternatives and rental furniture subscription models threaten permanent demand displacement for traditional home textile ownership. Incumbents must navigate substitution defense through service-layer transformation and circular economy positioning.
For Market Incumbents: Entrench recurring revenue relationships through RFID-enabled linen service contracts that embed inventory management into hospitality operational workflows. Backward integration into Texas cotton growing regions secures supply continuity against weather-driven price spikes. Certification investment in OEKO-TEX and GOTS standards defends premium positioning against direct-to-consumer entrants lacking traceability documentation.
For New Entrants and Emerging Players: Pursue white-space opportunity in Pacific Northwest organic bedding demand, where regional digital targeting enables customer acquisition below national brand media costs. Southern California zip codes offer concentrated traceability-premium households underserved by legacy department store distribution. Go-to-market through sleep-focused retailer partnerships bundles textile collections with mattress purchases, bypassing standalone customer acquisition economics.
For Investors and Strategic Acquirers: FTC Green Guides revision reshapes the acquisition landscape by elevating compliance infrastructure value for targets with substantiated environmental claims. Long-term viability favors commercial linen service operators with hospital and hotel contract backlogs over pure manufacturing assets exposed to raw material volatility. Monitor California Proposition 65 plaintiff bar activity as inflection indicator for litigation-driven consolidation pressure among bedding importers.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID Inventory Integration | Chipped textiles enable automated par-level replenishment for Marriott and Hilton procurement teams. |
| Organic Certification Investment | GOTS and OEKO-TEX credentials defend premium positioning against direct-to-consumer entrants. |
| Nearshoring Capacity Expansion | Monterrey cut-and-sew facilities reduce transit times for Texas hospitality developers. |
| Direct-to-Consumer Platform Launch | Warehouse automation captures full retail margin bypassing Macy's markup structures. |
| Commercial Service Contract Scaling | Asset-light leasing models replace ownership generating recurring revenue from hospital systems. |
Research Methodology
Operator-level perspectives from hospitality procurement directors, hospital linen service managers, department store bedding buyers, cotton spinning mill executives, and industrial laundering equipment technicians anchored the qualitative base. Primary interviews combined with secondary validation against FTC textile fiber labeling enforcement records, California Proposition 65 settlement databases, USDA cotton production statistics, and hospitality industry trade association procurement surveys. Bottom-up segment sizing across product types, materials, end users, and distribution channels triangulated with top-down market value reconstruction.
Scenario-bracketing around raw cotton price volatility bands and hospitality occupancy recovery trajectories bounded the projection range across the analysis window. Segmentation dimensions modeled include bed linen versus curtain versus towel product categories, cotton versus polyester versus linen material grades, household versus hotel versus hospital end users, and online retail versus department store versus specialty store distribution channels. CAGRs derived from historical replacement cycle compression rates and direct-to-consumer penetration curves. Forecast inputs incorporated hospitality asset-light leasing adoption rates and California chemical disclosure enforcement intensity.
Sensitivities concentrate around Texas drought frequency affecting domestic cotton supply, FTC Green Guides revision timing, and hospitality industry labor availability constraining linen service expansion. Forecasts reflect documented assumptions on replacement cycle duration and organic certification premium persistence. Macroeconomic recession triggering hospitality construction delays, regulatory divergence between federal and state chemical standards, or breakthroughs in biodegradable synthetic fibers would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Plush Blanket Market
Home Textiles
Global Theater Linen Market
Home Textiles
Germany Home Textile Market
Home Textiles
Linen Bed Sheets Market
Home Textiles
Textile Floorings Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Japan Home Textile Market
Home Textiles
UAE Home Textiles Market
Home Textiles
Turkey Home Textile Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
Russia Home Textile Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
North America Home Textile Market
Home Textiles
Cotton Towel Market
Home Textiles
France Home Textile Market