
 UAE Home Textiles Market | 2026-2036
UAE Home Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Home Textiles Market Analytics
The hospitality vertical is pivoting toward luxury-grade sustainable textiles as Dubai's hotel construction pipeline draws international procurement budgets. Pan Emirates Home Furnishings anchors its position through deep inventory breadth across curtain and bed linen categories. Home Centre leverages Landmark Group's mall footprint to control prime retail real estate. Ghazi Textile Trading specializes in wholesale volume supply to fit-out contractors serving institutional buyers.
Home textiles encompass woven, knitted, and non-woven fabric products designed for domestic interior environments, typically specified by thread count, GSM weight, and dye fastness ratings for residential and commercial end uses. Bed linen and towels command the largest volume share within product type segmentation, though curtains capture premium margin pools tied to custom sizing and installation services. Cotton dominates material demand for its breathability in the UAE's climate, while polyester blends compete on durability for high-traffic hospitality applications. The residential end user segment sustains baseline volume, but hospitality procurement cycles drive irregular demand spikes aligned with hotel opening timelines.
MOHAP enforces textile safety protocols for skin-contact products, while the Emirates Authority for Standardization and Metrology mandates fiber content labeling and flammability standards for curtains in commercial buildings. Dubai Municipality's green building regulations increasingly reference sustainable material sourcing, nudging suppliers toward certified organic cotton and recycled polyester portfolios. Stakeholders must monitor how evolving hospitality procurement criteria and tightening certification requirements reshape supplier qualification thresholds.
Market Dynamics
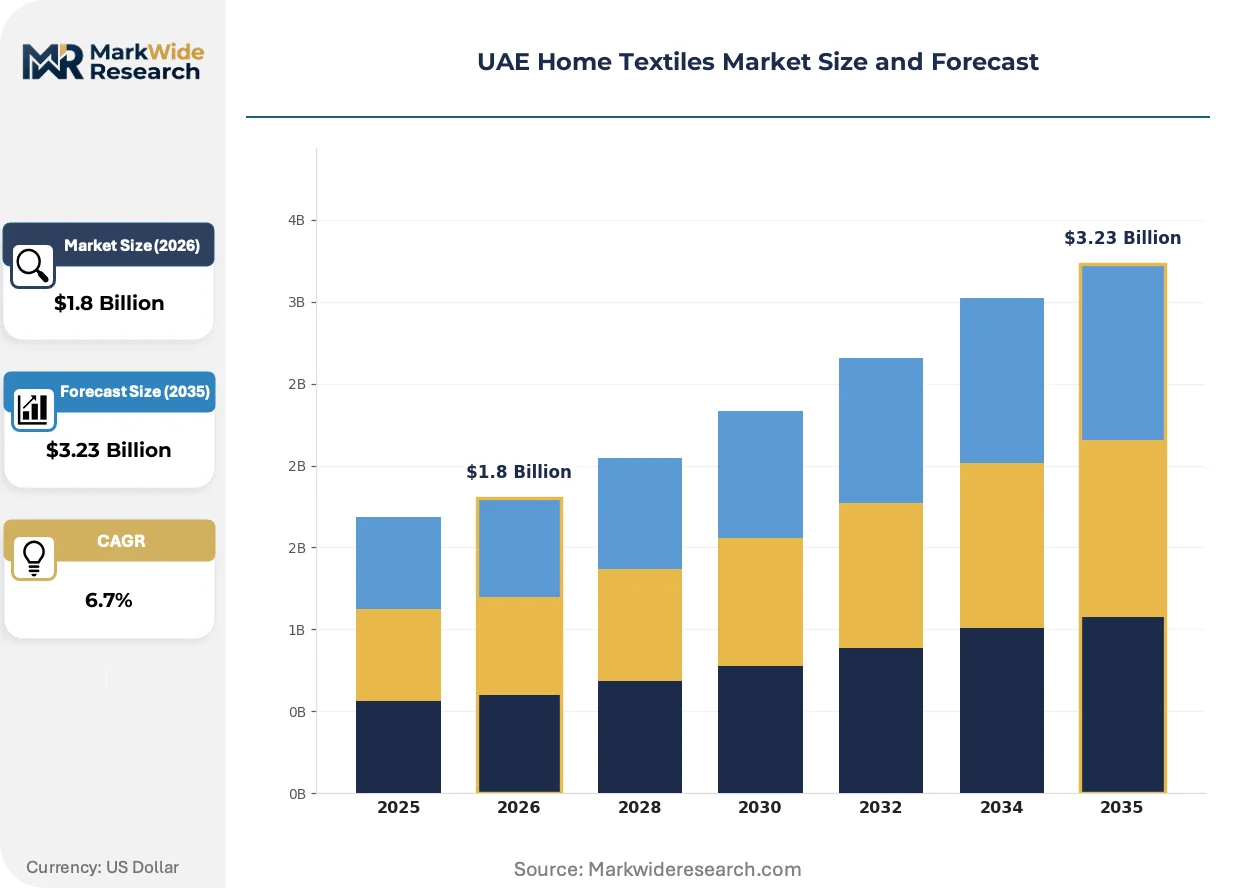
Hospitality procurement cycles are compressing supplier lead times as Dubai's hotel construction pipeline accelerates fit-out schedules. MOHAP textile safety protocols and Emirates Authority for Standardization and Metrology certification requirements are simultaneously tightening compliance thresholds for skin-contact products and commercial building materials.
Growth Catalysts
- Dubai hotel construction pipeline:New property openings are concentrating procurement budgets into premium linen and curtain specifications. Institutional buyers are consolidating vendor relationships to secure volume pricing.
- MOHAP textile safety standards:Mandatory skin-contact testing is filtering out low-grade imports. Certified suppliers are capturing shelf space in retail and hospitality channels.
- Recycled polyester fiber technology:Advanced mechanical recycling is closing the quality gap with virgin polyester. Hospitality laundries are specifying blends for durability under commercial wash cycles.
Market Restraints
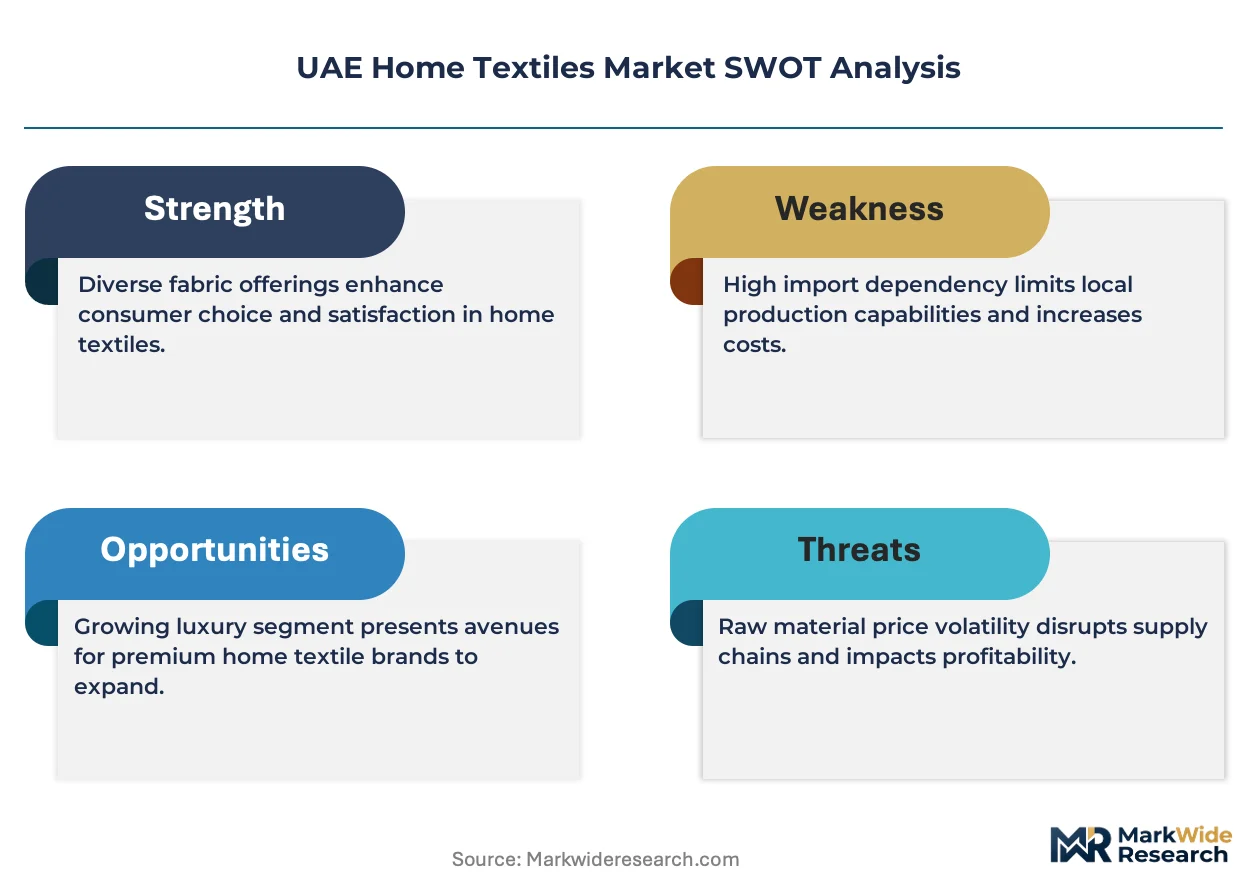
- Cotton price volatility:Raw fiber costs fluctuate with global harvest conditions and currency movements. Local weavers struggle to pass through input spikes to price-sensitive retail segments.
- Import concentration from South Asia:Bulk supply chains route through Karachi and Mumbai ports. Geopolitical disruptions or shipping bottlenecks cascade into inventory shortages.
- Flammability testing capacity:Limited accredited laboratories in the UAE create certification backlogs. Curtain suppliers face extended timelines for commercial building approvals.
Strategic Opportunities
- Abu Dhabi fit-out market:Government-backed cultural and hospitality projects are expanding procurement volumes. Early-entrant suppliers can anchor relationships before competitive saturation.
- Dubai Municipality green building regulations:Sustainable material mandates are creating preference for certified organic cotton and recycled fiber portfolios. Suppliers with existing certifications capture specification advantages.
- Direct-to-hospitality digital platforms:Procurement teams are bypassing traditional distributors for factory-direct relationships. B2B marketplaces are aggregating small-batch custom orders with faster turnaround.
Industry Challenges
- Dye fastness certification backlog:Commercial laundries require accelerated wash-cycle testing. Limited local testing infrastructure delays product launches.
- Legacy ERP integration:Family-owned trading houses operate on manual inventory systems. Digital procurement platforms face adoption friction among established wholesalers.
- Skilled textile merchandising talent:Technical specification translation between hospitality designers and manufacturing sources requires specialized knowledge. Recruitment pipelines from South Asian textile engineering programs are thin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Home Textiles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bed Linen, Curtains, Cushions, Towels Material: Cotton, Polyester, Silk, Linen End User: Residential, Hospitality, Retail, Institutional Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Pan Emirates Home Furnishings, Ghazi Textile Trading, Home Centre (Landmark Group), Pan Home, ABM Textile, IKEA, JYSK, Al Taqwa, Danube Home, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Home Textiles Market Evolving Landscape
Digital specification tools and sustainable fiber certifications are converging to reshape how hospitality buyers evaluate textile suppliers. Procurement teams now weight traceability documentation alongside traditional price and performance metrics.
Blockchain-based fiber traceability is unifying supply chain documentation from cotton gin to finished product. Dubai-based hospitality groups are piloting platform integration for ESG reporting compliance. This technology is compressing supplier qualification timelines by automating certificate verification.
Emirates Authority for Standardization and Metrology is expanding flammability testing protocols for blackout curtains in high-rise hospitality properties. Manufacturers must now submit samples to accredited laboratories before commercial installation permits. Curtain suppliers serving Dubai's hotel sector are restructuring product lines around pre-certified fabric libraries.
Specification-driven buying is displacing price-first procurement in premium hospitality segments. Design consultants are embedding textile performance requirements into early-stage fit-out briefs. This shift concentrates vendor selection power with architecture and interior design firms serving Dubai's luxury hotel developments.
UAE Home Textiles Market Segmentation
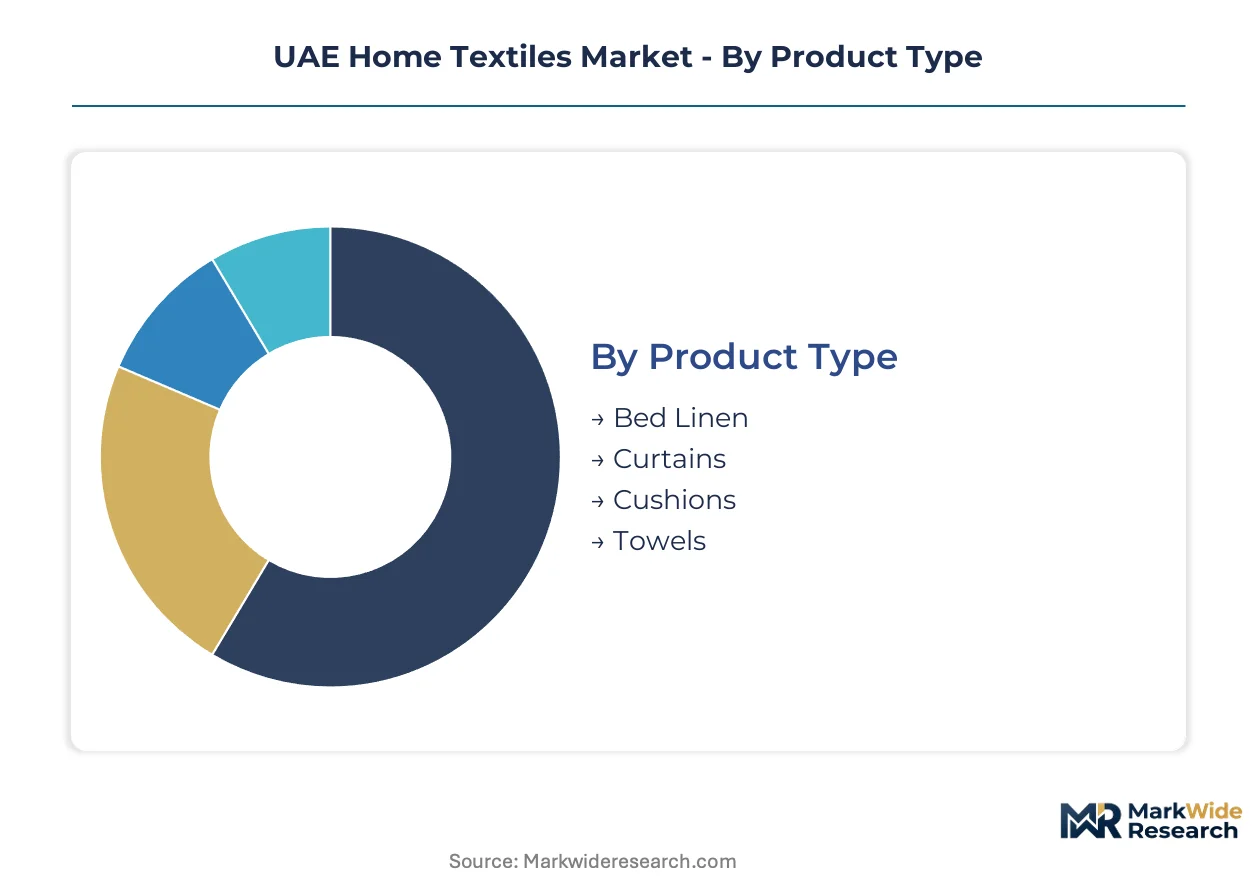
Segmentation reveals how procurement priorities diverge across Dubai's hospitality corridors and Abu Dhabi's institutional projects. Material specifications and distribution economics create distinct margin profiles that reshape supplier positioning.
Product Type:
Capital intensity concentrates in curtain manufacturing due to custom fabrication equipment and installation service infrastructure. Bed linen production scales through automated cutting and sewing lines with lower per-unit fixed costs.
- Bed Linen:Thread-count specifications range from 200 to 800 for hospitality-grade sheeting. Dubai's hotel fit-out pipeline concentrates procurement into bulk orders with dye-fastness certifications for commercial laundry cycles. MOHAP skin-contact testing mandates filter import competition.
- Curtains:Blackout and acoustic panels require specialized weaving looms and hardware integration. Emirates Authority for Standardization and Metrology flammability protocols for high-rise hospitality properties extend certification timelines and elevate supplier qualification barriers.
- Cushions:Decorative accent pieces with lower technical barriers attract fragmented local upholstery workshops.
- Towels:GSM weight ratings from 400 to 700 define hospitality versus retail tiers; bulk procurement flows through institutional distributors.
Most installed capacity flows through Bed Linen. Expansion is steepest in Curtains.
Material:
Raw material sourcing costs stratify supplier margins, with natural fibers commanding premium positioning against synthetic alternatives.
- Cotton:Egyptian and Pima long-staple varieties dominate luxury hospitality specifications for breathability in the UAE's climate. Dubai Municipality green building regulations increasingly reference certified organic cotton for sustainable procurement mandates.
- Polyester:Recycled fiber technology from mechanical recycling operations closes quality gaps with virgin feedstock. Hospitality laundries specify polyester-cotton blends for durability under industrial wash protocols.
- Silk:Ultra-premium residential and boutique hospitality applications; limited local weaving capacity drives import dependence.
- Linen:Belgian and French flax sources serve high-end residential segments; moisture-wicking properties suit the regional climate.
Cotton absorbs the largest procurement volumes. Recycled polyester is climbing the fastest.
End User:
Procurement scale and specification complexity separate institutional buyers from fragmented residential demand.
- Hospitality:Dubai's hotel construction pipeline concentrates fit-out budgets into premium linen and curtain specifications. International procurement teams consolidate vendor relationships for volume pricing and traceability documentation.
- Residential:Baseline volume sustains retail distribution through mall-based home furnishing chains and e-commerce platforms.
- Retail:Re-merchandising cycles and seasonal collections drive irregular replenishment patterns.
- Institutional:Healthcare and education facilities require MOHAP-certified skin-contact products with standardized durability ratings.
Hospitality commands the highest average order values. Institutional procurement is gaining share fastest.
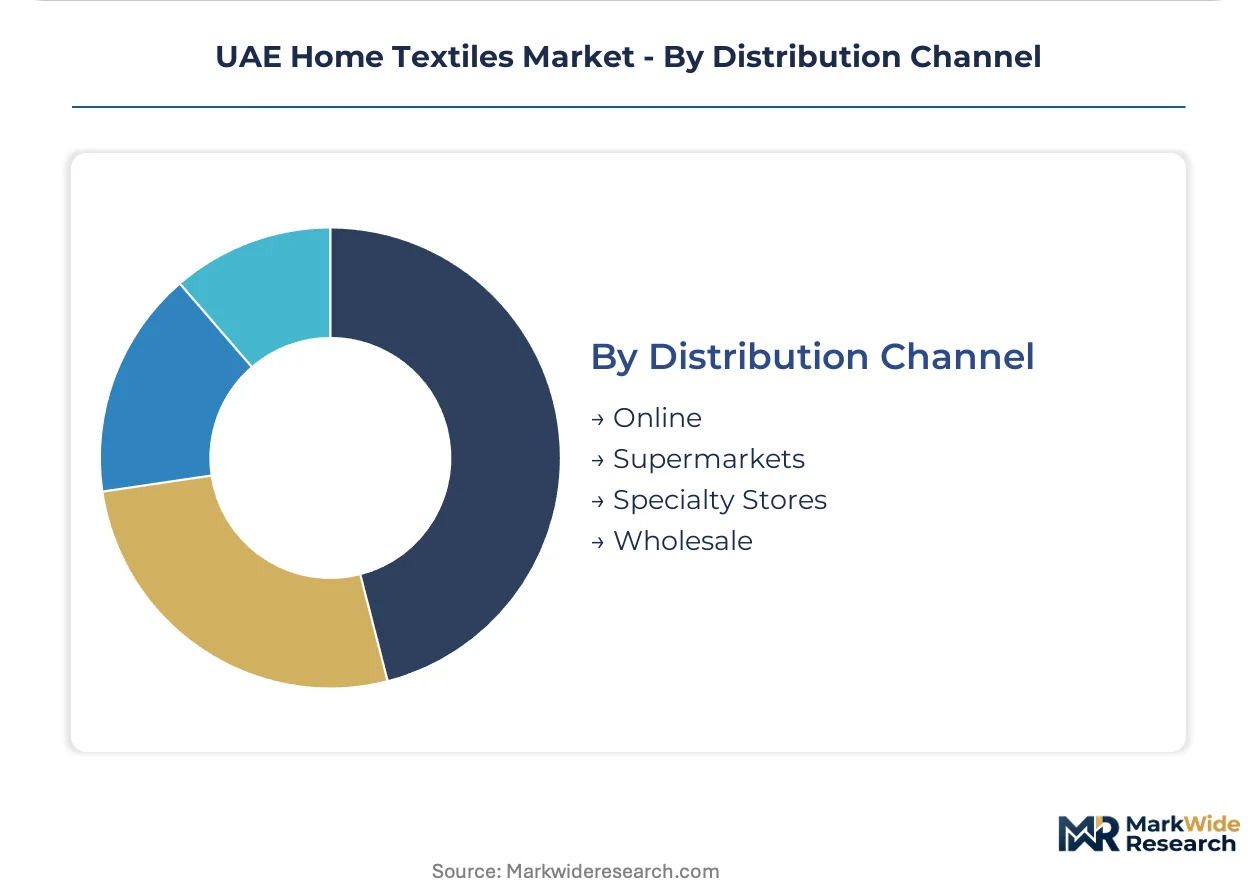
Distribution Channel:
Channel economics determine working capital intensity and customer acquisition costs across the value chain.
- Wholesale:Fit-out contractors serving Dubai's hotel developments source through trading houses in Deira and Al Quoz industrial zones. Volume discounts and extended payment terms anchor supplier relationships.
- Specialty Stores:Mall-based home furnishing retailers control prime real estate through Landmark Group and related conglomerate footprints.
- Online:Direct-to-consumer platforms and B2B marketplaces aggregate small-batch custom orders with compressed turnaround times.
- Supermarkets:Mass-market bed linen and towels through hypermarket chains serve price-sensitive residential replacement demand.
Wholesale channels handle the largest transaction values. Online penetration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's hospitality corridor anchors procurement volumes for premium linens and curtains as hotel fit-out cycles concentrate demand. Abu Dhabi follows with government-backed cultural projects expanding institutional absorption. Sharjah and the Northern Emirates serve secondary retail distribution roles.
Dubai
Dubai's hotel construction pipeline drives bulk procurement of thread-count certified bed linen and flammability-tested blackout curtains. Dubai Municipality green building regulations mandate sustainable material sourcing for new hospitality developments. The Al Quoz and Deira industrial zones cluster trading houses serving fit-out contractors with volume supply contracts.
Abu Dhabi
Abu Dhabi's cultural and government hospitality projects are expanding institutional procurement volumes beyond Dubai's shadow. Local fit-out specifications increasingly reference MOHAP textile safety protocols for skin-contact products. Saadiyat Island and Al Maryah Island developments concentrate premium linen demand for luxury property openings.
Sharjah
Sharjah's retail corridor serves price-sensitive residential replacement demand through mall-based home furnishing chains. The emirate's industrial zones host mid-tier weaving operations supplying domestic curtain fabricators. Sharjah's logistics connectivity to Dubai ports positions it as a secondary distribution hub for Northern Emirates coverage.
Ras Al Khaimah
Ras Al Khaimah's emerging hospitality developments on Al Marjan Island are creating new procurement nodes for resort-grade textiles. The emirate's lower operating costs attract warehousing operations serving UAE-wide retail replenishment. Local distributors are consolidating inventory positions to capture pre-opening hotel fit-out budgets.
Ajman and Umm Al Quwain
The Northern Emirates concentrate low-cost upholstery workshops and cushion manufacturing for mass-market retail channels. These emirates feed price-competitive product into UAE supermarket and hypermarket private label programs. Limited local testing infrastructure pushes suppliers to Dubai for MOHAP certification completion.
UAE Home Textiles Market Competitive Landscape
Portfolio diversification dominates the current landscape as trading houses expand from wholesale into direct retail and hospitality contracting. The vendor base stratifies across three tiers: mall-anchored retail conglomerates with prime real estate control, specialized wholesale traders serving institutional fit-out contractors, and mass-market furniture retailers with private label textile programs. Two competitive vectors define positioning: certification depth for hospitality compliance, and inventory breadth for retail assortment density.
Among UAE-based retail conglomerates, Pan Emirates Home Furnishings and Home Centre occupy positions defined by real estate footprint and category breadth. Ghazi Textile Trading represents the wholesale trading archetype, anchoring supply relationships with institutional fit-out contractors. These three entities exemplify how market position derives from channel control rather than manufacturing scale.
| Leading Market Players |
|---|
| Pan Emirates Home Furnishings |
| Ghazi Textile Trading |
| Home Centre (Landmark Group) |
| Pan Home |
| ABM Textile |
| IKEA |
| JYSK |
| Al Taqwa |
| Danube Home |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between MOHAP-tested hospitality linens and untested retail imports splits pricing power across supplier tiers, with premium-certified producers commanding extended payment terms while commodity traders absorb cotton volatility through thinner margins. This bifurcation concentrates procurement budgets toward Dubai's hotel fit-out corridor, where specification compliance overrides cost minimization.
Pricing Analysis
Input-cost pass-through from Egyptian and Pima cotton futures drives pricing volatility in luxury hospitality sheeting, while recycled polyester blends stabilize mid-tier quotations for institutional laundries. Three-tier pricing structure across premium, standard, and economy levels separates certified organic cotton from conventional blends and basic polyester imports. Pricing pressure stems from South Asian currency depreciation feeding cheaper substitute imports into retail channels. Hospitality procurement teams show lowest price sensitivity due to brand positioning requirements, whereas supermarket private-label buyers demand continuous cost-down.
Supply Chain Analysis
Raw cotton supply rests on Egyptian ginning operations, Indian spinning mills, and Pakistani weaving clusters, with finished goods routing through Karachi and Mumbai ports into Jebel Ali. Polyester fiber draws from Chinese petrochemical complexes and South Korean mechanical recycling facilities. Single-source vulnerability concentrates in long-staple Egyptian cotton, where climate shocks and Nile water policy disrupt harvest reliability. Distribution runs through Deira trading houses for wholesale hospitality contracts, with Landmark Group and related conglomerates controlling captive retail shelf space.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UAE home textiles hinges on certified sustainable fiber premiums replacing commodity cotton exposure, as Dubai Municipality green building mandates shift procurement specifications toward traceable organic and recycled inputs.
For Market Incumbents: Anchor certification depth against emerging digital-native competitors by accelerating MOHAP and Emirates Authority for Standardization and Metrology accreditation for curtain and bed linen portfolios. Invest in backward integration into Egyptian cotton sourcing partnerships to secure long-staple supply against harvest volatility. Defend Deira and Al Quoz trading house relationships by embedding inventory management systems into fit-out contractor workflows. For New Entrants and Emerging Players: B2B marketplace platforms targeting mid-size hospitality properties offer the most penetrable entry vector, bypassing entrenched wholesale relationships through factory-direct positioning and compressed custom-order turnaround. Focus initial penetration on Ras Al Khaimah's emerging resort corridor, where pre-opening procurement cycles lack incumbent vendor lock-in. Leverage blockchain traceability documentation as a specification wedge against legacy suppliers with opaque supply chains. For Investors and Strategic Acquirers: Consolidation pressure builds where family-owned trading houses face succession gaps and manual ERP systems block digital procurement integration. Target acquisition archetypes include mid-cap Deira wholesalers with established MOHAP certification and dormant e-commerce capabilities. Watch Dubai hotel construction pipeline announcements as volume inflection signals, with project financing closures preceding 18-24 month fit-out procurement windows.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | MOHAP and ESMA accreditations unlock hospitality procurement budgets and filter import competition. |
| Direct-to-Hospitality Digital Platform | B2B marketplaces aggregate fragmented custom orders and compress supplier qualification timelines. |
| Sustainable Fiber Sourcing Partnership | Certified organic cotton and recycled polyester contracts align with Dubai Municipality green building mandates. |
| Backward Integration into Egyptian Cotton | Long-staple ginning partnerships hedge against global harvest volatility and currency fluctuation. |
| Curtain Flammability Pre-Certification | Pre-tested fabric libraries accelerate commercial building approvals and capture high-rise hospitality specifications. |
Research Methodology
Coverage spans the UAE's seven emirates with primary inputs from each, combining structured interviews with hospitality procurement directors, fit-out contractor supply chain managers, retail category buyers, and textile testing laboratory accreditation leads. Secondary validation draws from Dubai Municipality building permit databases, Emirates Authority for Standardization and Metrology certification registries, customs import manifests through Jebel Ali and Khalifa ports, and hospitality development pipeline tracking. Bottom-up demand modeling triangulates against top-down spending allocation estimates from institutional buyers.
Granularity-level modeling disaggregates volume and value across product type, material composition, end-user segment, and distribution channel, with additional dimensioning by thread-count tier for bed linen and GSM weight classification for towels. CAGRs derive from fitted trend extrapolation adjusted for hotel opening timelines and regulatory implementation schedules. Key forecast inputs include Dubai hotel construction pipeline progression, MOHAP testing capacity expansion, and recycled polyester fiber quality advancement trajectories.
The model assumes a particular technology adoption path for blockchain-based fiber traceability; alternative pathways with slower platform integration would compress premium-tier pricing advantages. Forecasts reflect assumptions around sustained hospitality investment flows and stable South Asian supply chain connectivity. A small set of triggers warrants ongoing watch: Egyptian cotton harvest shocks, Emirates Authority for Standardization and Metrology protocol expansion, and geopolitical disruption at Karachi or Mumbai ports.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
India Home Textile Market
Home Textiles
Canada Home Textile Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
South Korea Home Textile Market
Home Textiles
Bath Towel Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
Saudi Arabia Home Textile Market
Home Textiles
Russia Home Textile Market
Home Textiles
France Home Textile Market
Home Textiles
Cotton Towel Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Mexico Home Textile Market
Home Textiles
Linen Bed Sheets Market