
 Blanket Market | 2026-2036
Blanket Market Size, Share, and Industry Trends Forecast 2026-2036
Blanket Market Analysis
OEKO-TEX Standard 100 certification is rotating as the primary gatekeeping qualification for suppliers seeking access to European and North American retail channels, forcing smaller mills to absorb testing costs or exit premium tiers. Pendleton Woolen Mills leverages its vertical wool operation from Oregon ranch partnerships to finished goods, sustaining price premiums against commodity imports. Shanghai Easun Group anchors volume production through integrated polyester fiber-to-fabric facilities, competing on cost for private-label hotel and hospital contracts.
A blanket is a layered textile covering engineered from woven, knitted, or non-woven substrates with specified thermal resistance measured in clo units, designed to modulate body heat retention through fiber loft, weave density, and surface treatment. Weighted blankets incorporate glass bead or plastic pellet filling at 5-12% of user body weight, functioning as therapeutic devices for anxiety and insomnia management in clinical and consumer settings. Polyester dominates material volume due to cost scalability and wash durability, while wool commands margin concentration in heritage and outdoor performance tiers. Electric blankets represent a regulated sub-segment where UL and IEC safety standards create barriers to entry, limiting competition to established appliance manufacturers.
The U.S. Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1610, while the EU's REACH regulation restricts azo dyes and flame retardant chemicals in textile finishing, elevating compliance costs for multi-market suppliers. China's GB 18401 national textile safety standard governs export-bound production from manufacturing clusters in Zhejiang and Jiangsu, shaping quality baselines for global supply. Stakeholders must monitor evolving chemical restriction lists and energy-efficiency labeling for heated products, as regulatory divergence between jurisdictions threatens to fragment sourcing strategies and inventory pooling.
Market Dynamics
The EU's Ecodesign for Sustainable Products Regulation is forcing blanket manufacturers to reconfigure material sourcing, with recycled polyester and organic cotton certifications now mandatory for European retail access.
Growth Catalysts
- REACH chemical restrictions:The EU's azo dye and flame retardant limitations are elevating compliance barriers that favor certified suppliers with established testing protocols.
- Weighted blanket therapeutic adoption:Hospital sleep therapy programs in the United States are expanding procurement of glass bead-filled blankets for anxiety and insomnia management.
- Heritage wool demand concentration:Premium wool blankets command sustained consumer loyalty through direct-to-channel growth and ranch-to-retail provenance marketing.
Market Restraints
- Polyester feedstock volatility:Crude oil price fluctuations directly compress margins for volume producers dependent on synthetic fiber inputs.
- Manufacturing cluster concentration:Zhejiang and Jiangsu provinces in China control the majority of export-bound production, creating single-point vulnerability.
- Electric blanket safety barriers:UL and IEC certification requirements limit heated blanket competition to established appliance manufacturers with testing infrastructure.
Strategic Opportunities
- Hospital contract expansion:North American healthcare systems are formalizing blanket procurement for patient comfort programs and pressure ulcer prevention.
- Dual carbon alignment:China's national carbon neutrality targets are incentivizing renewable energy adoption in textile manufacturing clusters.
- Therapeutic device classification:Weighted blankets are migrating from consumer goods to reimbursable medical equipment in select jurisdictions.
Industry Challenges
- OEKO-TEX testing cost absorption:Smaller mills face capital strain from certification fees required for European and North American retail channel access.
- Multi-jurisdiction compliance fragmentation:Divergent chemical restriction lists between the US Consumer Product Safety Commission, EU REACH, and China's GB 18401 standards complicate inventory pooling strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blanket Market |
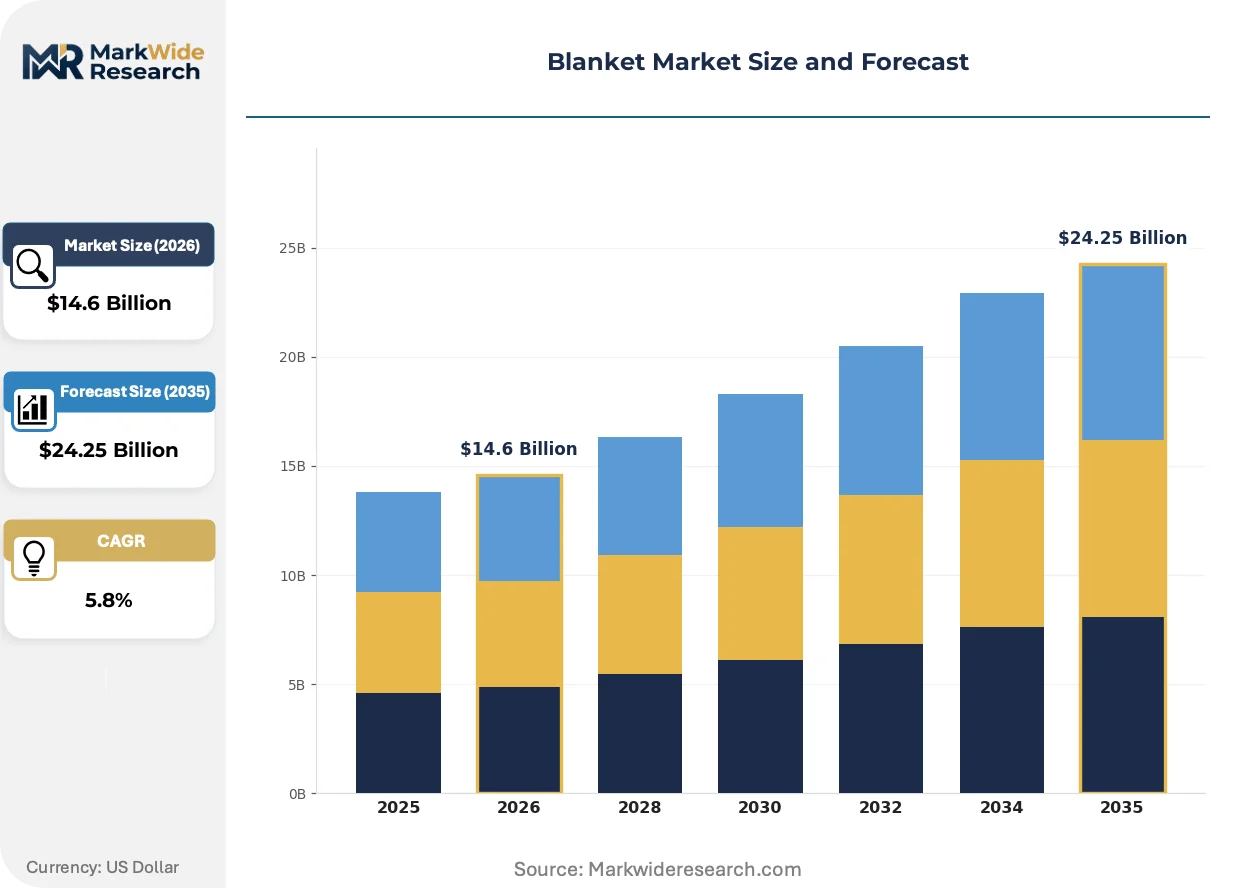
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $24.25 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Blankets, Weighted Blankets, Fleece Blankets, Travel Blankets Material: Cotton, Polyester, Wool, Acrylic End User: Households, Hotels, Hospitals, Outdoor Enthusiasts Usage Occasion: Winter, Camping, Travel, Home Décor |
| Companies Covered | Pendleton Woolen Mills, American Blanket Company, Faribault Woolen Mill Co., Hudson's Bay Company, Boll & Branch, Shanghai Easun Group, Jarden Corporation, Biddeford Blankets, Chellco Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blanket Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning across premium and volume tiers simultaneously.
Phase-change material microencapsulation is decomposing traditional thermal resistance engineering. Outdoor performance brands are adopting paraffin-wax-infused fibers for active temperature modulation. This technology is decomposing the historical trade-off between insulation weight and breathability that defined wool-polyester competition.
REACH Annex XVII updates on per- and polyfluoroalkyl substances are accelerating fluorocarbon-free water repellent development. Finish houses are reformulating durable water repellent chemistries to maintain performance without restricted compounds. The outdoor and hospitality segments are absorbing reformulation costs fastest to maintain EU market access.
Certification-driven sourcing decisions are compressing supplier qualification timelines. Retail buyers are consolidating vendor lists around pre-certified mills rather than managing parallel testing programs. This pattern concentrates procurement volume most visibly in German and French retail channels where OEKO-TEX Standard 100 has achieved de facto mandatory status.
Blanket Market Segmentation
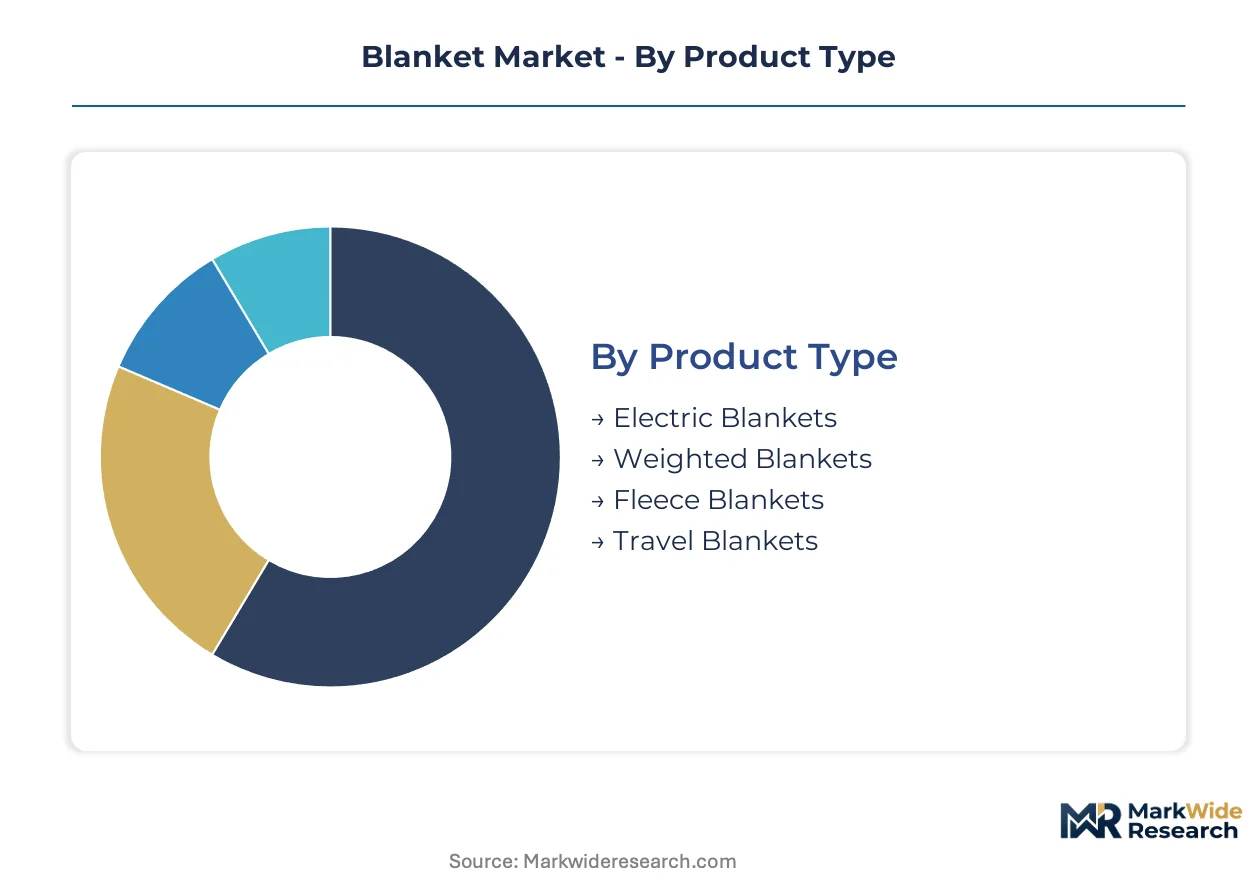
Blanket procurement decisions split across thermal performance specifications, safety certifications, and end-use durability requirements. Segmentation reveals how regulatory chemistry restrictions and institutional purchasing criteria reshape competitive positioning across material and product categories.
Product Type:
UL and IEC safety standards fragment competitive access, with appliance-grade certification requirements filtering manufacturer participation differently across heated versus non-heated categories.
- Electric Blankets:Resistive heating elements embedded between woven substrates require third-party electrical safety validation under UL 964 and IEC 60335-2-17 standards. Hospital procurement in the United States and Germany concentrates demand among established appliance manufacturers with captive testing infrastructure, while retail channels in France and Italy enforce additional energy-efficiency labeling.
- Weighted Blankets:Glass bead or plastic pellet filling at calibrated pressure levels functions as therapeutic equipment for anxiety and insomnia management. Clinical reimbursement pathways in select US states and Canadian provinces are expanding hospital and long-term care facility procurement beyond direct-to-consumer channels.
- Fleece Blankets:Brushed polyester knit structures deliver warmth-to-weight ratios suited for institutional bulk purchasing and hospitality replenishment cycles.
- Travel Blankets:Compressible woven or non-woven formats prioritize packability for airline amenity programs and outdoor retail channels.
Established volume favors fleece blankets for hospitality and institutional replenishment; emerging adoption favors weighted blankets crossing into reimbursable medical equipment classification.
Material:
REACH Annex XVII restrictions on azo dyes and flame retardant chemistry elevate compliance costs unevenly across natural and synthetic fiber supply chains.
- Cotton:Cellulosic staple fiber requiring pesticide residue testing and organic certification for EU retail access. Egyptian and Pima long-staple varieties command premium positioning in US direct-to-consumer channels, while standard upland cotton serves mass-market private label programs through South Asian spinning mills.
- Polyester:Petroleum-derived filament and staple fiber dominates volume production through integrated fiber-to-fabric facilities in Zhejiang province. Recycled PET feedstock certification is becoming mandatory for German and French retail channel access under Ecodesign for Sustainable Products Regulation implementation timelines.
- Wool:Keratin fiber from Merino and heritage breed sheep delivers inherent flame resistance and moisture management without chemical finishing. Oregon ranch partnerships and vertical mill operations in the United States sustain price premiums against commodity imports.
- Acrylic:Synthetic staple fiber mimicking wool aesthetics at lower cost points serves price-sensitive hospitality and promotional segments.
Cost scalability concentrates procurement in polyester for volume tiers; margin concentration and heritage provenance marketing favor wool in premium outdoor and direct-to-consumer channels.
End User:
Institutional procurement specifications diverge sharply from consumer retail criteria across flammability testing, laundering durability, and therapeutic functionality.
- Households:Direct-to-consumer channels emphasize design aesthetics, wash durability, and seasonal storage convenience. E-commerce platforms in the United States and United Kingdom are consolidating private-label sourcing around pre-certified mills to compress vendor qualification timelines.
- Hotels:Commercial laundering requirements drive procurement toward polyester-cotton blends and solution-dyed acrylics with validated colorfastness under industrial wash protocols. Marriott and Hilton specification standards influence supplier qualification across global hospitality supply chains.
- Hospitals:Patient comfort programs and pressure ulcer prevention protocols are formalizing blanket procurement with antimicrobial finishing and thermal resistance specifications. US Veterans Health Administration and NHS England contracting frameworks are expanding weighted blanket trials for sleep therapy programs.
- Outdoor Enthusiasts:Performance specifications prioritize warmth-to-weight ratios, compressibility, and moisture management for alpine and backcountry use cases.
Procurement standardization favors hotels for predictable volume contracting; clinical outcome validation favors hospitals for therapeutic device reclassification opportunities.
Usage Occasion:
Seasonal demand patterns and activity-specific functional requirements reshape material selection and distribution timing across retail and institutional channels.
- Winter:Maximum thermal resistance specifications drive demand for wool and high-loft polyester fills in northern European and North American markets.
- Camping:Synthetic insulation and water-resistant finishing prioritize packability and moisture tolerance for REI and Decathlon retail channels.
- Travel:Compact formats with antimicrobial finishing serve airline amenity programs and railway sleeping car operators.
- Home Décor:Aesthetic-driven purchasing emphasizes texture, color matching, and seasonal refresh cycles through furniture retail and e-commerce channels.
Seasonal replenishment predictability favors winter and home décor categories; year-round demand stability favors travel and camping formats with institutional contract anchoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement managers in the United States dominate institutional demand, while heritage wool buyers in Germany and France sustain premium positioning. Direct-to-consumer channels in the United Kingdom and Canada are consolidating vendor lists around pre-certified mills to compress qualification timelines.
United States
Veterans Health Administration and private hospital systems are expanding weighted blanket procurement for sleep therapy programs. The Consumer Product Safety Commission enforces 16 CFR Part 1610 flammability standards that elevate testing costs for multi-market suppliers. Oregon ranch partnerships feed vertical mill operations in the Pacific Northwest, sustaining heritage wool price premiums against commodity imports.
Germany
Retail buyers in German channels have achieved de facto mandatory OEKO-TEX Standard 100 status, consolidating procurement around pre-certified mills. The Ecodesign for Sustainable Products Regulation is mandating recycled polyester and organic cotton certifications for market access. Industrial laundries in North Rhine-Westphalia service hospitality procurement with validated colorfastness protocols under commercial wash conditions.
China
Zhejiang and Jiangsu provinces control the majority of export-bound polyester fiber-to-fabric production for global private-label programs. GB 18401 national textile safety standards govern export quality baselines from manufacturing clusters. Shanghai Easun Group anchors volume production through integrated facilities, competing on cost for hotel and hospital contracts.
United Kingdom
NHS England contracting frameworks are formalizing blanket procurement for patient comfort and pressure ulcer prevention protocols. REACH chemical restrictions on azo dyes and flame retardants complicate inventory pooling with US and Chinese regulatory regimes. E-commerce platforms are consolidating private-label sourcing around mills with existing certification portfolios to accelerate vendor onboarding.
Canada
Provincial healthcare systems in Ontario and British Columbia are expanding weighted blanket trials for reimbursable medical equipment classification. Health Canada maintains alignment with US flammability standards while enforcing additional labeling requirements for heated products. Hudson's Bay Company heritage positioning sustains consumer loyalty in domestic retail channels against international competitors.
Blanket Market Vendor Landscape
Player mix skews toward vertically integrated heritage mills and scale-driven synthetic fiber producers. The competitive structure fragments across three distinct tiers: premium wool specialists with ranch-to-retail provenance, integrated polyester manufacturers serving institutional bulk contracts, and safety-certified appliance producers dominating electric blanket segments. Dominant competitive moves include backward integration into fiber production and strategic consolidation around pre-certified supplier networks to accelerate retail channel access.
Within the heritage wool tier, Pendleton Woolen Mills and Faribault Woolen Mill Co. exemplify vertical control from fiber sourcing through finished goods, sustaining price premiums against commodity imports. Shanghai Easun Group occupies a position at the scale-driven end, anchoring volume production through integrated polyester facilities for private-label hospitality and healthcare contracts. American Blanket Company represents mid-market positioning between heritage provenance and institutional procurement specifications.
| Leading Market Players |
|---|
| Pendleton Woolen Mills |
| American Blanket Company |
| Faribault Woolen Mill Co. |
| Hudson's Bay Company |
| Boll & Branch |
| Shanghai Easun Group |
| Jarden Corporation |
| Biddeford Blankets |
| Chellco Industries Limited |
| Others |
Supply Flow & Price Mechanics
REACH Annex XVII chemical restrictions gate both supplier qualification timelines and price differentiation tiers simultaneously, forcing mills to absorb certification costs or forfeit European retail access while commanding premiums for compliant outputs.
Pricing Analysis
Polyester feedstock contracts index to crude oil benchmarks with quarterly adjustments, compressing margins for volume producers when energy markets spike. Pricing stratifies across OEKO-TEX certified premium tiers, standard compliant mid-market, and uncertified economy private-label. Cost compression in synthetic fiber tiers intensifies as recycled PET certification becomes mandatory under Ecodesign timelines. Hospital procurement managers demonstrate lowest price sensitivity due to therapeutic outcome requirements, while hospitality bulk buyers drive hardest bargain on per-unit replenishment costs.
Supply Chain Analysis
Yangtze River Delta port congestion creates chokepoint vulnerability for Zhejiang and Jiangsu export clusters serving North American retail. Raw material flows draw from Saudi Arabian petrochemical feedstock, Australian Merino wool clips, and Xinjiang cotton bales. Single-source concentration in Chinese fiber-to-fabric integration exposes buyers to tariff escalation and carbon border adjustment risks. Distribution runs through Rotterdam and Long Beach hub-and-spoke networks into retail consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Weighted blanket therapeutic reclassification represents a high-growth disruption, with clinical reimbursement pathways in select jurisdictions converting consumer goods into reimbursable medical equipment and rewriting margin structures.
For Market Incumbents: Shield heritage wool positioning by deepening Oregon ranch partnerships and captive scouring capacity against commodity import erosion. Accelerate OEKO-TEX Standard 100 pre-certification for supplier networks to compress German retail onboarding timelines. Defensive consolidation around weighted blanket medical device registrations will lock out late entrants from hospital contracting frameworks.
For New Entrants and Emerging Players: OEKO-TEX Standard 100 fast-track programs offer lowest barrier entry into French and German retail channels previously closed to uncertified mills. White-space concentrates in North American hospital sleep therapy procurement, where therapeutic device classification creates reimbursable demand outside commodity pricing. Go-to-market through GPO contracts with Veterans Health Administration bypasses retail channel consolidation.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed polyester volume producers in Zhejiang province facing Ecodesign compliance capex burdens. Long-term viability favors vertical wool control from ranch through retail against synthetic fiber margin compression. Watch for weighted blanket FDA 510(k) clearance signals as inflection indicator for medical device multiple expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wool Scouring | Pendleton-style ranch partnerships capture margin from Oregon fiber through finished goods. |
| OEKO-TEX Pre-Certification Investment | Compresses vendor qualification timelines for German retail channel consolidation. |
| Weighted Blanket FDA Submission | Unlocks Veterans Health Administration contracting beyond consumer retail channels. |
| Recycled PET Feedstock Transition | Ecodesign compliance maintains European market access against regulatory exclusion. |
| Hospital GPO Partnership Formation | NHS England and VHA frameworks anchor institutional volume outside price-sensitive hospitality. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, hospital procurement databases, and OEKO-TEX certification registries. Interviews with textile mill operations directors, hospitality procurement managers, hospital GPO contract specialists, and retail category buyers informed demand-side validation. Supply-side intelligence drew from Zhejiang province manufacturing cluster assessments and Oregon wool ranch operations. Bottom-up volume estimates triangulated against top-down market sizing from trade association disclosures.
Segmentation dimensions modeled include material type, product category, end-use sector, and certification tier across the projection horizon. CAGRs derive from regression analysis against macroeconomic indicators and regulatory implementation timelines. Weighted blanket therapeutic adoption curves and Ecodesign compliance phase-in schedules served as industry-specific forecast inputs. Scenario modeling incorporated crude oil price volatility and carbon border adjustment mechanisms.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH enforcement and stable hospital reimbursement pathways; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU chemical restriction list updates and US therapeutic device classification rulings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
Turkey Home Textile Market
Home Textiles
North America Home Textile Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Bangladesh Home Textile Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
Plush Blanket Market
Home Textiles
United Kingdom Home Textile Market
Home Textiles
Home Textile Products Market
Home Textiles
Europe Home Textile Market
Home Textiles
Bath Towel Market
Home Textiles
Vietnam Home Textile Market
Home Textiles
Global Theater Linen Market
Home Textiles
France Home Textile Market
Home Textiles
India Home Textile Market
Home Textiles
Linen Bed Sheets Market
Home Textiles
Germany Home Textile Market