
 South Africa High Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market Analytics
IEC 61803 qualification for HVDC converter stations is unwinding the competitive field, raising barriers for entrants lacking certified testing infrastructure. ABB Ltd leverages its converter valve manufacturing footprint to anchor premium project pipelines. Siemens AG sustains engineering density through localized service centers in Johannesburg and Cape Town. Hitachi Energy competes on thyristor reliability metrics that match Eskom's technical specifications.
South Africa High Voltage Direct Current Transmission Systems deploy converter stations, submarine cables, and overhead lines to transmit bulk electricity across distances exceeding conventional AC limits, typically operating at ±500 kV or higher with power ratings above 100 MW. The technology resolves stability constraints when connecting remote generation to load centers. VSC technology captures expanding share in grid interconnection applications where reactive power control proves critical. LCC installations dominate existing asset base given mature thyristor economics. Underground cable demand tracks mining sector electrification projects in Mpumalanga and Limpopo.
Eskom's grid code and the National Energy Regulator of South Africa licensing framework shape equipment certification timelines and interconnection queue priorities. The Department of Mineral Resources and Energy Integrated Resource Plan mandates transmission expansion corridors that directly convert to HVDC project pipelines. Stakeholders must monitor regulatory clarity on independent power producer transmission access rights.
Market Dynamics
Eskom's transmission expansion mandate under the Integrated Resource Plan is compressing project timelines while IEC 61803 certification requirements filter supplier participation. Converter station procurement now favors vendors with localized testing infrastructure.
Growth Catalysts
- Renewable integration corridors:The Department of Mineral Resources and Energy mandates HVDC links connecting Western Cape wind zones to Gauteng load centers, creating pipeline visibility through 2035.
- Grid code modernization:Eskom's 2024 technical specifications for reactive power control accelerate Voltage Source Converter adoption over legacy Line Commutated systems.
- Mining electrification:Platinum and manganese operations in Limpopo and Mpumalanga require underground cable HVDC feeds that bypass surface congestion constraints.
Market Restraints
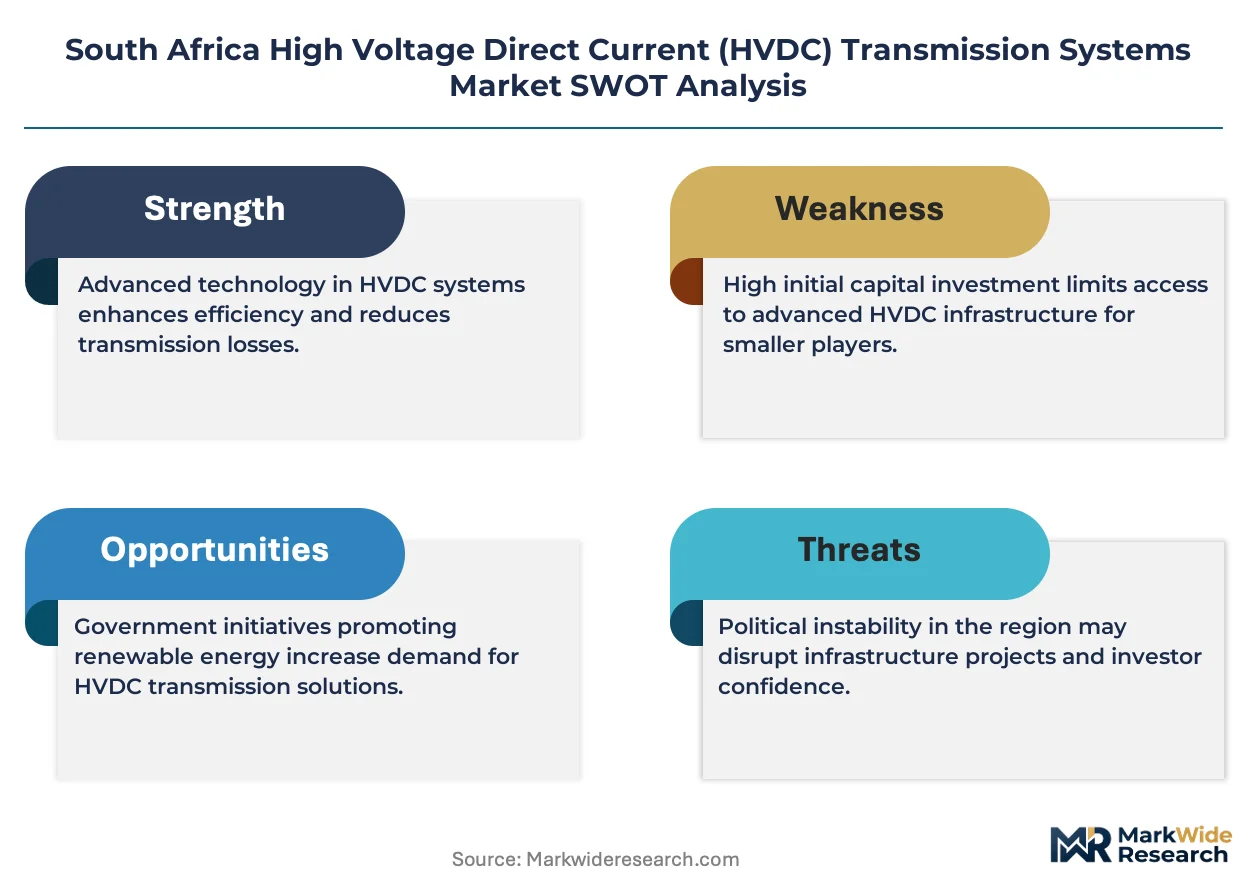
- Converter valve supply concentration:Thyristor and IGBT sourcing depends on Asian semiconductor fabrication capacity subject to export licensing volatility.
- Capital intensity barriers:±500 kV submarine cable installations require specialized marine vessels with 18-month charter lead times.
- Regulatory queue friction:National Energy Regulator of South Africa licensing timelines for interconnection permits extend beyond equipment delivery schedules.
Strategic Opportunities
- Eastern Cape renewable zones:Untapped offshore wind potential requires submarine cable HVDC corridors not yet specified in current Integrated Resource Plan iterations.
- Cross-border interconnection:Mozambique and Zimbabwe transmission access agreements could unlock regional power pooling beyond South African load boundaries.
- Digital twin integration:Convergence of HVDC control systems with predictive analytics platforms enables condition-based maintenance contracts that extend vendor revenue streams.
Industry Challenges
- Specialized commissioning expertise:Converter station startup engineers with IEC 61803 field certification remain concentrated in European and East Asian labor pools.
- Legacy AC integration complexity:Synchronous condenser requirements at HVDC terminal points demand coordination with aging Eskom substation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa High Voltage Direct Current (HVDC) Transmission Systems Market |
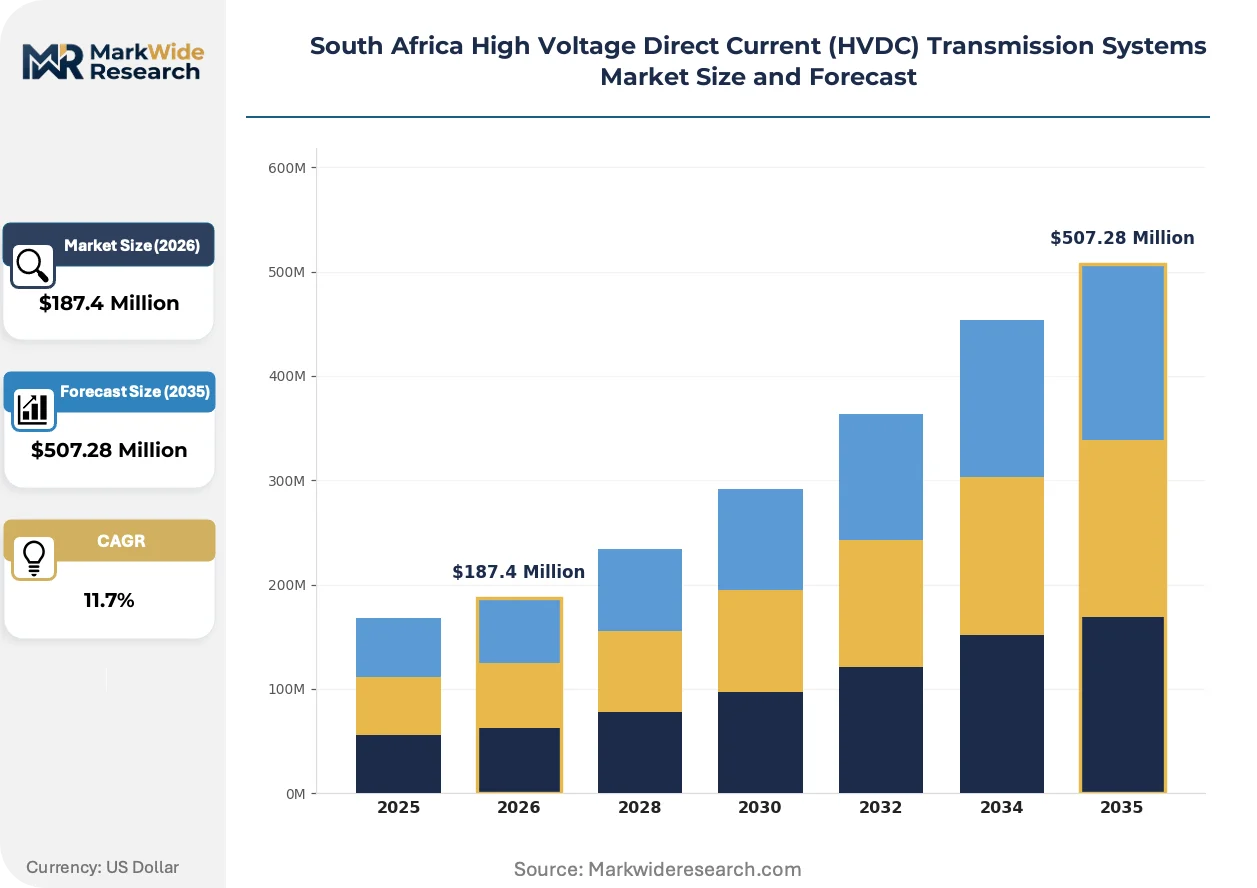
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LCC, VSC, Hybrid, Modular Multilevel End User: Utilities, Renewable Energy, Mining, Industrial Installation Type: Onshore, Offshore, Underground, Overhead Application: Power Transmission, Grid Interconnection, Energy Storage, Voltage Regulation |
| Companies Covered | Toshiba Corporation, LS Electric Co. Ltd., ABB Ltd, Hitachi Energy, Schneider Electric SE, Siemens AG, Prysmian SpA, Nexans SA, General Electric Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market Evolving Landscape
Modular converter architectures and digital control platforms are compressing station deployment schedules while forcing recalibration of long-term service revenue models. Equipment suppliers must now embed analytics capabilities to retain post-warranty relationships.
Voltage Source Converter technology is bifurcating project pipelines based on reactive power requirements. Grid interconnection applications in the Western Cape favor VSC systems for their black-start capability and independent reactive control. Eskom's technical evaluation committees now weight dynamic response specifications above capital cost in terminal station procurement, compressing thyristor-based Line Commutated Converter share in new awards despite mature unit economics.
The National Energy Regulator of South Africa's 2024 licensing framework revisions compress interconnection queue priorities for projects demonstrating grid stability contributions. Renewable energy independent power producers must now submit HVDC compatibility studies as condition precedent to generation licenses. Western Cape developers are responding by pre-qualifying converter station vendors before financial close to accelerate regulatory approval timelines.
Asset ownership structures are fragmenting traditional procurement patterns. Independent power producers now contract directly for converter station engineering-procurement-construction packages rather than routing through Eskom's centralized transmission procurement. Mining houses in Mpumalanga are pursuing captive HVDC links that bypass national grid scheduling, creating parallel demand channels that equipment suppliers must navigate with differentiated commercial terms.
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
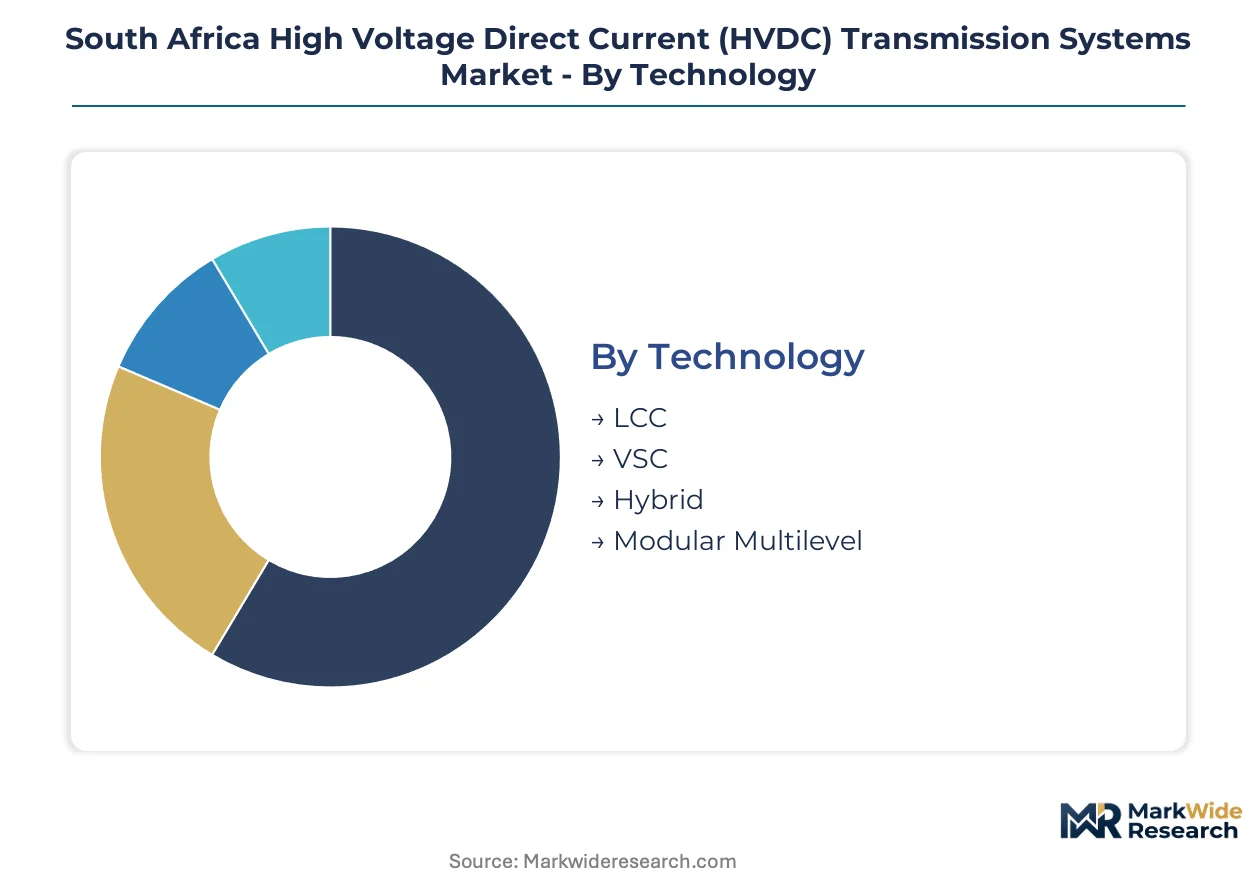
HVDC procurement channels in South Africa diverge sharply by customer type and technical specification. Eskom's centralized transmission procurement favors established converter architectures, while independent power producers and mining houses create parallel demand channels with distinct commercial terms and certification requirements.
Technology:
Channel mix varies by converter architecture maturity and certification burden. LCC systems flow through Eskom's legacy procurement frameworks, while VSC and hybrid configurations attract direct independent power producer contracting.
- LCC:Thyristor-based line commutated converter technology delivers mature unit economics at power ratings above 1000 MW. Eskom's existing asset base in Mpumalanga and Limpopo concentrates demand where black-start capability is less critical than capital efficiency.
- VSC:Voltage source converter systems employ IGBT or silicon carbide switching for independent reactive power control. Western Cape renewable integration projects specify VSC for grid code compliance where dynamic response specifications outweigh first-cost considerations.
- Hybrid:Combined LCC-VSC architectures balance power throughput with control flexibility for corridor applications.
- Modular Multilevel:Cascaded converter topology reduces harmonic filtering requirements and enables transformerless configurations.
LCC dominates installed base. VSC is where expansion concentrates.
End User:
Customer type dictates procurement scale, technical specification authority, and service contract structure. Utilities retain specification control for grid-connected assets, while captive industrial users bypass national scheduling frameworks.
- Utilities:Eskom's transmission division and municipal distributors specify equipment through centralized tender processes. Grid code compliance and IEC 61803 certification requirements filter supplier participation, with procurement timelines compressed by Integrated Resource Plan mandates.
- Renewable Energy:Independent power producers in Western Cape and Eastern Cape zones contract directly for converter station engineering-procurement-construction packages. Pre-qualification of vendors before financial close accelerates National Energy Regulator of South Africa licensing timelines.
- Mining:Platinum and manganese operations in Limpopo and Mpumalanga pursue captive HVDC links that bypass Eskom's scheduling queue.
- Industrial:Smelting and processing facilities with high load factors evaluate HVDC for voltage stability at terminal points.
Utilities anchor current procurement volume. Renewable energy developers are climbing the fastest.
Installation Type:
Physical deployment mode determines supply chain configuration and specialized contractor requirements. Marine and underground installations command premium pricing and extended lead times compared to conventional overhead corridors.
- Onshore:Converter stations and terrestrial cable routes constitute standard deployment for grid interconnection corridors. Johannesburg and Cape Town service centers support localized commissioning and maintenance.
- Offshore:Submarine cable installations require specialized marine vessels with extended charter lead times. Eastern Cape offshore wind zones remain unspecified in current Integrated Resource Plan iterations but represent future pipeline.
- Underground:Cable systems bypass surface congestion in mining electrification projects and urban transmission corridors.
- Overhead:Conventional tower configurations persist where right-of-way permits and visual impact constraints permit.
Overhead lines dominate existing transmission corridors. Underground installations are gaining share fastest in mining applications.
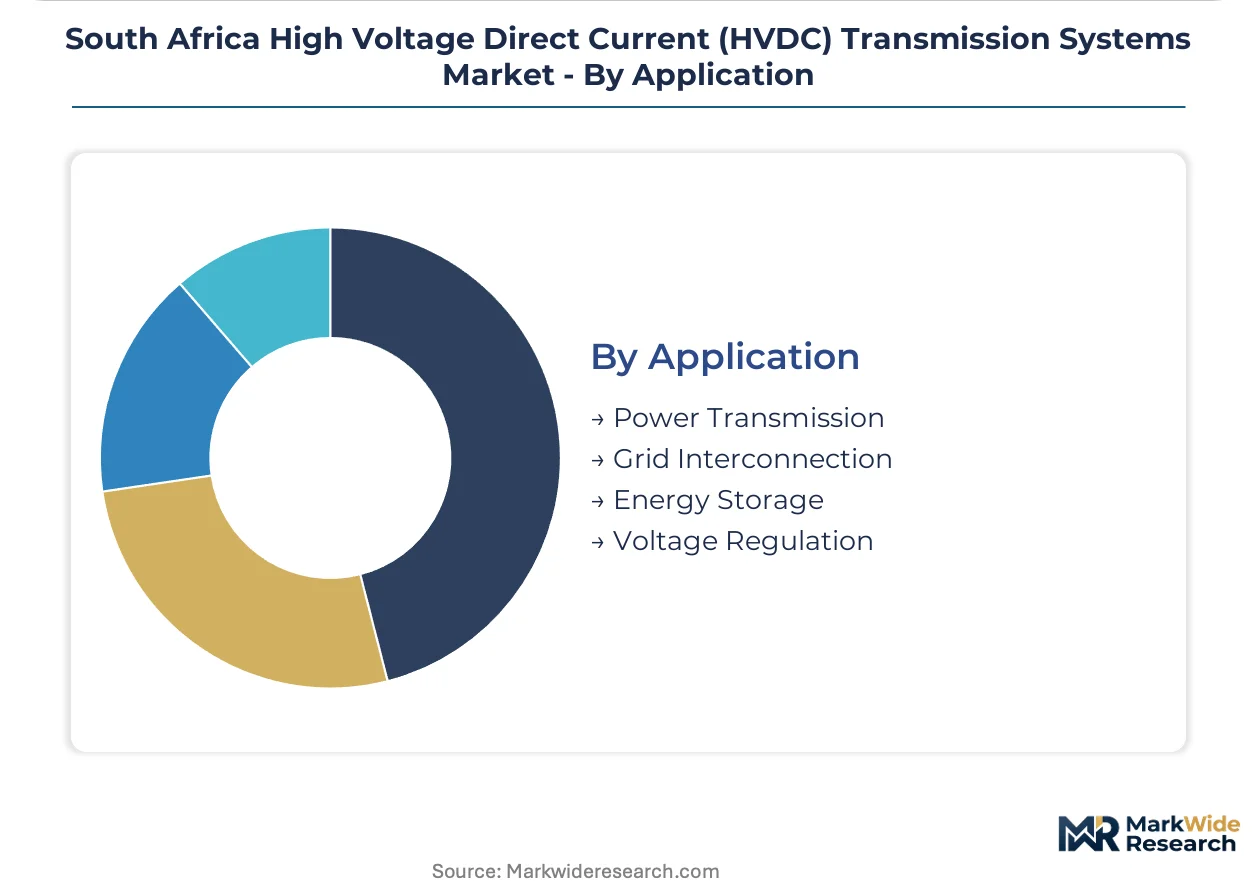
Application:
Use case determines control system specification, reactive power requirements, and revenue model structure. Bulk power transmission prioritizes throughput efficiency, while grid interconnection demands dynamic response capabilities.
- Power Transmission:Bulk electricity transport from remote generation to load centers constitutes foundational HVDC deployment. Western Cape-to-Gauteng corridors exemplify long-distance applications where AC stability constraints would otherwise limit transfer capacity.
- Grid Interconnection:Asynchronous grid linking and frequency stabilization require VSC technology with black-start capability. Cross-border agreements with Mozambique and Zimbabwe could unlock regional power pooling beyond South African boundaries.
- Energy Storage:Battery and pumped hydro integration with HVDC terminals enables time-shifting of renewable output.
- Voltage Regulation:Dynamic reactive compensation at terminal points supports AC grid stability.
Power transmission anchors current deployment. Grid interconnection represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate around Eskom's centralized procurement, Western Cape renewable developers, and Limpopo mining houses, each driving distinct HVDC specification priorities across South Africa's transmission corridors.
Gauteng Province
Eskom's transmission headquarters and Johannesburg load center anchor procurement decision-making for national grid expansion. The Department of Mineral Resources and Energy coordinates Integrated Resource Plan implementation from Pretoria, compressing project timelines for corridor approvals. The Johannesburg-Cape Town HVDC backbone development concentrates engineering and commissioning expertise in the province.
Western Cape
Renewable energy independent power producers in wind zones drive VSC technology demand for grid code compliance. The National Energy Regulator of South Africa processes interconnection licenses from Cape Town offices, with queue priorities favoring projects demonstrating grid stability contributions. The Saldanha-Cape Town corridor hosts converter station pre-qualification activities ahead of financial close.
Limpopo Province
Platinum and manganese mining operations pursue captive HVDC links that bypass Eskom's scheduling queue. The Department of Mineral Resources and Energy licensing framework permits mining houses to contract directly for underground cable installations. The Bushveld Igneous Complex concentrates demand for surface-congestion-bypassing transmission infrastructure.
Mpumalanga Province
Coal-to-renewables transition corridors and mining electrification projects create parallel demand channels for converter station engineering-procurement-construction packages. Eskom's existing LCC asset base in the province supports legacy procurement frameworks for bulk power transmission. The Witbank-Middelburg industrial cluster drives underground cable specifications for mining sector voltage stability.
Eastern Cape
Untapped offshore wind potential and submarine cable corridors represent pipeline expansion beyond current Integrated Resource Plan iterations. The National Energy Regulator of South Africa has yet to specify interconnection priorities for marine installations, creating regulatory uncertainty. The Port Elizabeth-Gqeberha coastal zone positions for future converter station landing points.
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market Competitive Landscape
Player mix skews toward integrated electrical equipment conglomerates with converter valve manufacturing footprints and specialized cable producers with marine installation capabilities. Market structure concentrates around three strategic archetypes: full-system integrators owning converter station and cable capabilities, component specialists dominating thyristor or IGBT supply, and regional engineering firms with localized commissioning presence. Competitive moves center on IEC 61803 certification acquisition and marine vessel charter partnerships for submarine installations.
Within the full-system integrator tier, ABB Ltd, Siemens AG, and Hitachi Energy occupy positions shaped by converter valve manufacturing density and localized service infrastructure. ABB Ltd leverages its manufacturing footprint to anchor premium project pipelines. Siemens AG sustains engineering presence through service centers in Johannesburg and Cape Town. Hitachi Energy competes on thyristor reliability metrics aligned with Eskom technical specifications. These three exemplify how certification burdens and procurement channel fragmentation reward integrated capabilities over pure component supply.
| Leading Market Players |
|---|
| Toshiba Corporation |
| LS Electric Co. Ltd. |
| ABB Ltd |
| Hitachi Energy |
| Schneider Electric SE |
| Siemens AG |
| Prysmian SpA |
| Nexans SA |
| General Electric Company |
| Others |
Value Network & Pricing Analysis
IEC 61803 certification gates both supplier qualification and price differentiation in South Africa's HVDC transmission market, compressing margins for uncertified vendors while rewarding localized testing infrastructure with premium contract access. Eskom's procurement committees weight certification status above unit cost in converter station awards, bifurcating the vendor landscape into certified premium tiers and excluded commodity suppliers.
Pricing Analysis
Cost-plus contracts with copper and semiconductor indexation dominate converter station procurement, insulating vendors from raw material volatility while exposing buyers to commodity swings. Price differentiation separates IEC 61803-certified system integrators from component-only suppliers, with after-sales service bundling commanding additional premiums. Pricing pressure stems from independent power producers consolidating engineering-procurement-construction packages to accelerate financial close timelines. Mining houses in Limpopo demonstrate lowest price sensitivity due to captive link economics, while municipal distributors face acute budget constraints.
Supply Chain Analysis
Strait of Malacca transit underwrites thyristor and IGBT delivery schedules from East Asian fabrication centers, creating logistics vulnerability for converter valve procurement. Semiconductor sourcing draws from Taiwan, Japan, and South Korea, while specialized marine vessels for submarine cable installation concentrate in European and Korean yards. Single-source vulnerability in silicon carbide wafer supply threatens VSC technology scaling. Distribution runs through Johannesburg engineering centers for onshore commissioning and Cape Town marine coordination for offshore corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among independent power producers consolidating direct converter station procurement, fragmenting Eskom's historical monopoly over transmission equipment specification and compressing incumbent margin structures.
For Market Incumbents: Compound certification advantages by embedding digital twin analytics into post-warranty service contracts, capturing recurring revenue streams threatened by modular converter architectures. Deepen backward integration into silicon carbide wafer sourcing to secure VSC technology pipelines against semiconductor supply volatility. Prioritize marine vessel charter partnerships ahead of Eastern Cape offshore wind corridor specification. For New Entrants and Emerging Players: Lead with commissioning engineering services where IEC 61803 field certification scarcity creates immediate contract access, bypassing capital-intensive converter valve manufacturing barriers. Target underground cable installations in Mpumalanga mining electrification as the most penetrable application segment, where surface congestion bypass requirements outpace established vendor capacity. Pursue joint development agreements with platinum producers seeking captive HVDC links outside Eskom scheduling queues. For Investors and Strategic Acquirers: National Energy Regulator of South Africa's 2024 licensing framework revisions reshape the acquisition landscape by privileging projects with pre-qualified converter vendors, elevating engineering-procurement-construction capabilities above pure equipment supply. Five-to-ten-year viability favors vertically integrated specialists with marine installation assets and localized commissioning presence. Signal to watch: clarity on independent power producer transmission access rights under Integrated Resource Plan iterations.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61803 Certification Acquisition | Qualification for Eskom premium procurement tiers filters competitor participation. |
| Marine Vessel Charter Partnership | Eastern Cape offshore wind corridors require specialized cable installation capacity. |
| Digital Twin Platform Integration | Predictive analytics contracts extend vendor revenue beyond equipment warranty periods. |
| Silicon Carbide Supply Anchoring | VSC technology scaling depends on securing wafer supply from East Asian fabrication. |
| Cross-Border Interconnection Development | Mozambique and Zimbabwe transmission agreements unlock regional power pooling economics. |
Research Methodology
Initial hypotheses were tested against primary input from Eskom transmission planning officers, independent power producer project developers, EPC contractors, and converter station commissioning engineers and refined through secondary validation. Primary fieldwork combined structured interviews with utility procurement committees and mining house energy managers. Secondary sources included Department of Mineral Resources and Energy Integrated Resource Plan documentation, National Energy Regulator of South Africa licensing determinations, and Eskom grid code technical specifications. Bottom-up project pipeline aggregation was triangulated against top-down transmission expansion mandate analysis.
Variance decomposition across technology segments, end-user categories, and installation types structured the analytical framework over the projection horizon. Modeled dimensions encompassed converter architecture maturity, customer procurement channel, physical deployment mode, and application use case. CAGRs were derived from segment-level demand build-ups calibrated to Integrated Resource Plan corridor specifications. Forecast inputs incorporated commodity price trajectories for copper and semiconductor materials alongside marine vessel charter availability curves.
Forecasts assume regulatory continuity in National Energy Regulator of South Africa licensing frameworks and Department of Mineral Resources and Energy transmission planning mandates; material policy shifts would require re-modeling interconnection queue priorities and independent power producer access rights. Practitioners should keep alternative scenarios live as Integrated Resource Plan iteration timing and cross-border agreement negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Flexible AC Transmission Systems Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
South-East Asia DC Distribution Network Market