
 Middle East and Africa Ultrasound Probe Disinfection Market | 2026-2036
Middle East and Africa Ultrasound Probe Disinfection Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Ultrasound Probe Disinfection Market Foresight
South Africa's hospital infrastructure expansion is fragmenting procurement patterns across public and private channels. Nanosonics specializes in trophon ultrasound probe disinfection systems with high-level disinfection chemistry validated for transesophageal echocardiography probes. Tristel plc leverages chlorine dioxide-based wipe systems for manual high-level disinfection in settings lacking automated infrastructure. Ecolab anchors hospital-wide infection prevention programs through bundled chemical disinfectant supply contracts.
Ultrasound probe disinfection encompasses validated protocols and chemistries designed to eliminate pathogens on semi-critical medical devices contacting mucous membranes or non-intact skin, requiring sporicidal efficacy within standardized contact times to prevent cross-contamination between patients. Automated systems incorporating ultraviolet light or thermal disintraction technology command premium positioning due to reproducible cycle documentation and reduced human error exposure, while manual disinfectants and wipes retain volume dominance in cost-constrained clinics and diagnostic centers. Chemical disinfection technology leads current installed base across obstetrics and cardiology applications where probe turnaround speed determines departmental throughput.
South Africa's national health regulator enforces infection control standards aligned with ISO 17664 for reusable medical device processing, while the UAE's MOHAP mandates probe disinfection documentation under healthcare facility licensing requirements. EMA-equivalent frameworks in Saudi Arabia through SFDA guidance on high-level disinfection validation shape product registration pathways for imported automated systems. Stakeholders must monitor evolving national essential device lists and reimbursement eligibility for automated disinfection capital equipment as Gulf Cooperation Council health systems consolidate procurement under centralized purchasing authorities.
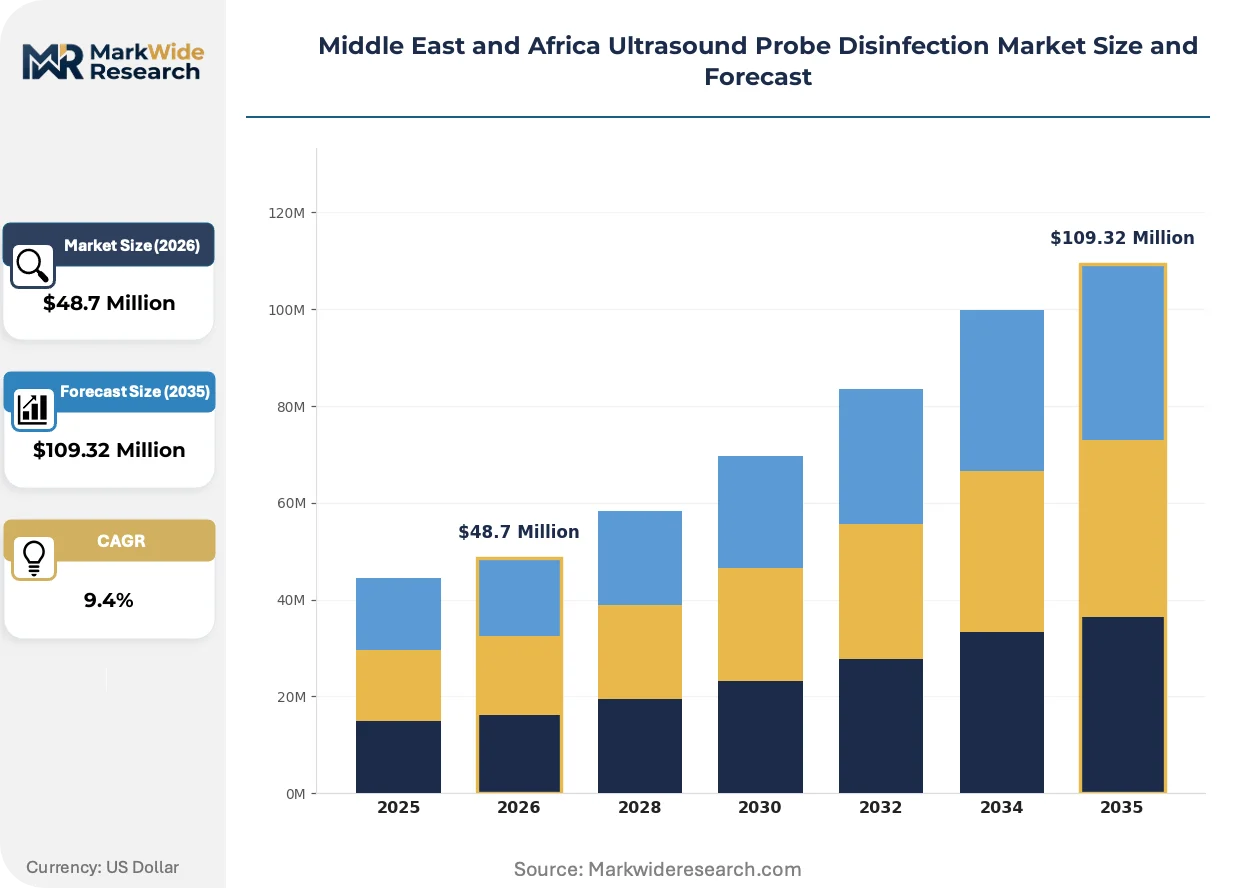
Market Dynamics
Automated ultraviolet light and thermal disinfection systems are displacing manual chemical protocols across tertiary hospital clusters in the Middle East and Africa, driven by stricter documentation mandates from national health regulators and the need for reproducible cycle validation.
Growth Catalysts
- ISO 17664 Alignment:South Africa's national health regulator mandates standardized processing documentation for reusable medical devices, forcing public hospitals to upgrade from manual wipes to traceable automated systems.
- Transesophageal Echocardiography Volume:Cardiology departments across Saudi Arabia's tertiary centers require high-level disinfection chemistries validated for TEE probes, creating dedicated demand for sporicidal efficacy within compressed turnaround windows.
- Gauteng Province Concentration:South Africa's tertiary hospital cluster in Gauteng drives disproportionate uptake of ultraviolet light-based automated systems as procurement centralizes under provincial health authorities.
Market Restraints
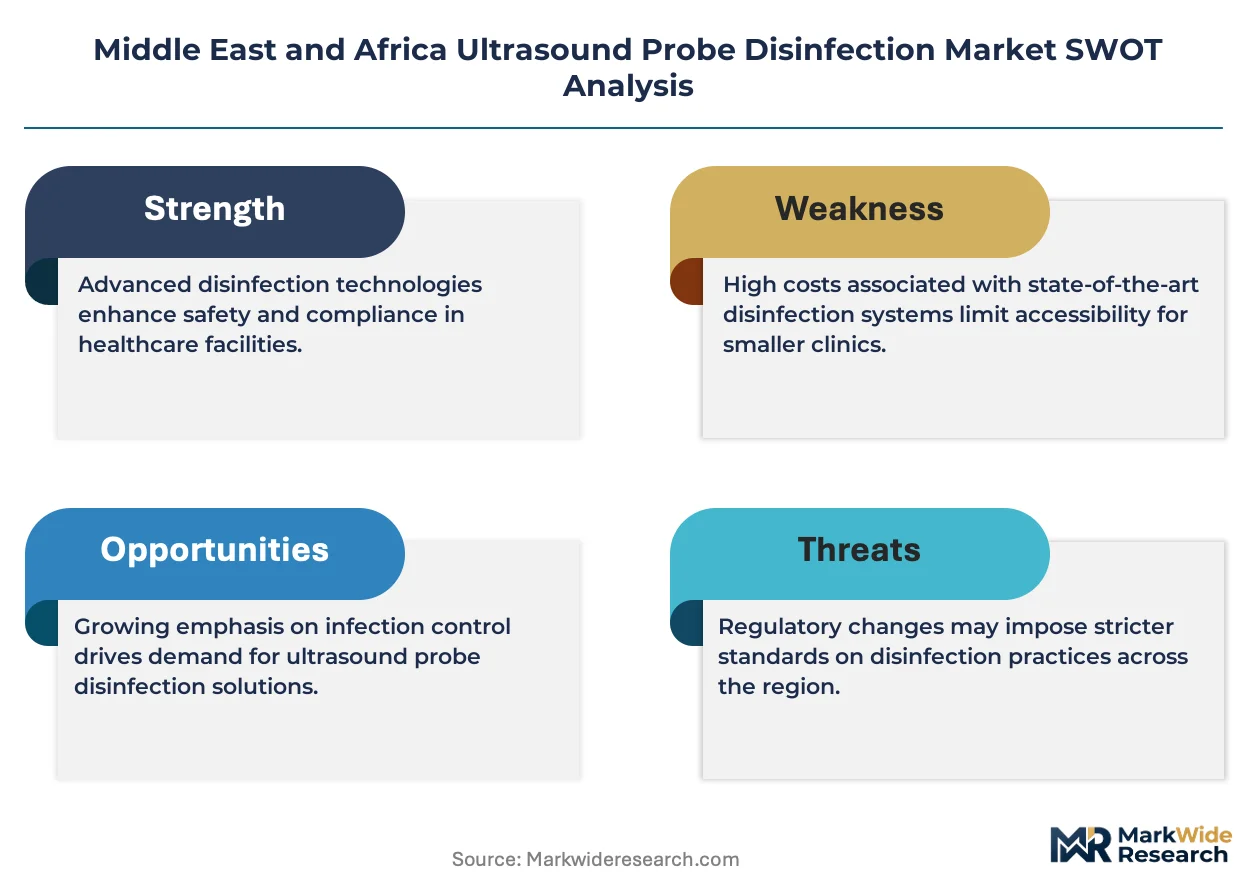
- Capital Equipment Intensity:Automated thermal and UV systems require upfront investment that excludes cost-constrained diagnostic centers and rural clinics from high-level disinfection compliance.
- Import Dependency:Automated disinfection hardware concentrates manufacturing in European and North American supply bases, exposing Middle East and African buyers to currency volatility and extended lead times.
- Manual Protocol Persistence:Chlorine dioxide and hydrogen peroxide wipe systems retain volume dominance where infrastructure gaps and intermittent electricity supply prevent automated system deployment.
Strategic Opportunities
- UAE Licensing Documentation Mandate:MOHAP's healthcare facility licensing requirements create pull-through demand for automated systems with integrated cycle logging and electronic record capture.
- Obstetrics Throughput Pressure:Maternity wards across Nigeria and Kenya face probe turnaround bottlenecks that thermal disinfection technology can compress from hours to minutes.
- Gulf Cooperation Council Consolidation:Centralized purchasing authorities in Saudi Arabia, UAE, and Qatar are bundling automated disinfection capital equipment into multi-hospital infection prevention contracts.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Automated system maintenance and validation require specialized technicians that remain concentrated in Johannesburg, Cairo, and Dubai metropolitan clusters.
- Legacy Probe Compatibility:Older ultrasound transducers from cardiology and radiology installed bases lack standardized connector geometries that automated disinfection chambers require.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Ultrasound Probe Disinfection Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Disinfectants, Wipes, Solutions End User: Hospitals, Clinics, Diagnostic Centers, Laboratories Technology: Ultraviolet Light, Chemical Disinfection, Thermal Disinfection, Ozone Treatment Application: Obstetrics, Cardiology, Emergency Care, General Imaging |
| Companies Covered | General Electric Company, Nanosonics, Ecolab, Schülke & Mayr GmbH, Siemens Healthcare GmbH, BODE Chemie GmbH, Tristel plc, CIVCO Medical Solutions, Germitec, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Ultrasound Probe Disinfection Market Shifts & Advancements
Documentation digitization and connected device architectures are reshaping competitive positioning in probe disinfection, as regulators and hospital accreditation bodies demand audit-ready cycle records rather than paper logbooks.
Ultraviolet-C LED arrays with integrated RFID probe recognition are digitizing compliance workflows across Saudi Arabia's SFDA-regulated facilities. Tertiary cardiology departments in Riyadh and Jeddah are deploying these systems to eliminate human error in exposure timing. The technology is digitizing what were previously manual documentation steps into automated electronic health record feeds.
SFDA guidance on high-level disinfection validation is compressing product registration timelines for imported automated systems while elevating chemistry efficacy documentation requirements. European manufacturers must now submit sporicidal kill-rate studies under EMA-equivalent frameworks before Saudi market entry. Cardiology probe disinfectors face the steepest compliance burden as TEE applications carry the highest patient risk classification.
Service unbundling from capital equipment contracts is fragmenting supplier relationships across South African private hospital groups. Netcare and Life Healthcare are separating automated system procurement from maintenance and chemistry supply, forcing vendors to compete on consumable pricing rather than bundled lifetime cost. This pattern is most visible in Gauteng and Western Cape provinces where procurement autonomy has devolved to individual facility managers.
Middle East and Africa Ultrasound Probe Disinfection Market Segmentation
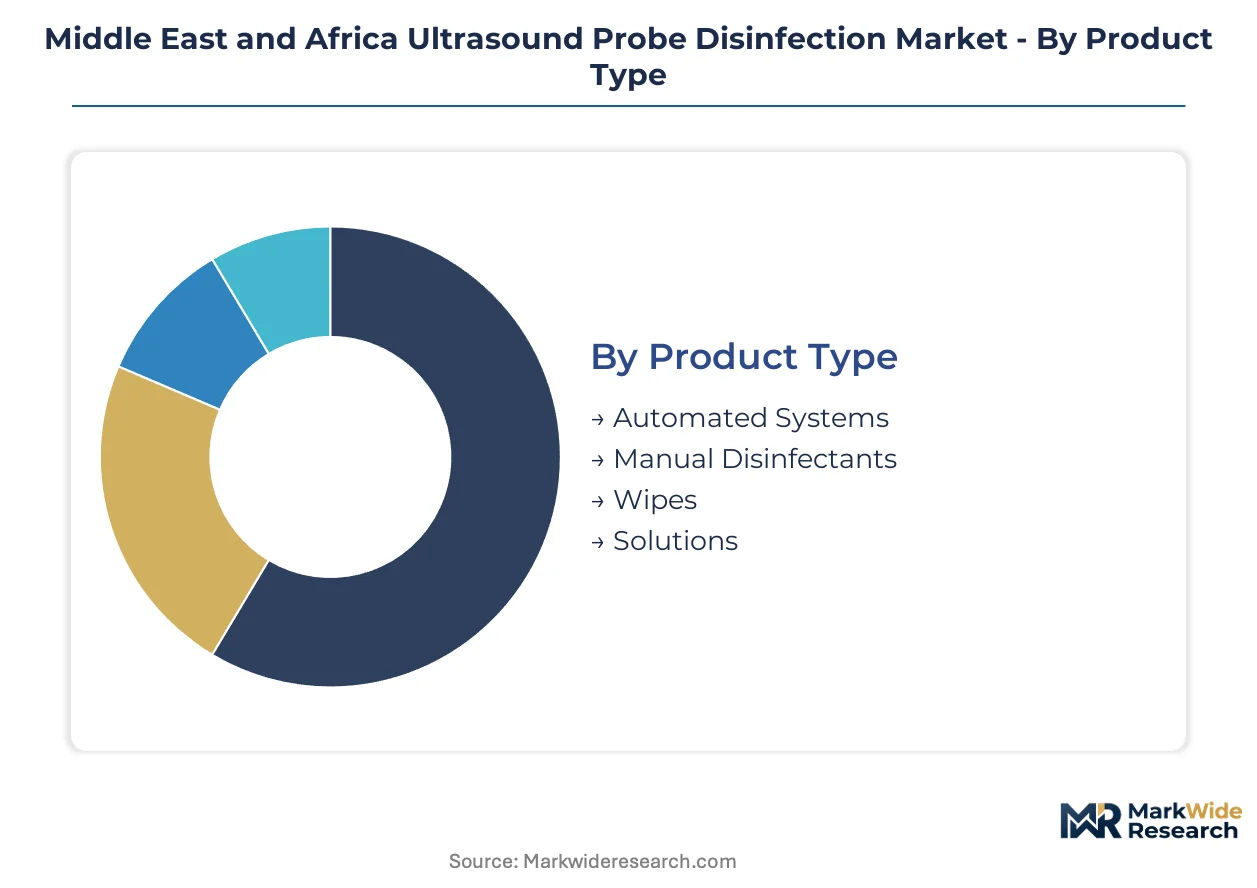
Ultrasound probe disinfection markets fragment sharply across technology maturity and infrastructure readiness. Procurement decisions in Middle East and Africa health systems diverge between capital-intensive automated platforms and consumable-dependent manual protocols, with each segment serving distinct compliance and throughput requirements.
Product Type:
Use cases span from high-throughput tertiary hospitals requiring validated cycle documentation to rural clinics dependent on wipe-based protocols.
- Automated Systems:UV-C and thermal chambers deliver reproducible high-level disinfection with electronic logging for regulatory audit trails. Demand concentrates in Saudi Arabia's SFDA-regulated tertiary centers and South Africa's Gauteng hospital cluster, where ISO 17664 documentation mandates exclude manual alternatives.
- Manual Disinfectants:Hydrogen peroxide and chlorine dioxide chemistries enable high-level disinfection without capital infrastructure. Nigeria and Kenya's diagnostic centers rely on these formulations where electricity intermittency and procurement budget ceilings block automated system deployment.
- Wipes:Pre-saturated towelettes offer point-of-use convenience for surface disinfection between patients.
- Solutions:Bulk liquid chemistries support manual immersion protocols in laboratories with trained biomedical staff.
The dominant share belongs to Manual Disinfectants, while Automated Systems is closing the gap fastest.
End User:
Customer infrastructure determines whether procurement favors capital equipment or recurring consumable contracts.
- Hospitals:Tertiary institutions with centralized sterile processing departments absorb automated disinfection systems under multi-year infection prevention contracts. UAE's MOHAP licensing requirements for documentation push Dubai and Abu Dhabi facilities toward connected UV platforms with electronic record integration.
- Clinics:Smaller outpatient settings prioritize probe turnaround speed over capital investment. Kenya's maternity clinics deploy thermal disinfection units to compress obstetrics probe cycles from hours to minutes without dedicated sterile processing staff.
- Diagnostic Centers:Imaging-focused facilities balance patient volume against equipment budgets.
- Laboratories:Research and pathology settings apply disinfection protocols for experimental imaging applications.
Hospitals command the largest procurement volumes, though Diagnostic Centers are expanding their technology investments most aggressively.
Technology:
Validation requirements and infrastructure dependencies create tiered adoption patterns across the region.
- Ultraviolet Light:UV-C LED arrays with RFID probe recognition automate compliance workflows and eliminate human timing errors. Riyadh and Jeddah cardiology departments deploy these systems under SFDA guidance requiring sporicidal kill-rate documentation for TEE probe applications.
- Chemical Disinfection:Established hydrogen peroxide and chlorine dioxide formulations retain volume leadership where automated infrastructure is unavailable. South Africa's public hospital network maintains these protocols in rural provinces beyond Gauteng's centralized procurement reach.
- Thermal Disinfection:Heated chamber systems deliver rapid cycle times for high-throughput obstetrics wards.
- Ozone Treatment:Emerging oxidative technology addresses niche applications with specific material compatibility requirements.
Chemical Disinfection retains the widest installed base, while Ultraviolet Light is gaining share fastest among new installations.
Application:
Clinical risk classification and probe turnaround pressure shape technology selection by department.
- Obstetrics:High patient volumes and rapid probe reuse cycles favor thermal disinfection technology. Nigerian and Kenyan maternity wards face throughput bottlenecks that automated systems can compress, though capital constraints perpetuate manual protocol dependence in public facilities.
- Cardiology:Transesophageal echocardiography probes carry the highest patient risk classification, mandating sporicidal efficacy within validated contact times. Saudi Arabia's tertiary centers concentrate demand for automated systems with integrated chemistry validation under SFDA high-level disinfection guidance.
- Emergency Care:Unpredictable patient flows require flexible disinfection protocols.
- General Imaging:Lower-risk applications accommodate broader technology options.
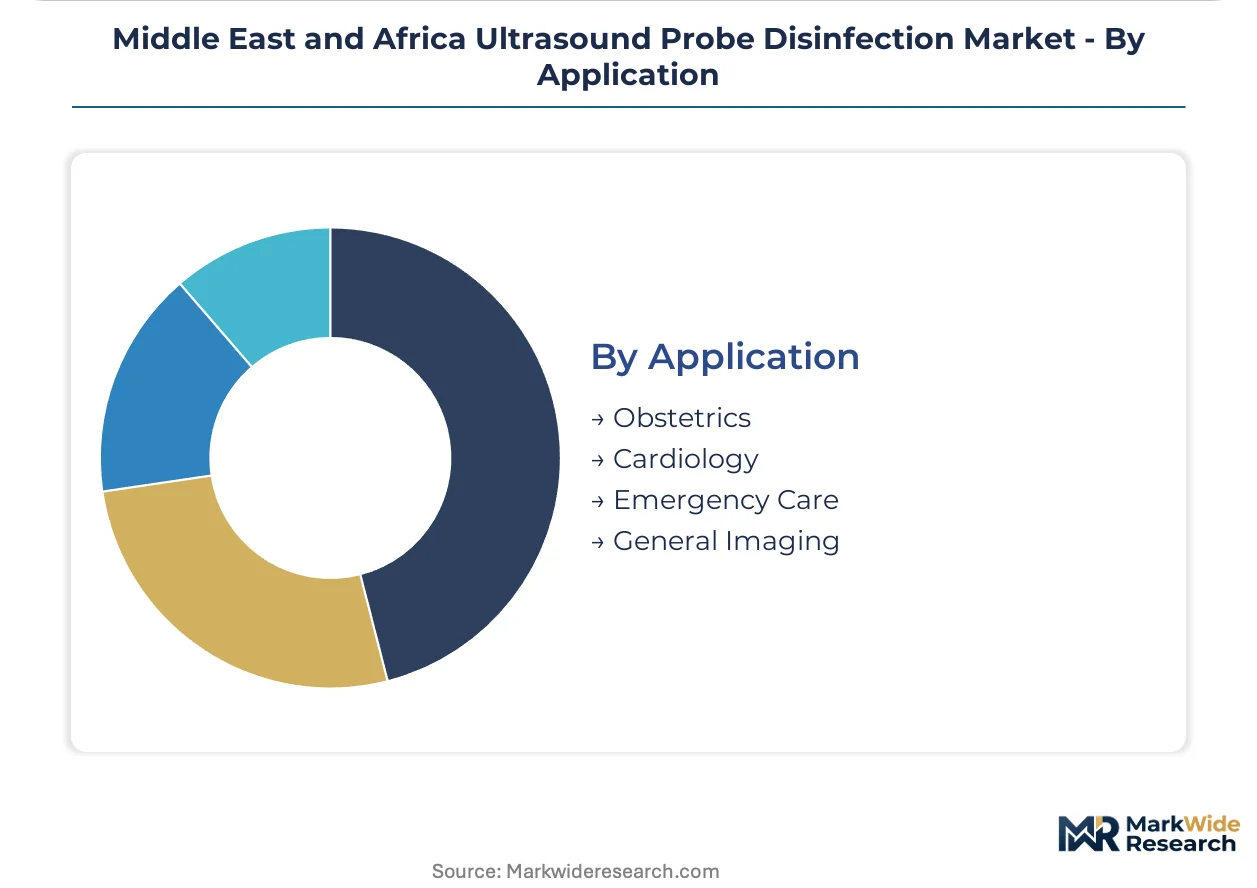
Obstetrics generates the highest procedure volumes, though Cardiology commands the steepest compliance investment per probe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated disinfection hardware concentrates manufacturing in European and North American supply bases, exposing Middle East and African buyers to currency volatility and extended lead times. Procurement patterns fragment across public and private channels as hospital infrastructure expands.
Saudi Arabia
SFDA guidance on high-level disinfection validation compresses product registration timelines for imported automated systems while elevating chemistry efficacy documentation requirements. The national pharmaceutical regulator mandates sporicidal kill-rate studies under EMA-equivalent frameworks before market entry. Riyadh and Jeddah cardiology departments deploy UV-C LED arrays with RFID probe recognition to eliminate human error in exposure timing.
United Arab Emirates
MOHAP's healthcare facility licensing requirements create pull-through demand for automated systems with integrated cycle logging and electronic record capture. The national health regulator enforces probe disinfection documentation under facility licensing standards. Dubai and Abu Dhabi tertiary hospitals absorb connected UV platforms with electronic health record integration.
South Africa
ISO 17664 alignment forces public hospitals to upgrade from manual wipes to traceable automated systems as the national health regulator mandates standardized processing documentation. The country's infection control standards require sporicidal efficacy within validated contact times. Gauteng Province's tertiary hospital cluster drives disproportionate uptake of ultraviolet light-based automated systems under centralized provincial procurement.
Nigeria
Maternity wards face probe turnaround bottlenecks that thermal disinfection technology can compress from hours to minutes. The country's national health regulator struggles with enforcement capacity across fragmented state-level hospital networks. Lagos-based diagnostic centers balance patient volume against capital equipment budgets while public facilities perpetuate manual protocol dependence.
Kenya
Obstetrics throughput pressure favors thermal disinfection units that compress probe cycles without dedicated sterile processing staff. The national medical device regulator aligns with WHO prequalification standards for imported disinfection equipment. Nairobi maternity clinics deploy automated systems where electricity reliability permits, while rural facilities retain hydrogen peroxide wipe protocols.
Middle East and Africa Ultrasound Probe Disinfection Market Competitive Landscape
Specialized disinfection technology developers and diversified infection prevention conglomerates split the market across automated hardware and consumable chemistry supply. The vendor base concentrates around three strategic archetypes: probe-specific system specialists, hospital-wide infection prevention platforms, and manual chemistry suppliers serving cost-constrained settings. Consolidation pressures intensify as Gulf Cooperation Council health systems bundle automated disinfection capital equipment into multi-hospital contracts. Geographic expansion and technology licensing represent the dominant competitive moves as European manufacturers navigate SFDA and MOHAP registration pathways.
Among Australia-based specialists, Nanosonics exemplifies the probe-specific system archetype through its trophon platform architecture. German chemical conglomerates Schülke & Mayr GmbH and BODE Chemie GmbH occupy positions within the manual disinfection chemistry tier, supplying hydrogen peroxide and chlorine dioxide formulations where automated infrastructure remains unavailable. These three anchors illustrate the geographic and technological bifurcation shaping procurement decisions across Middle East and African health systems.
| Leading Market Players |
|---|
| General Electric Company |
| Nanosonics |
| Ecolab |
| Schülke & Mayr GmbH |
| Siemens Healthcare GmbH |
| BODE Chemie GmbH |
| Tristel plc |
| CIVCO Medical Solutions |
| Germitec |
| Others |
Supply & Pricing Matrix
Import dependency on European and North American automated disinfection hardware exposes Middle East and African buyers to currency volatility that compresses pricing tier spreads between premium UV-C systems and manual chemical alternatives while forcing distributors to absorb landed cost fluctuations.
Pricing Analysis
ISO 17664 alignment dictates the pricing tier structure across South African public hospitals, separating premium automated systems with electronic documentation from economy manual wipe protocols. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Pricing pressure stems from Gulf Cooperation Council procurement consolidation bundling multi-hospital contracts. Diagnostic centers in Nigeria and Kenya exhibit highest price sensitivity, while Saudi tertiary cardiology departments show lowest sensitivity due to SFDA-mandated sporicidal validation requirements.
Supply Chain Analysis
Export control regimes on UV-C LED array technology and thermal disinfection chamber components limit hardware flows from Germany, the United States, and Australia to Middle Eastern health systems. Manufacturing draws from precision electronics clusters in Bavaria, semiconductor fabs in Taiwan, and medical-grade steel processing in Italy. Single-source vulnerability concentrates around specialized RFID probe recognition modules. Distribution runs through Dubai's Jebel Ali Free Zone serving as regional logistics hub for Saudi, UAE, and East African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward centralized Gulf Cooperation Council purchasing authorities consolidating multi-hospital infection prevention contracts, fragmenting vendor relationships across bundled procurement and unbundled service agreements.
For Market Incumbents: Entrench position through backward integration into consumable chemistry supply and captive maintenance networks in Johannesburg, Cairo, and Dubai metropolitan clusters. Biomedical engineering talent scarcity threatens service margin sustainability. Certification investment under SFDA and MOHAP evolving frameworks preserves premium tier access. For New Entrants and Emerging Players: Rural diagnostic centers in Nigeria and Kenya's public maternity wards represent the most penetrable entry point for thermal disinfection units bypassing sterile processing infrastructure requirements. Cost-constrained clinics lacking electricity reliability offer white-space for hydrogen peroxide wipe formulations. Direct procurement relationships with provincial health authorities in South Africa bypass Gauteng concentration. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors chemistry-integrated platform specialists over pure hardware vendors. Long-term viability hinges on recurring consumable revenue attachment rates. Acquisition target archetype: regional distributors with SFDA registration pathways and hospital GPO relationships. Signal to watch: national essential device list inclusions for automated disinfection capital equipment.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Investment | Accelerates Saudi market entry under EMA-equivalent sporicidal validation requirements. |
| MOHAP Licensing Documentation Integration | Captures UAE pull-through demand for electronic cycle logging capabilities. |
| GCC Procurement Consolidation Partnership | Locks multi-hospital bundled contracts across Saudi, UAE, and Qatar systems. |
| Consumable Chemistry Backward Integration | Defends margin position against unbundling trends in South African private hospital groups. |
| Biomedical Engineering Talent Development | Addresses maintenance scarcity concentrated in Johannesburg, Cairo, and Dubai clusters. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineering directors, infection control officers, and GPO contracts specialists converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation from SFDA guidance documents, MOHAP licensing standards, ISO 17664 processing protocols, hospital procurement databases, and customs import records. Bottom-up installation base modeling and top-down healthcare expenditure triangulation anchored volume estimates.
Demand-supply balance framing shaped the analytical approach across the projection horizon. Segmentation dimensions modeled include technology type, end-user infrastructure tier, application risk classification, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating probe procedure volume trajectories, capital equipment replacement cycles, and chemistry consumable attachment rates. Industry-specific inputs encompassed TEE probe utilization rates in Saudi cardiology departments and obstetrics throughput pressure in Nigerian maternity wards.
Practitioners should monitor SFDA high-level disinfection guidance revisions, GCC centralized purchasing authority contract awards, and South African provincial procurement decentralization for early signals of forecast drift. Material shifts in national essential device list eligibility or currency volatility exposure on European hardware imports would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market
Healthcare Equipment
Microbiological Safety Cabinets Market
Healthcare Equipment
Emergency Hospital Beds Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
Medical Waste Supervision Solution Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Clinical Mobility Market