
 Bedpan Washer Disinfectors Market | 2026-2036
Bedpan Washer Disinfectors Market Size, Share, and Industry Trends Forecast 2026-2036
Bedpan Washer Disinfectors Market Analytics
Hospital procurement consortiums is reshaping how bedpan washer disinfectors reach end users across Europe and North America. Getinge AB leverages its installed base of central sterile supply departments to sustain recurring service revenue streams. STERIS Corporation anchors its competitive position through direct field service networks that control aftermarket parts distribution. MEIKO Maschinenbau GmbH & Co. KG specializes in modular thermal disinfection platforms that accommodate retrofit installations in aging hospital infrastructure.
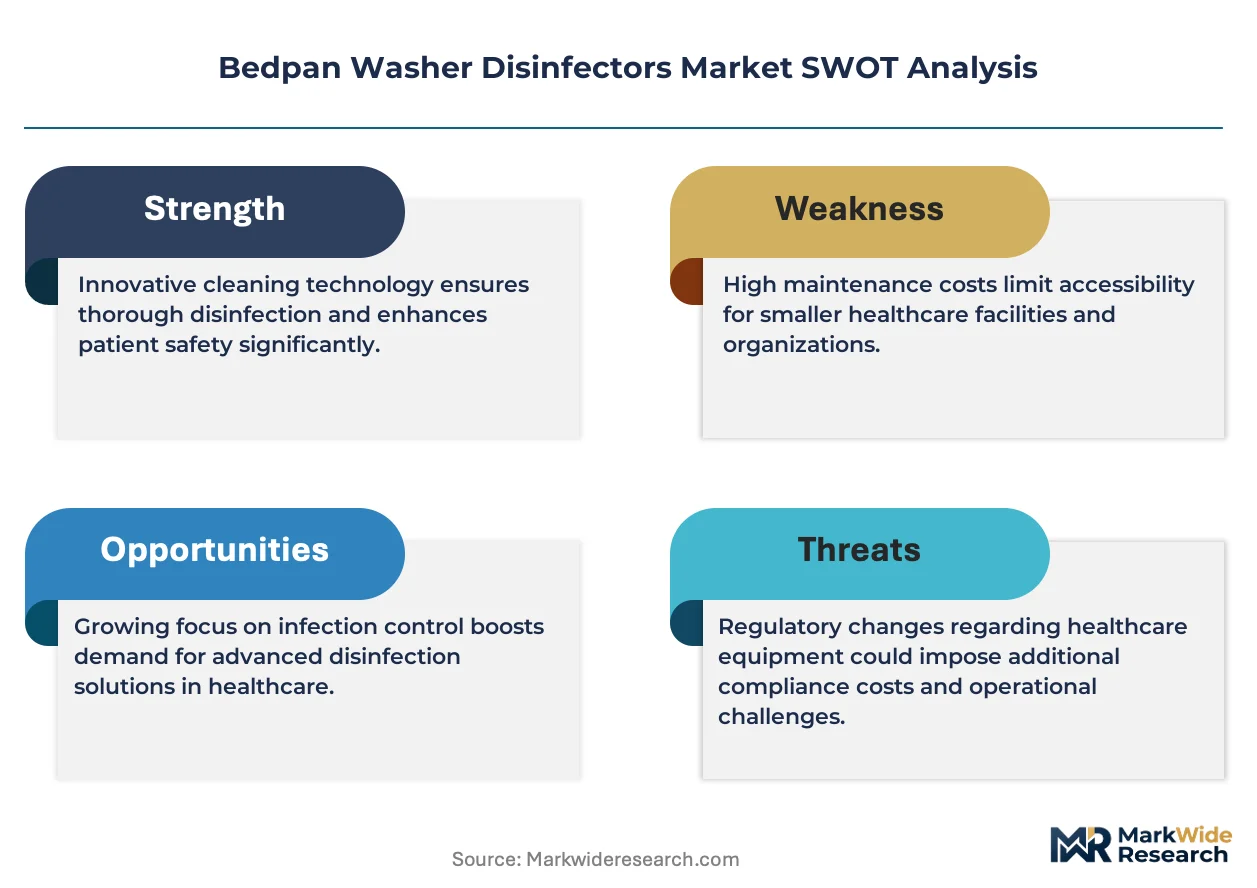
Bedpan washer disinfectors are enclosed mechanical systems that apply controlled thermal cycles, typically between 80°C and 93°C, combined with pressurized water jets and chemical dosing to decontaminate reusable human waste collection vessels. These units serve infection prevention departments by automating what was historically manual cleaning, eliminating cross-contamination pathways in acute care wards. Automatic product type systems command the dominant share of replacement demand as labor scarcity in hospital environmental services pushes facilities toward single-operator loading designs. Thermal disinfection technology leads installed capacity but ultrasonic cleaning configurations are gaining traction in long-term care facilities where lower throughput requirements match reduced cycle speed specifications.
The FDA regulates bedpan washer disinfectors as Class II medical devices under 21 CFR 880.6880, requiring 510(k) premarket notification for thermal disinfection claims and establishing minimum efficacy standards for spore reduction. EMA-coordinated national competent authorities enforce the EU Medical Device Regulation 2017/745, which reclassified washer disinfectors under higher scrutiny and demands updated clinical evaluation documentation from manufacturers seeking CE marking renewal. Stakeholders must monitor how impending amendments to ISO 15883 washer-disinfector standards will alter validation testing protocols and determine which existing product lines require engineering redesign for continued market access.
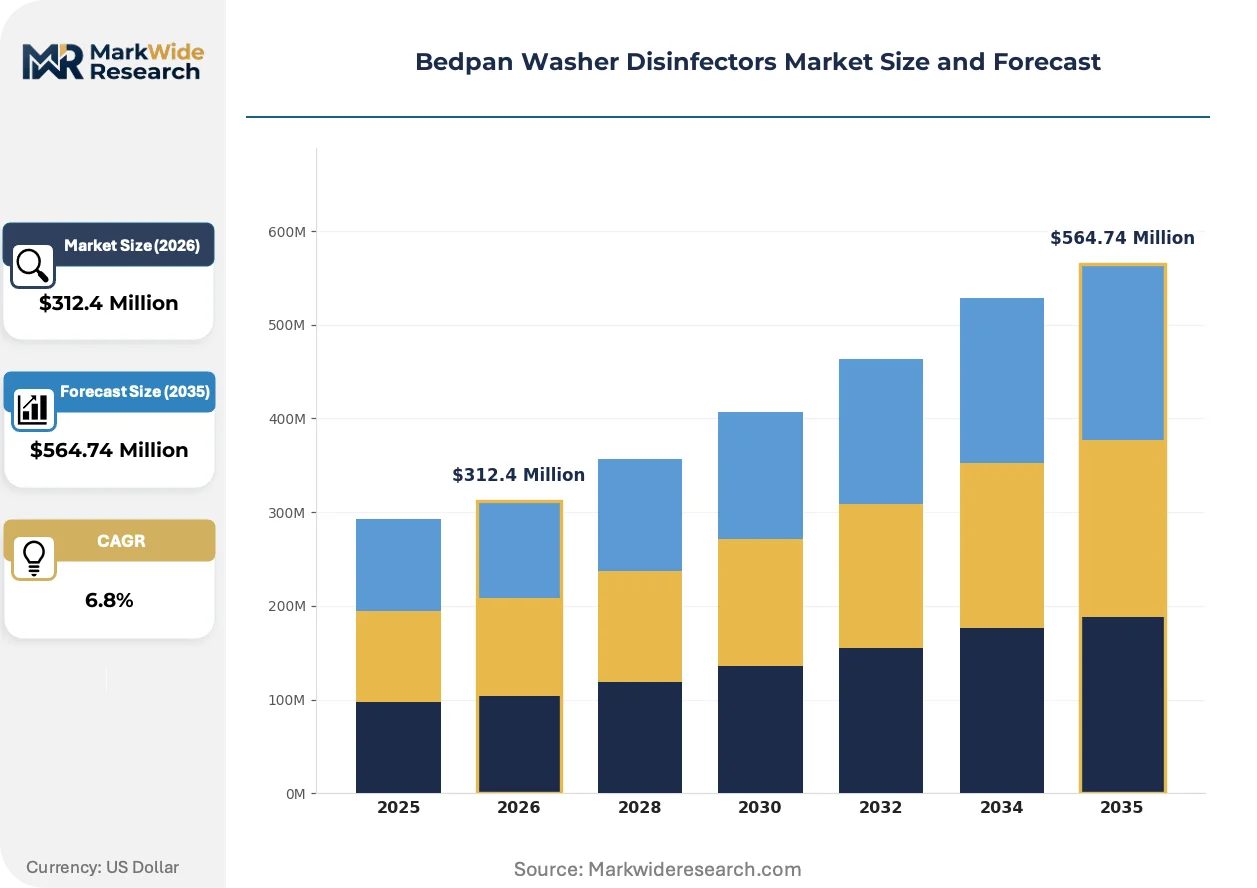
Market Dynamics
Automated thermal disinfection is displacing manual cleaning protocols across acute care wards as infection control departments face intensifying labor scarcity and tightening spore-reduction mandates from national health authorities.
Growth Catalysts
- EU Medical Device Regulation 2017/745:Reclassification of washer-disinfectors under higher scrutiny tiers accelerates replacement cycles for aging equipment fleets across European hospitals.
- Centralized sterile services departments:Bulk procurement consolidation in Germany and the United Kingdom drives volume purchasing of floor-standing automatic systems with single-operator loading designs.
- Thermal disinfection technology:Automated cycles operating between 80°C and 93°C eliminate cross-contamination pathways that manual cleaning protocols fail to address in high-acuity wards.
Market Restraints
- Stainless steel input volatility:Grade 316L chamber fabrication costs fluctuate with nickel and molybdenum commodity pricing, compressing margins for European manufacturers.
- Validation testing concentration:ISO 15883 compliance documentation requirements favor established testing laboratories in Germany and Switzerland, creating bottlenecks for new market entrants.
- Single-use bedpan substitution:Polypropylene disposable vessels gain traction in outbreak containment scenarios, threatening replacement demand in long-term care segments.
Strategic Opportunities
- Long-term care facilities:Ultrasonic cleaning configurations with reduced throughput specifications address labor constraints in nursing homes across France and Italy.
- HTM 01-04 compliance mandates:United Kingdom health technical memoranda create regulatory tailwinds for validated thermal disinfection equipment in NHS trusts.
- IoT-enabled cycle monitoring:Sensor integration with hospital building management systems enables predictive maintenance contracts and remote validation documentation.
Industry Challenges
- Biomedical engineering skill scarcity:Qualified technicians capable of validating A0 spore-reduction parameters remain concentrated in centralized sterile services departments, limiting field service expansion.
- Legacy plumbing infrastructure:Aging hospital wards in Southern Europe require costly steam and drainage retrofits to accommodate floor-standing automatic systems, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bedpan Washer Disinfectors Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Combination Installation Type: Wall-Mounted, Floor-Standing, Portable, Built-In End User: Hospitals, Long-Term Care Facilities, Home Care, Rehabilitation Centers Technology: Thermal Disinfection, Chemical Disinfection, Ultrasonic Cleaning, Steam Sterilization |
| Companies Covered | Getinge AB, AT-OS S.p.A., Arjo AB, Tuttnauer Europe B.V., Belimed AG, Steelco S.p.A., STERIS Corporation, DEKO MedTech, MEIKO Maschinenbau GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bedpan Washer Disinfectors Market Evolving Landscape
Sensor-enabled cycle validation and connected fleet management are reconfiguring how infection prevention departments monitor disinfection efficacy and schedule equipment maintenance across distributed hospital campuses.
Ultrasonic cleaning modules paired with reduced-cycle thermal finishing are digitizing documentation workflows for long-term care operators. These hybrid systems capture real-time A0 value logging and transmit compliance data directly to infection control dashboards. Nursing home chains in France and Italy adopt these configurations to satisfy regional health authority audit requirements without expanding environmental services headcount.
The EU Medical Device Regulation 2017/745 demands updated clinical evaluation documentation for CE marking renewal, compressing product lifecycle planning for manufacturers with legacy washer-disinfector portfolios. National competent authorities in Germany and the United Kingdom enforce stricter post-market surveillance protocols. Smaller equipment vendors without dedicated regulatory affairs functions face exclusion from tender processes requiring MDR-compliant technical files.
Hospital procurement consortiums are consolidating vendor relationships and unbundling after-sales service contracts from equipment purchases. NHS Supply Chain and regional purchasing cooperatives in Germany negotiate multi-site framework agreements that separate spare parts distribution from installation and validation services. This disintermediation pressures manufacturers to maintain direct field service networks or risk margin erosion through third-party maintenance providers.
Bedpan Washer Disinfectors Market Segmentation
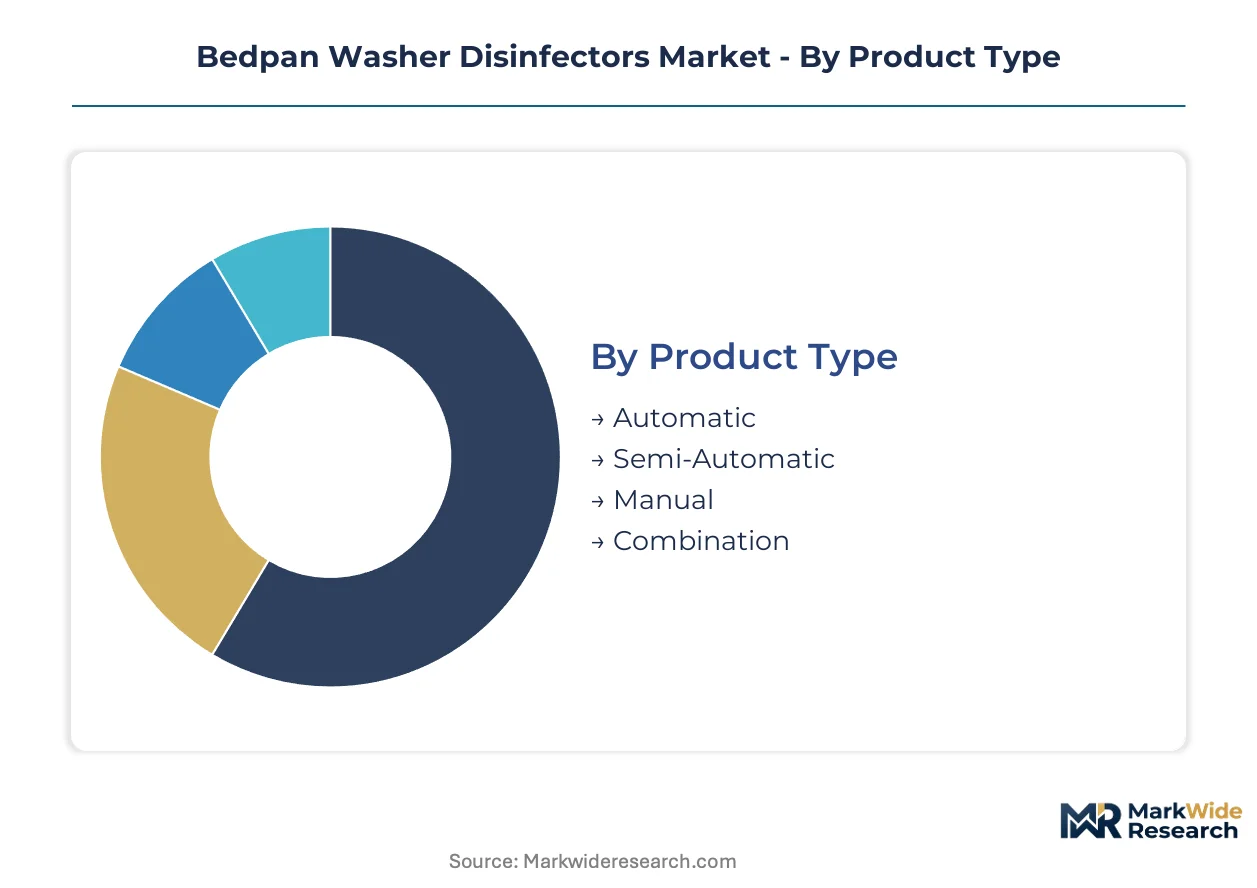
Segmentation in bedpan washer disinfectors determines service contract structures and validation complexity. Equipment configuration directly shapes aftermarket revenue streams and regulatory documentation burdens across acute care and long-term care environments.
Product Type:
After-sales-service intensity varies sharply across automation tiers, with automatic systems demanding predictive maintenance contracts and manual units requiring minimal field support.
- Automatic:Enclosed mechanical systems apply controlled thermal cycles between 80°C and 93°C with pressurized water jets and automated chemical dosing. Hospital procurement consortiums in Germany and the United Kingdom concentrate replacement demand here as labor scarcity pushes facilities toward single-operator loading designs.
- Semi-Automatic:Hybrid configurations require manual loading but automate thermal and rinse cycles, bridging cost constraints with infection control mandates. Long-term care facilities in France adopt these units where environmental services headcount limits preclude fully manual protocols but capital budgets resist floor-standing automatic systems.
- Manual:Basic units dependent on operator execution of cleaning and disinfection steps with minimal mechanical assistance.
- Combination:Modular platforms accommodating multiple vessel types through interchangeable rack systems.
Automatic systems hold the largest share; momentum sits with combination platforms that retrofit aging infrastructure.
Installation Type:
Physical mounting configuration dictates plumbing retrofit requirements and sales cycle duration, with floor-standing units facing extended timelines in aging European hospital wards.
- Floor-Standing:High-capacity automatic systems with integrated steam supply and drainage infrastructure. Centralized sterile services departments in Germany drive bulk procurement of these units, though legacy plumbing in Southern European hospitals extends installation timelines.
- Wall-Mounted:Space-constrained configurations for retrofit installation in existing sluice rooms. United Kingdom NHS trusts favor these units in older ward buildings where floor load ratings prohibit heavy equipment.
- Portable:Mobile units on casters for flexible deployment across multiple wards or temporary isolation facilities.
- Built-In:Custom-integrated systems requiring architectural coordination during new construction or major renovation projects.
Floor-standing configurations dominate replacement demand; wall-mounted variants are climbing the fastest as retrofit constraints tighten.
End User:
Customer type segmentation aligns with regulatory scrutiny intensity and validation documentation requirements, separating acute care mandates from long-term care audit protocols.
- Hospitals:Acute care settings with HTM 01-04 compliance mandates in the United Kingdom and EU Medical Device Regulation enforcement driving validated thermal disinfection procurement. Infection control departments here face intensifying spore-reduction mandates from national health authorities.
- Long-Term Care Facilities:Nursing homes and assisted living operators with reduced throughput requirements and regional health authority audit obligations. Facilities across France and Italy adopt ultrasonic cleaning configurations to satisfy documentation requirements without expanding environmental services headcount.
- Home Care:Domestic settings with minimal regulatory oversight and reliance on manual or small-scale chemical disinfection.
- Rehabilitation Centers:Post-acute facilities with intermediate infection control protocols and mixed patient mobility profiles.
Hospitals command the largest installed base; long-term care facilities show the steepest expansion trajectory as aging demographics concentrate demand.
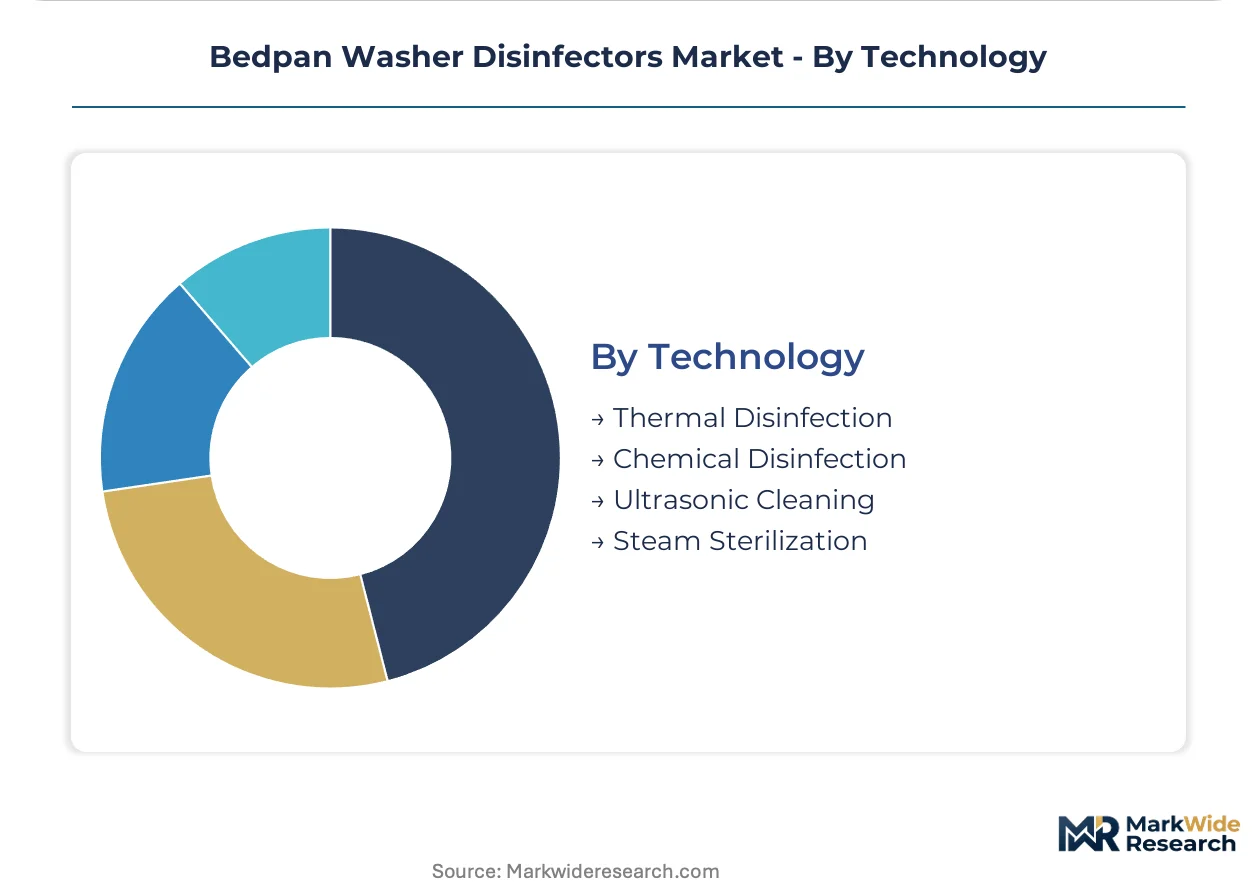
Technology:
Disinfection modality determines energy consumption profiles, cycle validation complexity, and compatibility with emerging IoT-enabled monitoring platforms.
- Thermal Disinfection:Automated cycles operating between 80°C and 93°C that eliminate cross-contamination pathways manual cleaning fails to address. This technology leads installed capacity across European acute care wards where EU Medical Device Regulation enforces updated clinical evaluation documentation.
- Ultrasonic Cleaning:High-frequency cavitation combined with reduced-cycle thermal finishing for digitized documentation workflows. Long-term care chains in France and Italy deploy these hybrid systems to capture real-time A0 value logging for infection control dashboards.
- Chemical Disinfection:Dosing-dependent protocols with lower capital costs but higher ongoing consumable expenditures and environmental discharge considerations.
- Steam Sterilization:High-pressure saturated steam achieving spore elimination beyond standard thermal disinfection parameters, primarily for specialized high-acuity applications.
Thermal disinfection retains the largest share; ultrasonic cleaning configurations are gaining share fastest as nursing home digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical logistics corridor underwrites continental Europe's dominance in bedpan washer disinfector distribution, channeling German-manufactured systems through Dutch sterile supply networks into British and French hospital procurement channels.
Germany
Centralized sterile services departments in Bavaria and North Rhine-Westphalia drive bulk purchasing of floor-standing automatic systems. The EU Medical Device Regulation 2017/745 accelerates replacement cycles for aging washer-disinfector fleets in university hospitals across Berlin and Hamburg.
United Kingdom
NHS trusts face intensifying HTM 01-04 compliance mandates that validate thermal disinfection equipment procurement. London and Southeast England concentrate demand for wall-mounted retrofit installations where older ward buildings prohibit heavy floor-standing units.
France
Nursing home chains in Île-de-France adopt ultrasonic cleaning configurations to satisfy regional health authority audit requirements. ANSM post-market surveillance protocols enforce stricter documentation for CE-marked equipment serving long-term care facilities.
Italy
Lombardy and Emilia-Romagna host manufacturing clusters supplying modular thermal disinfection platforms. Regional health authorities digitize compliance workflows, pushing facilities toward sensor-enabled cycle validation systems.
United States
The FDA's 510(k) premarket notification framework for Class II medical devices shapes validation testing protocols for thermal disinfection claims. Hospital procurement consortiums in the Northeast Corridor and California consolidate vendor relationships around predictive maintenance contracts.
Bedpan Washer Disinfectors Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified medical technology conglomerates with installed base leverage, specialized washer-disinfector fabricators with modular platform expertise, and regional equipment vendors serving price-sensitive long-term care segments. Dominant competitive moves include vertical integration into aftermarket service networks and technology licensing partnerships for IoT-enabled cycle monitoring.
Among European-based manufacturers, Getinge AB, STERIS Corporation, and MEIKO Maschinenbau GmbH & Co. KG represent the established tier. Getinge anchors the conglomerate archetype through central sterile supply department relationships. STERIS exemplifies the service-integrated model with direct field service networks. MEIKO occupies the modular specialization position, accommodating retrofit installations in aging infrastructure.
| Leading Market Players |
|---|
| Getinge AB |
| AT-OS S.p.A. |
| Arjo AB |
| Tuttnauer Europe B.V. |
| Belimed AG |
| Steelco S.p.A. |
| STERIS Corporation |
| DEKO MedTech |
| MEIKO Maschinenbau GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Overcapacity in Southern European washer-disinfector fabrication is compressing supplier pricing power while concentrating procurement leverage among German and British hospital consortiums. Utilization rates below threshold in Italian and Spanish assembly facilities force margin sacrifice on standard-tier equipment, even as premium automatic systems retain pricing resilience through HTM 01-04 and EU MDR compliance premiums.
Pricing Analysis
Volume-discount tiering structures separate MDR-validated premium systems from standard thermal units and economy manual configurations. Price differentiation rests on ISO 15883 compliance documentation depth and after-sales service bundling. Pricing pressure intensifies in the standard tier as procurement consortiums unbundle maintenance contracts from equipment purchases. Long-term care facilities exhibit highest price sensitivity; centralized sterile services departments in Germany show lowest.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized medical device fabricators in Lombardy and Bavaria holding chamber welding and control system integration capacity. Geographic supply concentration centers on Germany, Italy, and Switzerland for precision components. Raw material dependencies draw from Grade 316L stainless steel, nickel-molybdenum alloys, and programmable logic controllers. Single-source vulnerability runs through Swiss validation testing laboratories. Distribution runs through hospital procurement consortiums and GPO frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified biomedical engineers capable of A0 spore-reduction validation remain scarce outside centralized sterile services departments, constraining field service expansion and aftermarket revenue capture for equipment vendors.
For Market Incumbents: Pre-empt margin erosion from procurement consortiums by capturing direct field service networks before third-party maintenance providers consolidate. Anchor aftermarket parts distribution through exclusive technician certification programs. Invest in IoT-enabled cycle monitoring to lock in predictive maintenance contracts. For New Entrants and Emerging Players: Pursue ultrasonic cleaning configurations for French and Italian nursing home chains where digitized compliance documentation commands premium positioning. Target wall-mounted retrofit installations in United Kingdom NHS trusts with aging ward infrastructure. Lead with sensor-integrated A0 value logging as differentiated go-to-market proposition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular platform manufacturing as standardized control systems reduce per-unit engineering overhead. Long-term viability favors vendors with captive regulatory affairs functions navigating MDR documentation renewal. Watch for ISO 15883 amendment timing as inflection indicator for engineering redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | CE marking renewal under EU 2017/745 secures tender access in German university hospitals. |
| IoT Sensor Integration | Real-time A0 logging transmits compliance data directly to NHS infection control dashboards. |
| Field Service Network Expansion | Direct technician deployment captures aftermarket parts revenue from procurement consortiums. |
| Ultrasonic Module Development | Hybrid configurations address French nursing home audit requirements without headcount expansion. |
| Validation Testing Partnership | Swiss and German laboratory relationships accelerate ISO 15883 documentation for new entrants. |
Research Methodology
The analysis maps automatic, semi-automatic, and manual washer-disinfector configurations, each validated through infection control officers, biomedical engineering directors, hospital procurement committee members, and sterile services department heads. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, NHS Supply Chain tender records, and hospital procurement consortium frameworks. Bottom-up equipment shipment data triangulated against top-down healthcare capital expenditure flows.
Assumptions held regulatory enforcement timelines and stainless steel commodity volatility within observed bands while varying procurement consolidation intensity and long-term care digitization adoption. Segmentation dimensions modeled include product automation tier, installation configuration, end-user acute versus post-acute setting, and thermal versus ultrasonic disinfection modality. CAGRs derived from installed base replacement cycles and penetration rate trajectories across the projection horizon. Forecast inputs incorporated EU MDR amendment schedules and HTM 01-04 compliance mandate propagation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified medical technology conglomerates or specialized modular fabricators would shift outcomes. Regulatory enforcement acceleration or single-use bedpan substitution breakthroughs could revise demand trajectories. Quarterly review of NHS tender award volumes and ANSM post-market surveillance protocol updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
Patient Recliner Chair Market
Healthcare Equipment
Patient Recliner Market
Healthcare Equipment
Global Hospital Asset Management Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
North America Healthcare Machine Vision System Market
Healthcare Equipment
Middle East and Africa Hospital Furniture Market
Healthcare Equipment
Clinical Mobility Market
Healthcare Equipment
India Healthcare Machine Vision System Market