
 Real Estate Management Software Market | 2026-2036
Real Estate Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Real Estate Management Software Market Intelligence
Subscription-based pricing for software-defined property analytics is repositioning vendor economics toward recurring revenue pools. Yardi Systems leverages its vertical integration across residential and commercial modules to sustain platform stickiness. RealPage anchors its competitive position through deep channel control with multifamily operators. MRI Software differentiates via specialized investment-analysis tools tailored to institutional asset managers.
Real estate management software comprises integrated digital platforms that automate lease lifecycles, maintenance dispatch, financial reporting, and tenant relationship management through centralized databases with API-connected workflows. These systems serve commercial and residential property operators by reducing vacancy exposure and standardizing compliance documentation across distributed portfolios. Cloud-based deployment now leads adoption as property managers prioritize remote accessibility and automatic security patching over capital-intensive on-premises infrastructure. SaaS models capture expanding margin pools by converting upfront license sales into predictable annual contracts. Investment analysis functionality grows fastest among segments as institutional capital floods into real estate alternatives and demands real-time performance benchmarking.
The EU AI Act and GDPR impose algorithmic transparency requirements on automated tenant screening and predictive maintenance tools, forcing vendors to document decision logic and audit trails. The US SEC climate-disclosure rules and analogous ESG frameworks in Germany and Japan mandate granular energy and emissions tracking within property portfolios, elevating reporting modules from optional add-ons to core procurement criteria. Stakeholders must monitor how fragmented national data-localization laws reshape cloud architecture choices and vendor qualification standards.
Market Dynamics
Cloud migration mandates from the EU AI Act and parallel data-sovereignty frameworks are forcing property operators to requalify vendors around algorithmic transparency and cross-border data residency. This regulatory compression is accelerating procurement cycles while elevating compliance documentation from administrative overhead to competitive differentiator.
Growth Catalysts
- EU AI Act algorithmic transparency:Automated tenant screening and predictive maintenance tools now require documented decision logic, creating procurement pull for audit-ready platforms among German and French institutional asset managers.
- ESG disclosure mandates:The US SEC climate rules and Japan's GX League requirements are elevating energy-tracking modules from optional add-ons to core functionality in investment-grade portfolios.
- Remote accessibility imperatives:Distributed property management teams across the United States and Japan are prioritizing SaaS deployment models that enable real-time portfolio oversight without on-premises infrastructure.
Market Restraints
- Data localization compliance costs:Fragmented national requirements in Germany, France, and Japan are forcing vendors to maintain region-specific cloud instances, inflating operational overhead.
- Legacy system integration friction:On-premises ERP systems from the 2010s lack API connectivity, creating technical debt that slows cloud migration timelines for mid-sized operators.
- Specialized talent scarcity:Shortages of professionals combining real estate operations expertise with data engineering skills are constraining implementation velocity across commercial portfolios.
Strategic Opportunities
- Underpenetrated secondary US markets:Regional property managers in Texas and Florida lack institutional-grade analytics, creating white space for mid-market SaaS penetration.
- AI-driven predictive maintenance:Convergence of IoT sensor networks with machine learning models enables vacancy risk reduction through preemptive capital planning.
- Japan's GX League emissions framework:Corporate real estate owners face mandatory disclosure requirements, generating demand for automated carbon accounting modules.
Industry Challenges
- API standardization delays:Absence of universal data exchange protocols between property management platforms and accounting systems forces expensive custom integration work.
- Cybersecurity certification timelines:SOC 2 and ISO 27001 audits require 6-12 month preparation cycles, delaying market entry for emerging vendors serving institutional buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real Estate Management Software Market |
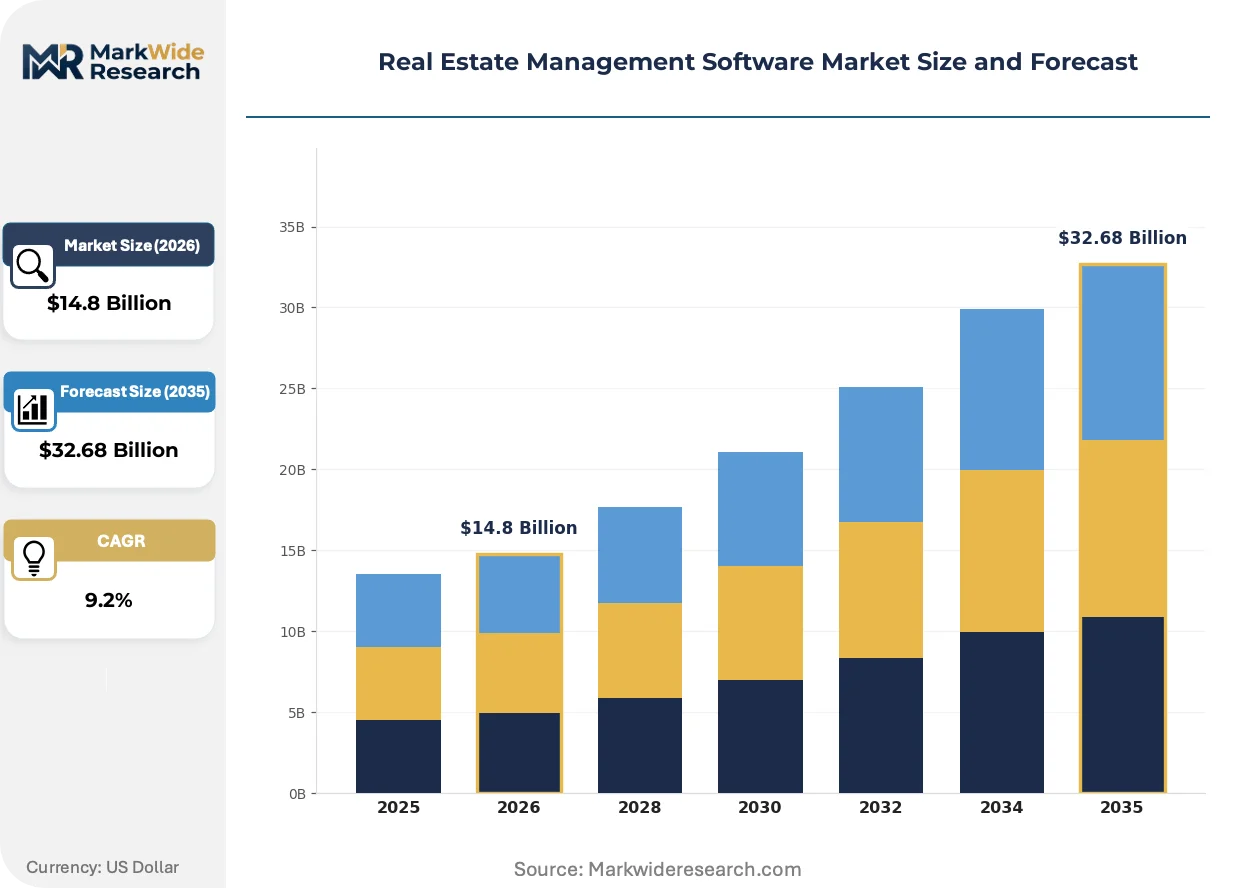
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Property Management, Lease Management, Maintenance Management, Investment Analysis Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Property Managers, Real Estate Agents, Corporates, Investors Functionality: Accounting, Reporting, CRM, Marketing Automation |
| Companies Covered | Yardi Systems, Inc., RealPage, Inc., MRI Software LLC, AppFolio, Inc., Entrata, Inc., CoStar Group, Buildium, ResMan, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real Estate Management Software Market Strategic Shifts & Innovations
Blockchain-enabled lease tokenization and embedded AI analytics are restructuring how property data flows between operators, investors, and regulators. These shifts are compressing reporting cycles while fragmenting traditional vendor control over transaction records.
Smart contract infrastructure for commercial lease administration is decentralizing escrow and payment verification away from centralized property management platforms. Mid-market multifamily operators in the United States are piloting these tools for automated rent collection and security deposit handling. This architecture reduces intermediary fees but forces incumbents to rebuild core financial modules around distributed ledger standards.
The EU AI Act's risk-classification framework for automated decision systems is mandating human-in-the-loop review protocols for tenant screening algorithms. Property operators deploying AI-driven applicant scoring must now maintain auditable override logs and bias testing documentation. German and French asset managers are responding by procuring platforms with built-in explainability dashboards rather than retrofitting legacy systems.
Subscription-based procurement of modular analytics is displacing perpetual license purchases among institutional investors. Japanese REITs and US pension fund advisors now demand month-to-month access to performance benchmarking tools without full platform commitments. This unbundling pressures vendors to maintain standalone pricing for investment analysis functionality previously bundled into enterprise contracts.
Real Estate Management Software Market Segmentation
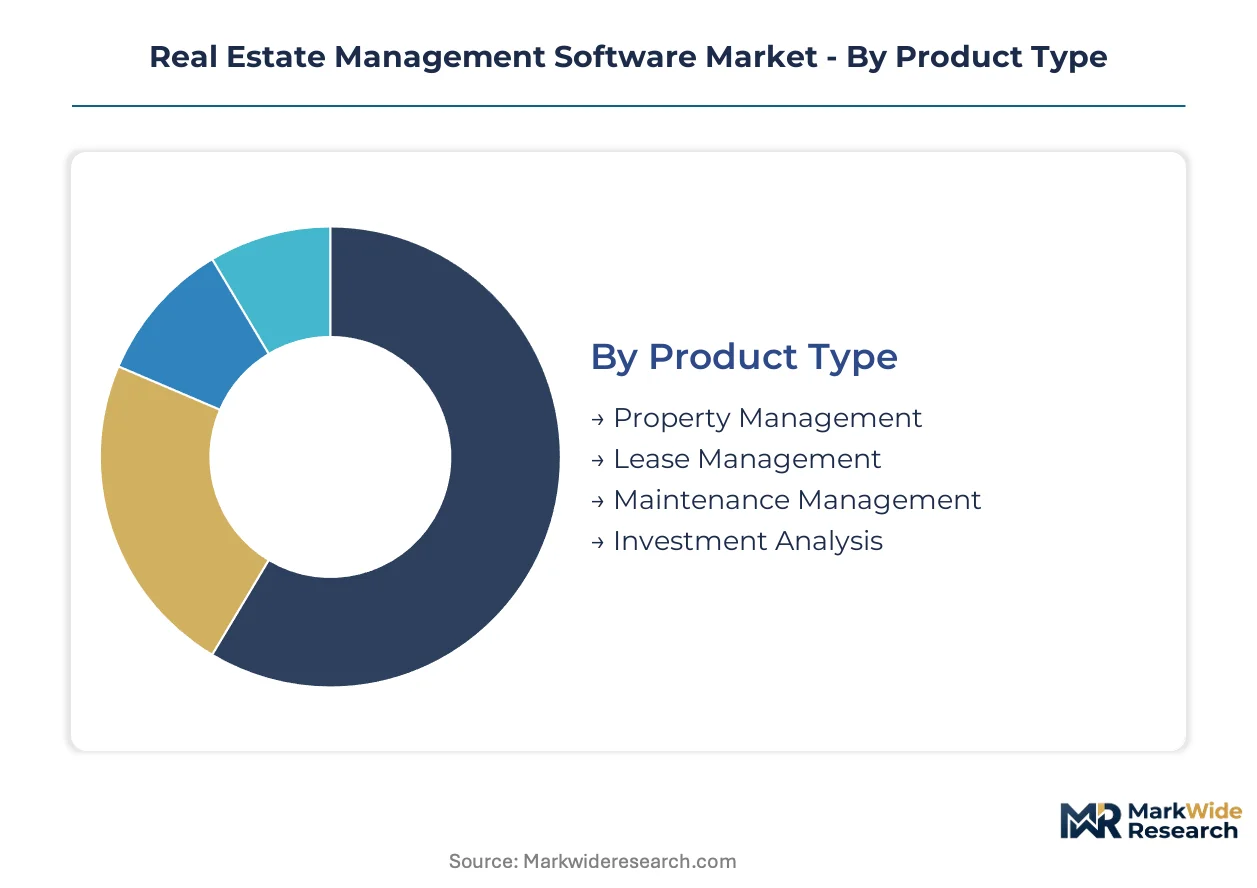
Segmentation in real estate management software reveals how procurement criteria fragment across operational needs and regulatory contexts. Vendors must align product architecture with distinct buyer workflows spanning lease administration, portfolio analytics, and compliance documentation.
Product Type:
Supply concentration among platform vendors clusters around modules addressing the highest-friction operational workflows in institutional portfolios.
- Property Management:Core platforms automate rent collection, tenant communications, and vacancy tracking through centralized dashboards. Demand concentrates with commercial operators in the United States seeking unified workflow visibility across dispersed assets.
- Lease Management:Specialized tools handle document generation, renewal triggers, and compliance deadline tracking. German asset managers are driving procurement here as the EU AI Act mandates auditable decision trails for automated lease terms.
- Maintenance Management:Work order dispatch and vendor coordination modules reduce capital expenditure surprises.
- Investment Analysis:Performance benchmarking and scenario modeling tools attract institutional capital allocators.
Property Management absorbs the bulk of installed capacity; Investment Analysis is expanding most quickly.
Deployment Model:
Cost tier differentiation separates buyers with capital reserves for infrastructure ownership from those prioritizing operational flexibility.
- Cloud-Based:Fully managed infrastructure eliminates server maintenance burdens and enables automatic security patching. Japanese REITs are prioritizing these deployments to satisfy METI guidance on data residency without on-premises capital outlay.
- SaaS:Subscription pricing converts upfront license costs into predictable operational expenditures. Mid-market multifamily operators in Texas and Florida favor this model for rapid scaling without IT staffing expansion.
- On-Premises:Self-hosted installations persist among operators with legacy ERP dependencies or stringent data control requirements.
- Hybrid:Split architectures keep sensitive financial data local while pushing tenant-facing applications to cloud instances.
Cloud-Based deployments dominate new procurement; SaaS is climbing the fastest among institutional buyers.
End User:
Application-specific requirements fragment feature prioritization across buyer categories with divergent workflow intensities.
- Property Managers:Daily operational platforms emphasize mobile accessibility and real-time vacancy alerts. United States-based residential operators demand tight integration with payment processors and maintenance vendor networks.
- Investors:Portfolio-level analytics and performance attribution tools support capital allocation decisions. German pension funds are procuring these capabilities to meet CSRD disclosure requirements across real estate allocations.
- Real Estate Agents:Transaction-focused tools prioritize listing management and client relationship tracking.
- Corporates:Occupier-focused platforms manage lease accounting and space utilization across enterprise real estate footprints.
Property Managers absorb the bulk of installed capacity; Investors are gaining share fastest.
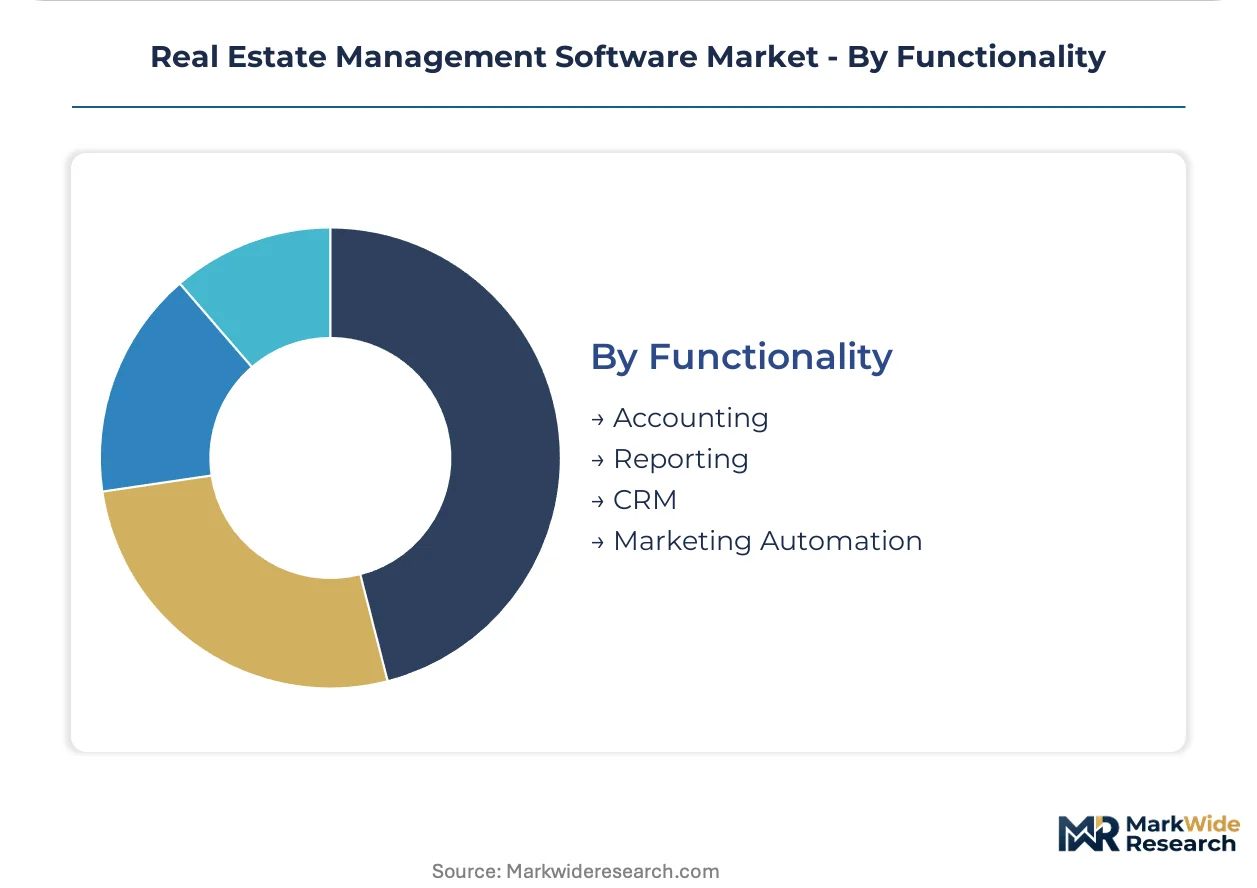
Functionality:
Margin structure varies sharply between compliance-mandated modules and discretionary productivity tools.
- Accounting:General ledger, accounts payable, and financial reconciliation engines form the technical backbone of property operations. Demand concentrates with United States commercial operators navigating SEC climate disclosure integration with financial statements.
- Reporting:Customizable dashboards and regulatory filing generators have shifted from optional to essential. Japanese corporate owners under GX League mandates are procuring automated carbon accounting modules bundled here.
- CRM:Tenant relationship and prospect pipeline management tools support leasing velocity.
- Marketing Automation:Listing distribution and lead nurturing capabilities reduce vacancy exposure.
Accounting absorbs the bulk of installed capacity; Reporting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors software development for property technology platforms, with venture funding clustering around AI-enabled analytics startups serving institutional asset managers.
United States
Institutional capital deployment into real estate alternatives drives procurement of investment analysis modules. SEC climate disclosure rules mandate granular emissions tracking across portfolios. Dallas-Fort Worth multifamily operators are piloting blockchain-enabled lease administration for automated rent collection.
Germany
CSRD requirements force pension funds to integrate real estate ESG data into portfolio reporting systems. The EU AI Act mandates algorithmic transparency for automated tenant screening tools. Frankfurt asset managers are procuring platforms with built-in explainability dashboards for compliance documentation.
Japan
METI guidance on data residency accelerates cloud migration among REITs seeking operational flexibility. The GX League emissions framework mandates automated carbon accounting for corporate real estate owners. Tokyo-based institutional investors demand month-to-month access to performance benchmarking tools.
United Kingdom
Institutional landlords prioritize SaaS deployment models enabling remote portfolio oversight across distributed assets. GDPR compliance requirements elevate audit-ready platforms in procurement criteria. London commercial operators are consolidating lease administration and maintenance workflows onto unified cloud platforms.
Canada
Pension fund advisors drive demand for modular analytics subscription models without full platform commitments. Privacy regulations require documented data residency controls for cross-border cloud architectures. Toronto property managers are adopting hybrid deployments keeping sensitive financial data local while pushing tenant-facing applications to cloud instances.
Real Estate Management Software Market Key Industry Players
Capital-heavy platform developers compete with asset-light specialized vendors for institutional procurement contracts. The vendor base clusters around three tiers: vertically integrated suite providers, modular point-solution specialists, and emerging AI-native entrants. Strategic differentiation centers on API ecosystem breadth and compliance documentation depth. Dominant competitive moves include geographic expansion into underpenetrated secondary markets and technology licensing partnerships with IoT sensor networks.
Within the vertically integrated tier, Yardi Systems, Inc. and RealPage, Inc. occupy positions exemplifying platform stickiness through residential and commercial module breadth. MRI Software LLC represents the specialized archetype with investment-analysis capabilities tailored to institutional asset managers. AppFolio, Inc. anchors the mid-market SaaS segment serving regional operators seeking rapid deployment without IT staffing expansion.
| Leading Market Players |
|---|
| Yardi Systems, Inc. |
| RealPage, Inc. |
| MRI Software LLC |
| AppFolio, Inc. |
| Entrata, Inc. |
| CoStar Group |
| Buildium |
| ResMan |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between SOC 2 Type II-compliant enterprise suites and unaudited mid-market offerings manifests in both subscription pricing power and cloud infrastructure sourcing strategies. Tier-one vendors command premium SaaS multiples through dedicated regional instances, while price-sensitive buyers in Texas and Florida accept shared-tenant architectures with longer patching cycles.
Pricing Analysis
Margin tightening in the mid-market SaaS tier reflects customer acquisition cost inflation as regional property managers demand free migration support from legacy on-premises systems. Three-tier pricing structure across enterprise, professional, and starter levels segments by API call volume and compliance documentation depth. Cost-down pressure on starter subscriptions accelerates because venture-backed entrants subsidize seats to capture workflow data. Institutional asset managers in Germany and Japan exhibit lowest price sensitivity, prioritizing audit-ready platforms over per-seat economics.
Supply Chain Analysis
Dual-sourcing requirements from Japanese REITs and German pension funds mandate redundant cloud region qualification across at least two hyperscaler providers. Software development concentrates in the United States, India, and Ireland, with implementation services drawing from regional partner networks in target markets. Supply chain risk centers on single-source vulnerability for AI model training data licensed from proprietary property transaction databases. Distribution runs through direct enterprise sales teams for institutional contracts and self-service portals for mid-market subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
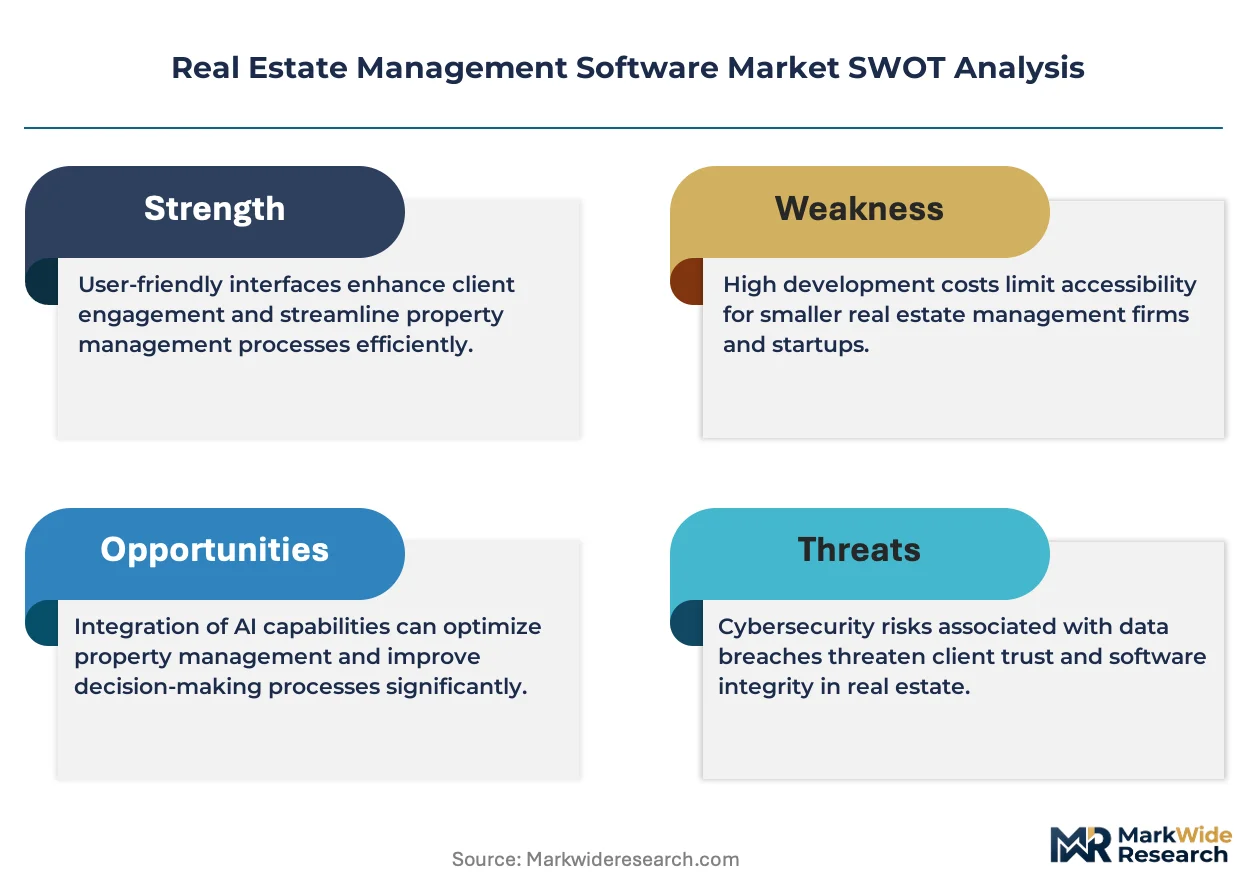
Talent scarcity for professionals combining real estate operations expertise with data engineering skills props pricing for implementation services and sustains vendor margins against commoditization pressure.
For Market Incumbents: Anchor platform stickiness through backward integration into IoT sensor networks for predictive maintenance, deepening the data moat against modular point-solution entrants. Prioritize SOC 2 and ISO 27001 certification investments to defend procurement position as Japanese and German buyers elevate security documentation to mandatory criteria. Channel control with multifamily operators in Texas and Florida remains the critical lever against SaaS challengers.
For New Entrants and Emerging Players: AI-native explainability dashboards for EU AI Act compliance represent the most penetrable wedge, as German and French asset managers seek audit-ready tenant screening tools without full platform replacement. Target secondary US markets in Texas and Florida where regional property managers lack institutional-grade analytics and tolerate higher implementation risk. Lead with month-to-month subscription models that unbundle investment analysis functionality from core property management modules.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized compliance-documentation vendors given CSRD and GX League disclosure mandates accelerating procurement cycles. Long-term viability favors platforms with proven API ecosystem breadth and existing hyperscaler partnership frameworks. The signal to watch is consolidation velocity among mid-market SaaS providers as customer acquisition costs compress returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies lease administration with maintenance workflows, reducing vacancy exposure for commercial operators. |
| Geographic Expansion | Captures underpenetrated regional markets in Texas and Florida lacking institutional-grade analytics capabilities. |
| Strategic Partnership | Secures IoT sensor network access for AI-driven predictive maintenance and preemptive capital planning. |
| Acquisition of Specialist Firm | Absorbs modular compliance-documentation vendors serving CSRD and GX League disclosure requirements. |
| Product Launch | Introduces explainability dashboards for EU AI Act algorithmic transparency mandates in Germany and France. |
Research Approach
Multi-period observation of cloud migration timelines, regulatory procurement criteria, and vendor pricing model shifts anchored the trend analysis, supplemented by interviews with property management executives, institutional asset managers, platform engineers, and compliance officers. Primary fieldwork drew from SEC filings, EU regulatory guidance documents, METI data residency advisories, and hyperscaler infrastructure expansion disclosures. Bottom-up sizing of vendor revenue pools triangulated against top-down real estate AUM growth projections.
Input-output matrices mapped deployment model adoption, organization size, vertical specialization, integration complexity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate blending weighted by procurement cycle visibility. Forecast inputs incorporated cloud infrastructure capacity expansion schedules and ESG disclosure mandate implementation timelines.
Several conditions sit outside the modeled scope, including unannounced M&A activity, abrupt data localization law changes, and hyperscaler service discontinuations. Deviation in regulatory enforcement intensity or AI Act implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Property Management
Space Planning and Space Management Solutions Market
Property Management
Hungary Warehousing Sector Market
Property Management
Europe Self Storage Market
Property Management
Property Management Software Market
Property Management
South Korea Self-Storage Market
Property Management
Residential Property Management Market
Property Management
United States Property Management Market
Property Management
US Property Management Software Market
Property Management
Spain Warehousing Market
Property Management
Real Estate (Property) Management Market
Property Management
Property Management Service Market
Property Management
Qatar Flexible Office Space Market