
 South America Confectionery Market | 2026-2036
South America Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
South America Confectionery Market Insights
Brazil is tilting toward expanded cocoa processing capacity with new industrial clusters emerging in Bahia. Arcor S.A.I.C. leverages its vertically integrated sugar-to-candy operations across Argentina and Brazil. Cacau Show sustains its dominant position in Brazil's premium chocolate segment through controlled retail expansion. Mondelēz International anchors its regional supply chain with manufacturing facilities in key South American metropolitan zones.
Confectionery comprises sweet food products manufactured from sugar or chocolate as primary substrates, typically incorporating flavoring agents, emulsifiers, and texturizing ingredients through processes of conching, panning, or depositing. These products serve consumer indulgence needs, gift-giving occasions, and impulse purchase moments across retail and foodservice channels. Chocolate commands the largest value share within product type segmentation, while gummies represent the fastest-growing format driven by gelatin and pectin innovation. Online retail distribution is expanding rapidly as logistics networks penetrate secondary cities, though supermarkets retain the deepest margin pools through shelf-space negotiations and promotional programming.
ANVISA in Brazil mandates front-of-package warning labels for high sugar content, directly influencing reformulation strategies across manufacturers. Argentina's national food code and Colombia's INVIMA standards enforce additive limits and hygiene protocols that determine import eligibility and local production compliance. Stakeholders must monitor evolving regulatory stringency on nutritional claims while calibrating portfolio mixes between indulgence positioning and permissible health-oriented messaging.
Market Dynamics
ANVISA's front-of-package warning label mandate is forcing reformulation across Brazilian confectionery portfolios, compressing sugar-dependent product lines while accelerating alternative sweetener adoption and clean-label positioning strategies.
Growth Catalysts
- Premium chocolate demand:Urban middle-class consumers in São Paulo and Minas Gerais are driving double-digit volume expansion in dark chocolate and single-origin cacao segments, with specialty retailers capturing disproportionate basket value.
- E-commerce logistics penetration:Last-mile delivery networks reaching secondary cities in Colombia and Peru are unlocking impulse purchase occasions previously constrained by traditional retail density.
- INVIMA additive modernization:Colombia's streamlined import protocols for pectin-based gummies are accelerating product registration timelines and reducing market entry friction for regional manufacturers.
Market Restraints
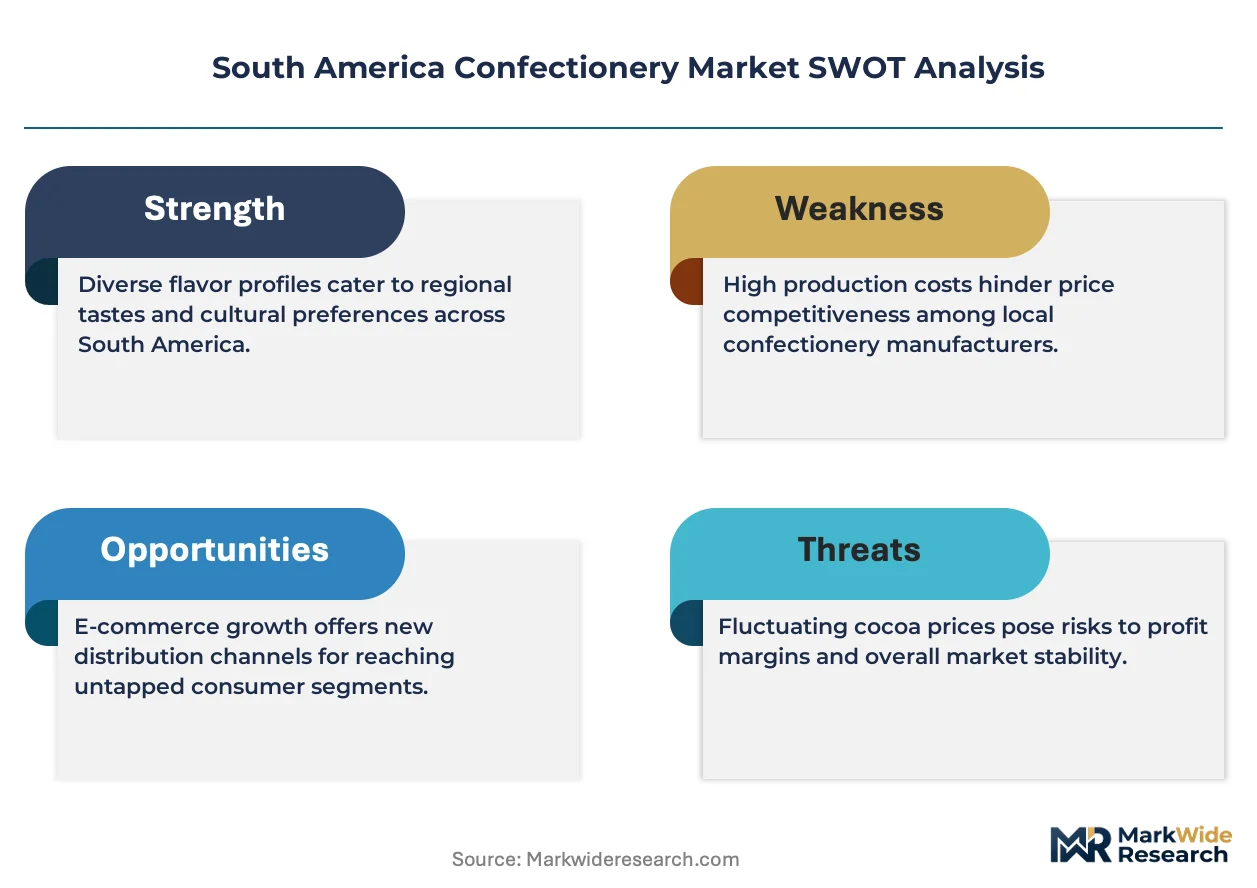
- Cocoa butter price volatility:Futures contracts for West African supply are transmitting cost pressure directly into Brazilian chocolate margins, with limited backward integration options for mid-tier processors.
- Argentina import substitution mandates:Local content requirements for sugar refining are fragmenting supply chains and extending lead times for multinational formulations dependent on standardized inputs.
- Stevia aftertaste limitations:Technical constraints in masking bitterness are capping substitution rates in children's confectionery, where palatability thresholds remain highest.
Strategic Opportunities
- Bahia cocoa cluster expansion:New processing infrastructure in Brazil's northeastern state is creating captive supply integration opportunities for brands seeking origin-controlled sourcing narratives.
- Functional gummy formats:Collagen and vitamin-fortified pectin matrices are capturing adult wellness segments previously unserved by traditional sugar confectionery positioning.
- Supermarket private-label acceleration:Chains across Chile and Uruguay are expanding controlled-assortment candy programs, creating white-space for co-manufacturing partnerships with regional processors.
Industry Challenges
- Reformulation R&D timelines:Compressed product development cycles to meet ANVISA compliance deadlines are straining sensory testing capacity and accelerating talent competition for food scientists.
- Legacy ERP integration:Batch traceability requirements for INVIMA and ANVISA are forcing mid-size manufacturers to replace paper-based systems, absorbing capital that would otherwise flow to capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Confectionery Market |
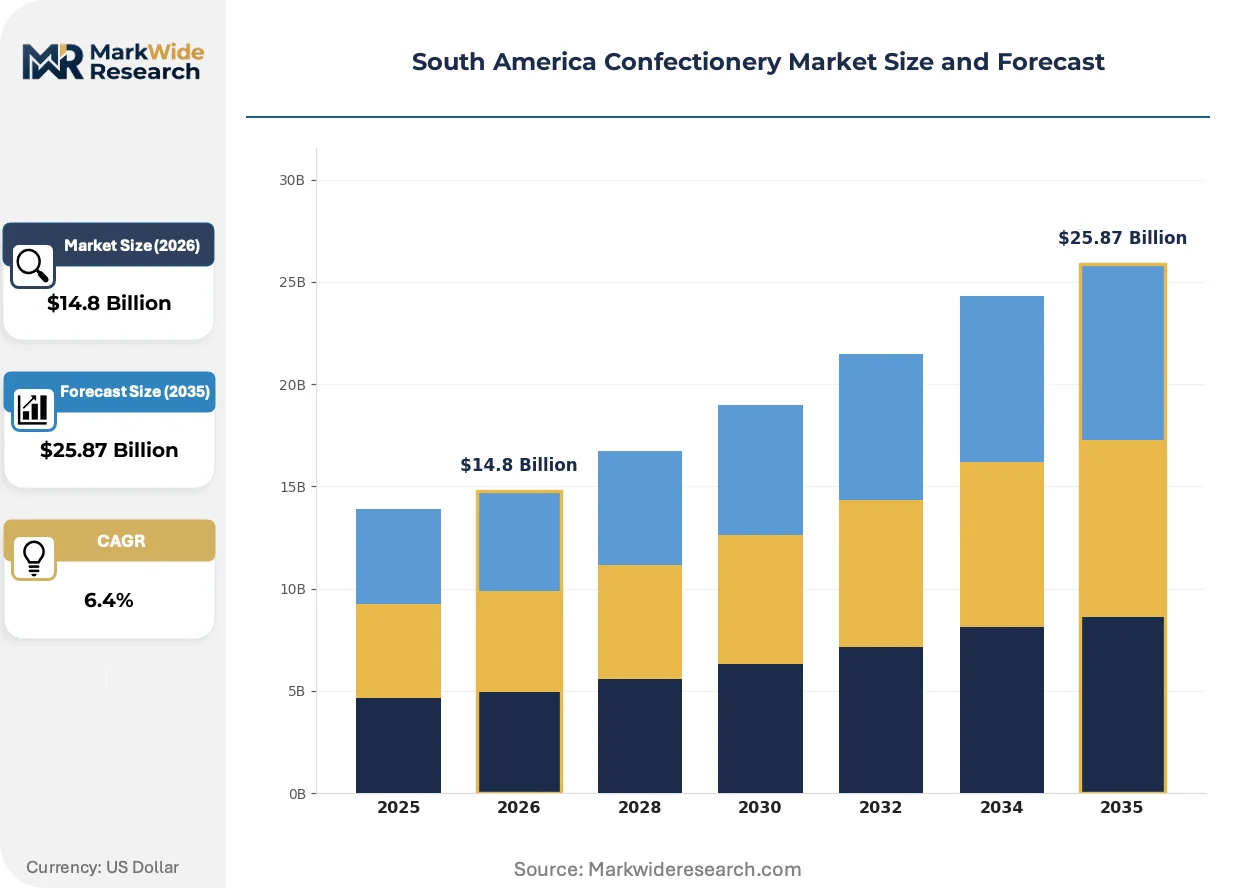
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Hard Candy, Gummies, Mints Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Customer Type: Children, Teenagers, Adults, Seniors Flavor Profile: Fruity, Minty, Nutty, Spicy |
| Companies Covered | Arcor S.A.I.C., Cacau Show, Colombina SA, Mondelēz International Inc., Nestlé SA, Ferrero International SA, Mars Incorporated, Barry Callebaut AG, Lindt & Sprüngli, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Confectionery Market Trends and Innovations
Clean-label fermentation and precision drying technologies are rewriting ingredient sourcing protocols, while regulatory disclosure mandates and channel fragmentation are simultaneously compressing legacy business models and opening novel revenue architectures.
Pectin-hydrocolloid hybrid gelling systems are rendering obsolete traditional starch-based molding processes in Brazilian gummy manufacturing. Mid-tier producers in São Paulo state are retrofitting depositing lines at accelerated capex cycles, enabling texture profiles previously restricted to premium imported SKUs and collapsing the quality tier differentiation that sustained import premiums.
ANVISA's octagonal warning label regime is mandating sugar threshold disclosures that directly determine shelf placement economics. Manufacturers are responding with dual-SKU strategies—reformulated compliant lines for modern trade, legacy formulations for traditional channels—creating portfolio complexity that favors scaled players with dedicated regulatory affairs functions.
Direct-to-consumer subscription boxes are capturing recurring revenue from gifting occasions in Chile's Santiago metropolitan region and Colombia's Bogotá high-income districts. Specialty chocolate brands are bypassing supermarket slotting fee structures entirely, building first-party data assets that enable flavor personalization and seasonal product drops without retail intermediary margin extraction.
South America Confectionery Market Segmentation
Segmentation in South America's confectionery sector reveals how regulatory pressure, channel evolution, and generational taste shifts create divergent growth trajectories across product formats and consumer cohorts. Understanding these fault lines enables manufacturers to calibrate reformulation investments and route-to-market priorities against distinct margin and volume profiles.
Product Type:
After-sales intensity varies sharply across product categories, with chocolate demanding sophisticated temperature-controlled logistics and gummies requiring technical support for pectin-hydrocolloid processing transitions.
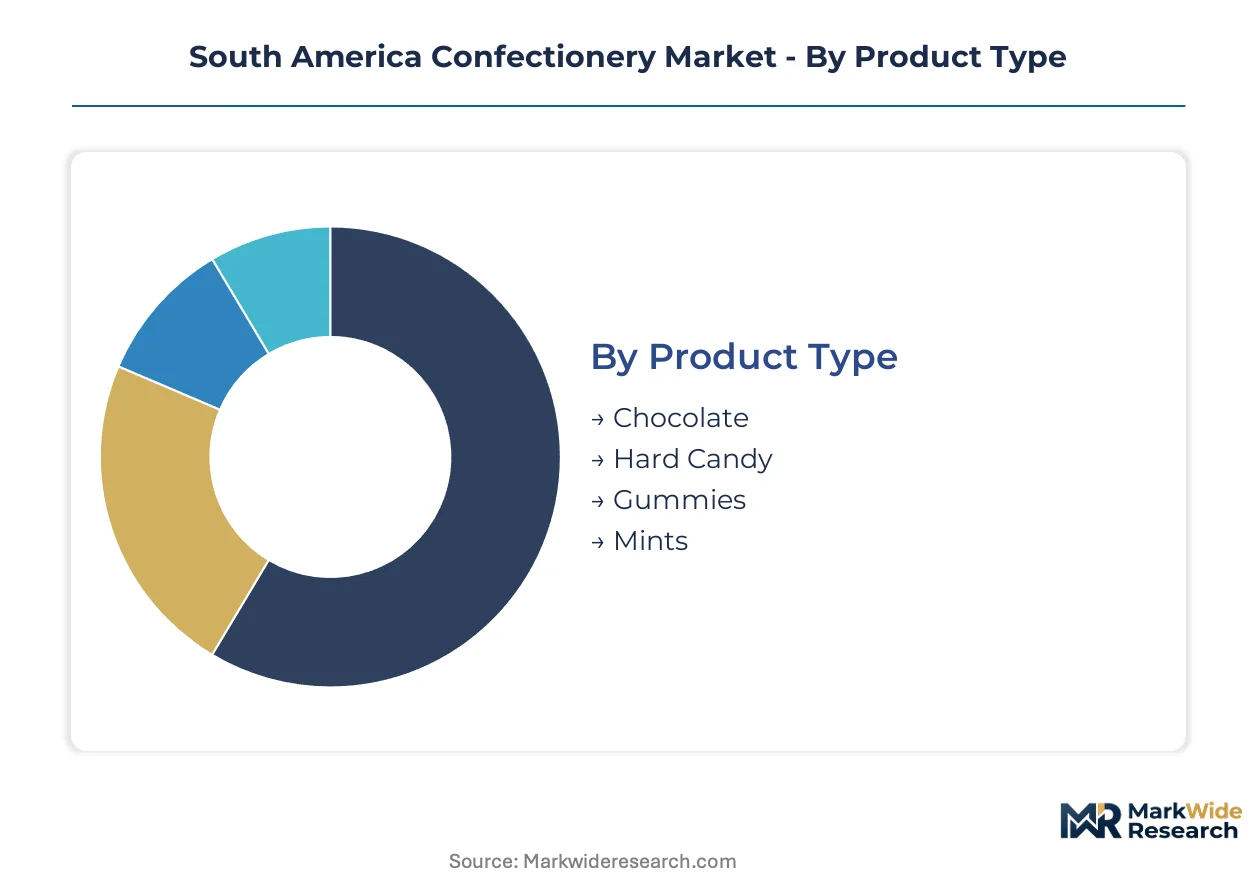
- Chocolate:Formulations center on cocoa butter, cocoa mass, and emulsifiers, with conching duration determining texture granularity. São Paulo and Minas Gerais urban consumers drive premium dark chocolate and single-origin cacao demand as ANVISA sugar disclosure rules compress legacy milk chocolate margins.
- Gummies:Pectin and gelatin matrices enable chewy texture profiles, with depositing-line retrofits accelerating across São Paulo state manufacturers. Colombian INVIMA streamlined protocols are reducing registration friction for pectin-based imports, unlocking faster SKU rotation.
- Hard Candy:High-boiled sucrose or isomalt bases deliver glassy amorphous structures; Brazil's sugar refining clusters in São Paulo state provide backward integration for regional producers.
- Mints:Compressed tablet or panned formats incorporate menthol and cooling agents; adult breath-freshening occasions concentrate in Brazilian and Argentine urban professional segments.
Chocolate holds the largest share; momentum sits with gummies as pectin innovation collapses quality-tier differentiation.
Distribution Channel:
Channel economics stratify sharply, with supermarkets extracting deepest margin pools through slotting fees while online retail captures impulse occasions previously constrained by physical retail density.
- Supermarkets:Controlled-assortment programs and private-label expansion across Chile and Uruguay create co-manufacturing white-space. Chains leverage shelf-space negotiations and promotional programming to capture disproportionate basket value in Brazil's southeastern states.
- Online Retail:Last-mile networks penetrating secondary Colombian and Peruvian cities unlock recurring gifting revenue. Santiago and Bogotá high-income districts see specialty chocolate brands bypass slotting fees entirely through direct-to-consumer subscription models.
- Convenience Stores:Impulse-oriented formats with limited SKU depth; Argentina's import substitution mandates fragment supply chains for standardized multinational inputs.
- Specialty Stores:Controlled retail expansion sustains premium positioning; Cacau Show's Brazilian network exemplifies origin-controlled sourcing narratives and personalized flavor drops.
Supermarkets dominate volume throughput; online retail is expanding most quickly as logistics infrastructure penetrates secondary metropolitan zones.
Customer Type:
Generational palatability thresholds determine sweetener substitution feasibility, with children's segments resisting stevia aftertaste while adult wellness positioning accelerates functional fortification.
- Adults:Collagen and vitamin-fortified pectin matrices capture wellness-oriented segments previously unserved by traditional confectionery. Brazilian ANVISA warning labels drive clean-label positioning among health-conscious urban professionals.
- Children:Highest palatability thresholds constrain alternative sweetener adoption; technical bitterness-masking limitations cap reformulation rates in sugar-dependent product lines.
- Teenagers:Social sharing and novelty-seeking behaviors concentrate in gummy and sour formats; e-commerce penetration aligns with digital-native purchase patterns.
- Seniors:Sugar-conscious and functional benefit priorities; reduced-portion and sugar-free hard candy demand concentrates in Argentine and Uruguayan aging demographics.
Adults command the highest per-capita expenditure; teenagers are gaining share fastest through social-driven format innovation and digital channel affinity.
Flavor Profile:
Flavor development cycles compress as regional manufacturers compete with imported premium positioning, with local fruit extracts and native Amazonian ingredients emerging as differentiation vectors.
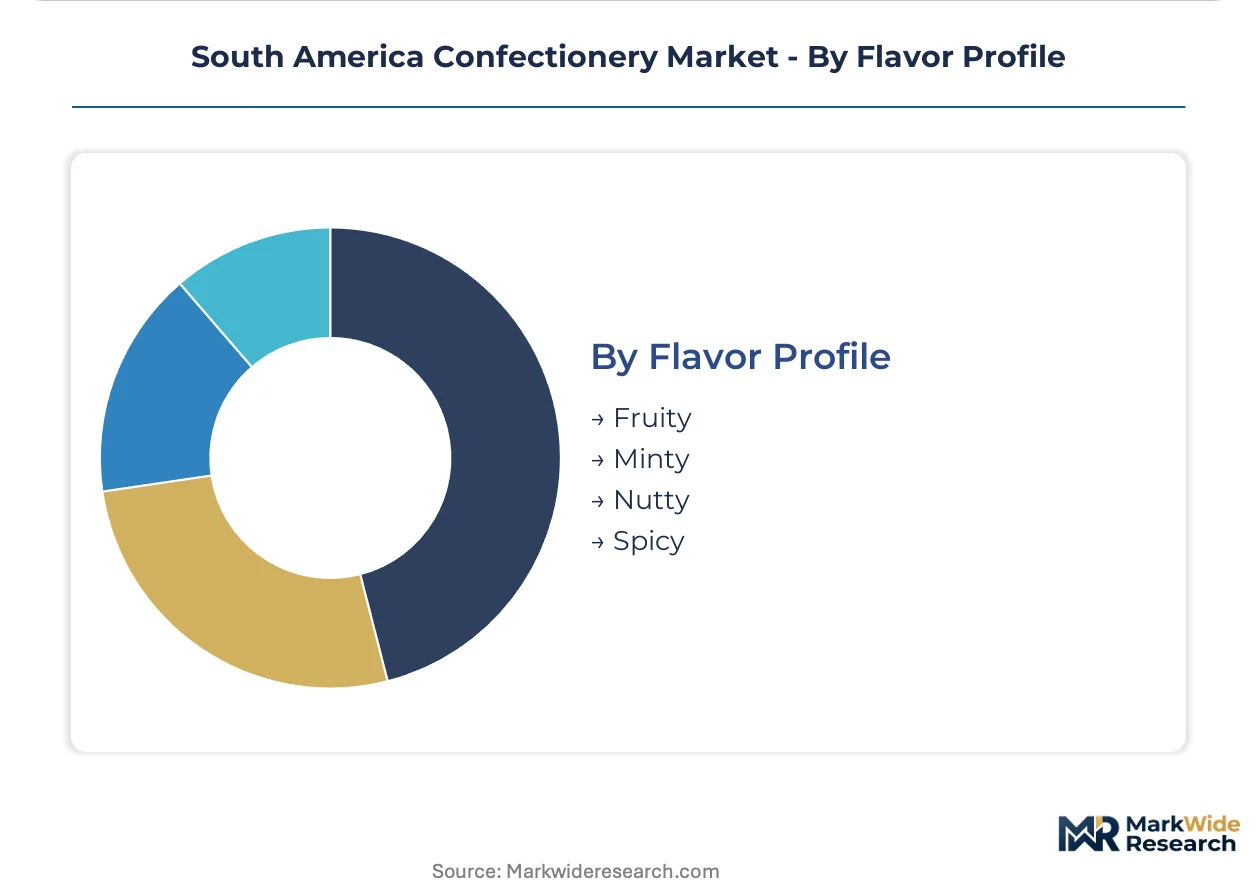
- Fruity:Native Amazonian açaí, cupuaçu, and passion fruit extracts enable origin-controlled sourcing narratives. Brazilian Bahia cocoa clusters integrate with regional fruit processing infrastructure.
- Nutty:Hazelnut, almond, and peanut inclusions anchor premium chocolate praline segments; Argentina's nut processing capacity supports regional supply.
- Minty:Cooling agent formulations serve breath-freshening and digestive positioning; adult professional demand concentrates in urban Brazilian and Chilean markets.
- Spicy:Chili and cinnamon infusions capture experimental and gifting occasions; limited but growing traction in Colombian and Peruvian premium segments.
Fruity profiles hold the largest share; nutty formulations show the steepest expansion trajectory as single-origin and praline positioning penetrates mid-tier price points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's front-of-package warning label mandate in Brazil is compressing sugar-dependent product lines while accelerating reformulation investments across the continent's largest confectionery market. Brazil's regulatory stringency is transmitting competitive pressure into neighboring markets as manufacturers harmonize portfolios across customs unions.
Brazil
São Paulo and Minas Gerais urban consumers drive premium dark chocolate and single-origin cacao demand as ANVISA disclosure rules compress legacy milk chocolate margins. Bahia's emerging cocoa processing clusters create captive supply integration for brands pursuing origin-controlled sourcing narratives. Supermarket chains leverage shelf-space negotiations to capture disproportionate basket value in southeastern states.
Argentina
Import substitution mandates for sugar refining fragment supply chains and extend lead times for multinational formulations dependent on standardized inputs. Arcor's vertically integrated sugar-to-candy operations anchor domestic production capacity across multiple provinces. Buenos Aires metropolitan demand concentrates in premium chocolate gifting segments.
Colombia
INVIMA's streamlined additive modernization protocols reduce registration friction for pectin-based gummy imports and accelerate SKU rotation timelines. Bogotá's high-income districts see specialty chocolate brands bypass supermarket slotting fees through direct-to-consumer subscription models. Last-mile networks penetrating secondary cities unlock impulse purchase occasions.
Chile
Santiago metropolitan region subscription boxes capture recurring revenue from gifting occasions as specialty brands build first-party data assets. Supermarket private-label acceleration creates white-space for co-manufacturing partnerships with regional processors. Adult wellness positioning drives collagen-fortified pectin matrix adoption.
Peru
E-commerce logistics penetration into secondary metropolitan zones expands impulse purchase access beyond traditional retail density constraints. Native Amazonian açaí and cupuaçu extracts enable origin-controlled sourcing differentiation for regional manufacturers. Lima's urban middle-class concentrates demand in premium chocolate segments.
South America Confectionery Market Competitive Landscape
Capability concentration sits with vertically integrated domestic specialists; scale advantage sits with multinational processors with regional manufacturing footprints. The market structures around three tiers: global FMCG conglomerates with dedicated regulatory affairs functions, mid-size regional processors retrofitting depositing lines for pectin-hydrocolloid transitions, and specialty retailers building direct-to-consumer subscription infrastructure. Dominant competitive moves include portfolio dual-SKU strategies separating reformulated compliant lines from legacy formulations, and captive supply integration into Bahia cocoa clusters.
Within the vertically integrated regional tier, Arcor S.A.I.C. exemplifies sugar-to-candy operational scope across Argentina and Brazil. Among Brazil-based premium specialists, Cacau Show occupies a position in controlled retail expansion and origin-controlled sourcing narratives. At the multinational scale end, Mondelēz International anchors regional supply chain positioning through metropolitan manufacturing facilities. These three represent distinct strategic archetypes: backward-integrated commodity processor, specialty retail brand builder, and global scale platform with localized compliance adaptation.
| Leading Market Players |
|---|
| Arcor S.A.I.C. |
| Cacau Show |
| Colombina SA |
| Mondelēz International Inc. |
| Nestlé SA |
| Ferrero International SA |
| Mars Incorporated |
| Barry Callebaut AG |
| Lindt & Sprüngli |
| Others |
Pricing and Supply Chain Analysis
Cocoa butter futures volatility from West African supply transmits directly into Brazilian chocolate processor margins, compressing standard-tier pricing spreads while forcing manufacturers toward backward integration into Bahia clusters or premium positioning to escape commodity cost cycles.
Pricing Analysis
Brazilian standard chocolate sits at a discount to Argentine and Chilean equivalents due to ANVISA compliance costs and local sugar refining capacity. Three-tier pricing structure across premium single-origin, standard mass-market, and economy private-label levels separates products by cacao percentage and origin certification. Pricing pressure stems from supermarket slotting fee escalation in São Paulo state, where chains extract disproportionate basket value through shelf-space negotiations. Private-label buyers exhibit highest price sensitivity, while gift-oriented consumers in Bogotá and Santiago tolerate significant premiums for controlled-origin narratives.
Supply Chain Analysis
Extended payment terms from Brazilian supermarket chains force mid-tier processors to rely on supply-chain finance facilities, elevating working capital costs that concentrate margin pressure on São Paulo state manufacturers. Raw material sourcing draws from Ivory Coast and Ghana for cocoa butter, São Paulo state for refined sucrose, and Colombia for pectin hydrocolloids. Single-source vulnerability concentrates in West African cocoa butter supply, with limited regional alternatives. Distribution runs through controlled-assortment supermarket programs in Brazil's southeast, direct-to-consumer subscription infrastructure in Chile and Colombia, and traditional wholesale in Argentina's interior provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of food scientists capable of stevia bitterness masking and pectin-hydrocolloid formulation is constraining reformulation velocity, creating acquisition premiums for technical talent clusters and R&D-ready facilities.
For Market Incumbents: Entrench regulatory compliance advantage by building dedicated ANVISA affairs functions that mid-tier competitors cannot replicate. Acquire depositing-line retrofit capacity in São Paulo state before equipment lead times extend. Prioritize backward integration into Bahia cocoa processing to escape West African futures volatility and capture origin-controlled pricing premiums.
For New Entrants and Emerging Players: Pursue functional gummy white-space in adult wellness segments, where collagen and vitamin fortification commands price premiums unconstrained by children's palatability thresholds. Target Colombia's secondary cities through e-commerce last-mile partnerships, exploiting INVIMA streamlined registration to outpace multinational SKU velocity. Launch direct-to-consumer subscription models in Santiago and Bogotá high-income districts to bypass supermarket slotting fee structures entirely.
For Investors and Strategic Acquirers: ANVISA's octagonal warning label mandate reshapes the acquisition landscape toward reformulation-capable assets with clean-label positioning. Long-term viability favors processors with captive supply integration and regulatory affairs scale rather than pure brand equity plays. Monitor stevia masking technology breakthroughs as inflection signal for children's segment re-entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Bahia Cocoa Cluster Integration | Captive supply of single-origin cacao reduces West African futures exposure for Brazilian processors. |
| Pectin-Hydrocolloid Line Retrofit | Enables texture profiles matching premium imports, collapsing quality-tier differentiation in São Paulo manufacturing. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees while building first-party data assets in Santiago and Bogotá districts. |
| Regulatory Affairs Function Buildout | Dedicated ANVISA compliance teams enable dual-SKU portfolio strategies separating reformulated and legacy lines. |
| Functional Gummy Format Extension | Collagen and vitamin fortification captures adult wellness segments with pricing power beyond traditional confectionery. |
Research Methodology
A standing panel of brand managers, supermarket category buyers, cocoa processing plant managers, and ANVISA regulatory consultants provided ongoing calibration throughout the study. Primary interviews with supply planners at São Paulo state manufacturers and channel sales heads across Chile and Colombia combined with secondary validation from customs records, Nielsen retail audit data, and ANVISA disclosure filings. Bottom-up volume modeling triangulated against top-down macroeconomic anchors.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions including product type, distribution channel, customer cohort, and flavor profile. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel shift elasticities. Forecast inputs incorporated cocoa butter futures curves, supermarket private-label expansion timelines, and e-commerce logistics penetration rates into secondary metropolitan zones.
Sensitivities concentrate around ANVISA enforcement intensity, West African supply disruption, and stevia masking technology advancement. Forecasts reflect documented assumptions regarding regulatory harmonization across Mercosur and consumer willingness to absorb clean-label price premiums. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar Free Candy Market
Confectionery
Low Calorie Nutella Market
Confectionery
Low Calorie Sweets Market
Confectionery
UK Chocolate Market
Confectionery
Global Compound Chocolate Market
Confectionery
Confectionery Fillings Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
Africa Compound Chocolate Market
Confectionery
North America Gummy Market
Confectionery
Real and Compound Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
US Dark Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Sugar-Free Gumballs Market