
 Fat Free Candy Market | 2026-2036
Fat Free Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Free Candy Market Analytics
Single-serve portion bundling is rebalancing buyer choice in fat free confectionery, shifting volume from bulk bags toward calibrated daily-intake packs. The Hershey Company leverages its retail shelf dominance to anchor multi-pack formats across mainstream grocers. Mars Incorporated competes through specialized manufacturing scale that sustains consistent texture profiles across sugar alcohol formulations. Nestlé differentiates via brand architecture that positions fat free lines adjacent to broader wellness portfolios.
Fat free candy denotes confectionery products formulated with negligible lipid content, typically substituting traditional fats with hydrocolloid stabilizers, modified starches, or aerated protein matrices to achieve comparable mouthfeel and structural integrity. These products serve consumers managing caloric restriction, cardiovascular risk profiles, or metabolic conditions requiring lipid minimization. Gummy candies lead product type revenue pools due to inherent formulation flexibility with gelatin and pectin bases that naturally exclude fat. Hard candies occupy mature volume positions with minimal innovation requirements, while chewy candies represent the fastest-expanding segment as texture-engineering advances close the sensory gap with full-fat equivalents.
FDA nutrition labeling mandates and USDA dietary guideline publications shape product formulation thresholds and front-of-pack claim permissibility in the United States. Sugar alcohol classification under FDA regulations determines gastrointestinal warning requirements and net carbohydrate declaration methods that directly influence consumer purchase confidence. Stakeholders must monitor evolving sweetener GRAS determinations and state-level sugar tax proposals that could restructure competitive economics across natural versus artificial ingredient pathways.
Market Dynamics
Sugar alcohol formulation engineering is compressing the sensory gap between fat free and full-fat confectionery, forcing ingredient suppliers to recalibrate stabilizer portfolios around texture-mimetic hydrocolloids.
Growth Catalysts
- FDA GRAS determinations:Expanding approved sweetener lists enable broader sugar alcohol deployment without gastrointestinal warning thresholds that previously constrained formulation flexibility.
- Cardiovascular risk management protocols:Clinical dietary guidelines from the American Heart Association now explicitly recommend lipid minimization, channeling patient populations toward fat free alternatives.
- Single-serve packaging automation:Flow-wrap and stick-pack machinery advances reduce unit economics for portion-controlled formats, accelerating retail adoption.
Market Restraints
- Pectin supply concentration:Citrus peel sourcing clusters in Spain and Brazil expose gummy candy manufacturers to climate-driven harvest volatility.
- Sugar alcohol digestive tolerance ceiling:Erythritol and maltitol consumption thresholds trigger consumer abandonment above 30-50g daily intake, hard-capping per-capita consumption velocity.
- Clean-label substitution pressure:Allulose and monk fruit extracts attract reformulation investment away from traditional sugar alcohol pathways.
Strategic Opportunities
- India FSSAI sweetener approvals:Pending regulatory expansions would unlock 1.4 billion consumer access for polyol-based confectionery previously restricted by formulation constraints.
- Direct-to-clinic sampling channels:Partnerships with endocrinology and cardiology practices create prescriptive trial pathways bypassing conventional retail competition.
- Aerated protein matrix convergence:Whey and pea protein foam technologies hybridize with hydrocolloid systems to achieve novel texture profiles beyond current gelatin limitations.
Industry Challenges
- Texture engineering talent scarcity:Food rheology and mouthfeel modeling expertise concentrates in legacy dairy and meat analog sectors, forcing confectionery recruiters to cross-train from adjacent industries.
- Sugar alcohol hygroscopicity management:Packaging moisture barrier specifications require capital-intensive multilayer film transitions that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Free Candy Market |
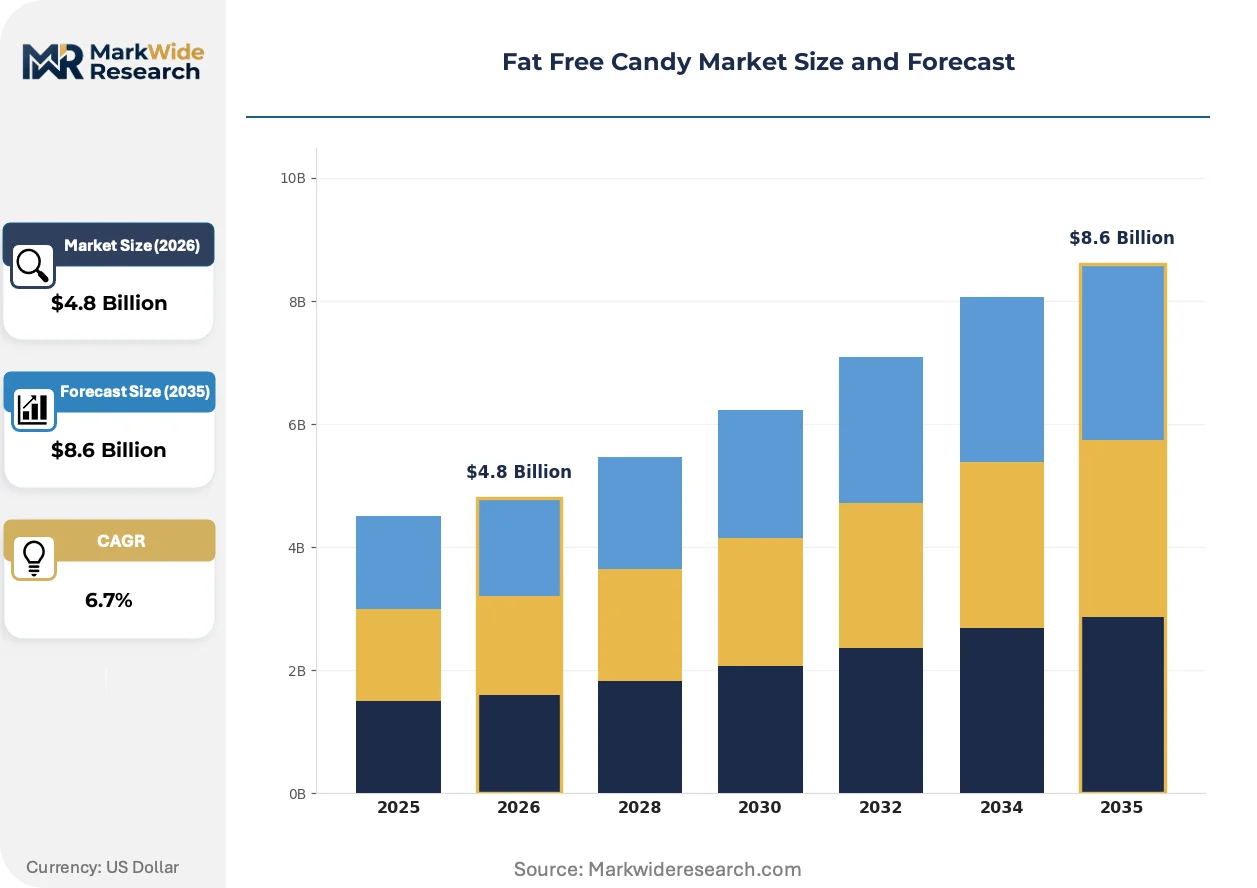
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummy Candies, Hard Candies, Chewy Candies, Licorice End User: Retail Consumers, Health Conscious Individuals, Fitness Enthusiasts, Diabetics Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Ingredient Type: Natural Sweeteners, Sugar Alcohols, Artificial Sweeteners, Others |
| Companies Covered | TruJoy Sweets, The Hershey Company, Nestlé, Russell Stover Chocolates, Tootsie Roll Industries, Mars Incorporated, Toms Confectionary, Godiva Chocolatier, Lindt & Sprüngli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Free Candy Market Evolving Landscape
Formulation science is converging with portion-format engineering to redefine what fat free confectionery can deliver sensorially, collapsing the historical compromise between health positioning and eating experience.
Pectin-gellan hybrid gelling systems are consolidating textural control in premium gummy segments. These hydrocolloid blends enable thermal stability and chew elasticity previously achievable only with gelatin. Clean-label vegan confectionery brands in Germany and the United Kingdom are adopting these systems at accelerated procurement cycles. The technology is consolidating supplier power around specialized hydrocolloid houses capable of custom blend optimization.
EU F-Gas Regulation phase-down schedules are pressuring refrigeration-dependent confectionery storage and transport networks. Chocolate-fat-free hybrid products requiring precise temperature control face escalating cold-chain compliance costs. Manufacturers serving Nordic markets are responding with modified atmosphere packaging investments that reduce temperature sensitivity.
Subscription-based personalized nutrition bundles are fragmenting traditional grocery channel dominance for fat free candy. Health-conscious consumers in metropolitan United States markets now source confectionery through curated wellness boxes alongside supplements and functional foods. This displacement is most visible in California and New York, where direct-to-consumer fulfillment infrastructure supports chilled and ambient mixed-product shipments.
Fat Free Candy Market Segmentation
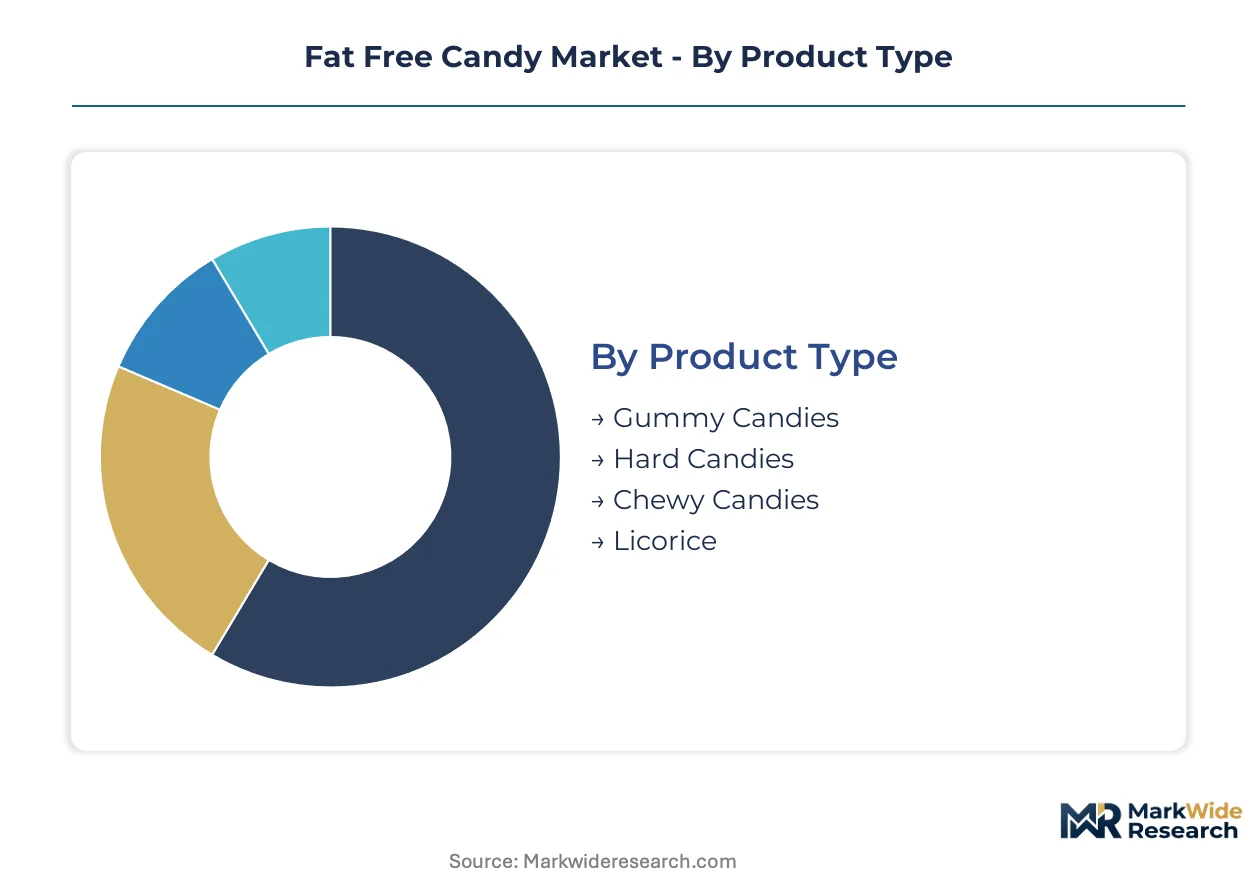
Fat free candy segmentation reveals how formulation constraints and purchasing contexts fragment commercial opportunity across distinct technical and channel pathways. Each dimension carries divergent margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Texture engineering capabilities and gelatin substitution economics differentiate manufacturers across product categories.
- Gummy Candies:These formulations leverage pectin, gellan, or modified starch matrices to replicate gelatin's elastic chew without lipid content. Demand clusters in Germany and the United Kingdom where clean-label vegan brands accelerate procurement of hybrid hydrocolloid systems.
- Hard Candies:Traditional boiled-sugar matrices require minimal reformulation for fat-free positioning, preserving mature margin structures. Volume concentrates in the United States through established retail shelf placements with limited innovation investment.
- Chewy Candies:Aerated protein and modified starch combinations now achieve taffy-like textures previously dependent on fat emulsions.
- Licorice:Wheat flour and molasses bases naturally exclude fat, though glycyrrhizin extraction sourcing constrains premium positioning.
Hard candies lead volumes today; chewy candies are gaining share fastest.
End User:
Purchasing motivation and dietary compliance requirements segment buyers into distinct price-elasticity tiers.
- Retail Consumers:Occasional purchasers responding to front-of-pack claims drive mainstream volume through impulse channels.
- Health Conscious Individuals:Sustained repeat purchasers prioritize clean-label ingredient decks and accept 15-30% price premiums for verified fat-free positioning.
- Fitness Enthusiasts:Macro-tracking consumers source single-serve formats through supplement retailers and direct-to-consumer wellness platforms.
- Diabetics:Medically motivated buyers require precise sugar alcohol labeling and net carbohydrate calculations, creating loyalty to brands with transparent glycemic indexing.
Retail consumers anchor current volume; fitness enthusiasts show the steepest expansion trajectory.
Distribution Channel:
Cold-chain requirements and planogram negotiation power separate channel economics.
- Online Retail:Direct-to-consumer fulfillment enables subscription bundling and personalized nutrition curation, capturing metropolitan United States demand in California and New York.
- Supermarkets:Slotting fee structures and multi-pack format dominance concentrate volume with legacy manufacturers possessing retail shelf leverage.
- Health Food Stores:Curated assortment and educated staff recommendations support premium pricing for clean-label and organic-certified lines.
- Specialty Shops:Ethnic confectionery and import channels serve diaspora populations seeking traditional formulations in fat-free variants.
Supermarkets maintain volume leadership; online retail climbs the fastest.
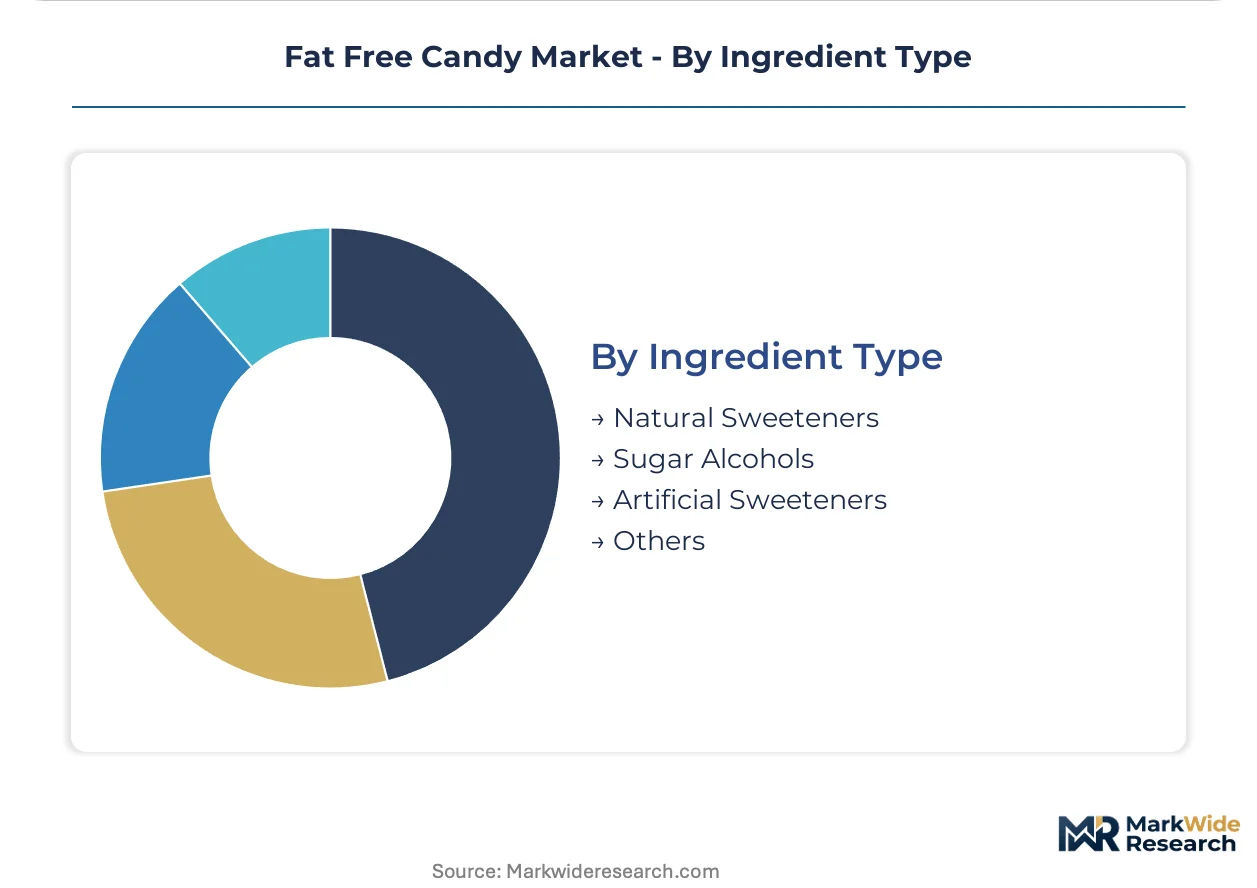
Ingredient Type:
Regulatory approval status and digestive tolerance thresholds determine formulation flexibility across geographies.
- Natural Sweeteners:Monk fruit and stevia extracts command reformulation investment despite bitterness masking challenges and supply concentration in China.
- Sugar Alcohols:Erythritol, maltitol, and xylitol dominate current production with established FDA GRAS status, though 30-50g daily tolerance ceilings constrain per-capita consumption velocity.
- Artificial Sweeteners:Sucralose and aspartame maintain cost advantages in value-tier products despite clean-label substitution pressure.
- Others:Allulose and rare sugar categories attract development investment pending expanded regulatory approvals.
Sugar alcohols dominate current formulation; natural sweeteners expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fat free confectionery industrialized first in Switzerland and Germany during the mid-twentieth century, when hydrocolloid stabilization science enabled lipid-free gummy matrices. Production expertise subsequently diffused to North American and Asian manufacturing centers as sugar alcohol formulation matured.
United States
Health-conscious consumers in metropolitan California and New York drive subscription-based procurement through direct-to-consumer wellness platforms. FDA GRAS determinations for expanded sweetener portfolios enable broader sugar alcohol deployment without gastrointestinal warning thresholds. Chicago and Hershey, Pennsylvania anchor manufacturing clusters where automated flow-wrap machinery reduces unit economics for single-serve formats.
Germany
Clean-label vegan brands in Berlin and Munich accelerate procurement of pectin-gellan hybrid gelling systems for thermal-stable gummy formulations. EU F-Gas Regulation phase-down schedules pressure refrigeration-dependent storage networks, prompting modified atmosphere packaging investments. The country's national food safety regulator maintains strict additive approval protocols that shape regional formulation pathways.
United Kingdom
Retail shelf space for reduced-fat confectionery widens through mainstream grocer negotiations in London and the Southeast. The national food standards agency enforces front-of-pack nutritional labeling mandates that determine claim permissibility. Birmingham and Manchester distribution hubs concentrate import flows from European hydrocolloid suppliers.
India
Pending FSSAI sweetener approvals would unlock formulation flexibility for polyol-based confectionery across Maharashtra and Gujarat manufacturing zones. The central food regulator's regulatory expansions remain the critical gating factor for market entry. Mumbai and Ahmedabad industrial corridors position for capacity scaling once approval timelines clarify.
Japan
Aging demographics with cardiovascular risk management protocols channel patient populations toward lipid-minimized alternatives in Tokyo and Osaka metro areas. The national health ministry's dietary guidelines explicitly recommend lipid minimization for metabolic condition management. Yokohama and Nagoya R&D clusters advance rare sugar categories including allulose pending expanded regulatory determinations.
Fat Free Candy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and clean-label certification tiers. The vendor base organizes around three structural tiers: multinational confectionery conglomerates with retail shelf leverage, mid-tier specialists in sugar alcohol engineering, and emerging vegan-clean-label challengers. Archetypes include scale-driven mass-market suppliers, texture-engineering specialists, and direct-to-consumer wellness-positioned entrants. Dominant competitive moves include portfolio diversification into functional confectionery and strategic partnerships with ingredient suppliers for exclusive hydrocolloid access.
Within the multinational tier, The Hershey Company and Mars Incorporated exemplify scale-driven archetypes with manufacturing footprint advantages. Nestlé occupies a position bridging mass-market volume and wellness-portfolio adjacency. Among European premium chocolatiers, Lindt & Sprüngli and Godiva Chocolatier represent heritage-positioned players navigating clean-label transition pressures. TruJoy Sweets exemplifies the emerging specialist archetype focused on vegan-certified formulations.
| Leading Market Players |
|---|
| TruJoy Sweets |
| The Hershey Company |
| Nestlé |
| Russell Stover Chocolates |
| Tootsie Roll Industries |
| Mars Incorporated |
| Toms Confectionary |
| Godiva Chocolatier |
| Lindt & Sprüngli |
| Others |
Value Network & Pricing Analysis
Food rheology specialists concentrated in Switzerland and Germany command wage premiums that compress margins at premium-tier manufacturers while value-tier producers in India and Brazil exploit labor-cost differentials to sustain 40-50% price spreads across the three-tier structure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and texture-engineering sophistication. Premium tiers capture clean-label vegan positioning with pectin-gellan hybrid systems; standard tiers rely on conventional sugar alcohol formulations; economy tiers use artificial sweetener bases. Cost compression in the standard tier is intensifying because mid-tier manufacturers face capital-intensive multilayer film packaging transitions. Health-conscious individuals show lowest price sensitivity; retail impulse buyers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from major confectionery manufacturers require qualification of at least two hydrocolloid suppliers per gelling system to mitigate climate-driven harvest volatility. Supply draws from Spain and Brazil for citrus-derived pectin, China for monk fruit extracts, and Thailand for native tapioca starches. Single-source vulnerability concentrates in specialized gellan gum fermentation capacity controlled by CP Kelco and DuPont Nutrition. Distribution runs through temperature-controlled logistics networks serving supermarket retail and direct-to-consumer fulfillment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fat free candy market represents a late-cycle quality story where health-conscious consumers now demand texture parity with full-fat equivalents, forcing reformulation investment toward premium hydrocolloid specifications.
For Market Incumbents: Cement formulation exclusivity through captive supply agreements with specialized gellan gum and pectin blend houses before clean-label vegan challengers lock up limited fermentation capacity. Defend shelf position by accelerating single-serve format automation in Chicago and Hershey manufacturing clusters against direct-to-consumer wellness platforms eroding grocery channel dominance. For New Entrants and Emerging Players: Aerated protein matrix technologies offer a technology-first wedge into the chewy candy segment where texture-engineering gaps persist against gelatin-based incumbents. Target fitness enthusiasts through supplement retailer partnerships and personalized nutrition subscription bundles in California and New York metropolitan markets, bypassing slotting-fee barriers at mainstream grocers. For Investors and Strategic Acquirers: Mid-cap confectionery conglomerates with wellness-portfolio adjacency are the most active acquirer in this space, seeking texture-engineering capabilities absent from legacy manufacturing footprints. Long-term viability hinges on regulatory approval velocity for rare sugar categories across FSSAI and FDA jurisdictions. Watch India FSSAI sweetener approval timelines as the critical inflection signal for polyol-based market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Pectin-Gellan Hybrid System Adoption | Enables thermal-stable vegan gummy formulations that bypass gelatin supply constraints. |
| Single-Serve Packaging Automation | Flow-wrap machinery investments in Hershey and Chicago reduce unit economics for portion-controlled formats. |
| Direct-to-Consumer Wellness Platform Launch | Subscription bundling in California and New York captures health-conscious consumers outside grocery channels. |
| Exclusive Hydrocolloid Supplier Partnership | Captive access to specialized gellan gum fermentation capacity locks out clean-label competitors. |
| Clean-Label Certification Investment | USDA Organic and vegan certifications support 15-30% price premiums from health-conscious buyers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with confectionery brand managers, hydrocolloid procurement leads at ingredient suppliers, retail category buyers, food rheology R&D directors, and regulatory affairs specialists with secondary validation against FDA GRAS determinations, FSSAI approval databases, EU F-Gas Regulation schedules, customs trade data for pectin and gellan gum imports, and SEC filings from publicly traded confectionery manufacturers. Bottom-up segment sizing and top-down macro anchoring were triangulated to verify volume and value estimates.
Historical reference periods anchored the projection framework to established sugar alcohol adoption curves and prior hydrocolloid substitution cycles across the analysis window. Segmentation dimensions modeled include product type, end-user motivation tier, distribution channel cold-chain requirements, and ingredient regulatory approval status. CAGRs were derived from fitted growth curves incorporating FDA sweetener GRAS expansion timelines, single-serve packaging automation diffusion rates, and cardiovascular dietary guideline publication impacts on patient-population purchasing.
The model holds under stable regulatory approval timelines for rare sugar categories; deviation in India FSSAI polyol authorization schedules or EU F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Bangladesh Candy Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
Sugar Free Lollipops Market
Confectionery
South America Confectionery Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Confectionery Coating Market
Confectionery
Truffle Chocolate Market
Confectionery
Macarons Market
Confectionery
Cookie Dough Market
Confectionery
North America Chocolate Market
Confectionery
North America Premium Chocolate Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market
Confectionery
Middle East and Africa Confectionery Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Carob Chocolate Market