
 South Korea Data Center Market | 2026-2036
South Korea Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Market Insights
South Korea's Green New Deal policy framework is decoupling data center expansion from fossil-reliant energy models, compelling operators to secure renewable power purchase agreements and carbon-neutral certifications. KT Corporation leverages its nationwide fiber backbone to anchor hyperscale campus developments in Pangyo and Busan. SK Telecom competes through integrated edge computing nodes that reduce latency for enterprise clients. Naver Cloud specializes in sovereign cloud architectures that satisfy domestic data residency requirements for public sector buyers.
A data center constitutes a dedicated facility housing servers, storage systems, networking equipment, and power/cooling infrastructure engineered to maintain 99.999% uptime through redundant uninterruptible power supplies and precision air handling units. Colocation services dominate current revenue as enterprises divest owned facilities, while cloud services represent the fastest-expanding segment driven by AI training workloads and SaaS migration. Hybrid deployment models capture widening margin pools as regulated industries seek to balance agility with control over sensitive workloads.
MFDS guidelines on medical data localization, KISA cybersecurity certification mandates, and Ministry of Environment emissions reporting standards collectively shape facility design and market access requirements for operators serving healthcare and financial verticals. Kepco tariff structures and renewable portfolio obligations from the Ministry of Trade, Industry and Energy further constrain power procurement strategies. Stakeholders must monitor evolving carbon border adjustments and real-time energy pricing mechanisms that will determine site selection economics and long-term contract viability.
Market Dynamics
The Green New Deal framework is decoupling data center expansion from fossil-reliant energy models, forcing operators to secure renewable power purchase agreements and carbon-neutral certifications before breaking ground on new facilities.
Growth Catalysts
- AI training workloads:Domestic e-commerce platforms and fintech operators are expanding cloud capacity requirements to support large language model deployment and real-time inference services.
- MFDS medical data localization:Healthcare providers must store patient records within sovereign boundaries, creating dedicated facility demand from hospital networks and digital health startups.
- Pangyo cluster concentration:Gyeonggi province offers fiber-dense connectivity and proximity to enterprise headquarters, anchoring hyperscale campus developments.
Market Restraints
- Kepco tariff volatility:Industrial electricity rates fluctuate with LNG import costs, compressing margins for power-hungry AI training facilities.
- Land scarcity in Seoul metropolitan cluster:Zoning restrictions and competing real estate demand limit greenfield expansion in the primary demand center.
- Liquid cooling supply concentration:Specialized coolant distribution networks remain concentrated among a narrow supplier base, creating procurement bottlenecks for high-density deployments.
Strategic Opportunities
- Busan secondary hub:Underutilized submarine cable landing points and lower land costs enable disaster recovery and latency-optimized edge nodes.
- KISA cybersecurity certification:Mandatory security ratings for public sector contracts create premium positioning for certified operators serving government and defense buyers.
- Immersion cooling convergence:Direct-to-chip thermal management combines with waste heat recovery systems to satisfy Ministry of Environment emissions reporting standards.
Industry Challenges
- Precision cooling technician shortage:Specialized HVAC and liquid cooling expertise remains scarce relative to facility buildout timelines, extending commissioning periods.
- Hybrid integration complexity:Enterprises struggle to orchestrate workloads across on-premise, colocation, and public cloud environments without performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Market |
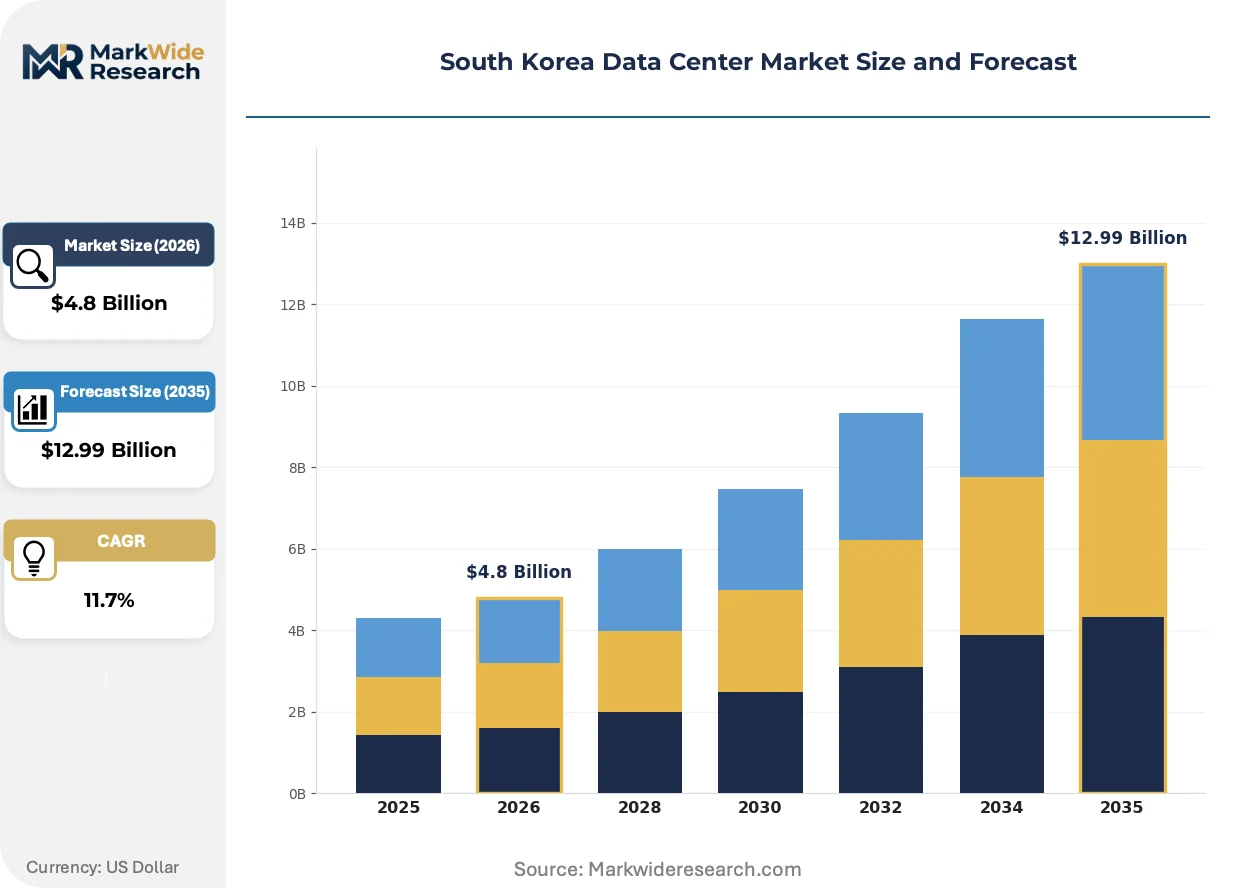
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Hosting, Cloud Services, Connectivity Solutions End User: IT & Telecom, BFSI, Government, E-Commerce Service Type: Infrastructure as a Service, Platform as a Service, Disaster Recovery, Backup Services Deployment Model: On-Premises, Off-Premises, Hybrid, Multi-Cloud |
| Companies Covered | KT Corporation, SK Telecom, LG Uplus, Naver Cloud, Equinix, Digital Realty, Samsung SDS, Amazon Web Services, NHN Cloud, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Market Trends and Innovations
Facility design is pivoting toward thermal efficiency and modular construction methods as power density requirements surge and construction timelines compress. Operators are racing to deploy next-generation infrastructure before regulatory thresholds tighten.
Immersion cooling is converging with waste heat district heating networks. KT Corporation and municipal utilities in Pangyo are piloting systems that capture server exhaust for residential and commercial heating. This dual-use thermal architecture reduces net carbon intensity while generating secondary revenue streams. The technology is converging with traditional air-handling units in retrofit scenarios, creating hybrid thermal stacks that operators can phase in without full facility replacement.
Ministry of Environment emissions reporting standards now mandate granular Scope 2 disclosure for facilities above 50MW capacity. Operators must install real-time monitoring systems and submit quarterly carbon intensity metrics. Financial services and healthcare verticals face the strictest audit requirements, driving demand for third-party verification services and automated compliance platforms.
Enterprise buyers are unbundling long-term colocation contracts into shorter, workload-specific engagements. Retail and gaming companies now procure capacity by the megawatt-hour rather than by the rack, matching payment to actual compute consumption. This shift is most pronounced among Series C and D technology startups in Seoul, who prioritize capital flexibility over committed-use discounts.
South Korea Data Center Market Segmentation
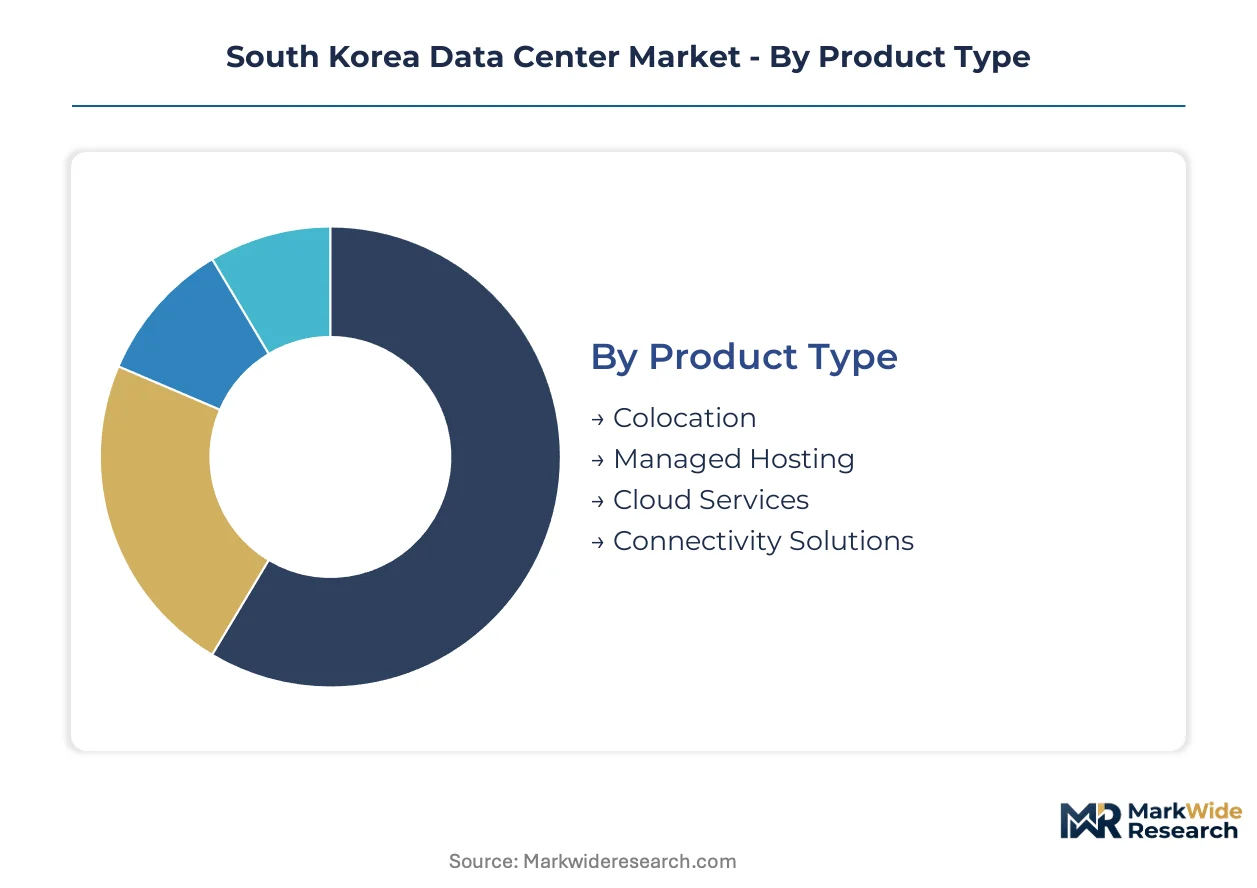
Segmentation in South Korea's data center market reveals how facility operators align service portfolios with regulatory mandates and compute-intensive workloads. Understanding these divisions clarifies where capital deployment concentrates and which verticals drive capacity expansion.
Product Type:
Technology specifications differentiate facility offerings across power density, latency guarantees, and operational control tiers.
- Colocation:Physical rack space and power provisioning within multi-tenant facilities where enterprises retain hardware ownership. Healthcare networks and financial institutions in Seoul favor this model to satisfy MFDS data localization and KISA cybersecurity certification requirements without facility construction.
- Managed Hosting:Fully outsourced server operations including hardware lifecycle management, patch deployment, and security monitoring. Domestic e-commerce platforms expanding AI inference capacity drive demand for GPU-optimized managed environments with dedicated support SLAs.
- Cloud Services:On-demand compute and storage resources delivered through virtualized infrastructure.
- Connectivity Solutions:Cross-connect and interconnection services linking tenant environments to cloud on-ramps and internet exchanges.
Mature deployment sits with Colocation. Newer deployment is concentrated in Cloud Services.
End User:
Cost sensitivity and compliance burden vary sharply across vertical procurement patterns.
- IT & Telecom:Hyperscale cloud providers and domestic carriers consuming megawatt-scale capacity for content delivery and edge node distribution. KT Corporation and SK Telecom anchor demand in Pangyo and Busan for low-latency backbone integration.
- BFSI:Banks, insurers, and securities firms subject to Financial Services Commission audit requirements and real-time transaction processing needs. Hybrid architectures dominate as institutions balance public cloud agility with sovereign control over core banking systems.
- Government:Central and municipal agencies procuring through Public Procurement Service frameworks.
- E-Commerce:Online retail and marketplace operators scaling flash sales and recommendation engine infrastructure.
Volume concentration rests with IT & Telecom. Margin expansion is concentrated in BFSI.
Service Type:
Abstraction layers determine how deeply operators embed into customer technology stacks.
- Infrastructure as a Service:Virtualized compute, storage, and networking resources provisioned through APIs and web consoles. Naver Cloud and KT Cloud compete here for AI training workloads requiring GPU cluster orchestration.
- Platform as a Service:Managed application runtime environments including container orchestration and database services. Fintech startups in Seoul favor this tier to accelerate product deployment without infrastructure overhead.
- Disaster Recovery:Geographically separated failover infrastructure with automated recovery orchestration.
- Backup Services:Scheduled data protection with immutable storage and ransomware recovery capabilities.
Standardization sits with Infrastructure as a Service. Differentiation is climbing fastest in Platform as a Service.
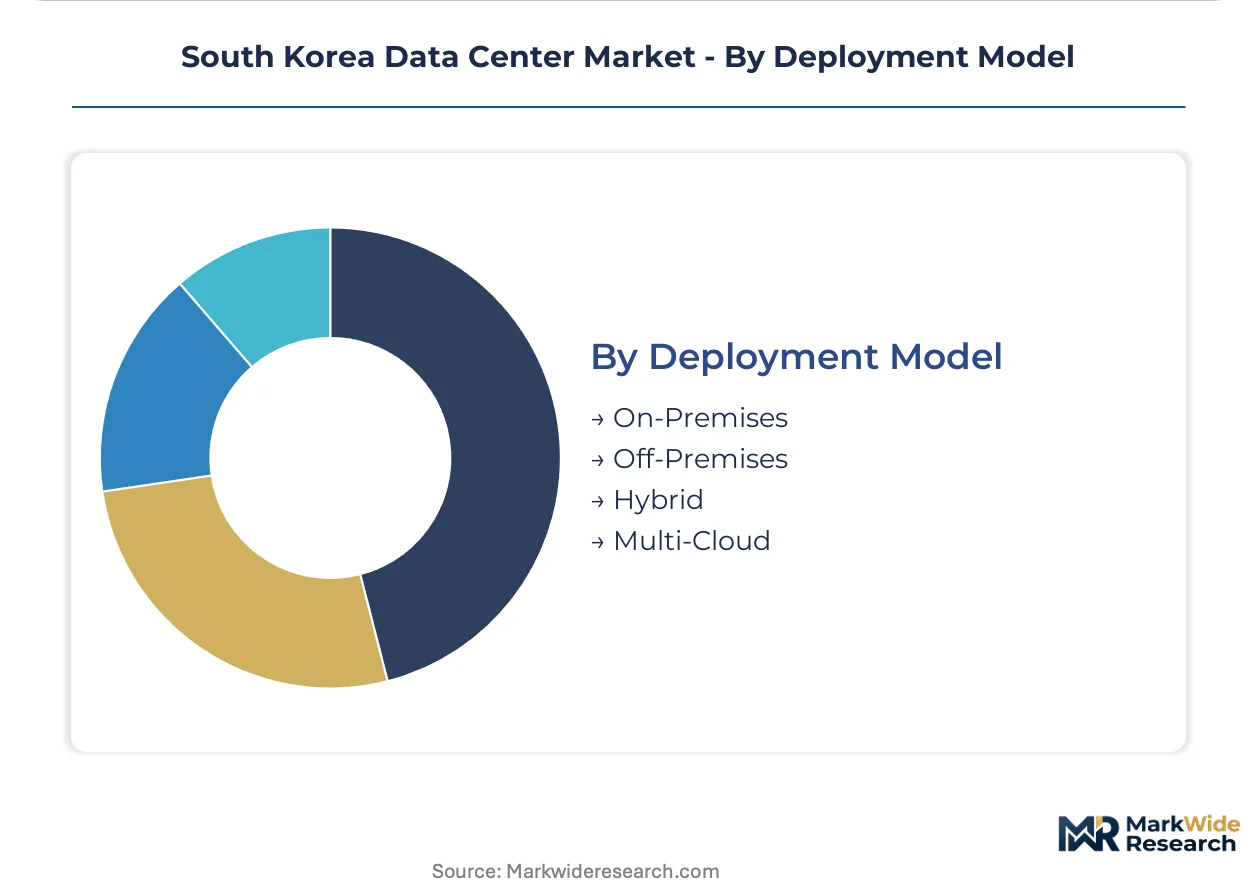
Deployment Model:
Physical location and control boundaries define architectural trade-offs for regulated workloads.
- On-Premises:Enterprise-owned facilities with full operational autonomy. Large manufacturing conglomerates and defense contractors maintain captive data centers to satisfy supply chain security requirements and avoid multi-tenant risk exposure.
- Off-Premises:Third-party facility utilization eliminating capital expenditure and operational staffing burdens. Series C technology startups prioritize this model to preserve runway while accessing Tier III reliability.
- Hybrid:Orchestrated workload distribution across owned and outsourced infrastructure.
- Multi-Cloud:Deliberate distribution across multiple hyperscale providers to avoid vendor lock-in.
Legacy concentration sits with On-Premises. Strategic investment is gaining share fastest in Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area concentrates over 70% of national data center capacity, with Pangyo's fiber-dense corridors anchoring hyperscale campus developments. Gyeonggi province surrounds the capital with secondary clusters that absorb overflow demand from land-constrained Seoul proper.
Seoul Capital Area
Financial services and e-commerce platforms drive multi-tenant facility demand. MFDS medical data localization mandates require healthcare networks to maintain sovereign storage. Songdo's smart city infrastructure hosts disaster recovery nodes for Seoul-based enterprises.
Busan-Ulsan
Underutilized submarine cable landing points attract latency-sensitive edge computing deployments. Lower industrial electricity rates compared to Seoul improve margins for AI training facilities. Haeundae district anchors pilot projects linking immersion cooling to municipal district heating networks.
Daegu-Gyeongbuk
Semiconductor manufacturing clusters generate co-location demand from chip design firms requiring proximity to fabrication plants. KISA cybersecurity certification programs operate regional training centers here. Gumi's industrial parks offer converted manufacturing facilities for retrofit data center projects.
Daejeon-Sejong
Government agency procurement concentrates in this administrative capital under Public Procurement Service frameworks. KAIST and national research institutes drive demand for high-performance computing infrastructure. Sejong City's planned district cooling systems support carbon-neutral facility commitments.
Gwangju-Honam
Agricultural technology and regional banking networks create mid-scale colocation demand. Renewable energy availability from Honam region wind farms supports Green New Deal compliance objectives. Gwangju's AI-focused industrial complex hosts specialized GPU clusters for computer vision workloads.
South Korea Data Center Market Competitive Landscape
The competitive structure tilts toward domestic telecommunications incumbents with captive fiber infrastructure. Three archetypes dominate: carrier-affiliated hyperscale operators, independent cloud specialists, and international platform providers leasing local capacity. Capacity expansion and renewable power procurement represent the primary competitive moves, with operators racing to secure grid interconnection agreements before Kepco tariff reforms take effect.
Among carrier-integrated operators, KT Corporation anchors the Pangyo cluster with backbone-connected campuses, while SK Telecom exemplifies the edge computing archetype through distributed low-latency nodes. Naver Cloud occupies a position serving sovereign cloud requirements for public sector buyers. International platform providers including Equinix and Digital Realty represent the third tier, offering interconnection services that bridge domestic enterprises to global networks.
| Leading Market Players |
|---|
| KT Corporation |
| SK Telecom |
| LG Uplus |
| Naver Cloud |
| Equinix |
| Digital Realty |
| Samsung SDS |
| Amazon Web Services |
| NHN Cloud |
| Others |
Pricing and Supply Chain Analysis
Telecommunications incumbents with captive fiber infrastructure anchor supply-side discipline, translating backbone ownership into pricing power across colocation and cloud service tiers while compressing margins for independent operators lacking vertical control over last-mile connectivity.
Pricing Analysis
Throughput-based pricing anchors enterprise contracts, with operators charging per megawatt-hour consumed rather than fixed rack commitments. Three-tier pricing structure across premium, standard, and economy levels separates Tier III+ certified facilities with KISA cybersecurity ratings from uncertified alternatives. Cost compression in standard-tier colocation is intensifying because domestic e-commerce platforms are unbundling long-term contracts into workload-specific engagements. Series C technology startups in Seoul exhibit highest price sensitivity, while BFSI buyers prioritize uptime guarantees over per-unit costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for precision cooling hardware, while systems integrators serve mid-scale retrofit projects. Manufacturing concentrates in Taiwan for advanced semiconductors, China for mechanical and electrical components, and South Korea for domestic fiber and power distribution equipment. Server assembly draws from Malaysian and Vietnamese facilities to balance cost and logistics efficiency. Single-source vulnerability in liquid coolant distribution networks creates procurement bottlenecks for high-density AI training deployments. Distribution runs through carrier-affiliated procurement arms for backbone-connected campuses, independent distributors for modular edge nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as operators pursue captive renewable power procurement to secure Green New Deal compliance ahead of Kepco tariff reforms.
For Market Incumbents: Lock in long-term power purchase agreements with Honam region wind farms before Ministry of Trade, Industry and Energy portfolio obligations tighten. Defend against international platform providers by embedding KISA cybersecurity certification into standard service tiers, creating switching costs for government and defense buyers. For New Entrants and Emerging Players: Capture Busan's underutilized submarine cable landing points for disaster recovery and latency-optimized edge nodes serving gaming and fintech verticals. Target mid-scale colocation demand from agricultural technology networks in Gwangju-Honam where carrier presence remains thin. Differentiate through immersion cooling expertise paired with municipal district heating integration. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent cloud specialists with sovereign cloud certifications in Daejeon-Sejong government procurement corridors. Long-term viability hinges on renewable interconnection queue position and real-time carbon monitoring infrastructure. Watch for Kepco tariff reform announcements as inflection signals for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement | Secures Green New Deal compliance for Pangyo hyperscale campus developments ahead of regulatory deadlines. |
| KISA Cybersecurity Certification Investment | Unlocks Public Procurement Service frameworks for central and municipal agency contracts. |
| Immersion Cooling Deployment | Enables waste heat recovery integration with municipal district heating networks in Haeundae pilot zones. |
| Busan Edge Node Expansion | Captures latency-sensitive AI inference demand from fintech operators seeking secondary hub redundancy. |
| Hybrid Cloud Platform Integration | Addresses BFSI workload orchestration complexity across on-premise, colocation, and public cloud environments. |
Research Methodology
Independent corroboration across facility operators, precision cooling system vendors, and enterprise IT procurement officers underwrites the qualitative findings. Primary interviews with data center engineering directors, KISA certification auditors, and Ministry of Environment compliance officers combined with secondary validation from Kepco tariff filings, hyperscaler capex disclosures, and Green New Deal policy documents. Bottom-up capacity buildout tracking and top-down electricity consumption modeling triangulate market size estimates.
Comparable-period anchoring to historical facility commissioning timelines and power density evolution patterns shaped the projection framework. Segmentation modeling spans product type, end user vertical, service abstraction layer, and deployment model dimensions across the analysis window. CAGRs derive from facility utilization trajectories, renewable interconnection queue velocities, and AI training workload growth curves. Forecast inputs include Kepco industrial tariff restructuring scenarios and MFDS medical data localization enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment implementations and real-time energy pricing mechanism rollouts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Mexico Data Center Rack Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Data Center Construction Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
South Africa Data Center Market