
 Asia-Pacific Soil Treatment Market | 2026-2036
Asia-Pacific Soil Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Soil Treatment Market Outlook
Agricultural input distribution through cooperatives and government procurement channels is reconfiguring across Asia-Pacific, shifting volume toward consolidated state-backed buyers and away from fragmented retail networks. BASF SE leverages its integrated production footprint to sustain cost advantages in soil amendment formulations. UPL Limited anchors its position through deep farmer-connect programs across India's hinterland. Corteva Agriscience competes by specializing in precision agriculture-enabled application systems.
Soil treatment encompasses physical, chemical, and biological interventions engineered to restore or enhance soil structure, nutrient bioavailability, and microbial activity for sustained crop productivity. Key functional parameters include cation exchange capacity, organic carbon thresholds, and pH stabilization ranges that determine amendment dosing protocols. Biofertilizers occupy the fastest-expanding margin pool as nitrogen-fixing and phosphate-solubilizing cultures displace synthetic baselines in rice and vegetable systems. Precision agriculture technology segments are gaining traction where variable-rate application hardware integrates with satellite imagery to optimize input placement. Herbicides retain volume dominance across broadacre cereal economies but face substitution pressure from mechanical weeding and cover-crop suppression protocols.
India's FSSAI and CEA frameworks govern agrochemical residue limits and soil health monitoring standards, while China's MEE enforces contamination remediation mandates that redirect demand toward certified organic amendments. Japan's METI subsidizes precision agriculture adoption, compressing payback periods for sensor-guided soil treatment equipment. Stakeholders must calibrate R&D portfolios against divergent national certification timelines and subsidy eligibility criteria that fragment product registration economics across the region.
Market Dynamics
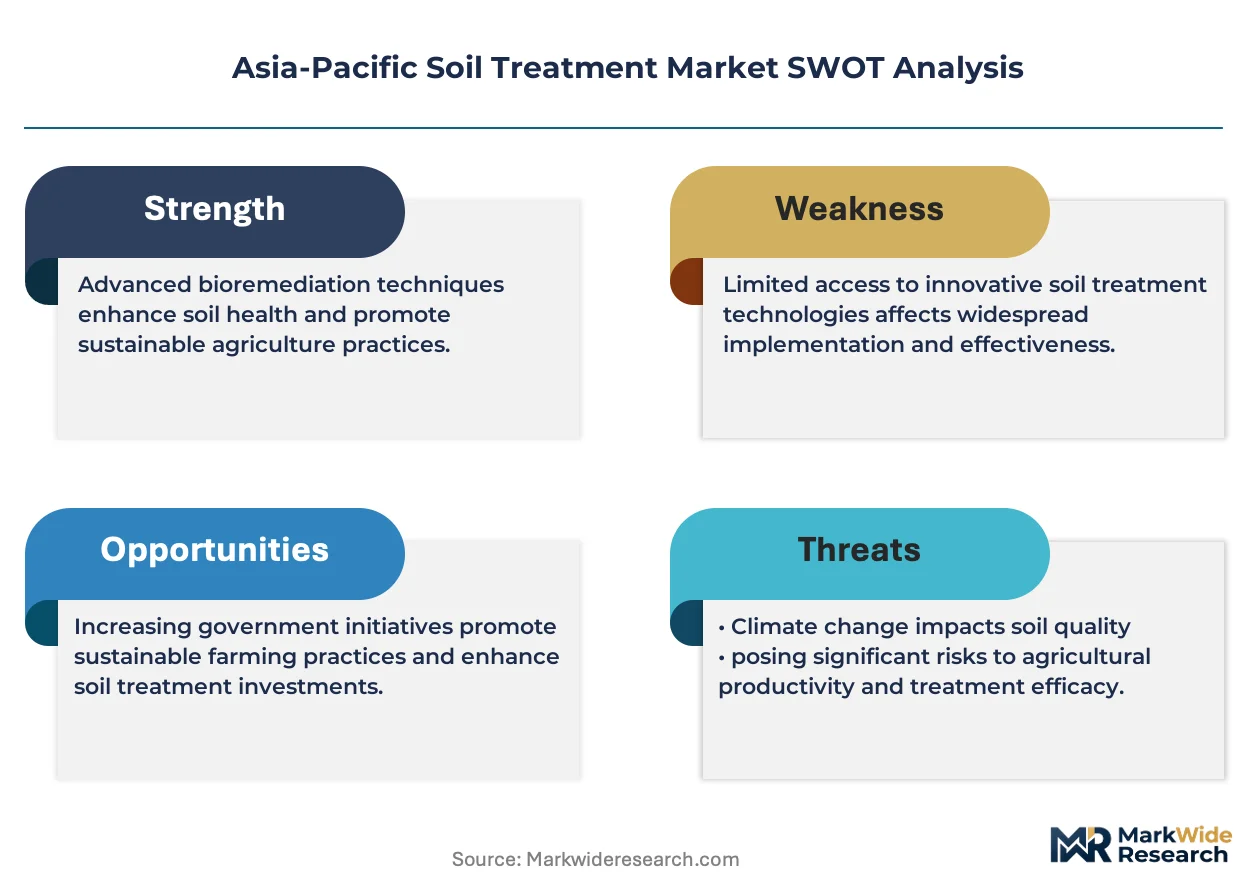
India's PLI scheme for agrochemical manufacturing is redrawing production economics across the Asia-Pacific soil treatment sector, compressing import dependence while accelerating domestic formulation capacity.
Growth Catalysts
- Rice cultivation intensification:Southeast Asia's paddy belt is expanding biofertilizer application as nitrogen-fixing cultures replace synthetic baselines in waterlogged soils.
- China's MEE contamination mandates:Soil remediation requirements are redirecting demand toward certified organic amendments in industrial-agricultural transition zones.
- Precision agriculture hardware:Variable-rate application systems integrating satellite imagery are optimizing input placement in eastern China's vegetable-growing belts.
Market Restraints
- Synthetic input price volatility:Ammonia and phosphate feedstock costs swing with natural gas and sulfur markets, squeezing margin stability for chemical amendment producers.
- Domestic production concentration:India's agrochemical formulation capacity clusters in Gujarat and Maharashtra, creating geographic supply risk during monsoon logistics disruptions.
- Microbial shelf-life limitations:Viability decay in biofertilizer cultures restricts distribution radius and cold-chain infrastructure requirements.
Strategic Opportunities
- Vietnam's Mekong Delta penetration:Triple-crop rice systems remain underpenetrated by certified biofertilizer protocols, offering volume expansion potential.
- Japan's METI precision subsidies:Sensor-guided soil treatment equipment purchases carry compressed payback periods, accelerating hardware adoption curves.
- Drone-sensor convergence:Aerial imagery platforms merging with ground-truth soil probes are enabling real-time amendment prescription mapping.
Industry Challenges
- Microbiologist talent scarcity:Formulation science expertise for strain stabilization and carrier optimization remains concentrated in academic and state-lab channels.
- Divergent national certification timelines:India's FSSAI residue limits, China's MEE remediation standards, and Japan's JIS amendments fragment product registration economics.
- Legacy equipment integration friction:Variable-rate applicators require retrofit compatibility with existing tractor and irrigation infrastructure across smallholder plots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Soil Treatment Market |
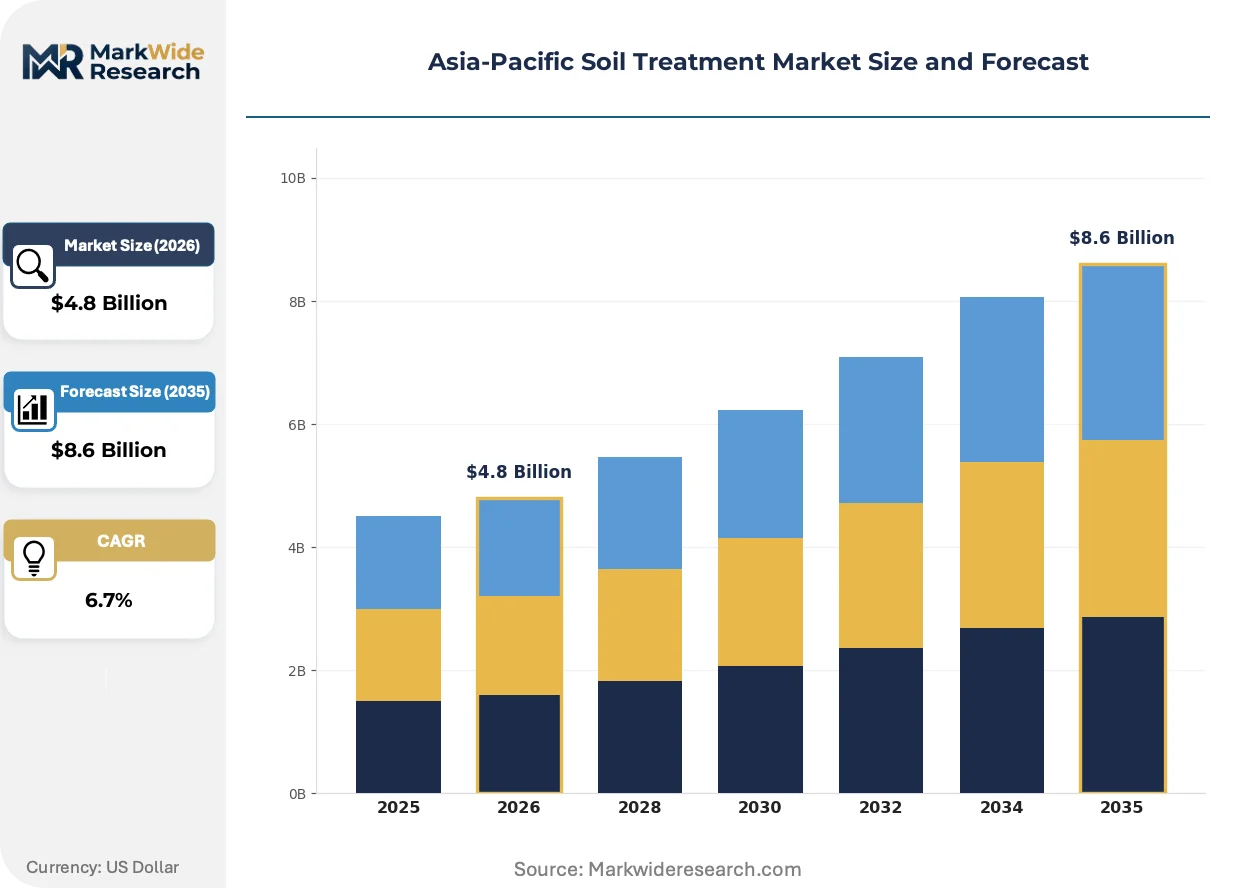
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofertilizers, Soil Amendments, Herbicides, Fungicides Application: Agriculture, Horticulture, Landscaping, Sports Turf Technology: Conventional, Organic, Precision Agriculture, Hydroponics End User: Farmers, Agricultural Cooperatives, Government Bodies, Research Institutions |
| Companies Covered | Syngenta AG, BASF SE, UPL Limited, Bayer AG, Rallis India Limited, Corteva Agriscience, Adama Agricultural Solutions Ltd, FMC Corporation, ADEKA Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Soil Treatment Market Strategic Shifts
Biological amendment protocols are displacing synthetic baselines across Asia-Pacific rice and vegetable systems, while regulatory mandates and procurement consolidation reshape competitive requirements.
Microbial consortia formulations combining nitrogen-fixing bacteria with phosphate-solubilizing fungi are collapsing the cost-performance gap against chemical fertilizers in paddy cultivation. Smallholder cooperatives in Indonesia and Vietnam are adopting these cultures at accelerating rates. The technology is collapsing traditional segmentation between organic and conventional farming inputs.
China's MEE enforcement of soil contamination remediation mandates is compelling industrial-agricultural zones to adopt certified organic amendments. Facility operators face mandatory testing protocols and liability frameworks. Eastern China's Shandong and Hebei vegetable belts are responding with accelerated substitution of synthetic baselines.
State-backed cooperative procurement is displacing fragmented retail distribution across India's hinterland. Consolidated buyers negotiate volume contracts directly with formulation manufacturers, compressing intermediary margins. This pattern is most visible in Punjab and Haryana wheat-rice systems where FPOs aggregate input demand.
Asia-Pacific Soil Treatment Market Segmentation
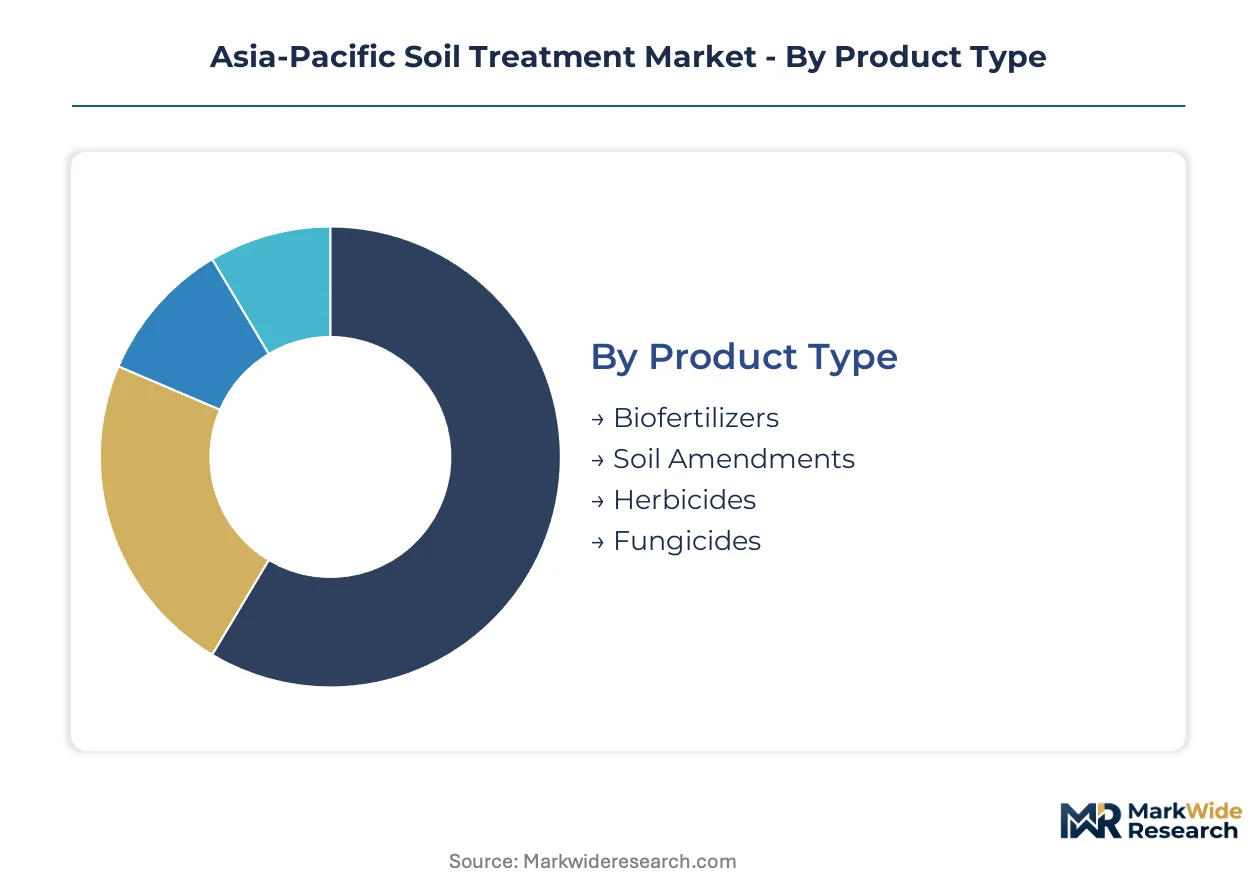
Segmentation in the Asia-Pacific soil treatment market reveals how procurement channels, cropping systems, and regulatory thresholds fragment demand across distinct technical specifications. Understanding these divisions enables suppliers to calibrate formulation portfolios against divergent performance requirements and subsidy eligibility criteria.
Product Type:
After-sales technical support intensity varies sharply across product categories, with biological formulations requiring sustained agronomist engagement for efficacy validation while chemical amendments demand minimal follow-through.
- Biofertilizers:Nitrogen-fixing and phosphate-solubilizing microbial cultures formulated for waterlogged paddy soils and intensive vegetable systems. Demand clusters in Vietnam's Mekong Delta triple-crop rice zones and eastern China's Shandong greenhouse belts, driven by MEE contamination remediation mandates and FPO procurement consolidation.
- Soil Amendments:Organic carbon builders, pH stabilizers, and cation exchange enhancers engineered for degraded industrial-agricultural transition zones. Procurement concentrates through China's state-backed remediation contractors and India's NABARD-linked watershed programs, with certification timelines fragmenting supplier economics.
- Herbicides:Synthetic and bio-based weed control agents retaining volume dominance across broadacre cereal economies.
- Fungicides:Soil-borne pathogen suppressants deployed in high-value horticulture and seed treatment applications.
By volume, herbicides lead. By growth pace, biofertilizers are expanding most quickly.
Application:
Cost tier stratification separates premium horticulture inputs from commodity agriculture formulations, with pricing spreads reflecting certification grade and performance guarantee structures.
- Agriculture:Broadacre cereal and oilseed systems across India's wheat-rice belts and Australia's winter cropping zones. India's PLI scheme is compressing import dependence while accelerating domestic formulation capacity for this segment.
- Horticulture:Protected cultivation and open-field vegetable production requiring precision nutrient management. Eastern China's Hebei and Shandong provinces anchor demand, with variable-rate application hardware integrating satellite imagery for input optimization.
- Landscaping:Urban green space and commercial estate maintenance with standardized amendment protocols.
- Sports Turf:Golf courses, stadiums, and recreational facilities requiring consistent playing surface characteristics.
Agriculture captures the largest volume base. Horticulture shows the steepest margin expansion trajectory.
Technology:
Customer maturity curves separate early precision agriculture adopters in Japan from conventional input users in emerging Southeast Asian markets, with payback period sensitivity governing equipment uptake.
- Precision Agriculture:Sensor-guided soil treatment equipment and variable-rate application systems. Japan's METI subsidies compress payback periods, accelerating hardware adoption in Hokkaido rice and Kyushu vegetable systems.
- Organic:Certified amendment protocols meeting China's MEE remediation standards and India's NPOP requirements for export-oriented production.
- Conventional:Synthetic chemical baselines retaining cost advantages in price-sensitive smallholder segments.
- Hydroponics:Soilless cultivation nutrient solutions deployed in urban vertical farming and controlled-environment agriculture.
Conventional methods dominate current volume. Precision agriculture is climbing the fastest among technology categories.
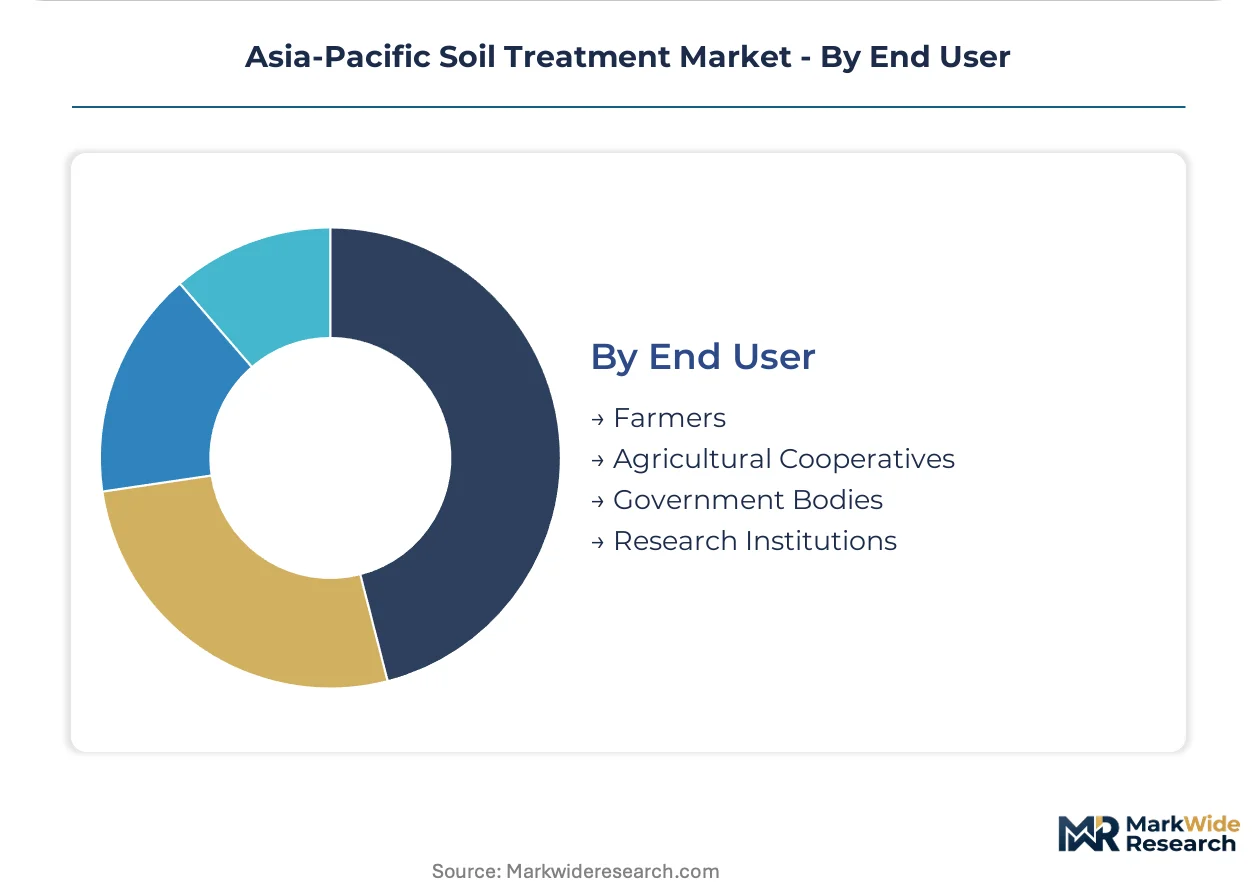
End User:
Supply concentration patterns differentiate fragmented smallholder networks from consolidated state-backed procurement channels, with logistics infrastructure determining serviceable radius for biological formulations.
- Agricultural Cooperatives:FPOs and farmer producer companies aggregating input demand across India's Punjab and Haryana wheat-rice systems. These entities negotiate direct volume contracts with formulation manufacturers, compressing intermediary margins.
- Farmers:Individual smallholders and commercial operators purchasing through retail and digital channels.
- Government Bodies:State procurement agencies administering subsidy programs and soil health mission implementations.
- Research Institutions:Agricultural universities and state labs conducting strain development and field validation trials.
Individual farmers represent the deepest volume pool. Agricultural cooperatives are gaining share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in agricultural input distribution, while the Trans-Asian Railway corridors link Mekong Delta production zones to processing centers across Southeast Asia.
China
Shandong and Hebei provinces anchor demand for certified organic amendments as MEE contamination remediation mandates redirect procurement from synthetic baselines. The Yangtze River Delta's intensive vegetable belts deploy variable-rate application hardware integrated with satellite imagery. Qingdao's port infrastructure enables biofertilizer import substitution through domestic formulation scale-up.
India
Punjab and Haryana wheat-rice systems drive biofertilizer uptake through FPO procurement consolidation. The PLI scheme for agrochemical manufacturing compresses import dependence while accelerating Gujarat and Maharashtra formulation capacity. NABARD-linked watershed programs channel soil amendment demand toward state-backed remediation contractors.
Japan
Hokkaido rice and Kyushu vegetable systems adopt sensor-guided soil treatment equipment under METI precision agriculture subsidies. Compressed payback periods accelerate hardware deployment across consolidated landholdings. Osaka-based equipment distributors anchor service networks for variable-rate applicator maintenance.
Vietnam
The Mekong Delta's triple-crop rice systems remain underpenetrated by certified biofertilizer protocols, offering volume expansion potential. Can Tho's riverine logistics hub supports distribution radius extension for microbial formulations. Provincial agricultural extension services pilot nitrogen-fixing culture adoption in An Giang and Dong Thap provinces.
Australia
Winter cropping zones across New South Wales and Victoria retain synthetic herbicide dominance in broadacre cereal systems. The Murray-Darling Basin's irrigation infrastructure supports precision agriculture hardware trials for variable-rate soil amendment placement. Adelaide's research corridor conducts field validation for drought-adapted microbial consortia.
Asia-Pacific Soil Treatment Market Competitive Environment
On the supply side, the industry is consolidating around integrated formulation manufacturers and precision agriculture technology providers. Three archetypes dominate: multinational agrochemical conglomerates with captive raw material positions, regional specialists leveraging farmer-connect programs, and precision hardware vendors bundling sensor-guided application systems. Capacity expansion in Gujarat and Maharashtra clusters, alongside technology licensing partnerships for microbial strain stabilization, represent the dominant competitive vectors.
Within the multinational tier, BASF SE and Bayer AG exemplify integrated production footprints that sustain cost advantages across soil amendment portfolios. UPL Limited anchors the regional specialist archetype through deep distribution networks across India's hinterland. Corteva Agriscience occupies the precision agriculture vector, bundling variable-rate hardware with agronomic advisory services.
| Leading Market Players |
|---|
| Syngenta AG |
| BASF SE |
| UPL Limited |
| Bayer AG |
| Rallis India Limited |
| Corteva Agriscience |
| Adama Agricultural Solutions Ltd |
| FMC Corporation |
| ADEKA Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Gujarat and Maharashtra formulation clusters is compressing supplier margins while accelerating price competition for generic soil amendment grades. This utilization squeeze is forcing manufacturers to extend payment terms and absorb logistics premiums to retain FPO procurement contracts.
Pricing Analysis
Volume-discount tiering separates FPO consolidated buyers from fragmented retail purchasers, with procurement scale commanding 15-20 point spreads on biofertilizer formulations. Certification grade under China's MEE remediation standards and India's NPOP organic protocols creates premium-mid-economy pricing differentiation across amendment categories. Cost compression in synthetic herbicide segments is intensifying because ammonia feedstock volatility feeds through from natural gas markets. Smallholder farmers purchasing through village retail channels exhibit highest price sensitivity, while state-backed remediation contractors in Shandong and Hebei provinces absorb premium certified organic grades with minimal elasticity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for FPO procurement contracts, with supply-chain finance facilities emerging from NABARD-linked institutions to bridge working capital gaps. Manufacturing capacity concentrates in India, China, and Japan, with formulation science expertise clustering in academic and state-lab channels across all three markets. Raw material dependencies center on ammonia and phosphate feedstocks, microbial culture substrates, and precision agriculture sensor components. Single-source vulnerability in cold-chain infrastructure for biofertilizer distribution creates spoilage risk during monsoon logistics disruptions. Distribution runs through state-backed cooperative procurement channels displacing fragmented retail networks across India's hinterland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific soil treatment sector is experiencing high-growth disruption as microbial consortia formulations collapse the cost-performance gap against synthetic baselines, with China's MEE contamination mandates accelerating certified organic amendment substitution.
For Market Incumbents: Build regulatory certification moats by accelerating FSSAI and NPOP registration timelines ahead of India's PLI scheme capacity expansion. Consolidate formulation capacity in Gujarat clusters to capture backward integration into microbial culture production. Defend against precision agriculture hardware entrants by bundling agronomist advisory services with amendment sales.
For New Entrants and Emerging Players: Pursue Vietnam's Mekong Delta triple-crop rice systems where certified biofertilizer penetration remains below 15 percent of addressable hectarage. Target drone-sensor convergence opportunities enabling real-time amendment prescription mapping for smallholder cooperatives. Anchor go-to-market strategy through provincial agricultural extension partnerships in An Giang and Dong Thap provinces.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision agriculture hardware segments as METI subsidies compress equipment payback periods. Five-to-ten year viability favors acquisition targets with captive microbial strain libraries and established cold-chain distribution radius. Monitor Japan's METI subsidy renewal cycles as inflection signal for hardware adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbial Strain Library Acquisition | Captive culture collections accelerate biofertilizer formulation pipelines beyond generic nitrogen-fixing baselines. |
| Cold-Chain Distribution Partnership | Extended shelf-life logistics unlock Mekong Delta penetration for viability-sensitive microbial consortia. |
| Precision Agriculture Hardware Bundling | Sensor-guided applicators integrated with satellite imagery capture METI subsidy eligibility in Hokkaido rice systems. |
| FPO Procurement Channel Direct Access | Volume contracts with Punjab and Haryana cooperatives displace intermediary margins and lock recurring amendment demand. |
| MEE Remediation Certification Investment | Certified organic amendment status opens Shandong and Hebei vegetable belt procurement to industrial-agricultural transition zones. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with formulation plant managers, FPO procurement leads, agricultural extension officers, and precision agriculture equipment distributors; and secondary validation through India's FSSAI residue limit filings, China's MEE contamination remediation protocols, customs trade data for ammonia and phosphate feedstocks, and NABARD watershed program disbursement records. Bottom-up triangulation across state-level procurement volumes and top-down reconciliation against national agrochemical production statistics anchored market sizing.
Forecast inputs incorporated product type segmentation across biofertilizers, soil amendments, herbicides, and fungicides; application splits between broadacre agriculture and intensive horticulture; technology adoption curves for precision agriculture versus conventional methods; and end-user concentration patterns from fragmented smallholders to consolidated cooperatives. CAGRs were derived from regression analysis of historical input intensity ratios and projected cropping system expansion across the analysis window. Industry-specific inputs included PLI scheme capacity addition schedules and METI subsidy renewal trajectories.
Sensitivities concentrate around regulatory certification timeline delays, monsoon logistics disruption severity, and microbial culture viability decay rates in ambient distribution conditions. Forecasts reflect documented assumptions on FPO procurement consolidation velocity and precision agriculture hardware cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
North America Castor Oil Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
South America Herbicide Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Global Feed Mycotoxin Binders and Modifiers Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Fish Feed and Shrimp Feed and Additives Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
North America Silage Additives Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
North America Feed Antioxidants Market
Agricultural Chemicals
North America Herbicide Market