
 Food Trays and Bowls Market | 2026-2036
Food Trays and Bowls Market Size, Share, and Industry Trends Forecast 2026-2036
Food Trays and Bowls Market Insights
The capital-intensity divergence between integrated fiber-molded specialists and commodity thermoformers is rotating competitive advantage toward players with captive pulp supply. Pactiv Evergreen leverages its vertically integrated paperboard network to sustain margin control across North American foodservice accounts. Huhtamaki Oyj anchors its position through proprietary molded-fiber technology that dominates European quick-service chain specifications. Amcor plc competes by extending its flexible packaging R&D into barrier-coated paper bowls for hot-fill applications.
Food trays and bowls are rigid or semi-rigid containers engineered from thermoformed plastic, molded fiber, aluminum sheet, or laminated paperboard, typically dimensioned to standard gastronorm or fractional sizes for portion control and automated filling lines. Their primary commercial purpose is to contain, protect, and present prepared food across away-from-home and retail channels while enabling temperature retention and stackable logistics. The biodegradable segment leads value creation as EU Green Deal procurement mandates and U.S. state-level extended producer responsibility laws reshape buyer specifications, while plastic remains volume-dominant in emerging markets where cost thresholds govern purchasing. Paper-based trays occupy the fastest-expanding margin pool among quick-service chains seeking fiber alternatives to polystyrene, though aluminum sustains share in airline and rail catering where reheating compatibility is non-negotiable.
The U.S. EPA guides material recovery facility standards that affect tray recyclability claims, while FDA food-contact substance notifications govern barrier coatings in fiber bowls. The EU F-Gas Regulation and REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of oil-resistant coatings across export-bound production. Stakeholders must monitor pending state-level U.S. packaging EPR bills and EU packaging waste regulation implementation timelines to calibrate material transition investments before compliance windows narrow procurement options.
Market Dynamics
The EU Single-Use Plastics Directive and parallel state-level mandates in California are compressing procurement timelines for fiber-based alternatives, forcing thermoformers to retool lines before compliance windows close.
Growth Catalysts
- EU Green Deal procurement mandates:Institutional buyers across Germany, France, and Italy now require certified compostable tableware for public catering contracts, redirecting volume toward molded-fiber specialists.
- Quick-service restaurant packaging pivots:North American chains are specifying barrier-coated paper bowls for hot-fill applications, creating pull-through demand for pulp-integrated producers.
- India's plastic waste management rules:The country's central environmental regulator is enforcing extended producer responsibility frameworks that accelerate transitions to biodegradable alternatives in urban foodservice.
Market Restraints
- Pulp price volatility:Integrated players with captive pulp supply maintain margin stability while commodity thermoformers face input cost squeezes during fiber shortages.
- Barrier coating technical limitations:Current oil-resistant formulations struggle to match polyethylene performance in extended hold times, constraining adoption in fried-food segments.
- REACH per- and polyfluoroalkyl substance restrictions:The EU chemicals regulator is forcing reformulation cycles that extend product certification timelines by 12-18 months.
Strategic Opportunities
- Underpenetrated Indian institutional catering:State-level school meal programs and railway catering present volume openings for compostable tray suppliers meeting FSSAI food-contact standards.
- Airline catering reheating compatibility:Aluminum tray alternatives with dual-ovenable fiber construction could capture share in premium cabin service where temperature retention is non-negotiable.
- California SB 54 implementation:The state's packaging extended producer responsibility law creates procurement preference for post-consumer recycled content in quick-service bowls.
Industry Challenges
- Molded-fiber tooling capex intensity:Automated fiber-molding lines require capital deployment 3-4x thermoforming equipment, stretching mid-tier producer balance sheets.
- Composting infrastructure certification mismatches:Industrial compostable claims face verification gaps where municipal facilities lack capacity to process certified products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Trays and Bowls Market |
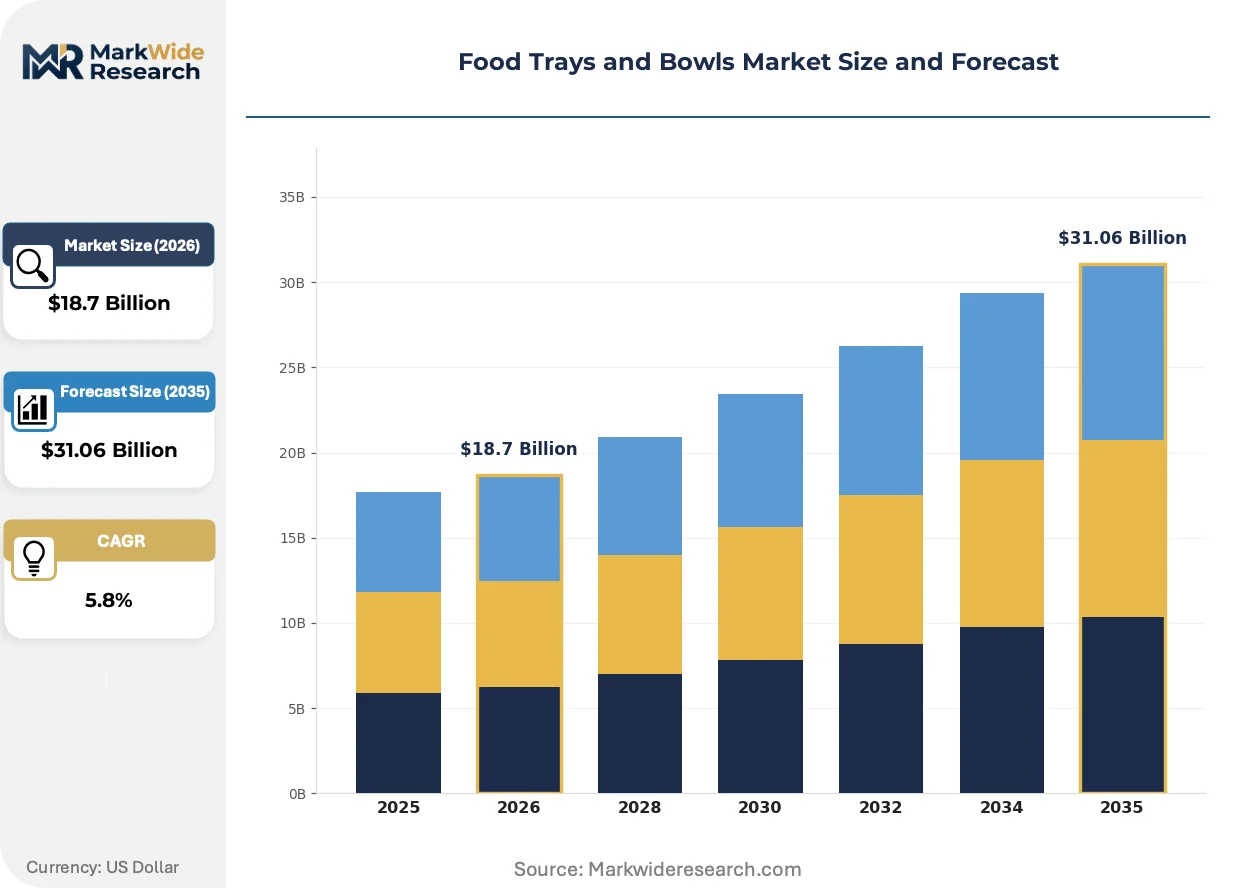
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Styrofoam Material: Plastic, Paper, Aluminum, Wood End User: Restaurants, Cafes, Catering Services, Home Use Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Pactiv Evergreen Inc., Huhtamaki Oyj, Amcor plc, Genpak LLC, Dart Container Corporation, Anchor Packaging, Mondi plc, Sealed Air Corporation, D&W Fine Pack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Trays and Bowls Market Trends and Innovations
Material science breakthroughs and regulatory compliance engineering are converging to reshape competitive advantage, with barrier performance and end-of-life verification becoming primary purchase criteria.
Barrier-coated molded fiber is decomposing the historical performance gap between paper-based and plastic alternatives. Quick-service chains in Germany and California are specifying these bowls for hot soups and sauced entrees. The technology is decomposing polystyrene's residual hold in grab-and-go applications by matching 30-minute heat retention benchmarks.
REACH restrictions on per- and polyfluoroalkyl substances are forcing coating chemistry redesigns across export-bound production. European thermoformers are accelerating partnerships with bio-barrier specialists to maintain EU market access. Fiber bowl manufacturers serving cross-border quick-service accounts face the steepest compliance cost curves.
Certification-driven procurement is consolidating buyer specifications around third-party compostability verification. Institutional foodservice distributors in France and Italy are rejecting uncertified alternatives regardless of price position. German municipal caterers now embed TÜV or OK Compost requirements directly into tender documents.
Food Trays and Bowls Market Segmentation
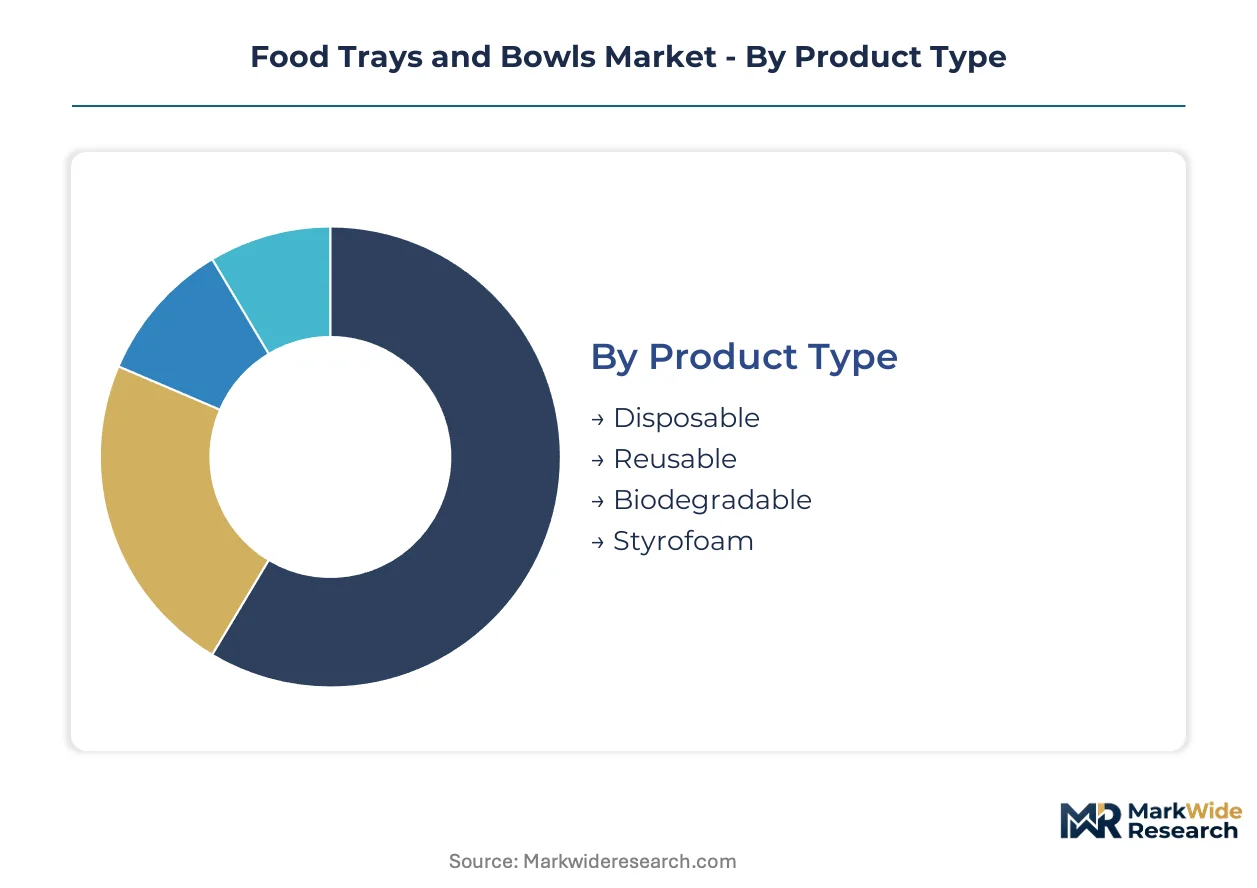
Segmentation in food trays and bowls tracks how procurement specifications diverge across institutional buyers, quick-service chains, and retail channels. Each dimension reveals where margin pools concentrate and which material transitions are accelerating.
Product Type:
Channel mix varies sharply: disposable products dominate quick-service and airline catering through wholesale distributors, while reusable formats concentrate in contract foodservice and premium restaurant accounts.
- Disposable:Single-use containers engineered for thermoformed plastic or molded fiber, optimized for automated filling lines and stackable logistics. Quick-service chains across Germany and California are specifying barrier-coated paper variants to meet EU Green Deal and state EPR procurement mandates.
- Biodegradable:Certified compostable tableware molded from bagasse or bamboo pulp with oil-resistant coatings. Institutional distributors in France and Italy now embed TÜV or OK Compost requirements directly into tender documents, redirecting public catering volume.
- Reusable:Durable melamine or stainless-steel formats for contract catering and corporate cafeterias. These products circulate through rental-pool models in Scandinavian institutional foodservice.
- Styrofoam:Expanded polystyrene trays retaining residual share in emerging markets and cost-sensitive fried-food segments. REACH restrictions and state-level bans are compressing procurement timelines for this category.
By volume, disposable leads. By growth pace, biodegradable is climbing the fastest.
Material:
Cost tiers separate commodity thermoformers from integrated fiber specialists with captive pulp supply and proprietary barrier technology.
- Plastic:Polypropylene and PET thermoformed trays dominating emerging market foodservice where cost thresholds govern purchasing. India's plastic waste management rules are forcing transitions to biodegradable alternatives in urban channels.
- Paper:Laminated paperboard and molded-fiber bowls with aqueous or PLA barrier coatings. North American chains are specifying these for hot-fill applications, creating pull-through demand for pulp-integrated producers.
- Aluminum:Sheet-metal trays for airline and rail catering where reheating compatibility is non-negotiable. Premium cabin service specifications sustain this segment despite fiber alternatives.
- Wood:Molded wood-pulp or bamboo composites for certified compostable tableware. German municipal caterers prioritize this material for public procurement contracts.
Plastic holds the largest volume position. Paper-based formats are gaining share fastest as quick-service chains pivot from polystyrene.
End User:
Application requirements dictate performance specifications: temperature retention, barrier duration, and end-of-life certification.
- Restaurants:Full-service and casual-dining accounts specifying portion-controlled trays for dine-in and takeout. California's SB 54 implementation is creating procurement preference for post-consumer recycled content in these channels.
- Catering Services:Institutional and event catering requiring certified compostable tableware for large-volume contracts. EU Green Deal mandates are redirecting volume toward molded-fiber specialists in Germany, France, and Italy.
- Cafes:Coffee-shop chains and bakery formats using bowls for hot soups and grain bowls. Barrier-coated molded fiber is displacing polystyrene by matching 30-minute heat retention benchmarks.
- Home Use:Retail-packaged trays and bowls for consumer preparation and storage. Supermarket private-label programs are expanding recycled-content offerings in this segment.
Catering services generate the highest certification-driven premiums. Restaurants represent the steepest volume expansion as quick-service chains retool specifications.
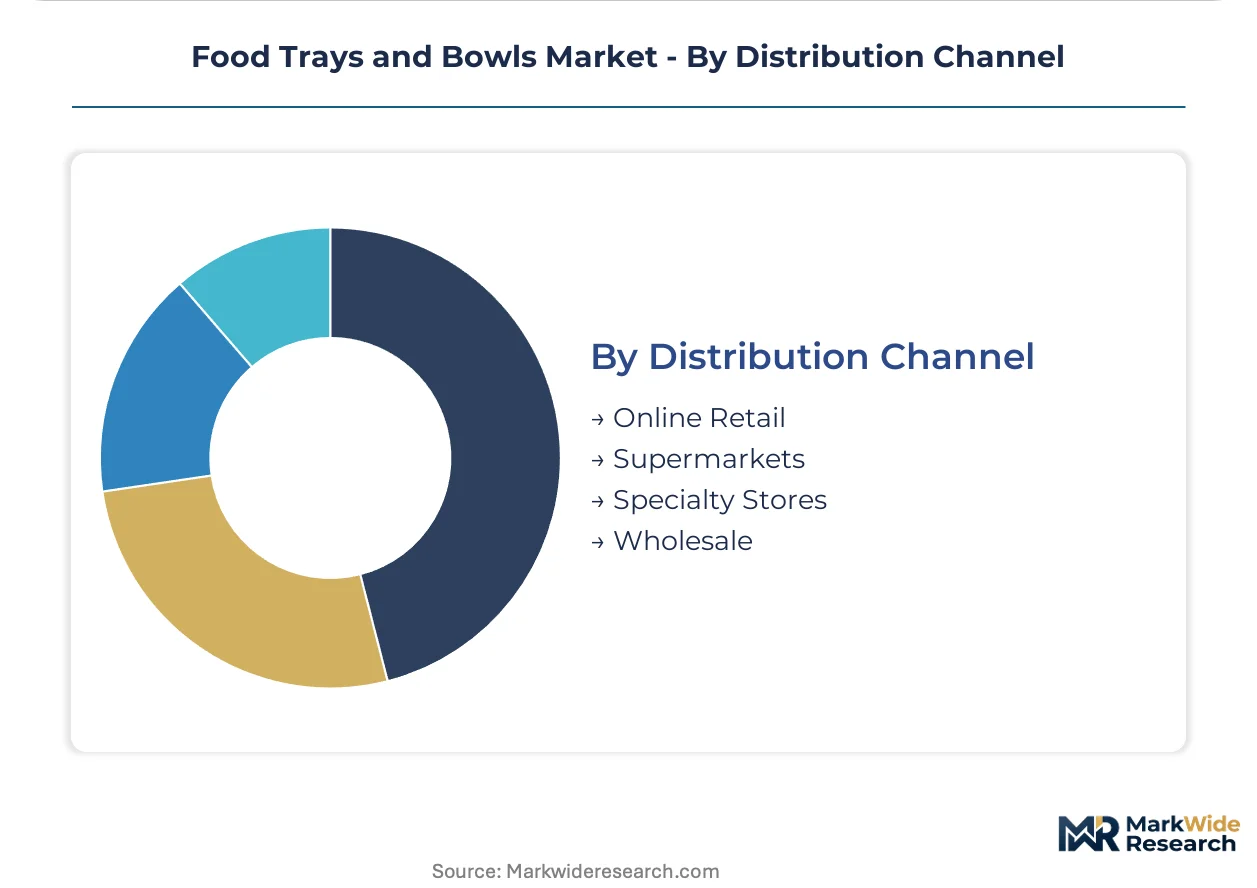
Distribution Channel:
Supply concentration shapes how products reach end users: wholesale dominates institutional accounts, while retail channels fragment across supermarket and specialty-store networks.
- Wholesale:Foodservice distributors supplying quick-service chains, airlines, and institutional caterers with pallet-scale procurement. These channels prioritize certified compostable specifications for EU and California accounts.
- Supermarkets:Mass retail carrying private-label and branded disposable tableware for home use. Post-consumer recycled content claims are becoming standard in California locations.
- Online Retail:E-commerce platforms aggregating specialty and bulk purchases for small restaurants and home consumers. Barrier-coated fiber bowls are gaining visibility in premium positioning.
- Specialty Stores:Eco-focused retailers and restaurant-supply showrooms emphasizing certified compostable and reusable formats. TÜV and OK Compost verification drives assortment decisions.
Wholesale channels move the highest volume. Online retail is expanding most quickly as procurement digitizes across smaller foodservice accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in molded-fiber food trays concentrate in Germany and the United States, with both countries running structural trade surpluses in certified compostable tableware while importing commodity thermoformed plastics from Asian manufacturing hubs.
Germany
Municipal caterers in Berlin and Hamburg are embedding TÜV compostability requirements directly into tender documents for institutional contracts. The EU Green Deal procurement mandates redirect public sector volume toward domestic molded-fiber specialists. Bavarian packaging clusters around Munich supply barrier-coated bowls to quick-service chains across Central Europe.
United States
California's SB 54 extended producer responsibility law creates procurement preference for post-consumer recycled content in quick-service bowls. The EPA guides material recovery facility standards that affect tray recyclability claims nationwide. Foodservice distributors in the Pacific Northwest prioritize fiber-based alternatives for corporate cafeteria contracts.
India
State-level school meal programs in Maharashtra and railway catering operations generate volume demand for FSSAI-compliant compostable trays. The central environmental regulator enforces plastic waste management rules that accelerate transitions to biodegradable alternatives in urban foodservice. Gujarat-based converters supply bagasse tableware to institutional buyers in Delhi-NCR and Mumbai.
France
Institutional foodservice distributors in Paris and Lyon reject uncertified alternatives regardless of price position. ANSM and ECHA frameworks govern food-contact substance notifications for barrier coatings in export-bound production. The Île-de-France region concentrates demand from airline catering operators seeking reheating-compatible formats.
China
Dual carbon goals and MIIT industrial policies are retooling manufacturing bases in Guangdong and Zhejiang toward pulp-integrated production. SAMR standards enforcement is phasing out expanded polystyrene in major urban foodservice channels. Yangtze River Delta converters supply molded-fiber bowls to quick-service chains across Southeast Asia.
Food Trays and Bowls Market Competitive Landscape
Concentration sits with integrated fiber-molded specialists and diversified packaging conglomerates. The vendor base spans three tiers: pulp-integrated producers with captive raw material supply, diversified multinational converters with cross-category R&D platforms, and regional thermoformers serving cost-sensitive emerging markets. Dominant competitive moves include strategic partnerships with bio-barrier coating specialists and geographic expansion into underpenetrated institutional catering segments.
Among North American packaging conglomerates, Pactiv Evergreen Inc. exemplifies the integrated fiber-molded archetype through its vertically organized paperboard network. Huhtamaki Oyj and Amcor plc represent the diversified multinational tier, with the former anchoring European quick-service specifications and the latter extending flexible packaging capabilities into barrier-coated formats. Genpak LLC and Dart Container Corporation occupy positions within the regional thermoforming segment.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc. |
| Huhtamaki Oyj |
| Amcor plc |
| Genpak LLC |
| Dart Container Corporation |
| Anchor Packaging |
| Mondi plc |
| Sealed Air Corporation |
| D&W Fine Pack |
| Others |
Pricing and Supply Chain Analysis
Sixty-day fiber pulp inventory cycles across European molded-fiber producers compress margin buffers when Baltic birch supply tightens, concentrating pricing power with vertically integrated players holding captive pulp assets while forcing spot-market dependent thermoformers into defensive contract renegotiations.
Pricing Analysis
Configured-to-order barrier-coated bowls command 35-50% premiums over standard molded-fiber formats, with pricing stratifying across premium, standard, and economy tiers based on certification grade and oil-resistant coating performance. Price differentiation hinges on TÜV/OK Compost verification and volume scale, with institutional buyers in Germany and France showing lowest sensitivity due to EU Green Deal procurement mandates. Cost compression in commodity thermoformed plastic is intensifying as REACH reformulation cycles extend certification timelines, while quick-service chains in California face margin tightening from SB 54 recycled-content requirements.
Supply Chain Analysis
Inventory-to-delivery lead times stretch 45-90 days for barrier-coated fiber bowls sourced from German and Chinese manufacturing clusters, with pulp supply anchored in Nordic and Southeast Asian forestry networks. Raw material dependencies center on bleached kraft pulp, aqueous barrier polymers, and aluminum sheet for dual-ovenable formats. Tariff exposure on coated paperboard imports from China creates vulnerability for North American distributors. Distribution runs through foodservice wholesalers supplying pallet-scale procurement to quick-service chains and institutional caterers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food tray and bowl procurement is shifting toward platform-standardized certification systems where TÜV and BPI interoperability unlocks institutional contract access, creating winner-take-most dynamics for suppliers embedding compliance into product architecture.
For Market Incumbents: Secure captive pulp supply through backward integration into Nordic or Southeast Asian forestry assets to defend margin stability against fiber price volatility. Deepen barrier-coating R&D partnerships with bio-polymer specialists to maintain EU market access as REACH restrictions tighten on per- and polyfluoroalkyl substance formulations.
For New Entrants and Emerging Players: Anchor in underpenetrated Indian institutional catering, specifically Maharashtra school meal programs and railway foodservice where FSSAI compliance creates addressable entry barriers. Pursue white-label manufacturing partnerships with Gujarat-based bagasse converters to bypass capital-intensive automated fiber-molding lines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates divesting non-core thermoforming divisions amid material transition pressures. Mid-tier European molded-fiber specialists with TÜV-certified product lines and existing quick-service chain relationships represent the highest viability acquisition profile over the five-to-ten year regulatory compliance window. Monitor California SB 54 implementation enforcement as the signal to watch for recycled-content premium inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Nordic forestry partnerships insulate margin stability from Baltic birch price volatility cycles. |
| Bio-Barrier Coating R&D Partnership | Collaboration with aqueous polymer specialists maintains EU market access under REACH restrictions. |
| Certification Platform Standardization | TÜV-BPI interoperability unlocks institutional procurement contracts across Germany and California. |
| Geographic Expansion into Indian Institutional Catering | Maharashtra school meal and railway contracts offer volume scale with FSSAI compliance barriers. |
| Post-Consumer Recycled Content Scale-Up | California SB 54 alignment captures procurement preference in Pacific Northwest corporate cafeteria channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging foodservice procurement directors at quick-service chains, molded-fiber plant managers in Germany and China, barrier-coating R&D leads, and institutional catering contract officers. Secondary validation drew from EU ECHA substance restriction filings, FDA food-contact substance notifications, U.S. EPA material recovery facility standards, and trade flow data from pulp and paperboard customs records. Bottom-up volume triangulation across product-type and material-grade segments was cross-checked against top-down market sizing from channel distribution analysis.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, material substrate, end-user application, and distribution channel, with particular attention to certification-grade tiering and geographic regulatory cluster effects. CAGRs were derived from trend extrapolation of procurement specification shifts, pulp price elasticity modeling, and compliance timeline compression scenarios. Industry-specific inputs included EU Green Deal mandate implementation pacing and California EPR law enforcement intensity.
Material uncertainties — regulatory enforcement variance, pulp supply disruption events, and barrier-coating performance breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions about compliance window timing and substitution elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Restaurant Dish Delivery Equipment Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Coffee Equipment and Supplies Market