
 Hardwood Market | 2026-2036
Hardwood Market Size, Share, and Industry Trends Forecast 2026-2036
Hardwood Market Outlook
The gap between premium-grade and commodity hardwood is shifting from a simple price divide into a structural separation defined by certification pedigree, drying precision, and provenance traceability. Weyerhaeuser leverages its Pacific Northwest timber base to sustain vertical control from stump to kiln-dried lumber. Georgia-Pacific competes through massive southern yellow pine and hardwood processing complexes that anchor regional supply.
Hardwood comprises dense, deciduous timber species—principally oak, maple, cherry, and walnut—typically characterized by Janka hardness ratings exceeding 1,000 lbf and slow growth rings that yield dimensional stability for precision milling. Its primary commercial purpose spans structural joinery, interior finishes, and high-wear surfaces where aesthetics and durability converge. Oak dominates volume across residential flooring and cabinetry applications where grain uniformity commands premium positioning, while walnut occupies narrower but higher-margin niches in bespoke furniture and musical instrument fabrication. Common and industrial grades serve construction and renovation channels where cost efficiency outweighs appearance specifications.
The U.S. EPA oversees formaldehyde emission standards under TSCA Title VI, directly shaping panel and composite hardwood product market access, while EU Timber Regulation and EUTR due diligence frameworks enforce legality verification across European supply chains. The Lacey Act amendments in the United States criminalize trade in illegally harvested timber, forcing importers to document species origin and chain of custody. Stakeholders must monitor evolving deforestation-free procurement mandates in both jurisdictions, as compliance architecture increasingly determines supplier eligibility rather than merely product quality.
Market Dynamics
Certification pedigree and chain-of-custody traceability are splitting the hardwood market into parallel supply tiers, with EU Timber Regulation due diligence and U.S. Lacey Act enforcement now determining supplier eligibility before price negotiation begins.
Growth Catalysts
- EU Timber Regulation due diligence:Mandatory legality verification across European supply chains is filtering out uncertified suppliers and concentrating volume with verified sustainable sources.
- Residential flooring renovation cycles:North American housing stock turnover and Western European energy-efficiency retrofits are sustaining replacement demand for premium-grade oak and maple installations.
- Kiln-drying precision advances:Computer-controlled moisture management is reducing dimensional instability defects, enabling tighter tolerances for precision joinery and musical instrument fabrication.
Market Restraints
- Old-growth harvest restrictions:Pacific Northwest and Appalachian supply constraints on high-density walnut and cherry are compressing premium-grade availability and extending lead times.
- Formaldehyde emission compliance costs:U.S. EPA TSCA Title VI testing and certification requirements for panel products are raising fixed costs for smaller composite hardwood manufacturers.
- Engineered wood substitution:Cross-laminated timber and high-density fiberboard are capturing structural applications where appearance specifications are secondary.
Strategic Opportunities
- Digital chain-of-custody platforms:Blockchain-enabled provenance tracking is creating differentiation premiums for suppliers who can deliver species-origin documentation from stump to finished product.
- Bespoke furniture fabrication:Custom millwork and artisanal cabinetry in Germany and Canada are absorbing higher-margin walnut and exotic hardwood grades that commodity flooring cannot absorb.
- Deforestation-free procurement mandates:Corporate sustainability commitments in the United States are accelerating preference for Forest Stewardship Council-certified supply, rewarding early compliance investments.
Industry Challenges
- Drying technician skill scarcity:Specialized kiln operation expertise is retiring faster than vocational programs can replenish, constraining capacity expansion at independent mills.
- Multi-jurisdiction certification stacking:Suppliers serving both U.S. and EU markets must maintain parallel documentation systems for Lacey Act and EUTR compliance, raising administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardwood Market |
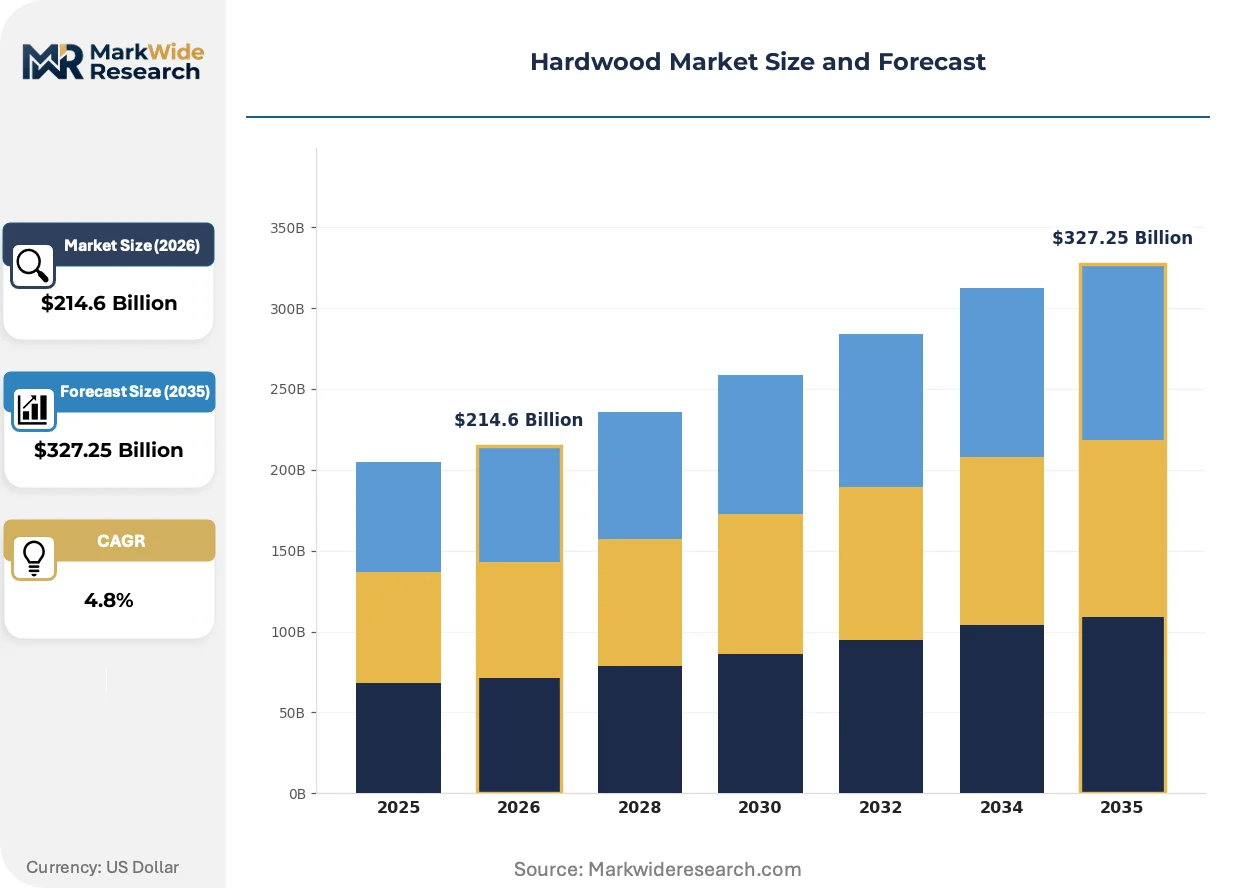
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $327.25 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oak, Maple, Cherry, Walnut End User: Furniture, Flooring, Cabinetry, Musical Instruments Grade: Premium, Select, Common, Industrial Application: Residential, Commercial, Construction, Renovation |
| Companies Covered | Canfor, UFP Industries, Weyerhaeuser, Hampton Affiliates, Boise Cascade Company, West Fraser, Georgia-Pacific, Interfor, Sierra Pacific Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardwood Market Strategic Shifts
Digital traceability infrastructure and precision moisture management are converging to redefine quality assurance in hardwood supply chains, compressing the information asymmetry that historically separated premium from commodity grades.
Thermal modification technology is expanding into residential decking and exterior cladding applications where untreated hardwood faces durability limitations. Scandinavian and German producers are scaling capacity for thermally treated oak and ash. The process is expanding into markets previously dominated by tropical hardwood imports, redirecting species substitution patterns.
EU Deforestation Regulation enforcement timelines are tightening due diligence windows for European importers. The framework requires geolocation verification for all timber sourced after December 2024. Panel manufacturers and flooring distributors in Germany and France are restructuring supplier portfolios to preempt compliance gaps.
Architects and commercial developers are consolidating specification authority around certified sustainable sourcing credentials. Design firms in Canada and the United States are embedding Forest Stewardship Council requirements into standard contract templates. This concentration of buying criteria is marginalizing uncertified mills from commercial project pipelines.
Hardwood Market Segmentation
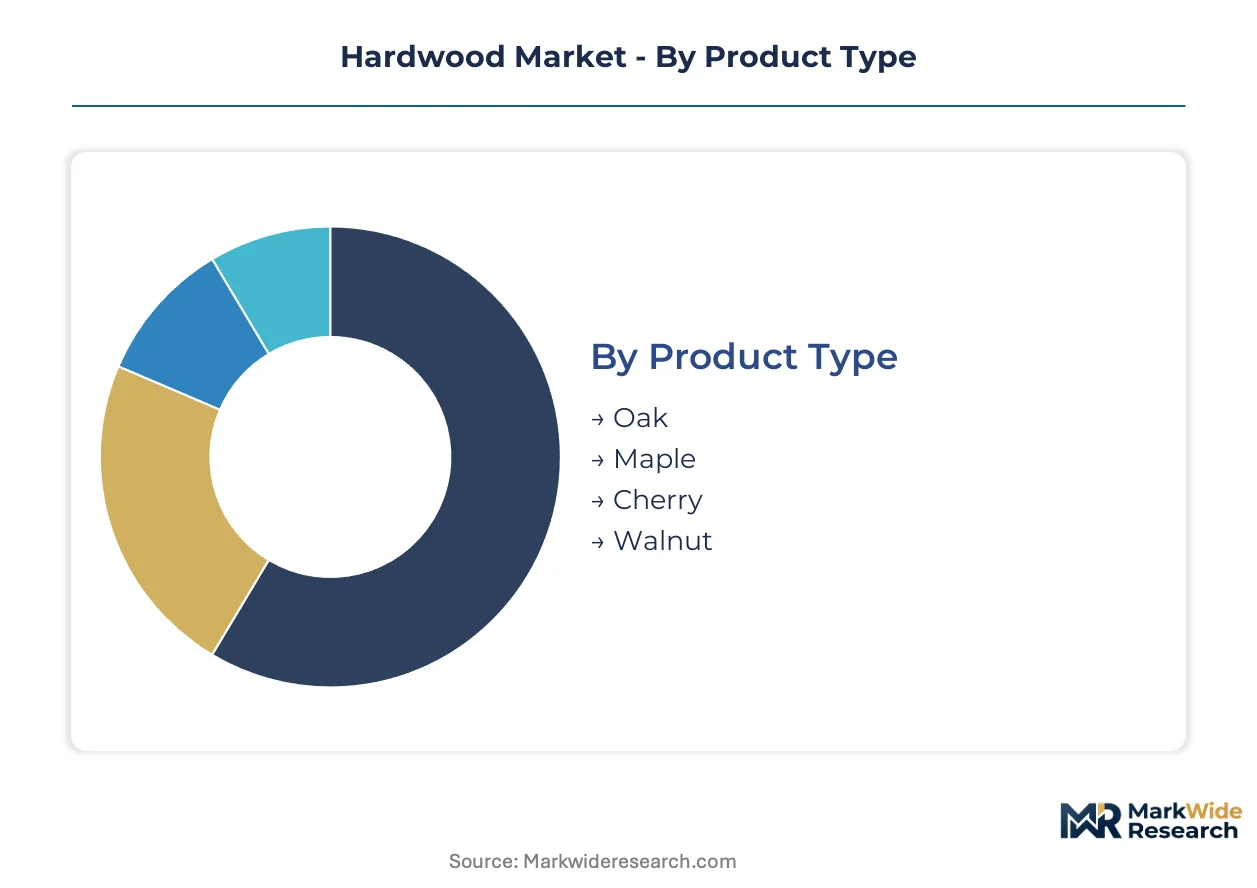
Hardwood procurement decisions now pivot on certification pedigree and end-use performance specifications rather than species alone. Buyers segment supply by grade precision, application durability requirements, and chain-of-custody documentation that satisfies multi-jurisdiction compliance mandates.
Product Type:
Species selection follows end-use hardness requirements and grain aesthetics, with buyers prioritizing dimensional stability for precision milling applications.
- Oak:Dense deciduous timber with pronounced grain patterns and Janka hardness exceeding 1,000 lbf. Flooring contractors in Germany and residential renovators across the United States specify white and red oak variants for high-traffic surfaces where wear resistance and visual consistency command specification priority.
- Maple:Fine, uniform grain structure delivers superior machinability for tight-tolerance joinery. Canadian millwork shops and U.S. cabinetry fabricators concentrate demand for hard maple grades that accept stains evenly and resist indentation in kitchen and bathroom installations.
- Cherry:Rich reddish-brown patina develops with oxidation, prized for executive furniture and high-end interior millwork.
- Walnut:Dark chocolate tones and workability position this species for bespoke furniture and musical instrument fabrication where material cost is secondary to acoustic or aesthetic performance.
Oak leads on scale; walnut leads on momentum.
End User:
Volume concentration varies sharply by margin structure, with specification authority consolidating around architects and commercial developers who mandate certified sourcing.
- Flooring:Engineered and solid hardwood planks for residential and commercial surface applications. German distributors and U.S. home improvement retailers drive specification of FSC-certified oak and maple for renovation cycles tied to housing stock turnover and energy-efficiency retrofits.
- Furniture:Solid stock and dimension lumber for residential, office, and hospitality furnishings. Artisanal producers in Canada and industrial manufacturers in the United States absorb premium walnut and cherry grades that command price premiums through design positioning.
- Cabinetry:Dimensionally stable grades for kitchen, bath, and built-in storage systems.
- Musical Instruments:Resonance-graded tonewoods for pianos, guitars, and orchestral instruments.
Flooring dominates absolute volume; musical instruments claim the steepest expansion trajectory.
Grade:
Quality tiers now function as compliance gateways, with premium and select grades requiring documented chain-of-custody that commodity suppliers cannot furnish.
- Premium:Clear, uniform grain with minimal defects and precise moisture content control. German flooring distributors and U.S. architectural millwork specifiers require this tier for commercial projects where appearance specifications and EUTR documentation are non-negotiable.
- Select:Sound knots and color variation permitted within defined tolerances. Residential contractors in Canada and renovation specialists across Western Europe specify select grades where cost efficiency must balance visual acceptability.
- Common:Greater defect allowance for paint-grade or structural applications.
- Industrial:Utility grades for pallets, crating, and non-appearance construction uses.
Premium leads on margin capture; select leads on volume throughput.
Application:
Demand fragmentation across project types forces suppliers to maintain parallel inventory positions for specification-driven commercial work and price-sensitive renovation channels.
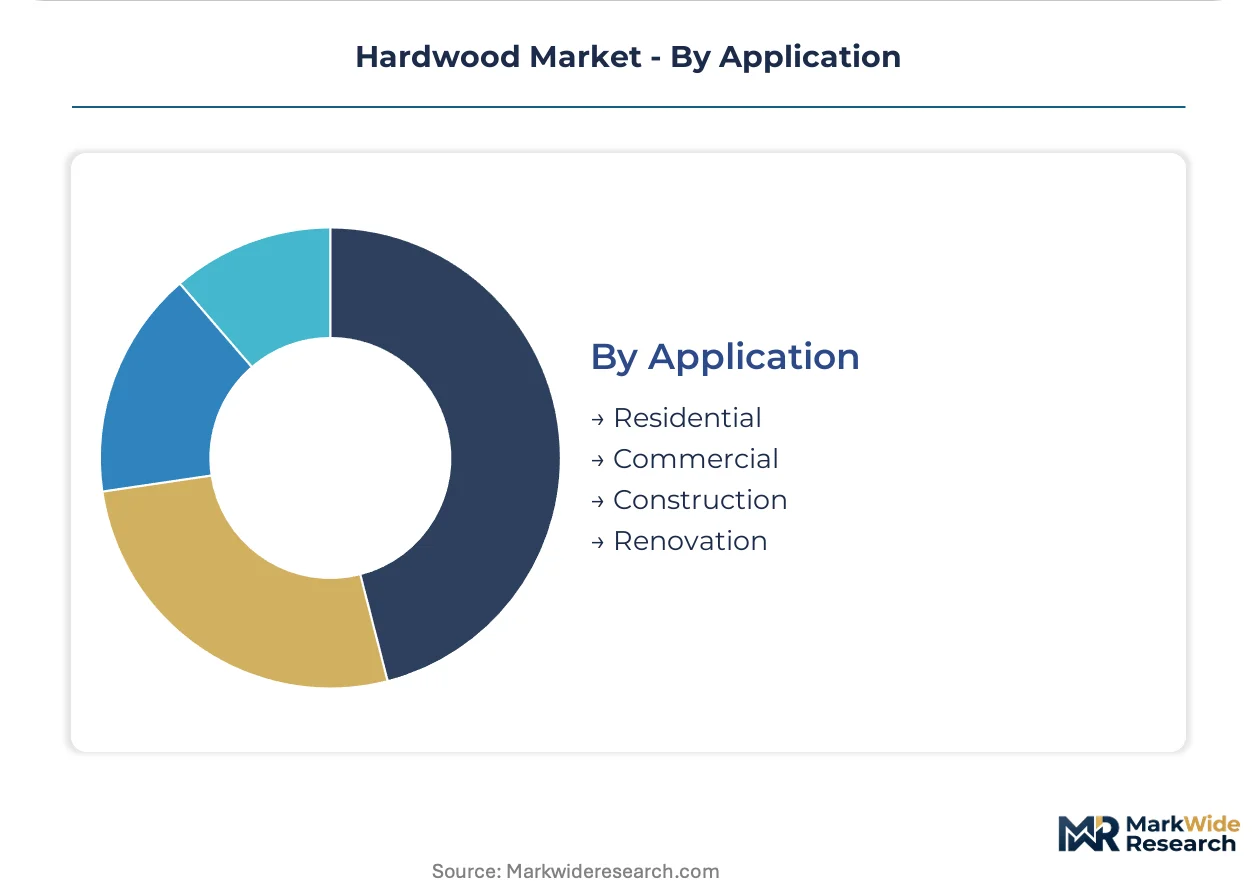
- Residential:Single-family and multi-family interior finishes including flooring, trim, and built-ins. U.S. housing market activity and Western European energy retrofit programs sustain replacement demand for certified oak and maple installations.
- Commercial:Offices, hospitality, retail, and institutional interiors where architect specifications govern procurement. Design firms in Canada embed FSC requirements into standard contract templates, filtering supplier eligibility before price negotiation.
- Construction:Structural and non-structural uses in new building projects.
- Renovation:Replacement and upgrade of existing residential and commercial interiors.
Residential anchors current volume; commercial is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium-grade procurement authority through its flooring distribution networks, while the United States anchors absolute consumption volume through residential renovation cycles and commercial construction pipelines.
United States
Residential flooring replacement and multi-family construction absorb certified oak and maple grades from Pacific Northwest and Appalachian supply basins. EPA TSCA Title VI enforcement shapes panel product market access through formaldehyde emission testing protocols. Weyerhaeuser's vertical control from Oregon timberlands to kiln-dried lumber sustains specification-grade output for architectural millwork.
Germany
Energy-efficiency retrofits across Western European housing stock sustain demand for FSC-certified engineered flooring. EU Timber Regulation due diligence mandates filter supplier eligibility before price negotiation begins. Hamburg and Bremen distribution clusters restructure procurement portfolios to accommodate EU Deforestation Regulation geolocation requirements.
Canada
Hard maple production from Quebec and Ontario feeds precision millwork shops serving U.S. cabinetry and furniture fabricators. Health Canada and PMRA oversight aligns with U.S. Lacey Act documentation demands for cross-border species verification. British Columbia interior mills concentrate on select-grade hemlock and Douglas fir for structural applications.
France
Commercial interior specifications in Paris and Lyon embed Forest Stewardship Council requirements into standard contract templates. ANSM and CNIL frameworks intersect with EU-wide timber legality verification for imported exotic species. Bordeaux and Nantes port clusters handle thermally modified oak shipments from Scandinavian producers.
China
Domestic furniture manufacturing absorbs lower-grade hardwood imports for re-export finishing operations. MEE and SAMR oversight of GB standards for wood product emissions shapes factory-level compliance investments. Zhejiang and Guangdong province clusters concentrate on value-added processing rather than raw material extraction.
Hardwood Market Competitive Environment
Top-tier vendors anchor integrated timber-to-lumber operations, while mid-scale independents compete through specialty drying capabilities and regional certification relationships. The vendor base stratifies across stump-to-kiln operators, commodity-grade processors, and precision-finish specialists. Three archetypes dominate: vertically integrated timberland owners, regional sawmill cooperatives, and custom-dry service providers. Competitive moves concentrate on kiln capacity expansion and blockchain-enabled chain-of-custody partnerships.
Among North American timberland-based operators, Weyerhaeuser and Georgia-Pacific exemplify the integrated archetype through Pacific Northwest and southern U.S. processing complexes respectively. West Fraser occupies a position within the Canadian dimension-lumber segment. These three represent contrasting geographic and operational models without implying equivalent scale or strategic priority.
| Leading Market Players |
|---|
| Canfor |
| UFP Industries |
| Weyerhaeuser |
| Hampton Affiliates |
| Boise Cascade Company |
| West Fraser |
| Georgia-Pacific |
| Interfor |
| Sierra Pacific Industries |
| Others |
Value Chain & Pricing Dynamics
Drying technician concentration in the Appalachian and Pacific Northwest regions feeds directly into premium-grade pricing spreads, as labor-cost differentials between certified kiln operators and commodity handlers widen the gap between select and common tier quotations. Certification pedigree now commands a structural premium that uncertified suppliers cannot bridge through volume discounts alone.
Pricing Analysis
Bundled chain-of-custody documentation versus unbundled commodity spot sales defines the pricing architecture across hardwood grades. Three-tier pricing structure across premium, select, and common levels separates certified sustainable supply from conventional alternatives, with FSC documentation and kiln-precision certification as primary differentiation drivers. Pricing pressure stems from engineered wood substitution in structural applications, compressing margins at the common grade tier. Residential renovation contractors exhibit highest price sensitivity, while commercial architects specifying commercial interiors demonstrate lowest sensitivity due to mandated sustainability credentials.
Supply Chain Analysis
Reverse-logistics flows for certified hardwood scrap and sawdust recovery are emerging as secondary revenue streams for mills serving furniture and musical instrument fabricators. Raw material supply concentrates in the United States, Canada, and Germany, with Appalachian and Pacific Northwest stumpage feeding premium-grade output. The chain draws from oak, maple, walnut, and cherry feedstocks, with moisture-content precision requirements tightening input specifications. Single-source vulnerability around specialized kiln-drying expertise constrains capacity expansion. Distribution runs through Hamburg and Bremen clusters in Germany, Pacific Northwest port terminals in the United States, and Quebec-Ontario mill networks serving cross-border cabinetry demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardwood procurement functions as a geographic-arbitrage play between EU Timber Regulation compliance costs in Germany and residual Lacey Act documentation burdens in the United States, with certification investment differentials creating margin capture opportunities for dual-jurisdiction suppliers.
For Market Incumbents: Extend certification coverage into emerging deforestation-free procurement mandates before compliance windows tighten, capturing specification authority from architects who embed Forest Stewardship Council requirements into standard contract templates. Deepen upstream control over stump-to-kiln operations in the Pacific Northwest to secure walnut and cherry supply against old-growth harvest restrictions. Kiln capacity expansion with computer-controlled moisture management represents the priority defensive lever against precision-grade competition. For New Entrants and Emerging Players: Flooring distributors in energy-efficiency retrofit corridors offer the most penetrable channel partnership entry point, as German and Western European housing stock turnover sustains replacement demand for certified oak and maple installations. Target bespoke furniture fabrication niches in Canada and artisanal cabinetry segments where walnut premiums absorb higher material costs. A digital chain-of-custody platform go-to-market angle creates immediate differentiation against legacy documentation systems. For Investors and Strategic Acquirers: Valuations sit cheapest among regional sawmill cooperatives with dormant certification assets that can be activated for EU market access. The five-to-ten-year viability window favors suppliers with demonstrated EUTR and Lacey Act compliance infrastructure over commodity-grade processors facing substitution pressure. Acquisition target archetype: independent mills with specialized drying capabilities and underutilized Forest Stewardship Council chain-of-custody certificates. The signal to watch is EU Deforestation Regulation enforcement tightening, which will force portfolio restructuring among importers lacking geolocation verification systems.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Chain-of-Custody Deployment | Geolocation verification from stump to finished product satisfies EU Deforestation Regulation mandates for German importers. |
| Kiln-Drying Capacity Expansion | Computer-controlled moisture management reduces dimensional instability defects for precision joinery specifications. |
| Certification Portfolio Activation | Dormant FSC certificates unlock commercial project pipelines where architects mandate sustainable sourcing credentials. |
| Specialty Species Forward Contracting | Long-term offtake agreements with Appalachian and Pacific Northwest timberland owners secure walnut and cherry supply. |
| Thermal Modification Technology Scale-Up | Scandinavian process licensing expands residential decking applications previously dominated by tropical hardwood imports. |
Study Parameters
Multiple input streams — primary interviews with sawmill operators, flooring distributors, and architectural specification consultants, secondary validation through customs records and Forest Stewardship Council certification databases, and trade flow analysis from industry associations — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged kiln operations managers, commercial procurement officers at German distribution clusters, and sustainability directors at North American timberland owners. Secondary sources included EPA TSCA Title VI filing records, EU Timber Regulation enforcement disclosures, and hardwood production statistics from national forestry agencies.
Data-stream reconciliation across species-grade segmentation, end-use application splits, and regional regulatory clusters anchored the analytical framework over the projection horizon. The modeling period incorporated product type dimensions spanning oak, maple, cherry, and walnut; end-user categories covering flooring, furniture, cabinetry, and musical instruments; and grade tiers from premium through industrial. CAGRs were derived from trend extrapolation adjusted for regulatory enforcement intensity and substitution elasticity parameters. Forecast inputs included housing stock turnover rates, energy-efficiency retrofit program commitments, and certification adoption curves across commercial specification channels.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Deforestation Regulation enforcement calibration, engineered wood substitution rates in structural applications, and drying technician workforce replenishment trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Tote Bags Market
Others
Agitator Bead Mill Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Storm Surge Barriers Market
Others
Wearable Solar Devices Market
Others
Digital Transformation of Maritime Freight Market
Others
North America Industrial Wearable Devices Market
Others
Global Mobile Gambling Market
Others
Subtilisin Market
Others
Latin America 3D Printing Construction Market
Others
Automotive Smart Lighting Market
Others
Global Digital Caliper Market
Others
Europe Intercom Devices Market
Others
Singapore Retail Market
Others
Connected Homes Market
Others
Textile Composites Market