
 Slewing Bearing Market | 2026-2036
Slewing Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Slewing Bearing Market Analysis
Direct procurement between bearing makers and wind turbine OEMs is reshaping how slewing bearings reach end-use equipment. ThyssenKrupp Rothe Erde leverages captive forging capacity in Germany to supply extra-large diameters for offshore installations. SKF Group anchors European aftermarket service networks with condition monitoring bundles. Schaeffler AG competes through integrated heat-treatment lines that shorten lead times for crane manufacturers.
A slewing bearing is a rotational rolling-element bearing that supports heavy axial, radial, and moment loads simultaneously; typical designs incorporate hardened raceways, internal or external gear rings, and seals rated for contamination exposure in construction and energy applications. Four-point contact variants dominate installed base in mobile cranes due to compact load distribution, while cross-roller configurations capture margin pools in precision industrial robotics and medical imaging equipment. Steel remains the default material across construction and marine segments, though stainless specifications are penetrating food-processing and coastal wind applications where corrosion resistance commands price premiums.
OSHA crane safety standards, EU machinery directives, and China's GB/T specifications collectively mandate traceable load ratings and fatigue testing for certified installations. These frameworks push non-compliant suppliers toward retrofit obligations or market exit, tightening vendor qualification lists for major OEMs. Stakeholders must monitor evolving certification reciprocity between jurisdictions, as diverging test protocols threaten to fragment supplier pools and extend qualification timelines for new market entrants.
Market Dynamics
Direct procurement contracts between wind turbine OEMs and forging houses are compressing distributor margins while concentrating order books among suppliers with captive heat-treatment capacity. This structural shift favors vertically integrated manufacturers over merchant bearing specialists.
Growth Catalysts
- Offshore wind scale-up:China's coastal provinces and Germany's North Sea clusters are commissioning 8MW-plus turbines requiring extra-large diameter slewing rings with integrated internal gearing.
- OSHA crane safety mandates:US construction fleet operators must replace non-certified swing bearings under updated load-rating traceability rules, forcing hardware refresh cycles.
- Cross-roller precision demand:Industrial robotics OEMs in Japan and South Korea are specifying compact crossed-roller configurations for six-axis arm joints.
Market Restraints
- Specialized steel input volatility:Through-hardened raceway steel from European electric arc furnaces faces price swings tied to scrap metal and energy costs.
- Supply concentration risk:Four forging groups control 70% of rings above 4-meter diameter, creating bottleneck vulnerability for offshore wind projects.
- Technical limitation in corrosion protection:Standard zinc-flake coatings degrade faster than bearing fatigue life in salt-laden offshore environments.
Strategic Opportunities
- India port infrastructure:Jawaharlal Nehru Port and Mundra Port expansion projects specify heavy-lift cranes with load-monitoring slewing systems.
- EU Green Deal manufacturing incentives:Domestic content requirements for wind energy components are reshoring bearing assembly to European forging corridors.
- Digital twin convergence:Vibration sensor integration with predictive maintenance platforms enables condition-based replacement contracts.
Industry Challenges
- Non-destructive testing certification:Magnetic particle and ultrasonic inspection qualifications for offshore-grade bearings extend supplier onboarding by 14-18 months.
- Legacy crane retrofit complexity:Integrating modern sealed slewing assemblies with 1980s-era boom structures requires custom adapter fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slewing Bearing Market |
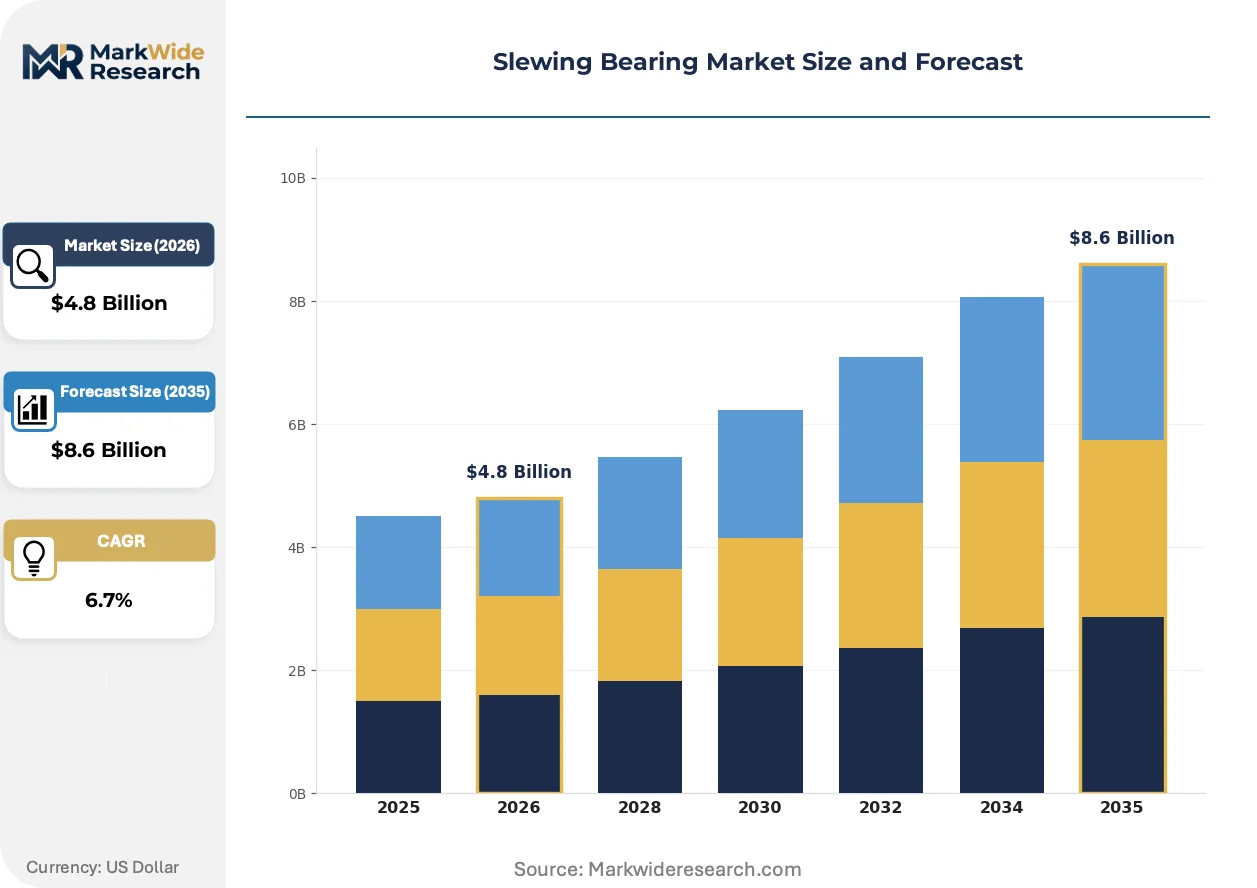
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Row, Double Row, Four Point Contact, Cross Roller Application: Construction, Renewable Energy, Marine, Industrial Machinery End User: OEMs, Aftermarket Providers, Utilities, Engineering Firms Material: Steel, Stainless Steel, Plastic, Bronze |
| Companies Covered | SKF Group, Schaeffler AG, ThyssenKrupp Rothe Erde, The Timken Company, NTN Corporation, JTEKT Corporation, Liebherr-International AG, Kaydon Corporation, IMO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slewing Bearing Market Emerging Trajectories
Material science breakthroughs and sensor integration are redefining how slewing bearings perform in extreme load cycles. These developments compress replacement intervals while opening new service revenue streams.
Ceramic hybrid rolling elements are collapsing maintenance schedules in wind turbine pitch and yaw systems. Vestas and Siemens Gamesa specify silicon nitride balls for their 6MW-plus platforms, cutting lubrication intervals from six months to two years. This material shift is collapsing the traditional aftermarket lubrication service market while transferring value capture to bearing OEMs with ceramic pressing capabilities.
EU machinery directives now mandate functional safety certification for crane slewing mechanisms in construction applications. The 2023 update to EN 13852 requires documented failure-mode analysis for bearings above 50-ton meter load moments. German and Dutch crane fleets are retrofitting older units to maintain site access, while Chinese exporters face compliance barriers without notified-body certification.
Long-term availability contracts are displacing spot purchasing for wind farm operators. Ørsted and Equinor now negotiate 15-year bearing supply agreements with embedded replacement scheduling and remote monitoring. This contracting shift concentrates procurement authority with EPC firms and away from regional distributors, visible most acutely in UK Round 4 and German Baltic Sea lease areas.
Slewing Bearing Market Segmentation
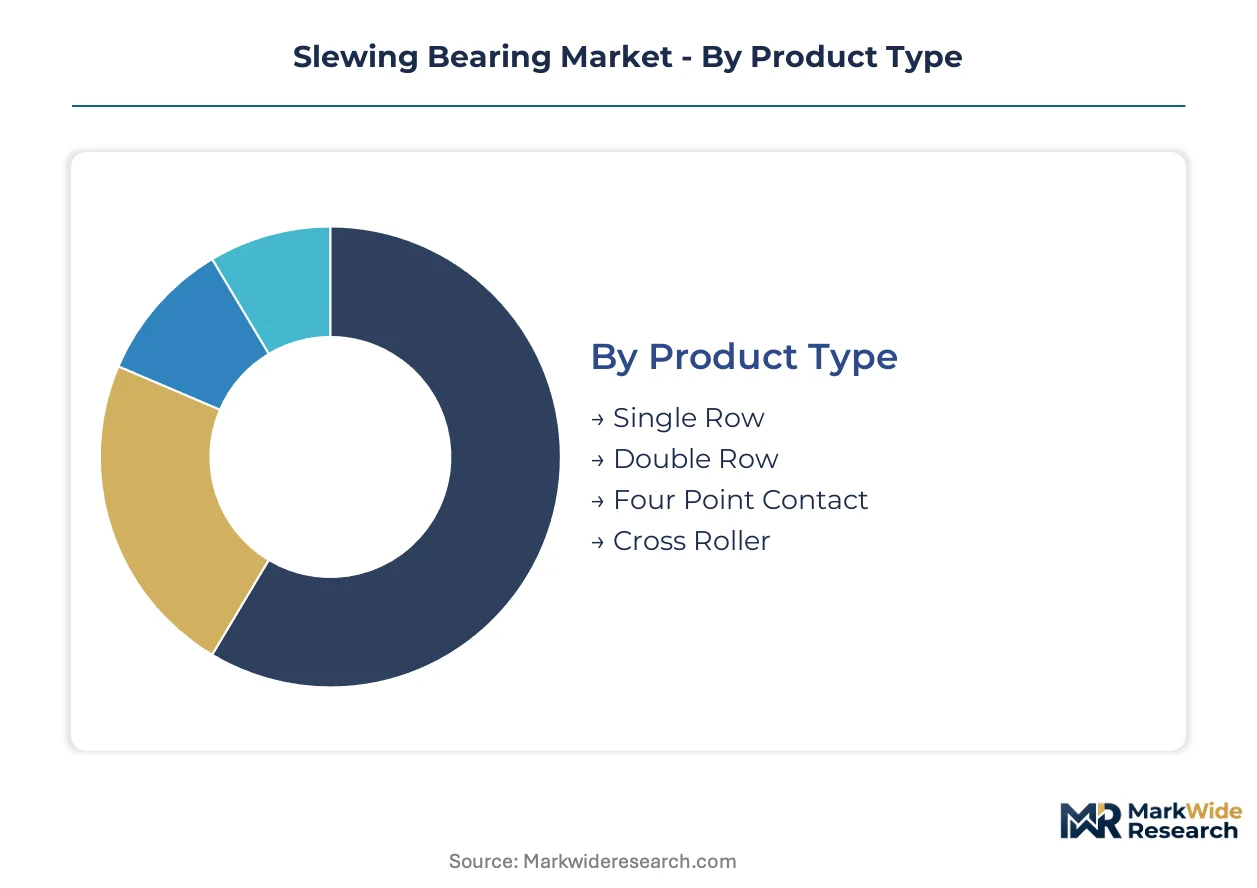
Slewing bearing procurement patterns diverge sharply across product architectures and end-use contexts. Understanding these splits reveals where margin pools concentrate and which specifications face tightening qualification barriers.
Product Type:
Mature designs dominate construction aftermarket volumes, while emerging configurations capture precision machinery specification shifts.
- Single Row:These bearings utilize one raceway with rolling elements arranged in a single circular path, delivering cost efficiency for light-to-moderate axial loads. Demand concentrates in mobile crane fleets across the US Great Lakes corridor, where OSHA-mandated refresh cycles are forcing hardware replacements on aging boom trucks. Single Row retains volume leadership; Four Point Contact holds the steepest expansion curve.
- Double Row:Twin raceway configurations distribute heavier combined loads through staggered rolling element arrays. German industrial belt crane OEMs specify these for harbor mobile cranes at Bremerhaven and Hamburg, where EU machinery directives now require documented fatigue ratings for dual-raceway assemblies. Double Row captures premium positioning in port infrastructure specifications.
- Four Point Contact:Angular contact raceways enable simultaneous axial, radial, and moment load handling through gothic arch geometry. Chinese wind turbine OEMs in Jiangsu and Guangdong provinces are scaling orders for 4-meter-plus diameters with integrated internal gearing.
- Cross Roller:Cylindrical rollers arranged at 90-degree angles deliver compact moment stiffness for precision rotation. Japanese and South Korean robotics manufacturers specify these for six-axis arm joints in semiconductor handling equipment.
Four Point Contact retains volume leadership; Cross Roller holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity construction procurement from premium renewable energy contracting.
- Construction:Tower cranes and mobile lifting equipment consume standardized bearing sizes with rapid replacement cycles. US fleet operators face compressed procurement timelines under updated OSHA load-rating traceability rules.
- Renewable Energy:Wind turbine pitch and yaw systems demand extra-large diameters with 25-year design life. Ørsted and Equinor negotiate 15-year supply agreements with embedded replacement scheduling for North Sea and Baltic installations.
- Marine:Deck cranes and offshore platform slewing systems require corrosion-resistant specifications. Standard zinc-flake coatings degrade faster than bearing fatigue life in salt-laden environments, creating specification pressure for alternative surface treatments.
- Industrial Machinery:Medical imaging gantries and semiconductor wafer handling systems prioritize rotational precision over load capacity. Cross-roller configurations dominate this specification band.
Construction retains volume leadership; Renewable Energy holds the steepest expansion curve.
End User:
Customer type determines contract structure, with direct OEM procurement displacing traditional distribution channels.
- OEMs:Wind turbine and crane manufacturers negotiate direct forging contracts, compressing distributor margins. ThyssenKrupp Rothe Erde supplies extra-large diameters from captive German capacity to Vestas and Siemens Gamesa.
- Aftermarket Providers:Service networks stock standardized sizes for construction fleet maintenance. SKF Group anchors European coverage with condition monitoring bundles tied to replacement scheduling.
- Utilities:Wind farm operators negotiate long-term availability contracts with embedded remote monitoring. UK Round 4 and German Baltic Sea lease areas show this contracting shift most acutely.
- Engineering Firms:EPC contractors concentrate procurement authority for port and infrastructure projects. Jawaharlal Nehru Port and Mundra Port expansions specify load-monitoring slewing systems through engineering-procurement channels.
OEMs retain volume leadership; Utilities hold the steepest expansion curve.
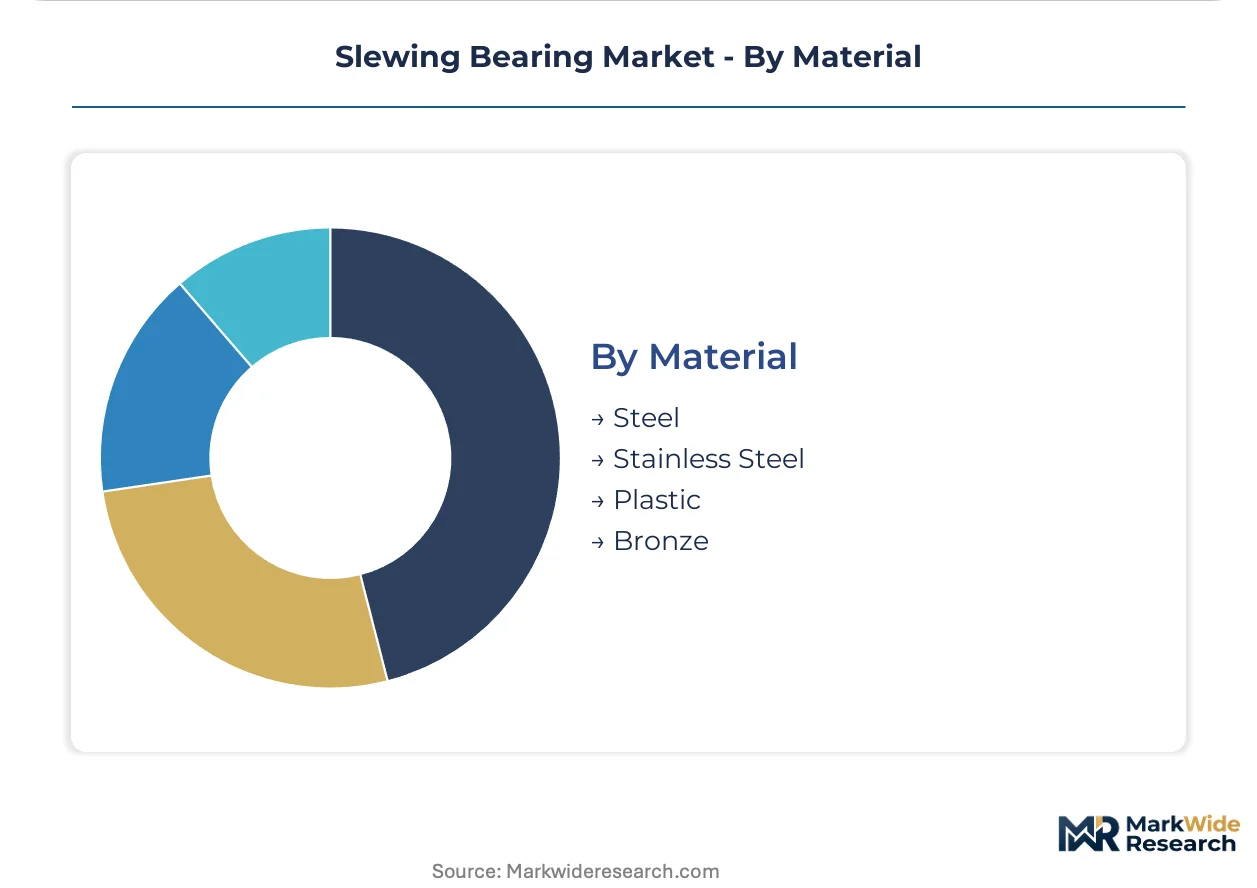
Material:
Application environment dictates material selection, with corrosion resistance commanding price premiums in coastal specifications.
- Steel:Through-hardened raceway grades remain default for construction and marine segments. European electric arc furnace output faces price volatility tied to scrap metal and energy input costs.
- Stainless Steel:Austenitic and martensitic specifications penetrate food-processing and coastal wind applications. Jiangsu province offshore installations increasingly specify these for salt-laden environments.
- Plastic:Polymer raceways serve light-load precision instruments where magnetic interference must be eliminated. Medical imaging equipment represents the primary demand pocket.
- Bronze:Copper-tin alloys deliver boundary lubrication tolerance for slow-speed heavy loads. Niche marine deck machinery applications persist despite higher material costs.
Steel retains volume leadership; Stainless Steel holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jiangsu coastal wind corridor anchors Chinese demand for extra-large diameter slewing rings, while German North Sea lease areas and the US Great Lakes manufacturing belt concentrate procurement authority for precision bearing assemblies.
China
Jiangsu and Guangdong province wind turbine OEMs are scaling orders for four-point contact bearings with integrated internal gearing above 4-meter diameter. GB/T standards now mandate traceable load ratings and fatigue testing for certified installations. The Yangtze River Delta forging corridor concentrates captive heat-treatment capacity for offshore wind projects.
Germany
North Sea offshore clusters are commissioning 8MW-plus turbines requiring extra-large slewing rings with 25-year design life. EU machinery directives and EN 13852 updates require documented failure-mode analysis for bearings above 50-ton meter load moments. The Ruhr industrial belt and Bremerhaven harbor zones concentrate crane OEM specification activity.
United States
Great Lakes manufacturing corridors and Gulf Coast wind lease areas are driving demand for load-monitoring slewing systems. OSHA crane safety mandates now require replacement of non-certified swing bearings under updated load-rating traceability rules. Texas and Illinois construction fleet operators face compressed procurement timelines for standardized bearing sizes.
Japan
Industrial robotics OEMs in Osaka and Nagoya are specifying compact cross-roller configurations for six-axis arm joints in semiconductor handling equipment. METI industrial standards influence precision bearing qualification protocols for medical imaging gantries. The Kansai manufacturing zone concentrates demand for corrosion-resistant specifications in coastal applications.
India
Jawaharlal Nehru Port and Mundra Port expansion projects specify heavy-lift cranes with load-monitoring slewing systems. BIS certification requirements are tightening vendor qualification lists for infrastructure procurement. The Gujarat maritime corridor concentrates engineering-procurement contracting for port modernization.
Slewing Bearing Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive forging and heat-treatment capacity, compressing margins for merchant bearing specialists and regional distributors. Three archetypes dominate: European forging houses with offshore wind scale capabilities, Japanese precision specialists serving robotics OEMs, and diversified industrial conglomerates with aftermarket service networks. Competitive moves center on long-term availability contracts with embedded replacement scheduling, and backward integration into through-hardened raceway steel supply.
Among European forging houses, ThyssenKrupp Rothe Erde exemplifies the vertically integrated archetype with captive German capacity, while SKF Group anchors the aftermarket service network model with condition monitoring bundles. Schaeffler AG occupies a position within the integrated manufacturing tier, representing heat-treatment line investments that shorten lead times for crane manufacturers. These three entities collectively illustrate how supply-side concentration is reshaping procurement channels toward direct OEM contracting and away from traditional distribution.
| Leading Market Players |
|---|
| SKF Group |
| Schaeffler AG |
| ThyssenKrupp Rothe Erde |
| The Timken Company |
| NTN Corporation |
| JTEKT Corporation |
| Liebherr-International AG |
| Kaydon Corporation |
| IMO Group |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor carries through-hardened raceway steel from European electric arc furnaces to Jiangsu province forging houses, with container rates feeding directly into price differentiation between captive-heat-treatment suppliers and merchant bearing specialists serving crane OEMs.
Pricing Analysis
Volume-discount tiering separates premium certified bearings for offshore wind from standard construction-grade units and economy aftermarket replacements. Price differentiation hinges on EN 13852 functional safety certification and captive forging capacity for diameters above four meters. Cost compression in the standard tier intensifies as Chinese wind turbine OEMs negotiate direct procurement contracts, bypassing distributor markups. Construction fleet operators in the US Great Lakes corridor exhibit highest price sensitivity due to compressed OSHA-mandated refresh timelines, while Equinor and Ørsted accept premium positioning for 25-year design life specifications.
Supply Chain Analysis
Contract manufacturing concentration rests with ThyssenKrupp Rothe Erde, SKF Group, and Schaeffler AG holding captive heat-treatment and forging capacity across Germany, Sweden, and China. Raw material dependencies draw from through-hardened raceway steel, silicon nitride ceramic pressing capacity, and corrosion-resistant austenitic grades. Single-source vulnerability concentrates in four forging groups controlling rings above four-meter diameter for offshore wind. Distribution runs through direct OEM contracting for renewable energy, with aftermarket service networks covering construction fleet maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore wind scale-up to 8MW-plus turbines constitutes a high-growth disruption, with EU Green Deal domestic content requirements and OSHA crane safety mandates compressing supplier qualification timelines and reshaping procurement authority.
For Market Incumbents: Harden captive forging capacity in the Ruhr industrial belt and Yangtze River Delta against merchant specialist erosion. Secure EN 13852 and GB/T certification reciprocity before notified-body bottlenecks extend onboarding timelines. Defensive consolidation through backward integration into through-hardened raceway steel supply insulates against European electric arc furnace volatility. For New Entrants and Emerging Players: Pursue precision cross-roller configurations for Japanese and South Korean robotics OEMs, where semiconductor handling equipment specifications outpace incumbent capacity expansion. Target India's Jawaharlal Nehru Port and Mundra Port crane modernization as the most penetrable infrastructure geography. Anchor go-to-market through engineering-procurement-contracting relationships with port authority technical consultants. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core bearing divisions lacking offshore wind scale capabilities. Long-term viability centers on 15-year availability contracting with embedded remote monitoring and predictive maintenance platforms. Watch ceramic hybrid rolling element adoption rates in Vestas and Siemens Gamesa pitch systems as inflection signal for material science value capture shift.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Capacity Expansion | ThyssenKrupp Rothe Erde's German forging corridors shorten lead times for crane OEMs. |
| Ceramic Hybrid Rolling Element Integration | Silicon nitride balls collapse lubrication intervals from six months to two years in wind turbines. |
| Long-Term Availability Contracting | Ørsted and Equinor negotiate 15-year agreements with embedded replacement scheduling. |
| Condition Monitoring Bundle Development | SKF Group anchors European aftermarket coverage with vibration sensor platforms. |
| Corrosion-Resistant Specification Penetration | Jiangsu province offshore installations drive stainless steel adoption in salt-laden environments. |
Methodological Framework
Operator-level perspectives from wind turbine OEM procurement directors, crane fleet maintenance managers, port authority engineering consultants, and forging house technical directors anchored the qualitative base. Secondary validation drew from customs trade data for through-hardened steel flows, SEC filings of listed bearing manufacturers, EU machinery directive update notices, and OSHA crane safety standard revisions. Bottom-up demand modeling across product architectures triangulated with top-down macro industrial capacity assessments.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, application context, end-user contracting structure, and material specification grade. CAGRs derived from unit shipment trajectories weighted by average selling price evolution, incorporating offshore wind turbine installation pipelines, crane fleet age demographics, and port infrastructure capital expenditure announcements as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in scrap metal pricing, European energy input costs, or container freight rates would shift the trajectory. Forecasts reflect assumptions on certification reciprocity timelines and ceramic pressing capacity expansion. Quarterly review of offshore wind lease award announcements, crane OEM order backlogs, and forging group capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Electro-Pneumatic Systems Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Asia-Pacific Fans and Blowers Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Global Temperature Control Units (TCU) Market
Industrial Equipment
Spherical Roller Bearings Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Washdown Scales Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Europe Fusion Splicer Market
Industrial Equipment
Snowrator Market