
 Europe Electric Car Market | 2026-2036
Europe Electric Car Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Car Market Intelligence
The 800-volt battery architecture is unwinding the market's previous reliance on slower charging standards. The Volkswagen Group, which includes Audi and Skoda, leverages its modular electric drive matrix (MEB) platform to scale production efficiently across multiple vehicle segments. Kia differentiates with distinctive design language and competitive warranty offerings. BMW sustains its premium market position through a focus on driving dynamics and luxury interior appointments.
An electric car is a road vehicle propelled by one or more electric motors, using electrical energy stored in a rechargeable battery pack. These vehicles are designed to produce zero tailpipe emissions, a key requirement for meeting urban air quality targets across European cities. Battery Electric Vehicles dominate new sales, while Plug-in Hybrid Electric Vehicles serve as a transitional technology for many consumers. Sales to Personal Consumers form the largest base, but the Fleet Operators segment represents the fastest-growing opportunity.
The market operates under the EU Green Deal framework, which mandates progressively lower CO2 emission fleet averages for automakers. Regulations like the Corporate Sustainability Reporting Directive (CSRD) also indirectly influence corporate fleet purchases by requiring large companies to report on their environmental impact. Automakers must now navigate the dual challenge of securing battery raw material supply chains while simultaneously expanding public charging infrastructure access.
Market Dynamics
The European electric car market's trajectory is defined by the dual pressures of stringent EU Green Deal emission mandates and the strategic imperative to secure battery raw material supply chains, which together dictate automaker investment priorities and production strategies.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal's progressively stricter CO2 emission standards for new vehicles directly compel automakers to increase the share of zero-emission vehicles in their sales mix to avoid substantial penalties.
- Technology Advancement:The adoption of 800-volt battery architectures significantly reduces charging times, addressing a key consumer concern and enhancing the practicality of long-distance travel with an electric vehicle.
- Consumer Incentives:Substantial government subsidies, tax credits, and non-monetary perks offered in key markets, particularly Germany and the Nordic countries, lower the total cost of ownership and stimulate demand from personal consumers.
Market Restraints
- Raw Material Volatility:Price fluctuations and supply-chain vulnerabilities for critical battery materials like lithium, cobalt, and nickel create cost uncertainty for manufacturers and can delay production schedules.
- Charging Infrastructure Gaps:The uneven distribution and availability of public fast-charging stations, especially in Southern and Eastern Europe, remains a significant barrier to widespread adoption for many potential buyers.
- Grid Capacity Limitations:Localized electricity grid constraints in certain residential areas and commercial zones can limit the speed and scale of charging infrastructure deployment, posing a structural bottleneck.
Strategic Opportunities
- Light Commercial Vehicle Electrification:The transition of urban delivery fleets to electric light commercial vehicles (e-LCVs) offers a major growth avenue, driven by corporate sustainability goals and the expansion of low-emission zones.
- Vehicle-to-Grid (V2G) Services:The development of bidirectional charging technology presents an opportunity for EV owners to sell stored energy back to the grid, creating a new value stream and supporting grid stability.
- Eastern Europe Expansion:Markets in Eastern Europe exhibit lower initial EV penetration, presenting significant white-space opportunity as charging infrastructure improves and more affordable models become available.
Industry Challenges
- Skilled Labor Shortages:A deficit of technicians and engineers with expertise in high-voltage battery systems, power electronics, and vehicle software presents a key operational challenge for both manufacturing and after-sales service.
- Manufacturing Transition Costs:Automakers face immense capital expenditure requirements to retool existing factories or build new gigafactories for dedicated EV and battery production, pressuring financial resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Car Market |
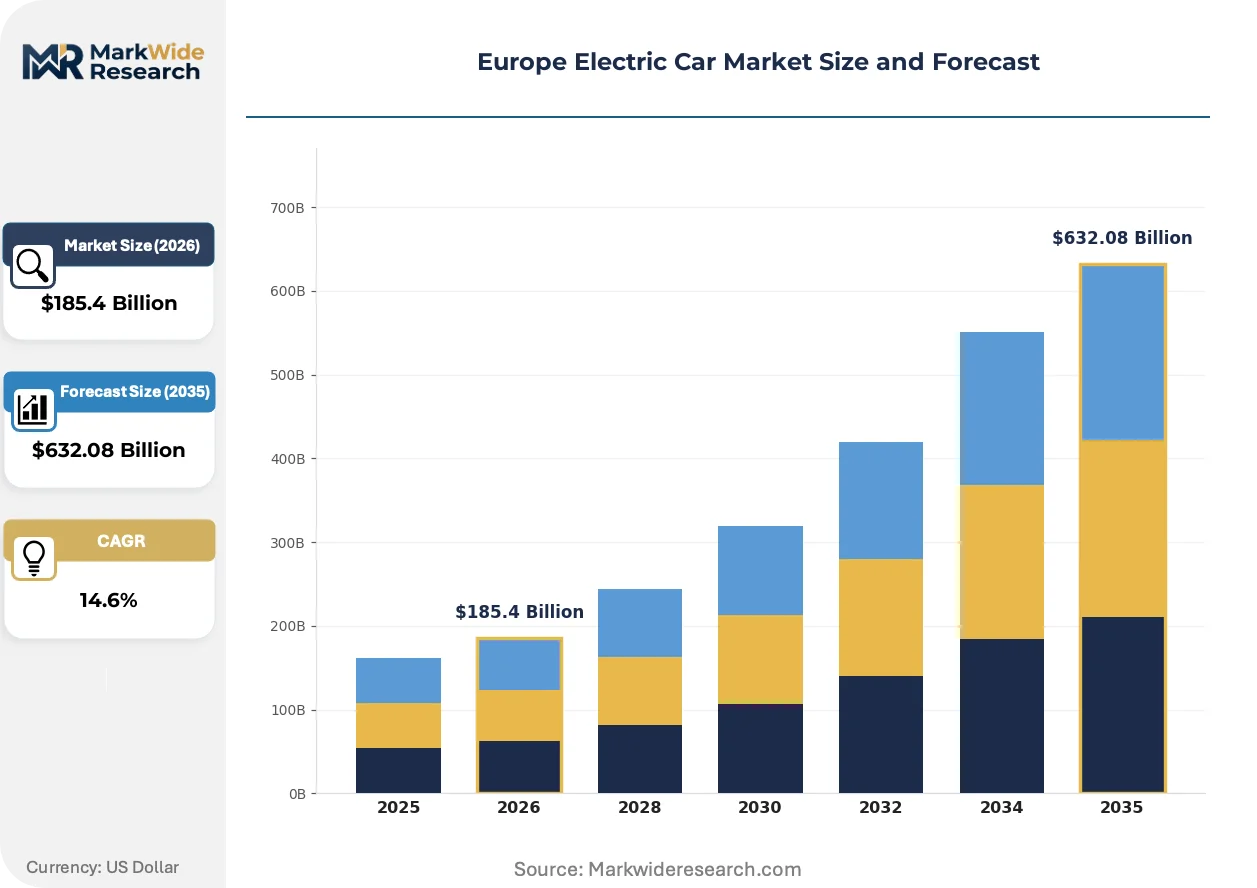
| Market Size in 2026 | $185.4 Billion |
| Market Size in 2035 | $632.08 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle, Hybrid Electric Vehicle Battery Technology: Lithium-ion, Solid-state, Nickel-metal Hydride, Lead Acid, Lithium Polymer Charging Infrastructure: Home Chargers, Public Fast Chargers, Workplace Chargers, Destination Chargers, Ultra-fast Chargers End User Segment: Personal Consumers, Fleet Operators, Car Rental Services, Government Agencies |
| Companies Covered | Volkswagen, Tesla, BMW, Audi, Skoda, Renault, Kia, Mercedes-Benz, Volvo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Car Market Strategic Shifts & Innovations
The competitive landscape is shifting from traditional automotive hardware engineering to a new battleground centered on battery technology, software-defined vehicle architecture, and charging ecosystem control. This transition is reshaping vehicle development cycles and altering the fundamental definition of automotive value for European consumers.
Silicon carbide (SiC) inverters are advanced power electronics that manage the flow of energy between the battery and the electric motor with higher efficiency. The technology is seeing rapid uptake in premium and long-range EV models where performance is a key differentiator. This innovation is miniaturizing the overall powertrain package, freeing up valuable space for designers and engineers to use for either increased passenger comfort or larger battery packs.
The EU's Corporate Sustainability Reporting Directive (CSRD) is forcing large companies to provide detailed disclosures on their environmental impact, including fleet emissions. This regulatory pressure directly influences corporate procurement, making the environmental credentials of a vehicle fleet a matter of public record and investor scrutiny. Consequently, the Fleet Operators segment is accelerating its switch to all-electric vehicles to align with these stringent ESG reporting mandates.
A clear behavioral change is the move from direct vehicle ownership toward flexible, subscription-based mobility services. These all-inclusive models, which bundle insurance, maintenance, and charging, are disrupting the traditional dealership sales channel, especially for younger demographics. This trend is most prominent among urban dwellers in major European hubs like Paris and Oslo, who value access and convenience over long-term asset commitment.
Europe Electric Car Market Segmentation
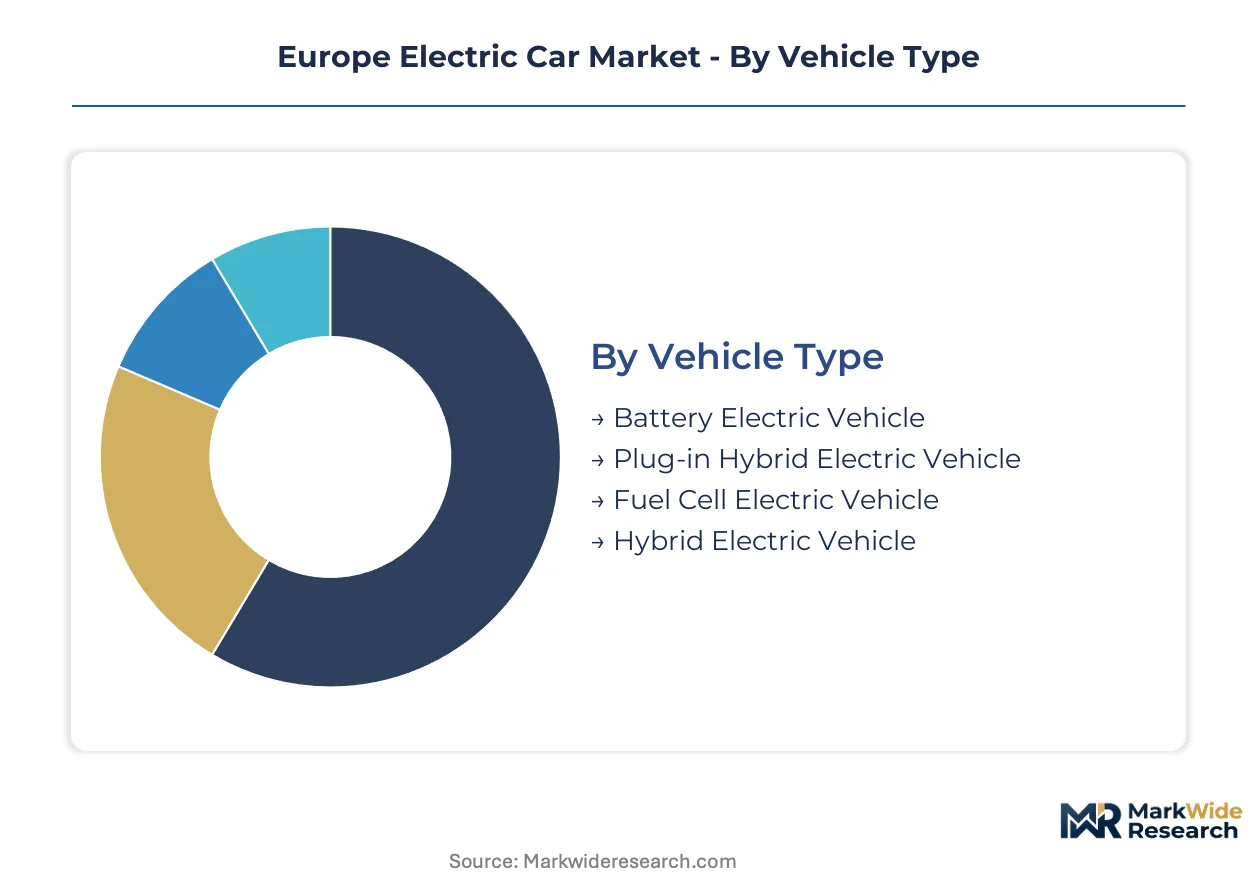
Understanding the Europe Electric Car Market through detailed segmentation reveals diverse technological and consumer preferences. This analysis provides insights into specific vehicle types, battery innovations, charging solutions, and end-user demands. Identifying these market components allows stakeholders to tailor strategies for growth.
Vehicle Type:
The market for electric vehicles in Europe shows varied adoption patterns, with certain vehicle types dominating domestic sales in key regions.
- Battery Electric Vehicle:These vehicles operate solely on electric power, producing zero tailpipe emissions. Demand is strong in Germany and Nordic countries, driven by consumer incentives and urban air quality targets.
- Plug-in Hybrid Electric Vehicle:PHEVs combine an internal combustion engine with an electric motor, offering limited electric-only range. This transitional technology serves a broad consumer base across Southern and Eastern Europe.
- Fuel Cell Electric Vehicle:FCEVs generate electricity from hydrogen, emitting only water vapor. Adoption remains niche, supported by public sector initiatives in Germany.
- Hybrid Electric Vehicle:HEVs use both gasoline and electric power but cannot be externally charged. These vehicles maintain a presence in cost-sensitive markets for efficiency.
Battery Electric Vehicles hold the largest share; momentum sits with Plug-in Hybrid Electric Vehicles as a bridge technology.
Battery Technology:
The maturity of various battery technologies directly impacts their deployment across different electric vehicle segments, influencing performance and cost.
- Lithium-ion:This technology forms the backbone of modern electric vehicles, offering high energy density and cycle life. Widespread adoption is driven by continuous improvements in cost and performance across Europe.
- Solid-state:Solid-state batteries represent the next generation, promising higher energy density, faster charging, and enhanced safety. Manufacturers are investing heavily for future premium and long-range models.
- Nickel-metal Hydride:NiMH batteries are a mature technology found in older hybrid electric vehicles. Lower energy density limits contemporary EV use.
- Lead Acid:Lead-acid batteries serve as auxiliary power units for 12V systems in EVs. Low energy density precludes their use as main traction batteries.
- Lithium Polymer:Lithium polymer batteries offer flexible form factors and high energy density, utilized in performance EV models. Cost and thermal management are higher.
Lithium-ion technology currently dominates the market, while solid-state batteries are gaining traction as a future standard.
Charging Infrastructure:
The diverse applications of charging infrastructure cater to varying user needs, from daily commuting to long-distance travel, influencing EV adoption.
- Public Fast Chargers:These stations provide rapid energy replenishment in public spaces, crucial for longer journeys and urban convenience. Uneven distribution, especially in Southern and Eastern Europe, remains a market restraint.
- Ultra-fast Chargers:Offering significantly higher charging speeds, ultra-fast units leverage 800-volt architectures to drastically reduce charging times. Deployment is expanding along major European highways, addressing range anxiety.
- Home Chargers:Residential AC Level 2 chargers provide convenient overnight charging for personal consumers. This forms the primary charging method for most EV owners.
- Workplace Chargers:Installed at corporate campuses, workplace chargers offer employees convenient charging. These facilities support corporate sustainability goals.
- Destination Chargers:Found at hotels and shopping centers, destination chargers encourage EV usage by providing options where vehicles are parked longer.
Home charging remains the most common method, with public fast and ultra-fast charging expanding most quickly to support broader adoption.
End User Segment:
The volume of electric vehicle sales varies significantly across different end-user segments, each driven by distinct purchasing motivations.
- Personal Consumers:Individual buyers constitute the largest base for electric car sales, driven by environmental consciousness, lower running costs, and government incentives. Demand is strong in Nordic countries and Germany.
- Fleet Operators:Businesses and organizations managing vehicle fleets represent a rapidly expanding opportunity, aligning with corporate sustainability goals and CSRD reporting mandates. This segment is accelerating its transition to all-electric vehicles.
- Car Rental Services:Rental companies incorporate electric vehicles to meet customer preferences and urban low-emission zone compliance. This segment offers short-term EV access.
- Government Agencies:Public sector bodies procure electric vehicles for official fleets, demonstrating commitment to environmental targets. Purchases often include specific tenders.
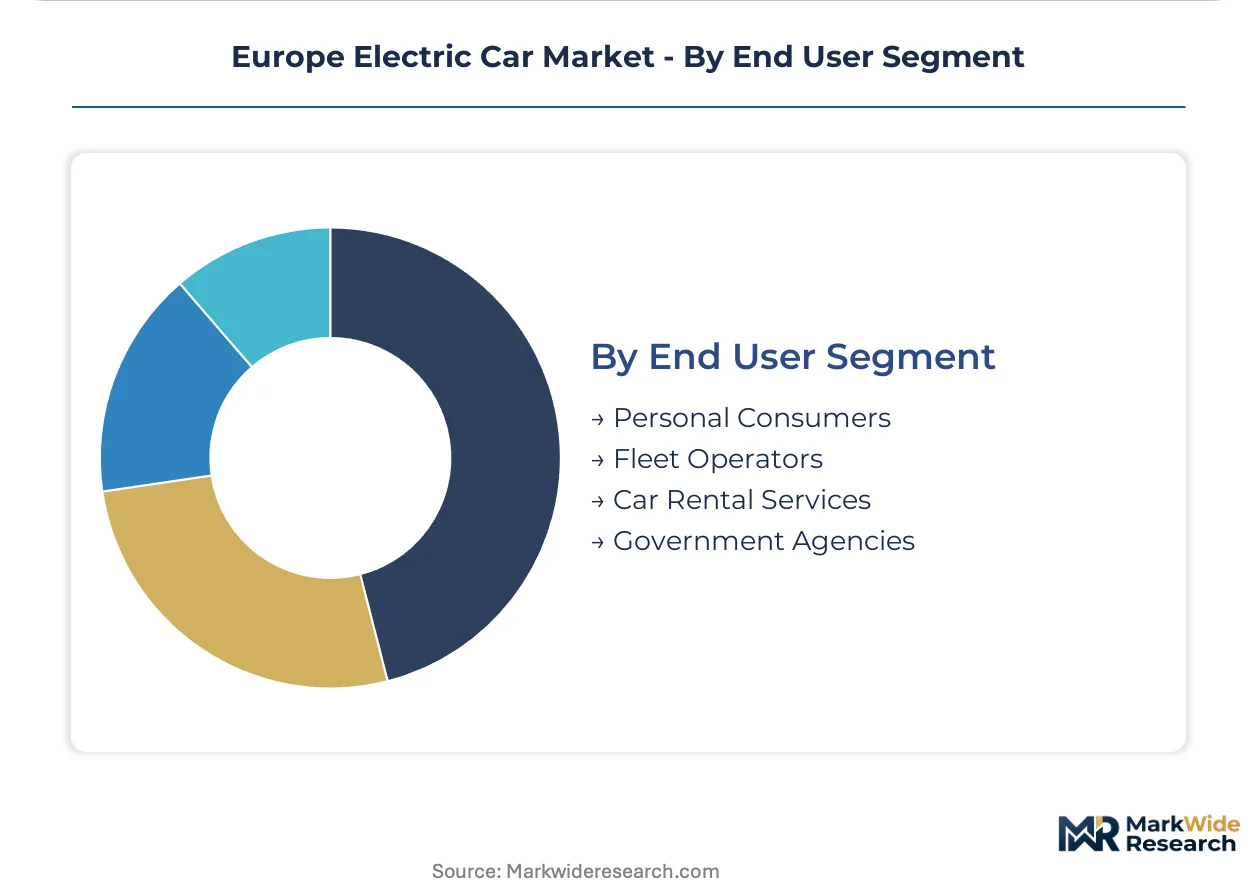
Personal Consumers represent the largest volume of sales, while Fleet Operators exhibit the steepest expansion trajectory due to regulatory pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European electric car market presents a complex interplay of import and export dynamics, with strong domestic production capabilities increasingly serving regional demand while also competing with international entrants. This regional market demonstrates varied adoption rates and policy landscapes across its member states, influencing overall growth trajectories and investment priorities. Strategic investments in local manufacturing and charging infrastructure are critical for sustaining this expansion.
Germany
German demand for electric vehicles is robust, driven by strong consumer incentives and a national focus on reducing urban air pollution. The German government's environmental bonus scheme significantly lowers the purchase price for new electric cars. Automakers in the Stuttgart and Munich regions are heavily investing in EV production and battery research, fostering an advanced manufacturing ecosystem.
Norway
Norway maintains the highest electric vehicle penetration rates in Europe, primarily due to comprehensive tax exemptions and strong public charging infrastructure support. Policies like the VAT exemption on EV purchases make electric cars highly competitive with traditional internal combustion engine vehicles. Cities like Oslo and Bergen demonstrate high EV density, supported by extensive urban charging networks.
France
French consumer demand is stimulated by generous government subsidies, including the "Bonus Écologique" and a scrappage scheme for older, more polluting vehicles. Strict urban air quality targets in major metropolitan areas like Paris further encourage EV adoption. The automotive cluster around Île-de-France and Lyon is a hub for EV design and component manufacturing.
Netherlands
Dutch fleet operators and personal consumers are rapidly transitioning to electric vehicles, influenced by favorable fiscal incentives and strong corporate sustainability goals. The Netherlands offers various tax benefits for EV ownership and company car schemes, promoting widespread uptake. Amsterdam and Eindhoven are leading cities in smart charging solutions and V2G technology deployment.
Sweden
Swedish electric car sales benefit from substantial consumer incentives, including a climate bonus for zero-emission vehicles, and a national commitment to renewable energy. The focus on environmental sustainability permeates both public policy and consumer behavior. Gothenburg, home to major automotive players, is a significant center for electric vehicle research and development.
Europe Electric Car Market Key Industry Players
Listed leaders compete with private specialists across vehicle segments and battery technology, shaping the European electric car market's competitive structure. The market exhibits a mix of established automotive giants and agile new entrants, each vying for market share. Key strategic archetypes include traditional automakers transitioning to electric, pure-play EV manufacturers, and component suppliers. Automakers focus on capacity expansion and strategic partnerships for battery raw material supply to secure their positions.
Within the established automotive manufacturer archetype, Volkswagen and BMW exemplify companies leveraging existing production capabilities and brand loyalty to introduce extensive EV lineups. Kia differentiates its offerings with distinctive design language and competitive warranty programs, appealing to a broad consumer base. These companies collectively shape the market through product diversification and continuous technological innovation, addressing varied consumer preferences across Europe.
| Leading Market Players |
|---|
| Volkswagen |
| Tesla |
| BMW |
| Audi |
| Skoda |
| Renault |
| Kia |
| Mercedes-Benz |
| Volvo |
| Others |
Cost & Logistics Intelligence
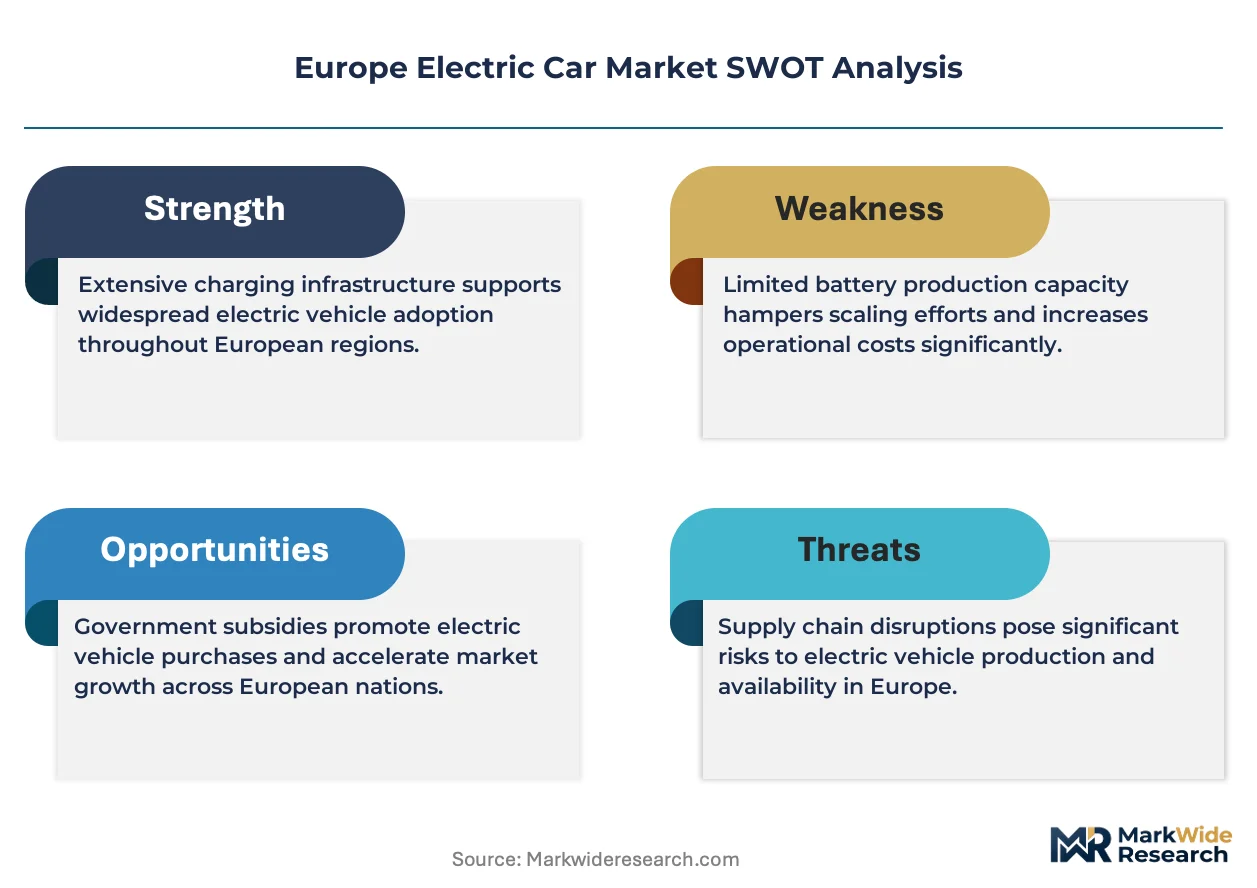
Solid-state battery development, a key substitution dynamic, simultaneously reshapes supply geography towards Asian expertise and pricing economics by promising higher energy density at potentially lower long-term costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing in the Europe Electric Car Market. This model incorporates differentiation based on volume scale and specific battery chemistry. Cost compression in battery raw materials is intensifying due to commodity price volatility, driving pricing pressure across the value chain. Fleet Operators demonstrate high price sensitivity when evaluating total cost of ownership, while premium Personal Consumers prioritize performance over initial vehicle cost.
Supply Chain Analysis
Long lead times for specialized components challenge European electric car manufacturers. Geographic supply concentration for critical battery materials and advanced cells primarily resides in China, South Korea, and Germany. The market heavily draws from raw materials like lithium, cobalt, and nickel. Single-source vulnerability for high-performance battery cells represents a significant structural risk. Distribution runs through a hybrid model, with direct-to-consumer channels expanding alongside established dealership networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Electric Car Market presents a fragmentation opportunity, as the shift toward subscription-based mobility services creates niches for specialized vehicle offerings and ownership models.
For Market Incumbents: Secure long-term battery raw material supply through strategic partnerships with mining companies, mitigating commodity price volatility. Standardize EV platforms to achieve economies of scale across diverse models and brands, countering the threat from agile pure-play EV manufacturers. Invest in vertical integration into battery cell production to control costs and enhance performance. This strategy defends against new entrants leveraging advanced battery technology.
For New Entrants and Emerging Players: Differentiate on charging ecosystem integration by offering bundled home charging solutions and preferential public network access. Target the underpenetrated Eastern European markets with more affordable models and localized charging partnerships. Focus on light commercial vehicle electrification for urban delivery fleets, addressing corporate sustainability goals. Develop V2G-enabled vehicles with flexible lease options, appealing to energy-conscious fleet operators and urban dwellers.
For Investors and Strategic Acquirers: The market sits at a rapid expansion phase that favors technology-agnostic component suppliers and charging infrastructure developers. Long-term viability is sustained by stringent EU Green Deal mandates and evolving consumer preferences for zero-emission transport. Investors should target specialized software firms enhancing vehicle-to-grid capabilities or battery recycling startups. The signal to watch for inflection is the accelerated deployment of ultra-fast charging infrastructure in Southern and Eastern Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces manufacturing complexity for diverse EV models across the Volkswagen Group. |
| Battery Supply Agreement | Secures critical raw materials like lithium and cobalt for future EV production volumes. |
| Software-Defined Vehicle Investment | Enhances over-the-air update capabilities and enables new digital services for BMW owners. |
| Charging Infrastructure Partnership | Expands public fast-charging access, addressing range anxiety for European consumers. |
| Light Commercial Vehicle Electrification | Aligns urban delivery fleets with low-emission zones and corporate sustainability targets. |
Research Approach
The analysis maps vehicle types, battery technologies, and end-user segments, each validated through primary interviews with automotive OEM platform engineers and fleet procurement managers. These insights were cross-referenced with secondary data from EU Commission reports, national transport agency statistics, and industry association publications. Bottom-up data aggregation and top-down market sizing ensured comprehensive coverage, triangulating findings across multiple sources.
Market volume and value outputs underwent rigorous consistency checks against external benchmarks, including national EV registration databases and public charging infrastructure deployment statistics. The analytical framework integrated historical trends with projected market penetration rates to derive compound annual growth rates across the analysis window. Segmentation dimensions modeled included vehicle class, propulsion architecture, charging speed, and regional adoption patterns. Key forecast inputs comprised battery cost trajectories and regulatory incentive levels.
Forecasts assume regulatory continuity in key European Union directives, such as the EU Green Deal and CSRD; material policy shifts would require re-modeling. The projections reflect inherent assumptions about technological advancements, though raw material price volatility and grid capacity limitations represent specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
E-SUV Market
Electric Vehicles
Electric Utility Vehicle Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Pickup Truck Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Lithium Battery Electric Scooters Market