
 Europe Hybrid Electric Vehicle Battery Market | 2026-2036
Europe Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hybrid Electric Vehicle Battery Market Insights
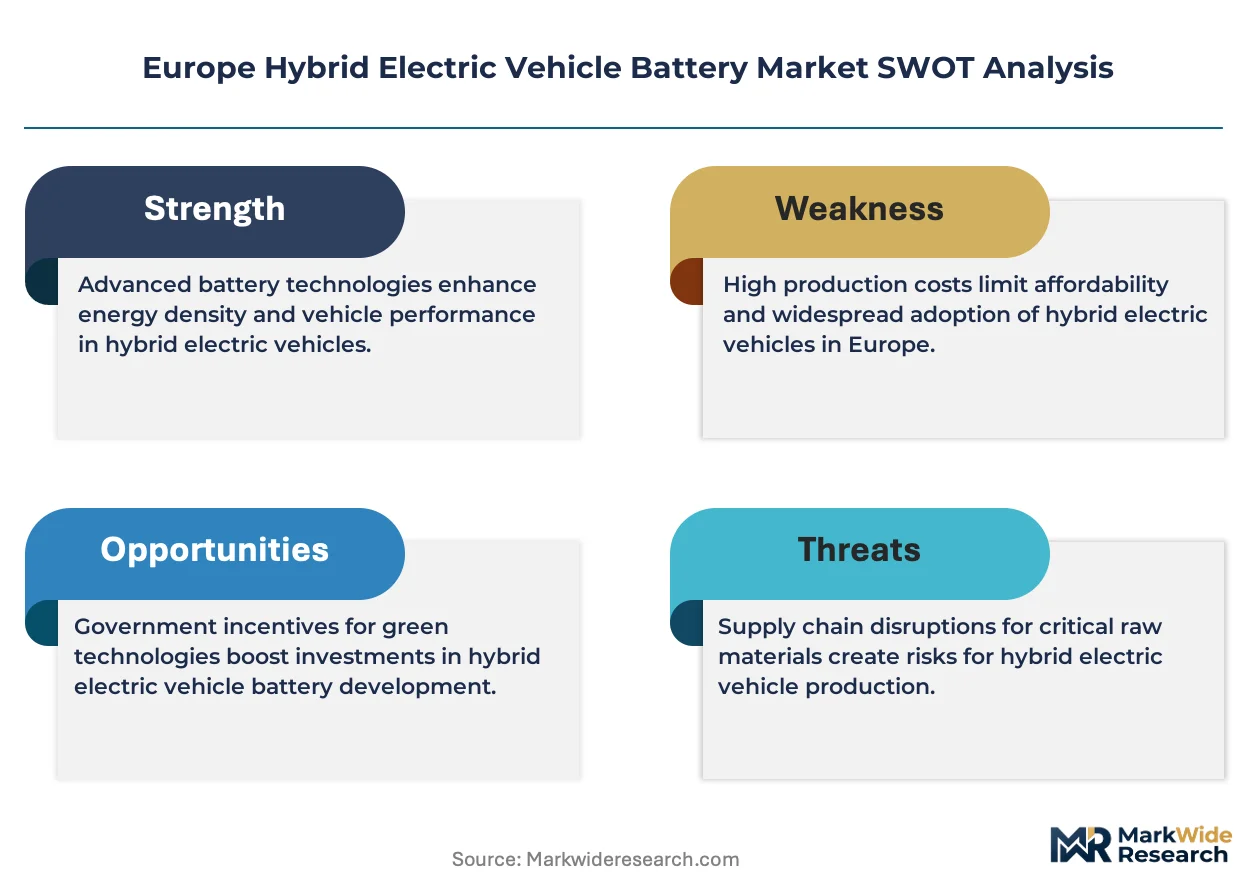
Silicon-dominant anode formulations is broadening energy density economics for European hybrid platforms. Northvolt AB anchors its position through in-house cathode production and regional supply security. Samsung SDI Co., Ltd. competes via high-nickel cell architectures optimized for German OEM thermal management protocols. CATL Europe extends its footprint through dedicated module lines serving French and Swedish vehicle plants.
Europe Hybrid Electric Vehicle Battery denotes electrochemical storage systems engineered for dual-powertrain vehicles, typically delivering 1–5 kWh usable capacity at 48–400 V nominal with liquid-cooled thermal regulation, enabling torque-fill and regenerative energy recovery during combustion-off operation. Lithium-ion cells occupy the dominant share due to gravimetric efficiency, while nickel-metal hydride retains cost advantages in mild-hybrid duty cycles where depth-of-discharge demands remain shallow. Passenger vehicles generate the largest absolute volume, though commercial vehicle applications present concentrated margin pools as logistics operators electrify last-mile and urban distribution fleets.
EU Green Deal emission targets, REACH chemical compliance for cell materials, and ECHA battery passport requirements collectively mandate recycled-content quotas and full lifecycle traceability, forcing pack producers to reconfigure supply chains and chemistries. CE marking under the EU Battery Regulation establishes mandatory performance and sustainability thresholds that determine market access. Stakeholders must monitor how delegated acts on carbon intensity thresholds reshape sourcing decisions for active materials and separator films.
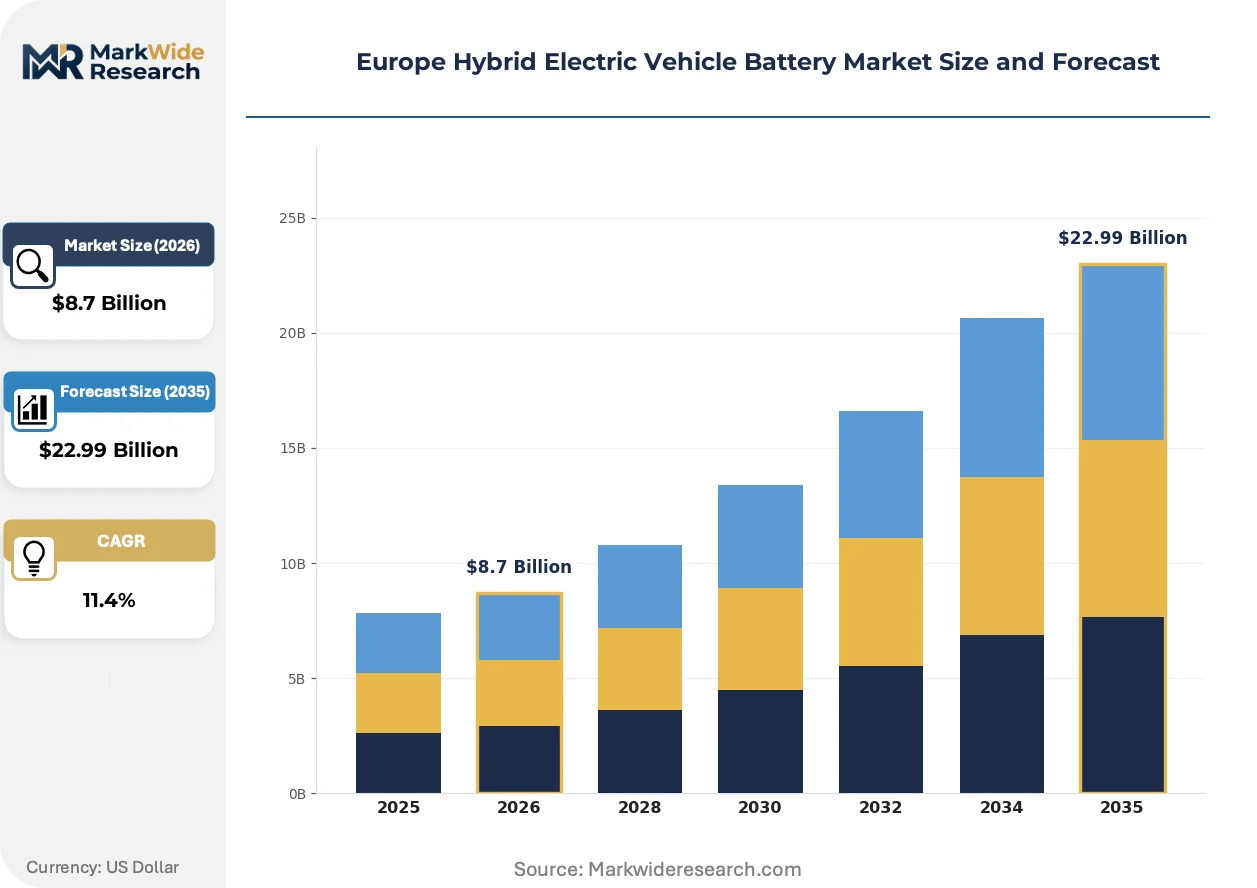
Market Dynamics
EU Green Deal emission mandates are compressing fleet electrification timelines, forcing OEMs to secure nickel-metal hydride and lithium-ion capacity for mild-hybrid architectures before 2030 compliance deadlines.
Growth Catalysts
- EU Green Deal fleet mandates:Binding CO2 reduction targets for passenger cars and vans are accelerating OEM procurement of 48V hybrid battery systems.
- Silicon-dominant anode chemistry:Gravimetric efficiency gains are expanding the addressable duty cycle for hybrid platforms previously limited by energy density constraints.
- German industrial corridor concentration:Cell assembly and pack integration demand clusters between Stuttgart and Dresden, creating localized supplier ecosystems.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress margin predictability for cell producers serving cost-sensitive mild-hybrid segments.
- Active material supply concentration:Cathode precursor refining capacity concentrates in East Asia, exposing European pack assemblers to trans-shipment risk.
- REACH chemical compliance friction:ECHA substance restrictions on nickel and cobalt compounds are forcing chemistry reformulation timelines that lag product development cycles.
Strategic Opportunities
- Poland and Hungary cell manufacturing:Greenfield gigafactory sites offer tariff-advantaged supply positions for French and Swedish vehicle assembly plants.
- Commercial vehicle last-mile electrification:Urban distribution fleet operators present concentrated margin pools for high-cycle-life nickel-metal hydride packs.
- EU Battery Regulation recycled-content quotas:Delegated acts on minimum recovered material thresholds are creating first-mover advantages for closed-loop recyclers.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and thermal management expertise pools remain shallow relative to projected capacity expansion needs.
- CE marking certification timelines:EU Battery Regulation performance and sustainability threshold documentation is extending product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hybrid Electric Vehicle Battery Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-Metal Hydride, Lead Acid, Solid State End User: OEMs, Aftermarket Providers, Commercial Fleet, Individual Consumers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses Charging Method: Level 1 Charging, Level 2 Charging, Fast Charging, Regenerative Charging |
| Companies Covered | LG Energy Solution, Samsung SDI Co., Ltd., Panasonic Holdings Corporation, CATL Europe, Northvolt AB, BYD Europe B.V., SK Innovation Co., Ltd., BMZ Germany GmbH, Hoppecke Batterien GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hybrid Electric Vehicle Battery Market Trends and Innovations
Solid-state electrolyte development is converging with hybrid duty-cycle requirements, compressing the performance gap between conventional lithium-ion and next-generation architectures. Three forces are reshaping competitive positioning: materials science advances, delegated regulatory acts, and fleet procurement centralization.
Solid-state ceramic electrolyte formulations are converging with silicon-dominant anode structures to enable 400V hybrid architectures with enhanced thermal stability. German OEM thermal management protocols are adopting these cell designs for next-generation mild-hybrid platforms. The technology is converging with existing liquid-cooled pack architectures to reduce retrofit complexity and preserve manufacturing capital.
Delegated acts under the EU Battery Regulation are mandating carbon intensity thresholds for active material sourcing that reshape separator film and cathode supply decisions. ECHA battery passport requirements are forcing full lifecycle traceability infrastructure investments across the value chain. Pack producers serving Swedish and French vehicle plants are responding by qualifying regional precursor suppliers ahead of 2027 enforcement windows.
Fleet procurement centralization among logistics operators is consolidating specification-setting power for last-mile commercial vehicle battery contracts. Traditional distributor channels serving independent garages are losing share to direct OEM-fleet agreements with embedded service provisions. Urban distribution electrification programs in Germany and the Netherlands exhibit the most pronounced procurement consolidation.
Europe Hybrid Electric Vehicle Battery Market Segmentation
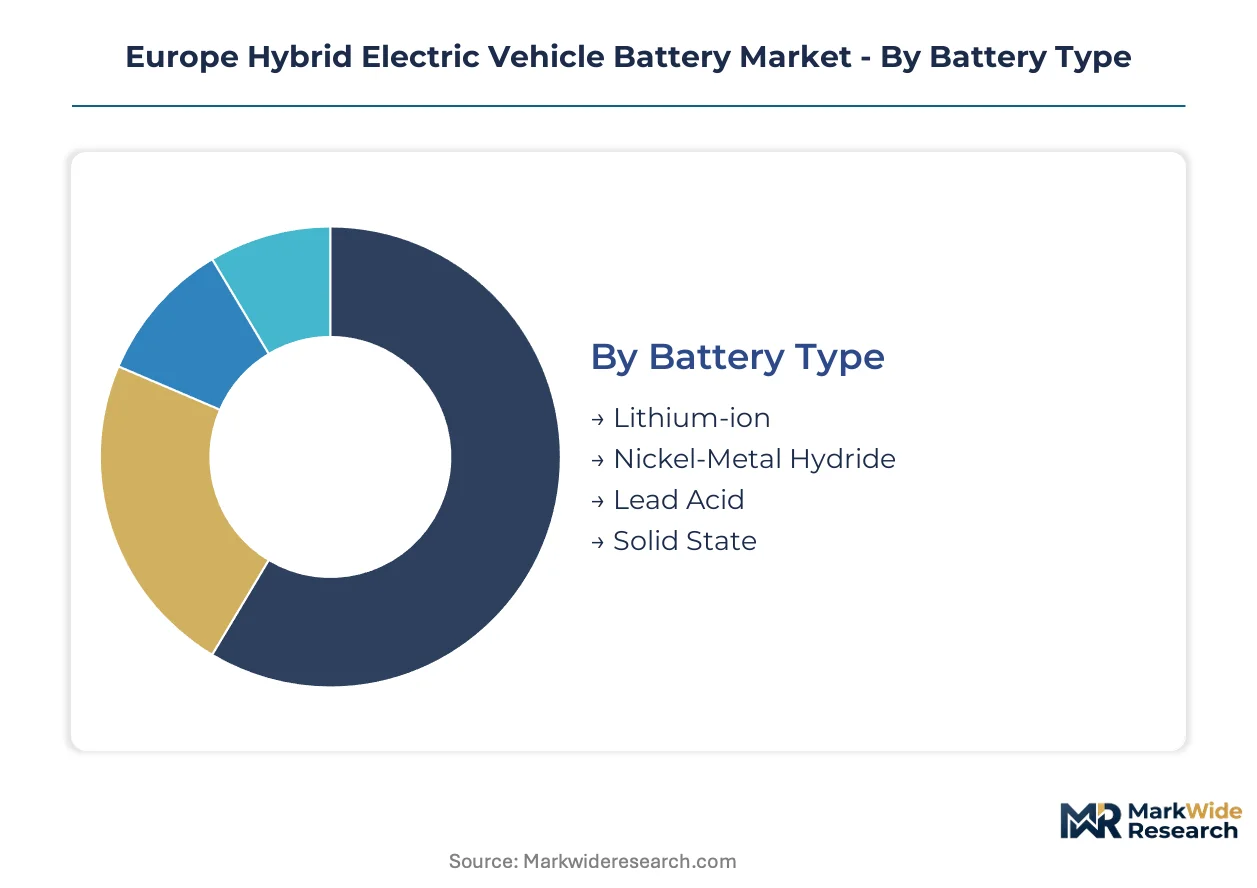
Segmentation in the Europe Hybrid Electric Vehicle Battery Market reveals how technical specifications, procurement channels, and duty-cycle demands fragment supply requirements. OEMs, fleet operators, and aftermarket channels each impose distinct performance thresholds and volume profiles that reshape pack design priorities across the value chain.
Battery Type:
Chemistry selection hinges on energy density requirements versus cost tolerance and thermal management complexity.
- Lithium-ion:Delivers 150-250 Wh/kg gravimetric density with liquid-cooled thermal regulation, enabling 48V to 400V architectures. German OEM procurement concentrates on high-nickel NMC variants for premium mild-hybrid platforms serving Stuttgart and Munich assembly plants.
- Nickel-Metal Hydride:Offers proven cycle stability above 2,000 shallow-depth cycles at lower pack cost. French and Swedish vehicle plants specify NiMH for fleet-focused mild-hybrid models where procurement prioritizes total cost of ownership over gravimetric efficiency.
- Lead Acid:Retains position in 12V auxiliary power and starter-generator applications with minimal electrification duty.
- Solid State:Ceramic electrolyte formulations are advancing through German OEM validation protocols for next-generation thermal stability requirements.
Lithium-ion leads volumes today; solid-state is gaining share fastest.
End User:
Procurement authority determines specification control, contract duration, and service integration expectations.
- OEMs:Direct cell and module sourcing with embedded thermal management system integration. German industrial corridor demand clusters around multi-year supply agreements with performance guarantees tied to EU Battery Regulation compliance milestones.
- Commercial Fleet:Centralized procurement for urban distribution electrification programs in the Netherlands and Germany. Fleet operators negotiate direct OEM agreements with battery-as-a-service provisions, bypassing traditional aftermarket channels.
- Aftermarket Providers:Serve independent garages and legacy vehicle refurbishment with replacement pack distribution.
- Individual Consumers:Minimal direct procurement; replacement demand routes through authorized service networks.
OEMs dominate contract value today; commercial fleet procurement is expanding most quickly.
Application:
Duty-cycle intensity and packaging constraints differentiate power and energy requirements across vehicle classes.
- Passenger Vehicles:Mild-hybrid architectures at 48V and 400V dominate absolute unit demand. French and Swedish assembly plants specify compact module formats for C-segment and D-segment integration with regenerative recovery optimization.
- Commercial Vehicles:Last-mile urban distribution fleets in Germany impose high-cycle-life requirements with opportunity charging compatibility. Logistics operators specify nickel-metal hydride for depot-based charging patterns with predictable route profiles.
- Two-Wheelers:Emerging electrification in Southern European urban mobility programs drives compact pack demand.
- Buses:Municipal procurement in the Netherlands and Belgium specifies high-capacity hybrid systems for stop-start urban duty cycles.
Passenger vehicles anchor installed base today; commercial vehicle applications show the steepest expansion trajectory.
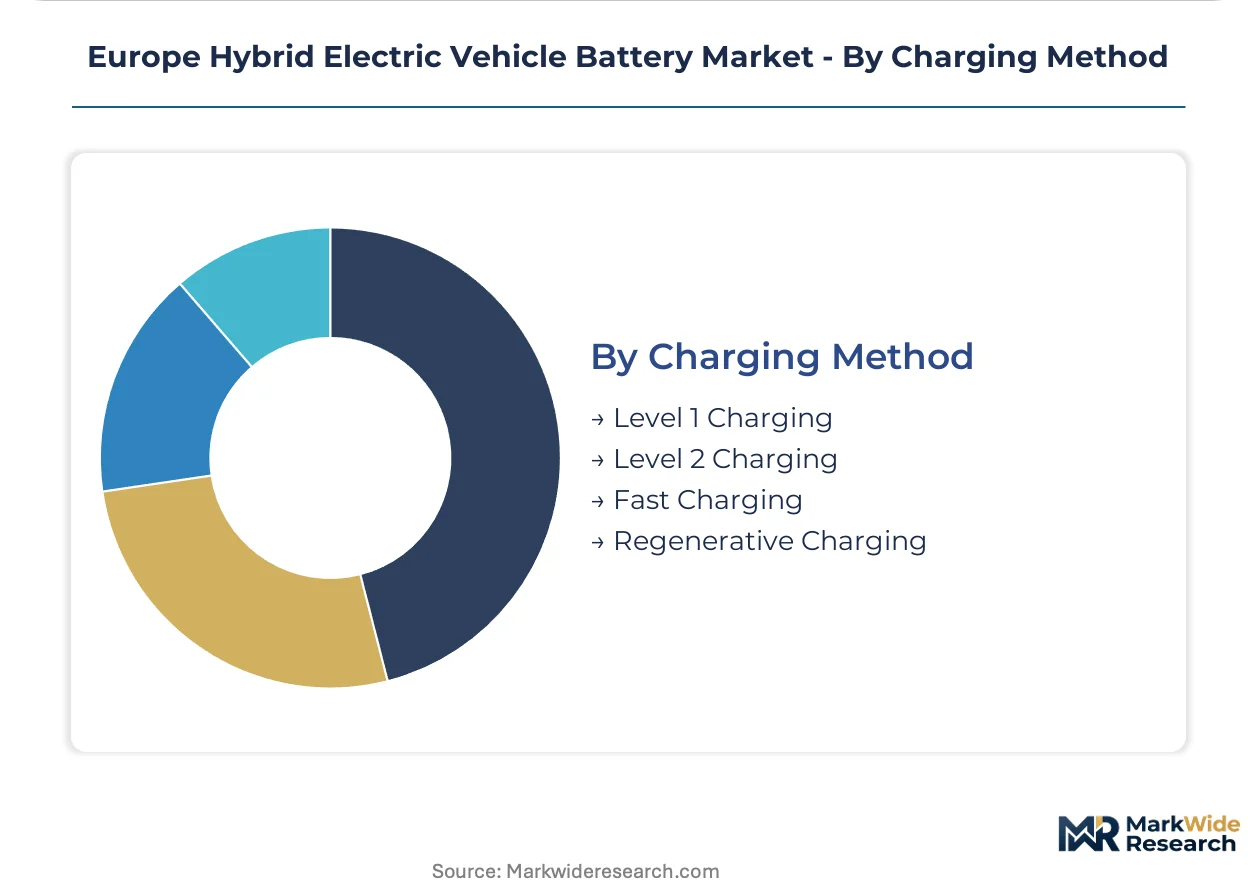
Charging Method:
Infrastructure availability and dwell-time economics determine power acceptance rates and thermal management specifications.
- Regenerative Charging:Captures kinetic energy during deceleration without external infrastructure dependency. German OEM thermal management protocols optimize for frequent 10-50 kW charge pulses during combustion-off operation in urban traffic.
- Level 2 Charging:3.7-22 kW AC supply enables depot and workplace replenishment for plug-in hybrid architectures.
- Level 1 Charging:Standard household socket supply serves residential overnight replenishment for low-range plug-in variants.
- Fast Charging:DC supply above 50 kW remains limited in hybrid applications due to pack size constraints and thermal management cost trade-offs.
Regenerative charging dominates hybrid-specific duty cycles; Level 2 infrastructure is climbing the fastest as plug-in hybrid penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-Dresden industrial corridor anchors European demand for hybrid electric vehicle battery systems. This concentration reflects German OEM procurement patterns and the clustering of cell assembly facilities serving premium mild-hybrid platforms. Five national markets within Europe exhibit distinct demand profiles shaped by local fleet electrification mandates and industrial policy.
Germany
Stuttgart-based OEMs drive procurement of 48V and 400V hybrid battery systems for premium passenger vehicle lines. The EU Green Deal fleet mandates compress supplier qualification timelines for nickel-metal hydride and lithium-ion chemistries. Dresden hosts expanding cell assembly operations supplying module integration plants across Baden-Württemberg and Bavaria.
Sweden
Volvo Car's electrification roadmap sustains demand for high-nickel lithium-ion cells in Gothenburg manufacturing operations. ECHA battery passport requirements are forcing full lifecycle traceability investments across Swedish pack producers. Northvolt's Västerås gigafactory anchors a supplier ecosystem serving Nordic and German vehicle plants.
France
Renault Group's hybrid platform strategy sustains procurement of compact module formats for C-segment integration. REACH chemical compliance deadlines are accelerating chemistry reformulation timelines for nickel and cobalt compounds. The Paris-Saclay cluster hosts thermal management engineering centers supporting French OEM validation protocols.
Netherlands
Urban distribution fleet operators in Rotterdam and Amsterdam impose high-cycle-life requirements for last-mile commercial vehicle electrification. CE marking certification under the EU Battery Regulation extends product validation cycles for Dutch pack assemblers. Eindhoven's automotive technology corridor concentrates battery management system development for plug-in hybrid architectures.
Poland
Greenfield gigafactory sites in Lower Silesia offer tariff-advantaged supply positions for French and Swedish vehicle assembly plants. The country's industrial zones attract cell manufacturing investments seeking proximity to German OEM procurement centers. Wrocław and Poznań host expanding module integration facilities serving European hybrid platform demand.
Europe Hybrid Electric Vehicle Battery Market Competitive Landscape
Capacity expansion dominates the current landscape as cell producers race to secure OEM supply agreements before 2030 compliance deadlines. The vendor base stratifies across three tiers: integrated cell-to-pack manufacturers, specialized module assemblers, and regional pack integrators serving aftermarket channels. Two strategic archetypes predominate: Asian-headquartered suppliers leveraging established cathode precursor networks, and European challengers emphasizing regional supply security and recycled-content compliance. Geographic expansion and strategic partnerships constitute the dominant competitive moves, with producers establishing module lines adjacent to major vehicle assembly plants.
Within the integrated cell-to-pack tier, LG Energy Solution and Samsung SDI Co., Ltd. exemplify the scale-driven archetype anchored in established high-nickel cell architectures. CATL Europe occupies a position representing Chinese-headquartered suppliers extending dedicated production lines to serve regional OEM demand. Northvolt AB represents the European challenger model, emphasizing in-house cathode production and closed-loop recycling infrastructure aligned with EU Battery Regulation recycled-content quotas. These three companies collectively illustrate the competitive tension between established Asian supply networks and emerging European supply-security narratives.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI Co., Ltd. |
| Panasonic Holdings Corporation |
| CATL Europe |
| Northvolt AB |
| BYD Europe B.V. |
| SK Innovation Co., Ltd. |
| BMZ Germany GmbH |
| Hoppecke Batterien GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
German OEM procurement of 48V mild-hybrid battery systems under EU Green Deal fleet mandates is forcing cell producers to absorb lithium carbonate volatility while maintaining contract price stability for multi-year supply agreements.
Pricing Analysis
Input-cost pass-through from cathode precursor materials dominates pricing structures across European pack assemblers. Contract-based long-term offtake agreements with German OEMs feature partial indexation to lithium and nickel spot markets, creating margin compression when raw material swings outpace contractual adjustment windows. Price differentiation separates high-nickel NMC cells serving premium thermal management protocols from cost-optimized nickel-metal hydride packs for fleet-focused mild-hybrid platforms. Commercial fleet operators exhibit highest price sensitivity due to total cost of ownership procurement criteria, while premium passenger vehicle OEMs prioritize performance guarantees over unit cost.
Supply Chain Analysis
EU Battery Regulation recycled-content quotas and carbon intensity thresholds under delegated acts are forcing pack producers to qualify regional precursor suppliers ahead of enforcement windows. Cathode active material refining concentrates in China, South Korea, and Japan, exposing European assemblers to trans-shipment risk and tariff exposure under evolving trade measures. Cell production draws from lithium hydroxide feedstock, nickel sulfate, and cobalt compounds with limited European refining capacity. Distribution runs through module integration facilities clustered adjacent to Stuttgart, Gothenburg, and Paris vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal emission mandates and ECHA battery passport requirements create structural demand expansion regardless of near-term commodity cycles.
For Market Incumbents: Anchor multi-year supply agreements with embedded service provisions before 2030 compliance deadlines compress procurement timelines further. Secure backward integration into cathode precursor production to defend margin position against East Asian supply concentration. Prioritize closed-loop recycling infrastructure investments to capture first-mover advantages under EU Battery Regulation recycled-content quotas.
For New Entrants and Emerging Players: Fleet operators in urban distribution electrification programs present the most penetrable demand segment, bypassing entrenched OEM-direct channels through battery-as-a-service offerings. Target Poland and Hungary greenfield manufacturing sites for tariff-advantaged positions serving French and Swedish vehicle plants. Pursue direct OEM-fleet agreements with embedded thermal management system integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with European challengers emphasizing regional supply security and in-house cathode production aligned with ECHA traceability requirements. Long-term viability favors integrated cell-to-pack manufacturers with qualified positions under CE marking certification pathways. Watch delegated acts on carbon intensity thresholds as the critical inflection signal for sourcing decisions reshaping competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Secures supply chain resilience against East Asian refining concentration under REACH compliance. |
| Closed-Loop Recycling Infrastructure | Captures EU Battery Regulation recycled-content quota advantages ahead of 2027 enforcement. |
| Module Line Geographic Expansion | Establishes tariff-advantaged production adjacent to Stuttgart-Dresden OEM procurement clusters. |
| Solid-State Electrolyte R&D Partnership | Positions for next-generation 400V thermal stability requirements in German OEM validation protocols. |
| Battery-as-a-Service Fleet Agreements | Bypasses traditional aftermarket channels for urban distribution electrification procurement consolidation. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, cell manufacturing operations heads, and commercial fleet electrification managers grounded qualitative findings in operational reality. Secondary validation drew from EU Battery Regulation delegated acts, ECHA substance restriction filings, vehicle production databases, and customs trade records for lithium-ion cell imports. Bottom-up capacity expansion tracking across Polish and Hungarian greenfield sites triangulated against top-down OEM procurement disclosure analysis.
Segment-level outputs across battery chemistry, end-user procurement channel, vehicle application class, and charging method dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from installed base growth modeling and replacement cycle dynamics for mild-hybrid architectures. Forecast inputs incorporated EU Green Deal fleet mandate compliance timelines, silicon-dominant anode technology maturation curves, and ECHA battery passport infrastructure investment trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium carbonate price volatility, REACH chemical compliance friction on nickel and cobalt compounds, and electrochemical engineering talent scarcity constraining capacity expansion. A small set of regulatory enforcement triggers and raw material supply disruptions warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
Mexico Solar E-Bike Market