
 E-Bike Smart Systems Market | 2026-2036
E-Bike Smart Systems Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Smart Systems Market Insights
Modular controller-and-display bundling is realigning how OEMs specify smart system packages for mid-tier e-bike platforms. Bosch eBike Systems leverages its integrated drive unit ecosystem to dominate premium original equipment placements across European assemblers. Shimano Inc competes through proprietary wireless connectivity protocols that anchor its position in performance-oriented road and gravel e-bike segments. Bafang Electric (Suzhou) Co., Ltd. specializes in open-architecture motor controllers that allow regional brands to customize firmware for local terrain and regulatory requirements.
E-bike smart systems encompass networked hardware-software assemblies that govern motor assistance, energy distribution, rider telemetry, and fleet connectivity through CAN-bus protocols and over-the-air update architectures. These systems serve the dual commercial purpose of optimizing powertrain efficiency under variable load conditions and enabling remote diagnostics for shared mobility operators. Pedal assist configurations occupy the largest installed base due to regulatory permissiveness across European Union member states and established consumer familiarity. Smart battery management technology represents the fastest-expanding technology segment as cell chemistry complexity and thermal runaway risks intensify manufacturer investment in predictive state-of-charge algorithms. Delivery services channel disproportionate margin capture through high-utilization fleet contracts that prioritize uptime guarantees and integrated theft-recovery functionality.
The European Union's Machinery Directive harmonization through CE marking requirements shapes minimum safety and electromagnetic compatibility standards for smart system imports. Germany's KBA and France's national consumer safety authority enforce divergent type-approval pathways that fragment homologation timelines for multi-market suppliers. The EU AI Act introduces emerging compliance obligations for predictive maintenance algorithms and automated rider assistance features. Stakeholders must monitor whether forthcoming battery passport mandates under the EU Green Deal will force architectural redesigns of cloud-connected energy management platforms.
Market Dynamics
Fleet electrification mandates from logistics operators are compressing specification cycles for connected drive systems as procurement shifts from component sourcing to integrated uptime-guarantee contracts.
Growth Catalysts
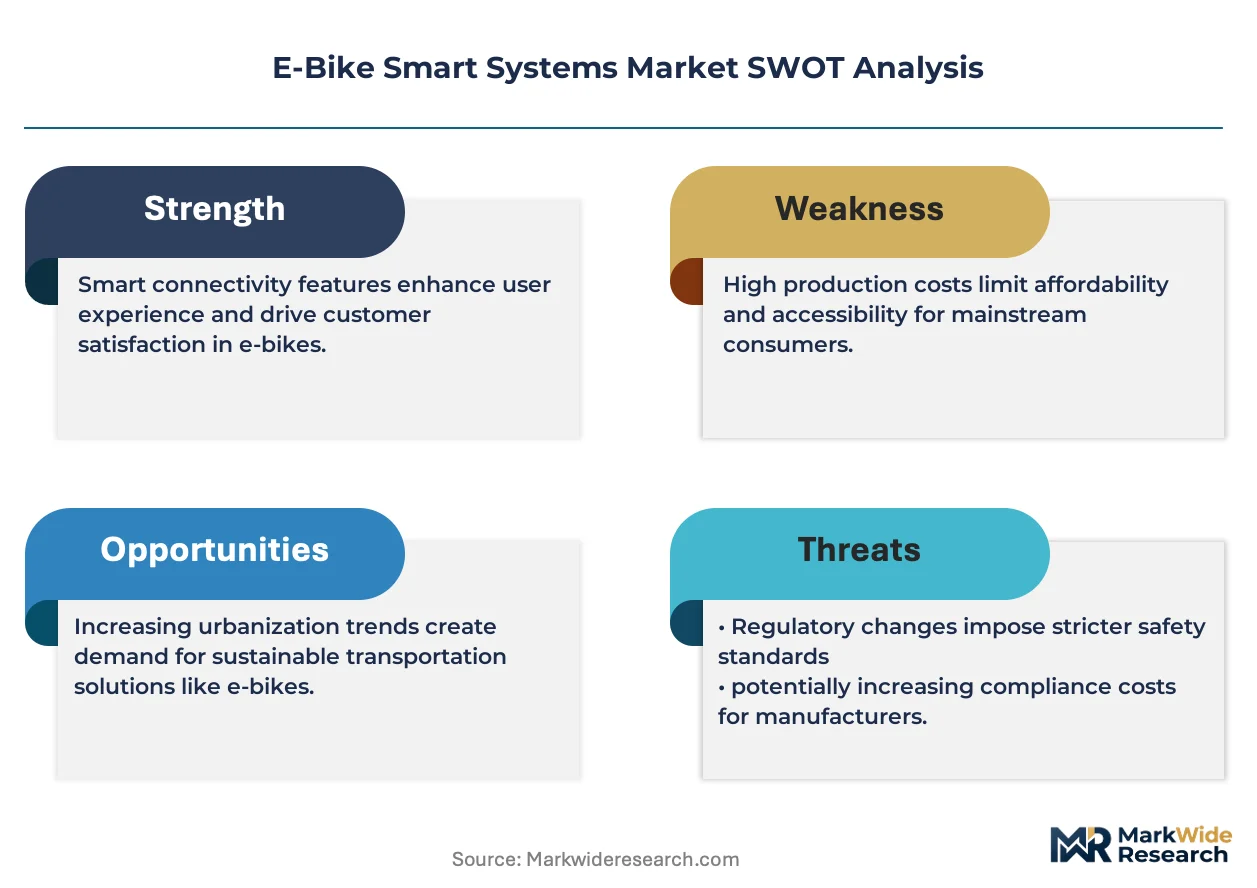
- Last-mile delivery fleet contracts:Logistics operators replacing combustion vans with e-cargo bikes generate concentrated demand for theft-recovery and remote diagnostics functionality.
- Germany's KBA type-approval streamlining:Accelerated homologation pathways for connected drive units reduce time-to-market for mid-tier OEMs serving corporate procurement.
- Lithium-nickel-manganese-cobalt cell chemistry advances:Higher energy density configurations enable extended range specifications that unlock commercial fleet viability in suburban delivery corridors.
Market Restraints
- Controller semiconductor supply concentration:Taiwan-based foundry capacity constraints create input bottlenecks for CAN-bus motor control modules.
- F-Gas Regulation compliance costs:The EU's phasedown of fluorinated greenhouse gases forces thermal management system redesigns for battery enclosures.
- Pedelec speed cap divergence:Netherlands 25 km/h limits versus Swiss 45 km/h type-approval categories fragment firmware development requirements.
Strategic Opportunities
- Battery passport mandate preparation:The EU Green Deal's forthcoming digital product passports create first-mover advantage for cloud-connected energy management platforms.
- AI Act algorithmic maintenance:Predictive state-of-health diagnostics for battery cells open subscription revenue streams under emerging AI liability frameworks.
- Insurance-telematics partnerships:Usage-based coverage models for shared mobility fleets require integrated accelerometer and GPS data architectures.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortages of engineers proficient in real-time operating systems for motor control delay product roadmap execution.
- Multi-market homologation timelines:Divergent electromagnetic compatibility testing between France's national consumer safety authority and German KBA protocols extend certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Smart Systems Market |
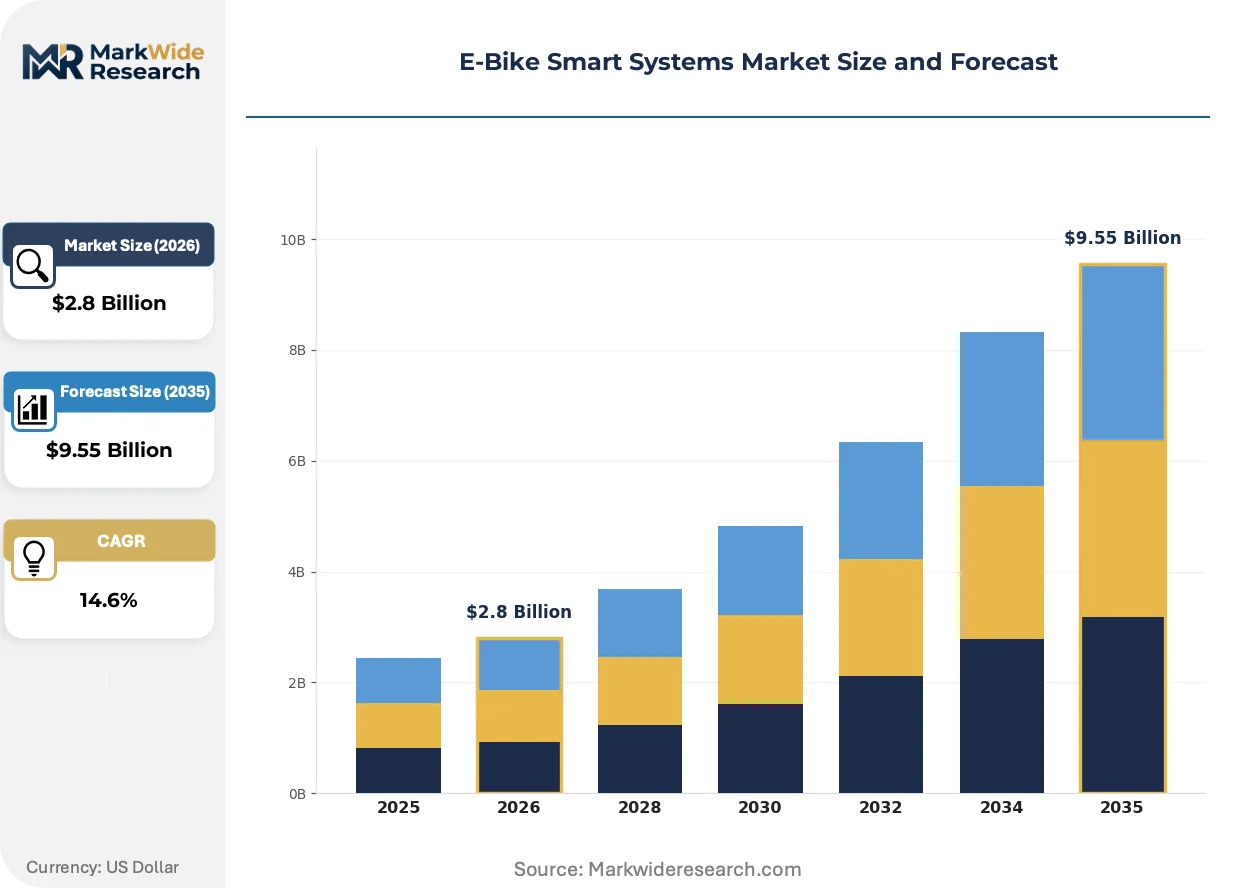
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pedal Assist, Throttle Control, Speed Pedelec, Cargo E-Bike Technology: Integrated GPS, Bluetooth Connectivity, Smart Battery Management, Cloud Connectivity End User: Recreational Users, Commuters, Delivery Services, Tour Operators Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Rental Services |
| Companies Covered | Bosch eBike Systems, Shimano Inc, Bafang Electric (Suzhou) Co., Ltd., Yamaha Motor Co., Ltd, Mahle GmbH, Ananda, Robert Bosch GmbH, Accell Group NV, Pon.Bike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Smart Systems Market Trends and Innovations
Connected vehicle architectures are absorbing functionality from adjacent domains as e-bike systems converge with automotive-grade telematics and consumer electronics interfaces.
Solid-state inertial measurement units are absorbing gyroscopic stability functions previously handled by mechanical sensors in anti-theft and crash-detection subsystems. Fleet operators in Dutch corporate bike leasing programs are specifying these components as standard equipment. The technology is absorbing margin from aftermarket alarm installers by embedding recovery protocols at the factory level.
The EU AI Act's risk classification framework is reshaping development priorities for predictive maintenance algorithms that anticipate battery degradation. Manufacturers must now document training data provenance and algorithmic transparency for systems deployed in shared mobility contexts. German operators face the steepest compliance burden given the KBA's alignment with Brussels enforcement timelines.
Corporate procurement departments are consolidating vendor relationships around integrated system suppliers who bundle hardware, connectivity, and service-level agreements. This displaces the historical pattern of OEMs sourcing displays, controllers, and telematics modules from separate vendors. The Netherlands exhibits the most advanced concentration, where cycling infrastructure density justifies dedicated fleet management platform investments.
E-Bike Smart Systems Market Segmentation
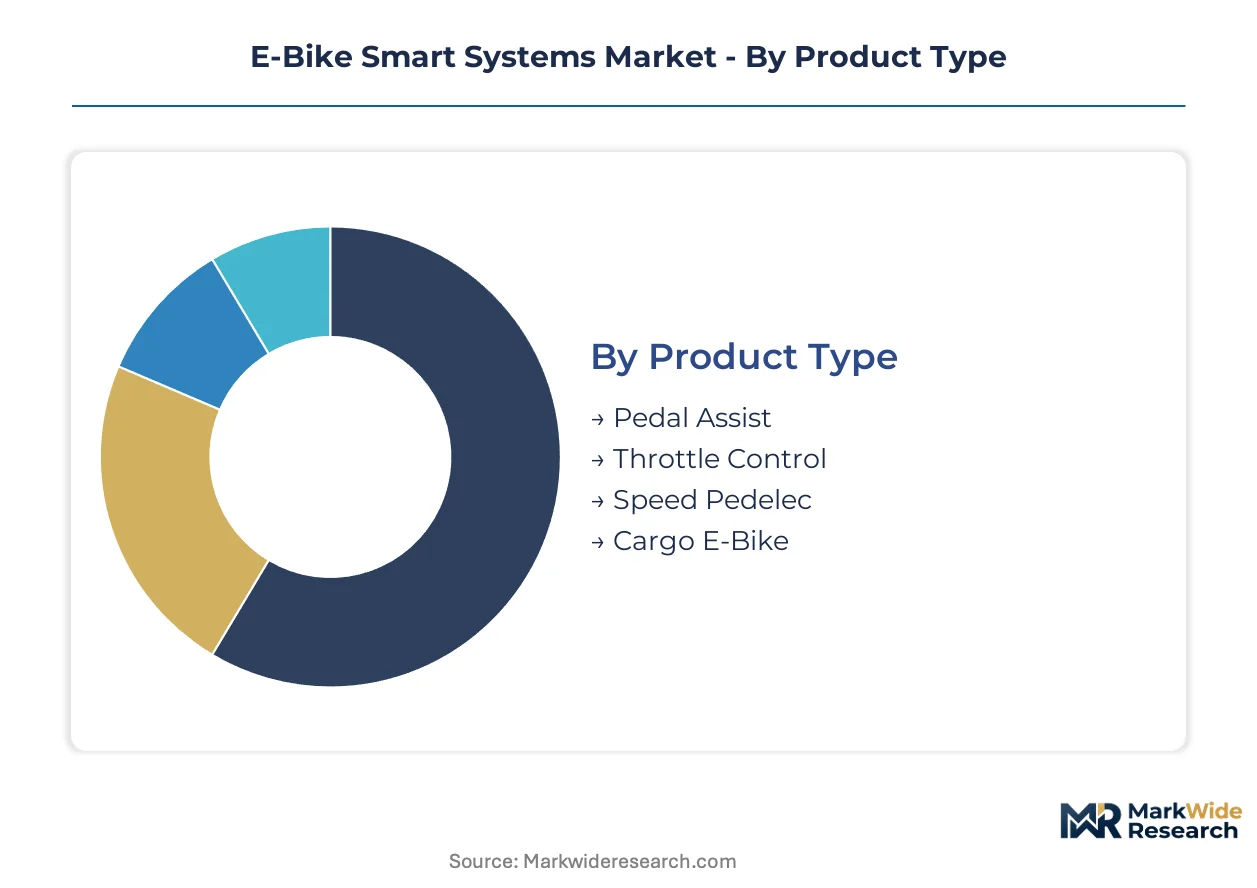
Segmentation in e-bike smart systems determines procurement specifications, firmware development priorities, and margin capture potential across divergent use cases. Fleet operators and individual consumers impose fundamentally different connectivity, durability, and service-level requirements on system suppliers.
Product Type:
Supply concentration among European drive unit manufacturers shapes how product categories penetrate distinct regulatory environments and price tiers.
- Pedal Assist:Sensor arrays measure cadence and torque to modulate motor output proportionally to rider effort. Demand concentrates in the Netherlands and Germany, where urban commuting infrastructure and employer bike-leasing subsidies sustain volume procurement.
- Throttle Control:Twist-grip or thumb-actuated mechanisms deliver motor power independent of pedaling input, requiring distinct firmware architectures for power curve mapping. North American recreational markets absorb the bulk of production, though regulatory restrictions in EU member states limit homologation pathways.
- Speed Pedelec:45 km/h capable systems demand enhanced braking integration and mandatory helmet compliance under KBA and Swiss type-approval frameworks.
- Cargo E-Bike:Reinforced frame-integrated controllers manage higher load profiles for urban logistics fleets, with Dutch delivery operators specifying theft-recovery telemetry as standard.
Pedal Assist absorbs the bulk of installed capacity; Cargo E-Bike is expanding most quickly.
Technology:
Component sourcing patterns for semiconductor and connectivity modules determine which technology layers achieve scale economics first.
- Smart Battery Management:Predictive state-of-charge algorithms and cell-balancing circuitry mitigate thermal runaway risks in high-density lithium-nickel-manganese-cobalt configurations. Fleet contracts in German last-mile delivery prioritize these systems for uptime guarantees and warranty cost containment.
- Cloud Connectivity:Over-the-air firmware update architectures and real-time telemetry streaming enable remote diagnostics for shared mobility operators. Dutch corporate leasing programs mandate these capabilities for asset tracking and usage-based billing integration.
- Integrated GPS:Multi-constellation positioning modules support geofencing and theft recovery, with insurance-telematics partnerships driving specification in premium commuter segments.
- Bluetooth Connectivity:Low-energy protocols link smartphones to motor controllers for ride data logging and assist mode customization, dominating recreational user preferences.
Smart Battery Management commands the highest unit economics; Cloud Connectivity is climbing the fastest as fleet digitization accelerates.
End User:
Customer procurement sophistication varies sharply, with institutional buyers extracting service-level agreements that reshape supplier margin structures.
- Delivery Services:Logistics operators specify integrated uptime guarantees, remote diagnostics, and theft-recovery functionality in multi-year fleet contracts. German and Dutch urban corridors concentrate demand as van replacement programs accelerate.
- Commuters:Employer-subsidized leasing schemes in Belgium and the Netherlands drive specification of connected displays and smartphone integration for route optimization.
- Recreational Users:Weekend riders prioritize intuitive interface design and fitness tracking over fleet-grade durability, absorbing mid-tier controller-display bundles.
- Tour Operators:Rental fleet managers in Austrian and Italian alpine regions require ruggedized enclosures and simplified user interfaces for transient customer bases.
Delivery Services generate the steepest expansion trajectory; Commuters retain the largest installed base.
Distribution Channel:
Channel configuration determines service attachment rates and data capture opportunities for aftermarket revenue streams.
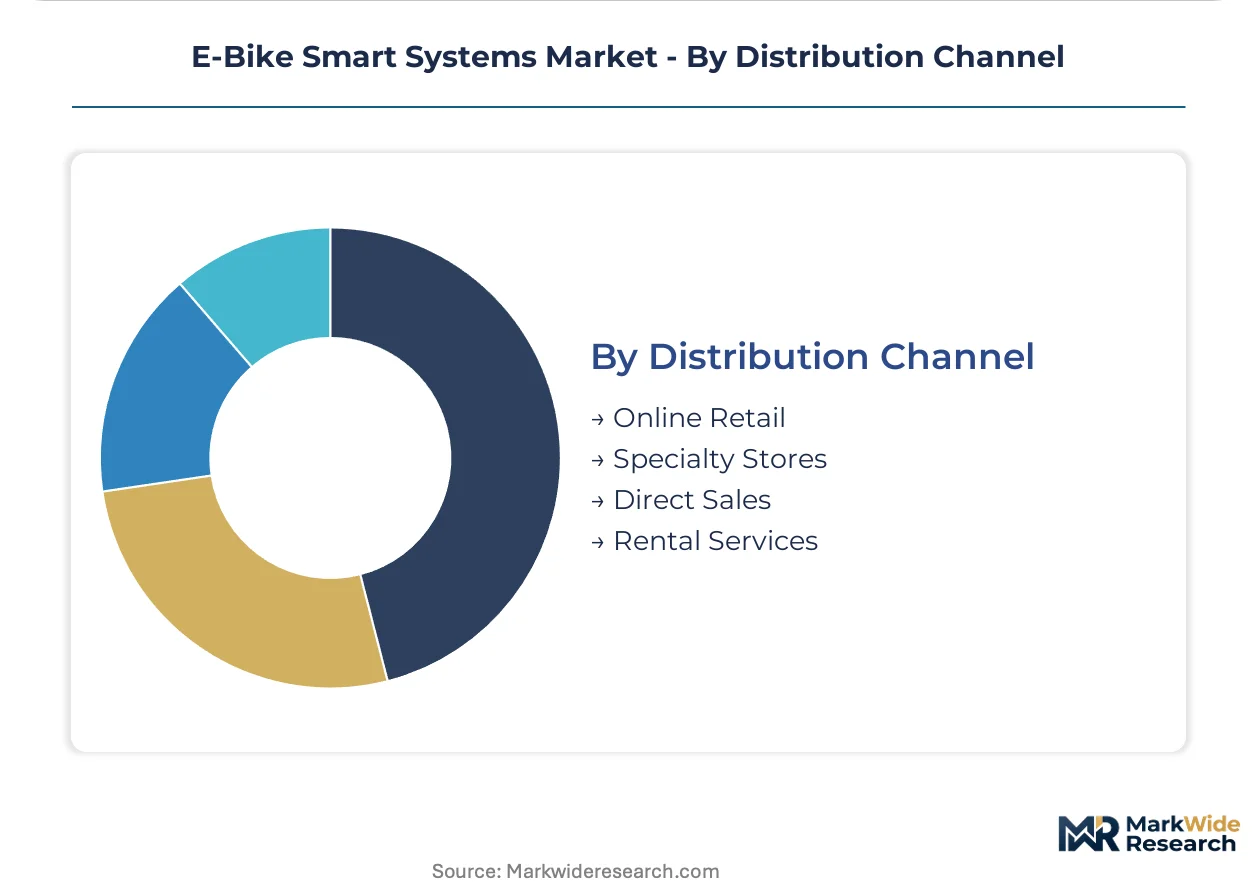
- Specialty Stores:Independent retailers in German cycling hubs provide installation, firmware updates, and warranty handling that sustain premium pricing for integrated drive systems.
- Direct Sales:Manufacturer-owned channels bypass margin stacking, enabling aggressive pricing on cloud-connected platforms with subscription service attachments.
- Online Retail:E-commerce penetration concentrates in price-sensitive recreational segments, though complex homologation requirements limit direct-to-consumer volume in regulated EU markets.
- Rental Services:Mobility-as-a-service operators in Paris and Barcelona specify bundled hardware-connectivity-service contracts that displace discrete component sourcing.
Specialty Stores dominate premium system attachment; Rental Services are gaining share fastest as shared mobility models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German and Chinese manufacturing clusters while consumption gravitates toward Dutch and German fleet operators. The Netherlands absorbs the highest per-capita procurement volumes for connected cargo systems.
Germany
KBA type-approval streamlining accelerates homologation for mid-tier OEMs serving corporate bike-leasing programs. The EU AI Act imposes documentation burdens on predictive maintenance algorithms deployed in shared mobility contexts. Stuttgart and Munich anchor development clusters where drive unit manufacturers integrate CAN-bus architectures with automotive-grade telematics.
Netherlands
Employer-subsidized leasing schemes and dense cycling infrastructure sustain concentrated demand for pedal-assist commuter configurations. The EU Green Deal's battery passport mandates force architectural redesigns of cloud-connected energy management platforms. Randstad logistics corridors generate fleet-scale contracts for theft-recovery telemetry in last-mile delivery applications.
China
Domestic e-bike volume and export-oriented controller manufacturing create dual demand streams for open-architecture motor systems. GB standards and MIIT regulations govern electromagnetic compatibility for connected drive units. Suzhou and Shenzhen production clusters supply firmware-customizable controllers to regional brands targeting European regulatory environments.
United States
Recreational throttle-control preferences and limited federal standardization sustain fragmented state-level regulatory landscapes. The FCC governs wireless connectivity protocols for Bluetooth-linked smartphone interfaces. California and Colorado outdoor recreation markets absorb premium integrated display-controller bundles for trail and gravel applications.
Switzerland
Speed pedelec categories at 45 km/h generate distinct firmware development requirements separate from EU 25 km/h limits. Swissmedic alignment with CE marking streamlines import pathways for German and Austrian system suppliers. Zurich and Geneva corporate leasing programs specify enhanced braking integration for high-speed commuter configurations.
E-Bike Smart Systems Market Competitive Landscape
The competitive structure tilts toward integrated drive unit ecosystems over modular component suppliers. Premium placements favor manufacturers bundling hardware, connectivity, and service-level agreements. Three archetypes dominate: automotive-heritage system integrators, bicycle-component specialists with proprietary wireless protocols, and open-architecture controller fabricators serving regional OEMs. Geographic expansion through fleet management platform partnerships and vertical integration into battery management software represent the dominant competitive vectors.
Among automotive-heritage integrators, Bosch eBike Systems and Mahle GmbH anchor the premium tier through captive supply of drive unit ecosystems. Shimano Inc exemplifies the component-specialist archetype with proprietary connectivity protocols. Bafang Electric (Suzhou) Co., Ltd. occupies the open-architecture position, enabling firmware customization for brands navigating divergent national regulatory requirements.
| Leading Market Players |
|---|
| Bosch eBike Systems |
| Shimano Inc |
| Bafang Electric (Suzhou) Co., Ltd. |
| Yamaha Motor Co., Ltd |
| Mahle GmbH |
| Ananda |
| Robert Bosch GmbH |
| Accell Group NV |
| Pon.Bike |
| Others |
Pricing and Supply Chain Analysis
Over-the-air firmware architectures are compressing development timelines while simultaneously redistributing margin capture toward cloud-connected platform providers and away from discrete component vendors. This technological shift concentrates procurement leverage among fleet operators in the Netherlands and Germany who bundle hardware specifications with multi-year service-level agreements.
Pricing Analysis
Cost-down pressure on mid-tier controller-display bundles accelerates because open-architecture suppliers from Suzhou are undercutting integrated drive unit premiums. Three-tier pricing structure across premium, standard, and economy levels separates Bosch-anchored OEM placements from Shimano protocol-locked configurations and Bafang-customizable regional alternatives. Price differentiation hinges on KBA type-approval certification tiers and after-sales telemetry subscription attachments. Delivery services exhibit the lowest price sensitivity due to uptime-guarantee contract structures, while recreational consumers in North America drive standard-tier commoditization.
Supply Chain Analysis
Semiconductor supply for CAN-bus motor control modules rests on Taiwan-based foundry capacity that feeds controller fabrication clusters in Suzhou and Shenzhen. Lithium-nickel-manganese-cobalt cathode active materials draw from Chinese and South Korean chemical processors, while multi-constellation GPS modules source from Taiwanese and Japanese component houses. Single-source vulnerability concentrates in automotive-grade microcontroller supply for predictive battery management algorithms. Distribution runs through German specialty retailers for premium integrated systems and direct manufacturer channels for fleet-scale cloud platform deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for predictive maintenance algorithms erects compliance barriers that favor incumbents with documented training data provenance and algorithmic transparency capabilities.
For Market Incumbents: Cement market position by deepening in-house production of battery management software and securing exclusive fleet management platform partnerships with Randstad logistics operators. The threat of open-architecture controller commoditization from Chinese suppliers demands defensive certification investment in KBA and Swissmedic alignment ahead of smaller competitors. For New Entrants and Emerging Players: Begin with white-space targeting of throttle-control firmware customization for North American recreational markets where EU regulatory fragmentation creates incumbent blind spots. The most penetrable entry vector lies in insurance-telematics integration for shared mobility fleets in Paris and Barcelona, leveraging accelerometer-GPS data architectures as a differentiated go-to-market anchor. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by automotive Tier 1 suppliers seeking e-mobility software capabilities. Long-term viability favors targets with captive cloud connectivity platforms and established CE marking documentation under the EU Green Deal's battery passport mandates. The signal to watch is KBA enforcement timeline acceleration for AI Act compliance in German shared mobility deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Passport Platform Development | EU Green Deal mandates force architectural redesigns of cloud-connected energy management systems ahead of compliance deadlines. |
| Predictive Maintenance Algorithm Certification | AI Act documentation requirements create subscription revenue streams for state-of-health diagnostics under emerging liability frameworks. |
| Fleet Management Software Integration | Dutch corporate leasing programs demand bundled hardware-connectivity-service contracts that displace discrete component sourcing. |
| Insurance-Telematics Data Architecture | Usage-based coverage models for shared mobility fleets require integrated accelerometer and GPS telemetry standardization. |
| Open-Architecture Controller Customization | Regional brands in European markets require firmware flexibility for divergent national speed limits and electromagnetic compatibility standards. |
Research Methodology
Document review covered EU regulatory filings including AI Act implementation guidance and KBA type-approval pathways, complemented by interviews with drive unit engineering directors, fleet procurement managers at Dutch logistics operators, and specialty retailer service heads across German cycling hubs. Secondary validation drew from SEC filings of listed component suppliers, EU trade customs data for e-bike system imports, and automotive telematics patent disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across the analysis window.
Cross-referencing historical adoption curves with panel input from OEM platform engineers and shared mobility operators anchored the projection framework. Segmentation dimensions modeled include product type hierarchy, technology layer penetration, end-user procurement sophistication, and regional regulatory cluster alignment. CAGRs were derived from slope consistency checks against fleet electrification mandate timelines and battery chemistry advancement curves. Key inputs incorporated F-Gas Regulation compliance cost trajectories and semiconductor foundry capacity utilization assumptions.
Underlying measurement precision varies by segment; cargo e-bike fleet contracts carry tighter precision than recreational throttle-control estimates due to concentrated buyer visibility. Forecasts reflect documented assumptions around KBA streamlining efficacy and EU battery passport implementation schedules. A small set of triggers warrants ongoing watch: Taiwan foundry capacity constraints, divergent EU member state AI Act enforcement timelines, and lithium-nickel-manganese-cobalt commodity price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Latin America Electric Bus Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market