
 Organic Lamb Market | 2026-2036
Organic Lamb Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Lamb Market Outlook
Capital-intensity divergence between integrated processors and boutique organic suppliers is rotating competitive advantage toward vertically scaled operators. Danish Crown A/S leverages its Nordic cold-chain infrastructure to sustain year-round organic lamb distribution across European retail banners. Silver Fern Farms anchors premium export positioning through pasture-to-plate traceability systems that dominate trans-Pacific trade lanes. Thomas Foods International competes on slaughter capacity, operating large-scale facilities that control cost structures for commodity-grade organic cuts.
Organic lamb denotes ovine meat derived from animals raised on certified organic pasture without synthetic hormones, antibiotics, or genetically modified feed, with carcass processing adhering to residue-free protocols and cold-chain integrity standards below four degrees Celsius. Its primary commercial purpose centers on supplying protein to premium retail and food service channels where clean-label credentials command price premiums. Whole lamb and lamb rack segments concentrate margin pools in direct-to-restaurant trade, where specialty butchers and food service buyers prioritize intact carcass breakdown for menu customization. Online retailers represent the fastest-growing distribution channel, though supermarkets still occupy the volume base through private-label organic lines that consolidate consumer trust.
USDA Organic standards govern livestock feed sourcing and pasture access in the United States, while EU Organic regulations enforce stricter stocking-density limits and veterinary-input restrictions across member states. Australia's national organic certification bodies align with AQIS export protocols, creating a triad of compliance frameworks that shape market access and product differentiation. Stakeholders must monitor evolving pasture-certification requirements and cold-chain carbon-accounting rules that will determine which producers retain premium market positioning.
Market Dynamics
Pasture-certification compliance under tightening USDA Organic and EU Organic livestock standards is forcing capital reallocation toward integrated cold-chain operators capable of sustaining year-round residue-free distribution.
Growth Catalysts
- EU Organic Regulation 2018/848:Stricter stocking-density limits and veterinary-input restrictions across member states are accelerating conversion of conventional flocks to certified organic systems.
- Grass-fed premium positioning:Australian and New Zealand export-oriented cold chains supply provenance-labeled proteins to North American food service buyers prioritizing menu transparency.
- Blockchain traceability platforms:Pasture-to-plate digital verification systems enable real-time carcass tracking that satisfies retail banner requirements for clean-label documentation.
Market Restraints
- Organic feed grain costs:Synthetic fertilizer restrictions and non-GMO sourcing requirements concentrate input price volatility among certified producers.
- Southern Hemisphere supply dominance:Australia and New Zealand control over 70% of exportable organic lamb volumes, creating geographic concentration risk for import-dependent markets.
- Extended flock conversion timelines:Three-year pasture-certification periods and breeding-stock replacement requirements delay revenue recognition for transitioning operators.
Strategic Opportunities
- Direct-to-restaurant channels:Specialty butchers and chef-driven procurement models in the United States and Germany bypass retail margin compression through intact carcass sales.
- Carbon-accounting integration:Cold-chain emissions measurement protocols under emerging EU Green Deal agricultural frameworks enable premium positioning for low-carbon certified producers.
- Cellular agriculture convergence:Cultivated ovine fat and collagen technologies may eventually hybridize with conventional organic processing for value-added ingredient applications.
Industry Challenges
- Veterinary therapeutics scarcity:Antibiotic prohibition under organic standards leaves producers dependent on limited approved alternatives during endemic disease outbreaks.
- Slaughter capacity bottlenecks:Dedicated organic processing lines require segregated equipment and residue-testing protocols that extend facility turnaround times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Lamb Market |
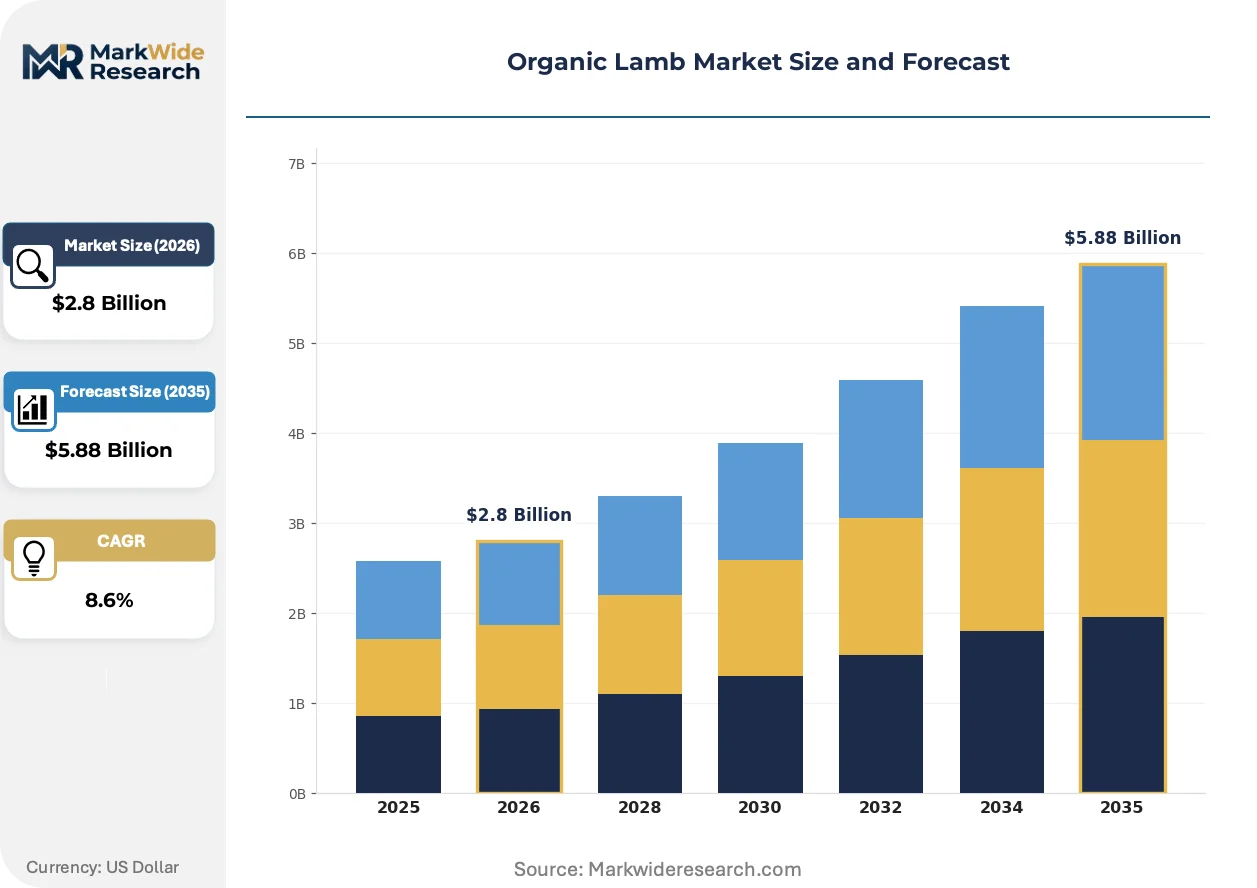
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Lamb, Lamb Chops, Ground Lamb, Lamb Rack Distribution Channel: Supermarkets, Farmers' Markets, Online Retailers, Specialty Butchers Packaging Type: Vacuum Packed, Tray Sealed, Bulk Packaging, Retail Packs Market Segment: Food Service, Retail, Export, Organic Certification |
| Companies Covered | Tyson Foods, Inc., Hormel Foods Corporation, Danish Crown A/S, Minerva Foods S.A., Australian Lamb Company, New Zealand Lamb Company, Organic Valley, Thomas Foods International, Silver Fern Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Lamb Market Strategic Shifts
Digital traceability infrastructure and alternative protein technologies are compressing traditional sourcing hierarchies while regulatory carbon-accounting requirements reshape competitive differentiation mechanisms.
Blockchain-enabled provenance verification is fragmenting established wholesale relationships by enabling restaurant groups and retail banners to contract directly with certified pastoral operations. Danish Crown and Silver Fern Farms have deployed distributed ledger systems that record individual animal pasture history, slaughter dates, and cold-chain handoffs. This disintermediation compresses margin pools previously captured by layered traders and regional distributors.
EU Green Deal agricultural carbon-footprint disclosure mandates are forcing cold-chain operators to instrument refrigerated transport with real-time emissions monitoring. The F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants compounds this transition, requiring fleet retrofits or replacement. Australian exporters targeting European retail banners now bundle AQIS-certified organic status with transport-emissions documentation to maintain shelf placement.
Chef procurement teams in premium North American food service channels are consolidating supplier relationships around vertically integrated operators offering intact carcass breakdown and custom fabrication. This concentration displaces traditional commodity auctions and spot-market purchasing. Thomas Foods International and comparable processors capture this demand through dedicated organic slaughter lines and in-house aging facilities that deliver specification-cut primals directly to restaurant back-of-house operations.
Organic Lamb Market Segmentation
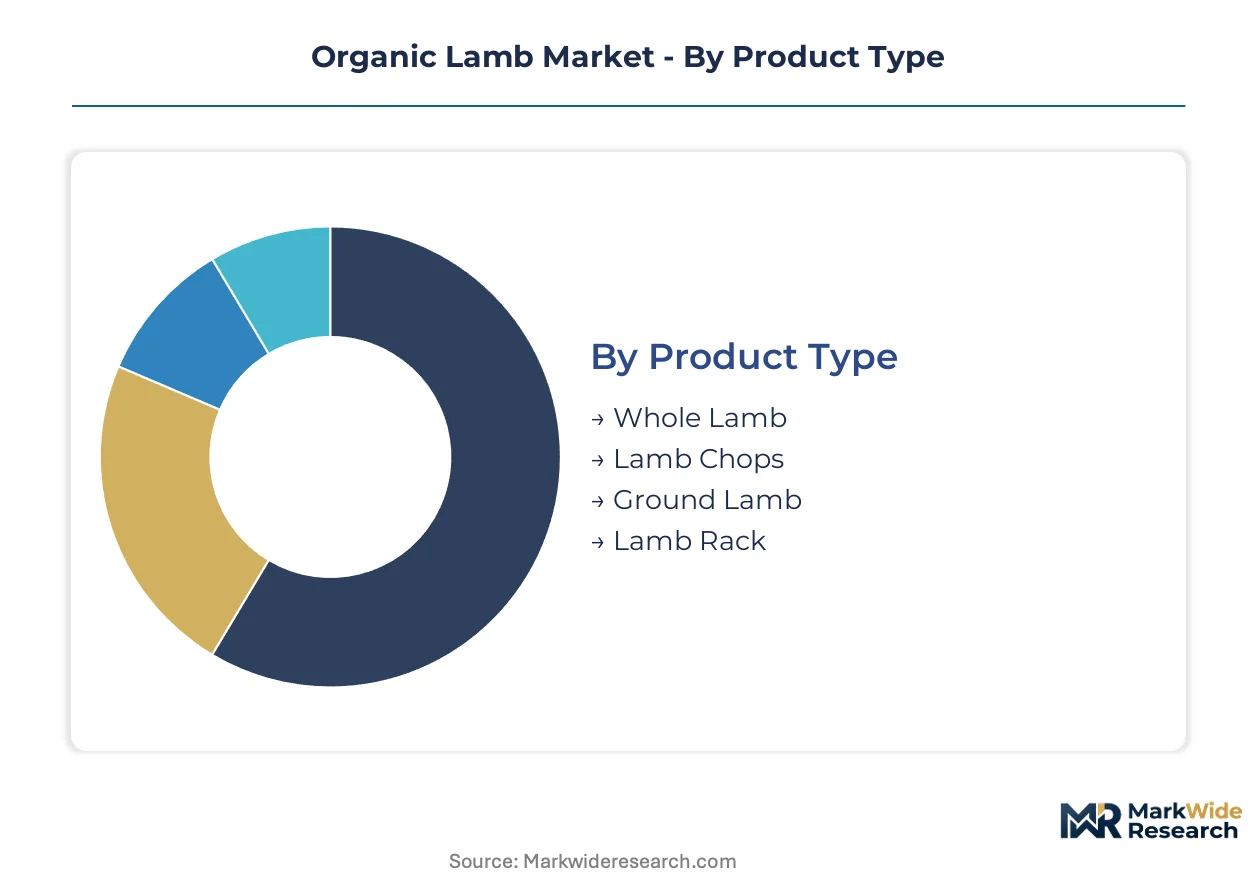
Organic lamb segmentation reflects divergent margin structures across intact carcass trade versus fabricated cuts, with distribution channel selection determining access to premium pricing pools. Product form and packaging specifications align with distinct cold-chain requirements and buyer procurement protocols.
Product Type:
Whole lamb dominates domestic food service procurement in Australia and New Zealand, while fabricated cuts concentrate export value in European retail banners.
- Whole Lamb:Intact carcasses enable custom fabrication by specialty butchers and chef-driven procurement teams. Australian pastoral operations supply whole lamb direct to North American restaurant groups seeking provenance-labeled menu proteins with intact breakdown control.
- Lamb Rack:Frenched rib sections command the highest per-kilogram pricing in premium retail and white-tablecloth channels. EU Organic-certified racks from Danish Crown A/S sustain year-round placement in German and French supermarket premium tiers.
- Lamb Chops:Loin and shoulder cuts target mid-market retail segments with shorter aging requirements.
- Ground Lamb:Trim-derived product serves ethnic grocery and food manufacturing applications with compressed margin structures.
Whole lamb holds the largest share; momentum sits with lamb rack as retail banners consolidate premium private-label lines.
Distribution Channel:
Channel selection determines cold-chain investment recovery rates, with direct-to-restaurant bypassing retail margin stacking.
- Supermarkets:Private-label organic lines consolidate consumer trust through dedicated shelf placement and residue-free certification signage. German retail banners Edeka and Rewe maintain year-round organic lamb programs sourced through Nordic cold-chain intermediaries.
- Online Retailers:Home-delivery platforms are expanding most quickly as subscription meat-box services aggregate demand across postcode clusters. Australian exporters leverage AQIS-certified status to supply direct-to-consumer platforms in California and Texas.
- Specialty Butchers:Independent fabricators source intact carcasses for custom aging and cut specification.
- Farmers' Markets:Direct pastoral sales capture full margin but face seasonality constraints and limited cold-chain control.
Supermarkets anchor volume throughput; online retailers are climbing the fastest as logistics platforms mature.
Packaging Type:
Packaging specification aligns with shelf-life extension requirements and retail banner display protocols.
- Vacuum Packed:Oxygen-exclusion systems extend retail case-ready shelf life to 35 days under controlled atmosphere. EU cold-chain operators deploy vacuum technology to satisfy F-Gas Regulation compliance while maintaining four-degree Celsius integrity.
- Tray Sealed:Modified-atmosphere packaging dominates fresh retail presentation with shorter dating windows.
- Retail Packs:Pre-portioned cuts target convenience-oriented consumers with specification-grade labeling.
- Bulk Packaging:Food service totes and primal bags serve restaurant back-of-house operations with minimal retail-ready finishing.
Vacuum packed commands premium placement; tray sealed is gaining share fastest as retail dating standards tighten.
Market Segment:
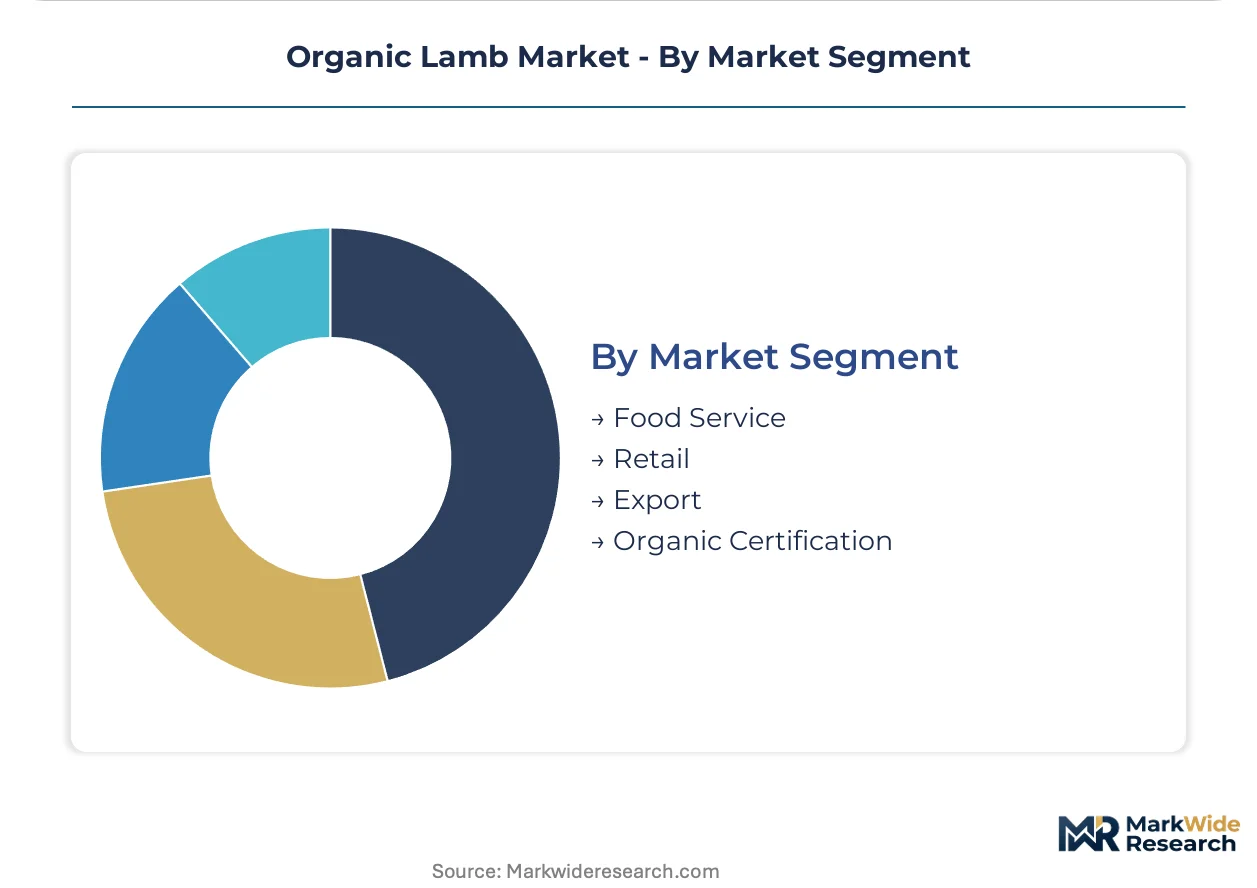
End-use segmentation separates commodity-grade export flows from certification-premium domestic channels.
- Food Service:Chef procurement teams prioritize intact carcass access and pasture-to-plate documentation for menu transparency. Thomas Foods International operates dedicated organic slaughter lines supplying specification-cut primals direct to restaurant operations.
- Retail:Supermarket banners consolidate private-label organic lines with residue-free certification and origin labeling. Silver Fern Farms anchors trans-Pacific trade through retail-ready packaging compliant with USDA Organic standards.
- Export:Australia and New Zealand supply over 70% of tradeable organic lamb volumes to import-dependent markets.
- Organic Certification:Certification-grade premiums separate USDA Organic, EU Organic, and AQIS-aligned product streams.
Food service captures the highest margin per kilogram; retail is expanding most quickly as consumer trust consolidates around banner certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export premiums from Australian and New Zealand pastoral operations command pricing power over North American food service buyers, while EU regulatory compliance costs compress margins for domestic European producers. This asymmetry concentrates profit pools in Southern Hemisphere supply chains. Cold-chain infrastructure investments in Denmark and Germany attempt to recapture value through year-round distribution capability.
Australia
Queensland and New South Wales pastoral zones supply over half of exportable organic lamb volumes to trans-Pacific trade lanes. TGA-aligned AQIS certification protocols govern residue-free export eligibility, creating compliance moats for established operators. Thomas Foods International anchors South Australian processing capacity with dedicated organic slaughter lines serving direct-to-restaurant channels in California and Texas.
New Zealand
South Island high-country stations dominate grass-fed flock production for premium North American retail placement. Silver Fern Farms operates pasture-to-plate traceability systems that satisfy USDA Organic documentation requirements. Canterbury processing clusters concentrate vacuum-packing and cold-chain staging for trans-Pacific shipment consolidation.
United States
California and Texas consumer bases drive domestic demand through subscription meat-box platforms and specialty butcher networks. USDA Organic livestock standards enforce three-year pasture-certification timelines that constrain domestic supply expansion. Colorado and Wyoming ranching operations increasingly convert conventional flocks to capture restaurant procurement premiums in Denver and Austin metro areas.
Germany
Bavarian and Lower Saxony retail banners Edeka and Rewe sustain year-round organic lamb programs through Nordic cold-chain intermediaries. EU Organic Regulation 2018/848 stocking-density limits accelerate conventional-to-organic flock conversion among domestic producers. Berlin and Hamburg food service clusters prioritize intact carcass procurement with blockchain-verified pasture documentation.
Denmark
Danish Crown A/S leverages integrated Nordic cold-chain infrastructure to distribute EU Organic-certified product across German and French supermarket premium tiers. F-Gas Regulation refrigerant phase-down requirements drive fleet retrofit investments in refrigerated transport. Jutland pastoral operations concentrate breeding-stock genetics optimized for organic certification compliance.
Organic Lamb Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the organic lamb value chain. Vertically integrated processors with captive cold-chain infrastructure capture margin pools through year-round distribution capability, while boutique pastoral operations compete on provenance narrative and direct-channel relationships. The market structures around three archetypes: scale-driven slaughterhouses, traceability-integrated exporters, and cooperative pastoral networks. Dominant competitive moves include backward integration into breeding-stock genetics and strategic partnerships with retail banner private-label programs.
Among Antipodean exporters, Silver Fern Farms and Thomas Foods International exemplify divergent scale-versus-specialization positioning, while Danish Crown A/S anchors European integrated processing. Silver Fern Farms occupies the traceability-premium tier through pasture-to-plate digital verification. Thomas Foods International represents volume-scale competitive logic with large-scale facility operations. Danish Crown A/S sits within the regional consolidation archetype leveraging Nordic infrastructure for cross-border distribution.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| Hormel Foods Corporation |
| Danish Crown A/S |
| Minerva Foods S.A. |
| Australian Lamb Company |
| New Zealand Lamb Company |
| Organic Valley |
| Thomas Foods International |
| Silver Fern Farms |
| Others |
Value Chain & Pricing Dynamics
Ninety-day pasture-certification timelines tether inventory velocity to seasonal breeding cycles, compressing pricing power into Southern Hemisphere harvest windows while EU and North American buyers absorb freight-adjusted premiums for year-round cold-chain continuity. This structural lead-time asymmetry concentrates margin capture among integrated operators capable of bridging hemispheric supply gaps.
Pricing Analysis
The customization-premium spread between intact whole-lamb carcasses and specification-cut primals spans certification-grade and fabrication-complexity differentials. Three-tier pricing structure across premium, standard, and economy levels stratifies by EU Organic, USDA Organic, and AQIS-aligned certification tiers, with frenched racks commanding the widest spreads. Pricing pressure stems from organic feed grain cost volatility under synthetic fertilizer restrictions. Food service buyers exhibit the lowest price sensitivity due to menu-premium pass-through capability, while ethnic grocery channels trading ground lamb trim face acute margin compression.
Supply Chain Analysis
Australia and New Zealand anchor grass-fed flock production, supplying over seventy percent of exportable organic lamb volumes to North American and European buyers. The supply chain draws from certified pasture inputs, non-GMO feed supplements, and segregated slaughter-line equipment. Single-source vulnerability concentrates in trans-Pacific refrigerated container capacity, where F-Gas Regulation fleet retrofits constrain equipment availability. Distribution runs through vertically integrated cold-chain operators capable of sustaining four-degree Celsius integrity across hemispheric transit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of three-year pasture-certified breeding stock and dedicated organic slaughter capacity constrains supply expansion faster than demand growth, creating structural leverage for asset holders over traders. The capability gap centers on residue-free cold-chain infrastructure capable of EU Green Deal emissions documentation.
For Market Incumbents: Consolidate breeding-stock genetics programs and captive cold-chain infrastructure to defend against blockchain-enabled disintermediation threatening layered distributor margins. Secure year-round distribution capability through Nordic or trans-Pacific infrastructure partnerships. Prioritize EU Organic certification investment ahead of tightening stocking-density enforcement under Regulation 2018/848. For New Entrants and Emerging Players: Direct-to-restaurant procurement platforms represent the most penetrable white-space where incumbents under-serve chef-driven specification demands. Target California and Texas metro food service clusters with intact carcass offerings and pasture-verification documentation. Deploy subscription meat-box models aggregating postcode-cluster demand to bypass retail banner slotting-fee barriers. For Investors and Strategic Acquirers: Long-term, this sits as a premium protein infrastructure play because cold-chain carbon-accounting capabilities will determine shelf-placement access under emerging EU agricultural frameworks. Acquisition targets cluster around vertically scaled processors with AQIS-certified export eligibility and in-house vacuum-packing capacity. Watch F-Gas Regulation refrigerant phase-down compliance timelines as inflection indicators for fleet replacement cycles and stranded-asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Pasture-Certification Compliance Investment | Three-year conversion timelines lock in supply eligibility under tightening USDA Organic and EU Organic livestock standards. |
| Cold-Chain Carbon-Accounting Integration | EU Green Deal transport-emissions documentation secures premium retail banner placement for Australian and New Zealand exporters. |
| Blockchain Traceability Deployment | Pasture-to-plate digital verification enables direct contracting between pastoral operations and North American restaurant groups. |
| Direct-to-Restaurant Channel Development | Intact carcass sales bypass retail margin compression while capturing chef procurement premiums in Denver and Austin metro areas. |
| Organic Feed Grain Sourcing Security | Non-GMO supply contracts under synthetic fertilizer restrictions stabilize input cost volatility for certified producers. |
Study Parameters
A spread of perspectives from pastoral operation managers, cold-chain logistics directors, food service procurement officers, and retail banner category buyers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through AQIS export protocols, EU Organic Regulation 2018/848 documentation, USDA Organic livestock standards, and customs trade data. Bottom-up flock inventory estimates and top-down retail channel revenue triangulation anchored volume and value assessments.
Product type, distribution channel, packaging specification, and market segment dimensions structured the analytical framework across the projection horizon. CAGRs derived from hemispheric supply-cycle modeling and certification-conversion pipeline analysis. Forecast inputs incorporated organic feed grain price indices, refrigerated container freight rates, and EU F-Gas Regulation compliance cost curves.
Underlying assumptions cover pasture-certification timeline stability and cold-chain integrity standards, with deviation risk concentrated in veterinary therapeutics scarcity during endemic disease outbreaks and Southern Hemisphere climate variability affecting grass-fed flock weights. Recalibration cycles align with material shifts in EU Green Deal agricultural carbon-accounting mandates and USDA Organic livestock standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat-Based FPP Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Bacon Slicers Market
Meat Products
Brisket Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Organic Halal Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Bacon Flavors Market
Meat Products
Pork Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Hams Market
Meat Products
Beef Bouillon Market
Meat Products
North America Canned Meat Market
Meat Products
France Meat Products Market
Meat Products
Global Beef Market