
 Europe Edible Meat Market | 2026-2036
Europe Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Edible Meat Market Foresight
The EU Green Deal's Farm to Fork Strategy is restructuring how European meat processors source livestock and verify carbon footprints across their supply chains. Danish Crown leverages its cooperative ownership model to sustain direct farmer relationships across Denmark and Sweden. Vion Food Group anchors its operations through controlled slaughter and deboning capacity in the Netherlands and Germany. Tönnies Holding competes via large-scale pork processing complexes that dominate Central European supply.
Europe edible meat encompasses muscle tissue from cattle, swine, poultry, and ovine species intended for human consumption, typically processed under controlled temperature chains with specified pH decline curves and microbial load thresholds to ensure shelf stability and safety. The primary commercial purpose centers on providing protein-rich foodstuffs for retail, food service, and industrial prepared-meal applications. Beef and pork occupy mature volume positions where margin pools concentrate in aged and premium-cut segments. Poultry leads growth trajectories across food service channels due to favorable cost-to-protein ratios and shorter production cycles. Certification tiers stratify across organic, free-range, and conventional labels, with organic commanding sustained price premiums in German and French retail.
EMA and EFSA frameworks govern veterinary residue limits and zoonotic risk protocols, while REACH and EU Green Deal regulations impose binding sustainability disclosures on feed sourcing and methane intensity. These standards shape demand by restricting market access for non-compliant imports and redirecting procurement toward verified low-carbon suppliers. Stakeholders must monitor evolving CSRD reporting obligations and their cascading effects on supplier certification requirements.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing production timelines while mandating farm-to-retail traceability systems that restructure procurement relationships across Western European supply chains.
Growth Catalysts
- CSRD reporting obligations:Large food retailers in Germany and France now require verified carbon intensity data from meat suppliers, redirecting procurement toward certified low-carbon producers.
- Food service channel expansion:Quick-service operators across the Netherlands are expanding poultry procurement due to favorable cost-to-protein ratios and shorter production cycles.
- Organic certification premiums:German retail chains sustain price premiums for organic-labeled beef and pork, locking in farmer loyalty through long-term supply contracts.
Market Restraints
- Feed input cost volatility:Soybean and grain price swings compress processor margins, particularly for pork operations dependent on imported protein meal.
- Slaughter capacity concentration:Central European processing complexes create geographic supply risk during disease outbreaks or labor disruptions.
- REACH chemical compliance:Veterinary residue testing protocols add documentation burden and extend batch-release timelines for export-bound products.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania present white-space expansion for premium certified meats as retail modernization accelerates.
- Cellular-cultivated hybrid products:Convergence of bioreactor technology with traditional processing expertise opens novel product categories for food service channels.
- Direct-to-restaurant distribution:Bypassing wholesale intermediaries allows processors to capture margin and build chef-relationship data assets.
Industry Challenges
- Veterinary pharmacology expertise gap:Shortage of residue-testing specialists delays compliance verification for smaller slaughter operations.
- Cold-chain capex intensity:Controlled-temperature logistics upgrades require capital deployment that strains mid-tier processor balance sheets.
- Organic certification timeline compression:Three-year conversion periods for livestock farms create supply gaps during demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Edible Meat Market |
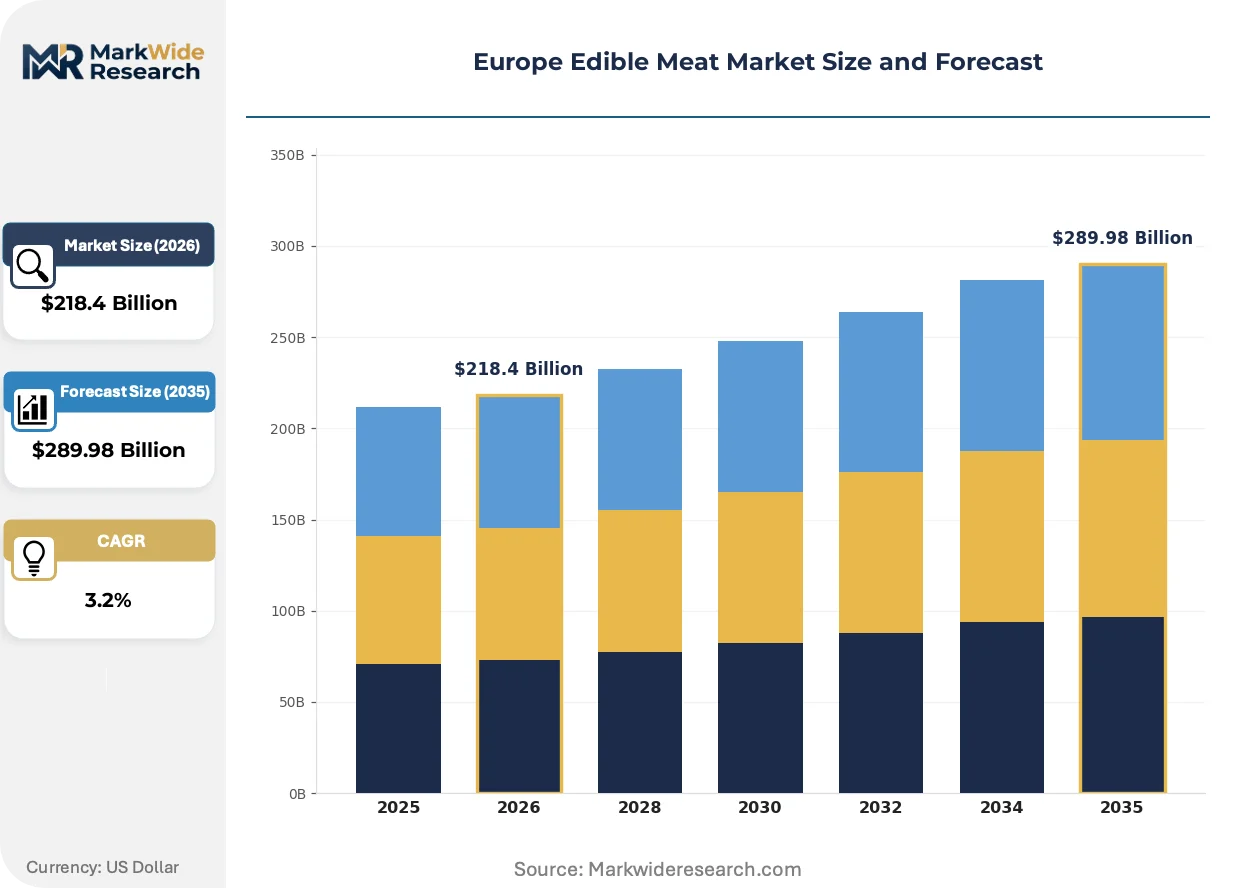
| Market Size in 2026 | $218.4 Billion |
| Market Size in 2035 | $289.98 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb End User: Restaurants, Retailers, Households, Food Service Distribution Channel: Supermarkets, Online, Specialty Stores, Farmers' Markets Certification: Organic, Free-range, Grass-fed, Conventional |
| Companies Covered | Danish Crown, Vion Food Group, Tönnies Holding, JBS, Cargill, ABP Food Group, Groupe Bigard, Cherkizovo Group, WH Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Edible Meat Market Shifts & Advancements
Blockchain-enabled traceability platforms are reconfiguring how European meat processors verify origin claims and manage supplier compliance across multi-tier supply networks.
Blockchain-based livestock tracking systems assign immutable digital identifiers to individual animals from birth through slaughter. Danish and Swedish cooperatives are deploying these platforms at herd-scale to satisfy retailer audit requirements. This technology is decentralizing traceability authority away from centralized certification bodies toward distributed farmer-processor data networks.
REACH and EU Green Deal regulations now mandate binding sustainability disclosures on feed sourcing and methane intensity for large-scale operators. These frameworks force restructuring of procurement contracts to include carbon-footprint clauses. Beef processors in Germany face the steepest compliance burden due to cattle's higher methane output relative to poultry or pork.
Certification-driven purchasing now dominates French and German retail procurement, with buyers demanding organic, free-range, or carbon-neutral labels before contract award. Traditional commodity-grade meats lose shelf space to verified alternatives in urban supermarket chains. This preference shift concentrates most visibly in Paris and Berlin metropolitan retail zones where consumer willingness-to-pay for labeled products exceeds rural benchmarks.
Europe Edible Meat Market Segmentation
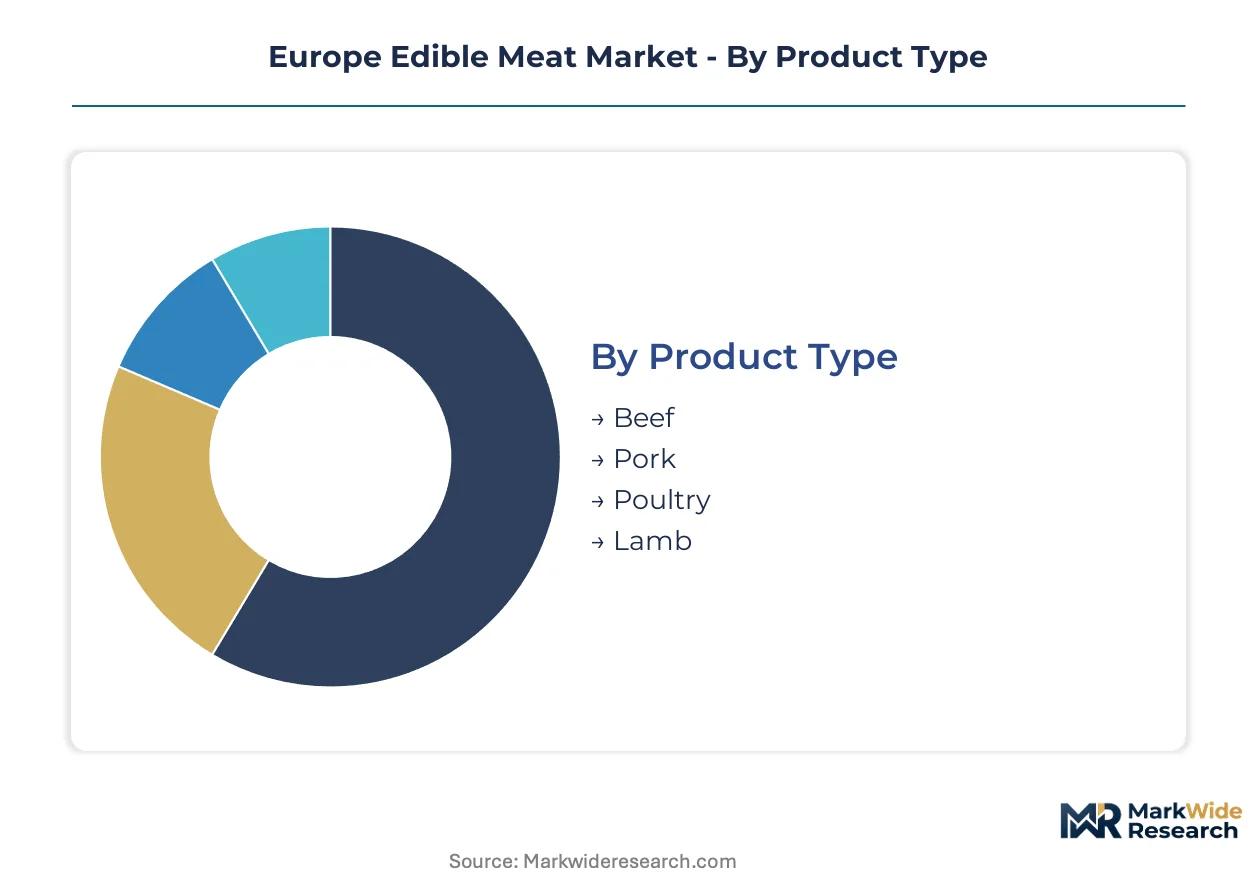
Certification tiers and channel fragmentation now dominate procurement decisions across European meat supply chains. Buyers in Germany and France increasingly filter supplier selection through carbon-intensity verification and traceability platform compatibility.
Product Type:
Protein cost ratios and production cycle length determine volume allocation across food service procurement desks.
- Poultry:Shorter grow-out periods and favorable feed-conversion ratios position poultry as the default protein for quick-service operators. Dutch and Belgian food service distributors are expanding cold-chain capacity specifically for poultry portions.
- Pork:Central European slaughter complexes achieve scale efficiencies through integrated farrow-to-finish operations. German processors leverage these assets to supply standardized cuts for industrial prepared-meal manufacturers.
- Beef:Aged premium cuts command sustained margin pools in French and Italian retail, though methane-intensity disclosures under CSRD pressure procurement patterns.
- Lamb:Seasonal demand concentration in Mediterranean markets limits year-round volume, with Irish and UK suppliers dominating spring procurement cycles.
Pork leads on scale; poultry leads on momentum.
End User:
Margin capture varies sharply by buyer sophistication and contract structure.
- Food Service:Quick-service and contract catering operators prioritize specification consistency and just-in-time delivery windows. French institutional buyers now mandate carbon-footprint documentation alongside HACCP compliance.
- Retailers:German supermarket chains leverage private-label muscle to extract price concessions while demanding exclusive organic supply lines. Shelf-space allocation increasingly favors certified tiers over conventional alternatives.
- Restaurants:Independent chefs in Copenhagen and Amsterdam build direct processor relationships to secure heritage-breed supply and custom aging programs.
- Households:Price-sensitive procurement through discount channels sustains volume for conventional pork and poultry cuts, though organic penetration climbs in urban households.
Retailers dominate absolute volume; restaurants expand most quickly.
Distribution Channel:
Cold-chain reliability and last-mile temperature integrity separate premium from commodity positioning.
- Supermarkets:Controlled-atmosphere packaging and case-ready presentation now standard for beef and pork in French and German hypermarkets. Retailer consolidation concentrates bargaining power among fewer national chains.
- Online:Direct-to-consumer subscription models for organic and heritage meats gain traction in Scandinavian urban markets, though logistics costs constrain rural penetration.
- Specialty Stores:Artisan butchers in Italian and Spanish city centers sustain demand for dry-aged beef and breed-specific pork, supported by origin-labeling schemes.
- Farmers' Markets:Short supply chains appeal to sustainability-motivated buyers in German university towns, though volume remains marginal to total market.
Supermarkets anchor volume; online channels gain share fastest.
Certification:
Label credibility and audit trail completeness determine price premium realization.
- Organic:Three-year conversion timelines and prohibited antibiotic use create supply inelasticity. German retailers lock in farmer loyalty through five-year forward contracts at fixed premiums.
- Free-range:Outdoor access mandates raise production costs 15-25% above conventional systems, with French consumers showing highest willingness-to-pay for poultry bearing this designation.
- Grass-fed:Irish and Scottish beef processors leverage pasture-based systems to meet methane-intensity thresholds under EU Green Deal reporting, accessing preferential procurement terms from sustainability-focused buyers.
- Conventional:Commodity-grade supply faces margin compression as retailer shelf space reallocates toward verified alternatives, though volume remains substantial in price-sensitive Eastern European markets.
Organic commands the steepest price premiums; grass-fed shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale meat processing took root in Denmark and Germany during the late 19th century, when cooperative slaughterhouses and rail-linked cold chains first enabled transnational protein distribution across Northern Europe.
Germany
Food service operators in Berlin and Munich are expanding procurement of carbon-verified beef under CSRD retailer mandates. The country's Federal Ministry of Food and Agriculture enforces strict veterinary residue protocols through official control laboratories. North Rhine-Westphalia hosts Tönnies Holding's large-scale pork processing complexes, where integrated farrow-to-finish operations supply standardized cuts to industrial prepared-meal manufacturers.
France
Parisian retail chains command sustained price premiums for organic-labeled beef and heritage-breed pork, locking farmer loyalty through long-term supply contracts. ANSM and DGCCRF frameworks govern veterinary pharmacology compliance and origin-labeling enforcement. The Auvergne-Rhône-Alpes cluster anchors Groupe Bigard's controlled slaughter and deboning capacity, serving both domestic retail and export-bound premium cuts.
Denmark
Cooperative ownership models sustain direct farmer relationships across Jutland and Zealand, with Danish Crown leveraging herd-scale blockchain traceability to satisfy retailer audit requirements. The Danish Veterinary and Food Administration enforces EU Green Deal-aligned methane intensity reporting for large-scale operators. Copenhagen's metropolitan retail zones show consumer willingness-to-pay for labeled products that exceeds rural benchmarks by significant margins.
Netherlands
Quick-service operators in Amsterdam and Rotterdam are expanding poultry procurement due to favorable cost-to-protein ratios and shorter production cycles. The Netherlands Food and Consumer Product Safety Authority mandates binding sustainability disclosures on feed sourcing under REACH-aligned frameworks. Vion Food Group anchors operations through controlled slaughter capacity in the Gelderland region, supplying specification-consistent portions to food service distributors.
Poland
Retail modernization in Warsaw and Kraków is creating white-space expansion for premium certified meats as discount channels gradually upgrade assortment depth. The country's Chief Veterinary Officer enforces EU-harmonized zoonotic risk protocols and border inspection post controls. Greater Poland Voivodeship concentrates mid-tier pork processing operations that serve price-sensitive Eastern European markets while building compliance capability for Western retail entry.
Europe Edible Meat Market Competitive Landscape
Capital-heavy producers compete with asset-light traders across a tiered structure where slaughter capacity ownership separates margin capture from commodity brokerage. Cooperative ownership models in Scandinavia and the Netherlands sustain direct farmer relationships that centralized competitors cannot replicate. Three archetypes dominate: integrated processors with captive slaughter assets, cooperative federations with member-locked supply, and diversified agribusiness conglomerates with trading desks. Competitive moves concentrate on M&A for regional slaughter capacity and strategic partnerships for cold-chain logistics.
Within the cooperative federation tier, Danish Crown and Vion Food Group exemplify member-owned structures that anchor procurement loyalty through profit-sharing mechanisms. Tönnies Holding occupies a position at the scale-driven end, representing family-controlled processing complexes that dominate Central European pork supply. Among diversified agribusiness operators, JBS and Cargill sit within the trading-and-processing hybrid archetype, leveraging global protein desks to arbitrage regional price spreads.
| Leading Market Players |
|---|
| Danish Crown |
| Vion Food Group |
| Tönnies Holding |
| JBS |
| Cargill |
| ABP Food Group |
| Groupe Bigard |
| Cherkizovo Group |
| WH Group |
| Others |
Supply & Pricing Matrix
Consolidated German and French retail chains command disproportionate pricing power through private-label muscle and exclusive organic supply line demands. This buyer concentration forces processors into cost-plus contract structures with certification premiums that vary by methane-intensity verification tiers.
Pricing Analysis
Three-tier pricing structure across organic, free-range, and conventional certification levels dominates procurement contracts. Price differentiation hinges on carbon-intensity disclosure grades under CSRD mandates and breed-origin verification status. Cost compression in conventional pork runs through feed input volatility and discount channel volume concentration. Eastern European retail buyers exhibit highest price sensitivity; Paris and Berlin metropolitan buyers show lowest sensitivity for heritage-labeled beef.
Supply Chain Analysis
Fuel and refrigerated transport costs are amplifying geographic sourcing radius constraints across European protein distribution. Supply concentrates in Denmark, Germany, and the Netherlands through cooperative-owned slaughter complexes and integrated farrow-to-finish operations. Raw material flows draw from Brazilian and Argentinian soybean meal, Ukrainian grain corridors, and domestic pasture systems. Single-source vulnerability concentrates in Central European pork processing clusters. Distribution runs through cold-chain wholesalers to retailer consolidation points and direct-to-restaurant bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe edible meat market functions as a stable compounder anchored by protein demand inelasticity and recurring certification upgrade cycles. Regulatory disclosure obligations under EU Green Deal frameworks sustain procurement pattern predictability.
For Market Incumbents: Lock in farmer loyalty through profit-sharing cooperative structures and five-year forward organic supply contracts. Invest in blockchain-enabled traceability platforms to defend against emerging cellular-cultivated hybrid entrants. Prioritize slaughter capacity modernization in North Rhine-Westphalia and Gelderland regions to maintain specification consistency for food service accounts.
For New Entrants and Emerging Players: Independent chef networks in Copenhagen and Amsterdam represent underserved buyers seeking heritage-breed supply and custom aging programs. Polish retail modernization in Warsaw and Kraków offers white-space expansion for premium certified meats. Deploy direct-to-restaurant distribution to bypass wholesale intermediaries and capture margin.
For Investors and Strategic Acquirers: Diversified agribusiness conglomerates with protein trading desks are the most active acquirers in this space. Mid-tier processors with compliant cold-chain assets and CSRD-ready carbon accounting represent prime acquisition targets across the medium-term horizon. Monitor cellular-cultivated hybrid product regulatory approvals as inflection signal for traditional processor valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Danish Crown leverages herd-scale digital identifiers to satisfy retailer audit requirements. |
| Organic Certification Investment | Three-year farm conversion timelines lock supply inelasticity for German retail chains. |
| Cold-Chain Capacity Expansion | Dutch and Belgian distributors build poultry-specific infrastructure for quick-service growth. |
| Direct-to-Restaurant Distribution | Processors bypass wholesalers to capture margin and build chef-relationship data assets. |
| Eastern European Market Entry | Poland and Romania retail modernization creates white-space for premium certified meats. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged meat processing executives, veterinary compliance officers, retail category buyers, food service procurement managers, and cooperative farmer representatives. Secondary validation drew from EFSA residue monitoring reports, EU Green Deal implementation documents, customs trade databases, and SEC filings of listed protein conglomerates. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Segment-weighting approaches distributed value across poultry, pork, beef, and lamb product types with channel and certification overlays. The analytical framework incorporated protein cost ratios, production cycle lengths, and methane-intensity disclosure compliance tiers across the projection horizon. CAGRs emerged from historical trajectory analysis and regulatory mandate impact assessment. Feed input cost curves and CSRD reporting obligation timelines served as meat-specific forecast inputs.
Underlying measurement precision varies by segment; poultry volume estimates carry tighter precision than lamb given production cycle standardization. Forecasts reflect assumptions about regulatory enforcement consistency and feed commodity price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
North America Edible Meat Market
Meat Products
Europe Processed Meat Market
Meat Products
Beef Bone Broth Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Antibiotic Free Meat Market
Meat Products
Meat Products Market
Meat Products
Organic Meat Market
Meat Products
Meat Ingredients Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Beef Extract Market
Meat Products
United States Red Meat Market
Meat Products
Meat Paste Market
Meat Products
Low Fat Beef Market
Meat Products
Meat Packaging Market
Meat Products
Canned Pork Market