
 North America Processed Pork Meat Market | 2026-2036
North America Processed Pork Meat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Processed Pork Meat Market Analytics
Midwestern packing capacity is recalibrating around automated cutting and sorting lines that raise throughput per shift. Tyson Foods Inc. leverages vertical integration from feed milling to case-ready packaging across its Arkansas and Texas complexes. Smithfield Foods Inc. anchors its position through controlled-environment hog production tied directly to large-scale processing plants in North Carolina and Virginia. Hormel Foods Corporation specializes in value-added branded portfolios that command premium shelf placement in retail deli cases.
Processed pork meat comprises fresh or frozen pork carcasses and primals that undergo curing, smoking, cooking, or fermentation to achieve shelf stability, flavor development, and textural transformation through controlled moisture loss and salt-protein matrix formation. The resulting products serve commercial food manufacturing, foodservice portion control, and retail consumer convenience segments. Bacon and sausage categories dominate volume flows through supermarket and convenience store channels, while cured meat segments capture higher margin pools in specialty retail and online direct-to-consumer distribution. Vacuum pack and tray formats are displacing traditional canning across retail bacon and ham segments as brands emphasize visual product quality and resealability.
The USDA enforces HACCP-based pathogen reduction standards and FSIS labeling rules that govern ingredient declarations, nutritional panels, and safe handling instructions across all interstate commerce. The FDA oversees feed additive approvals and veterinary drug residue limits that cascade into packer quality assurance programs and export certification. State-level agriculture departments in Iowa, North Carolina, and Minnesota administer additional facility inspection regimes that affect plant operating schedules and interstate shipment eligibility. Stakeholders must monitor evolving antibiotic stewardship mandates and carbon accounting disclosures that will reshape sourcing specifications and capital allocation toward lower-intensity production systems.
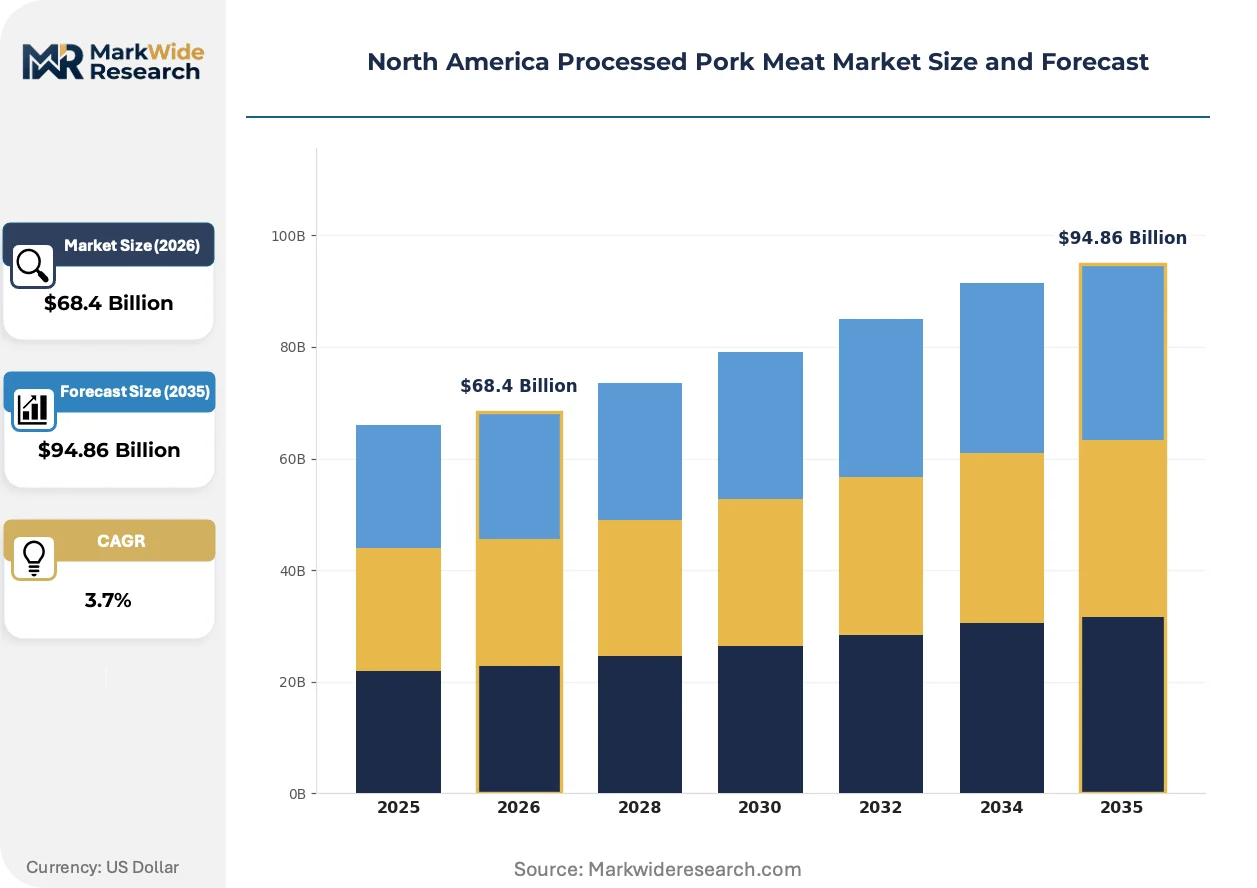
Market Dynamics
Automated portion-cutting lines at Tyson Foods and Smithfield Foods complexes are compressing labor costs while tightening microbiological control, forcing mid-scale processors to consolidate or exit as throughput thresholds rise.
Growth Catalysts
- USDA HACCP modernization:Updated pathogen reduction mandates accelerate capital deployment toward validated intervention technologies at federally inspected plants.
- Foodservice menu expansion:Restaurant operators across the US Midwest and Southeast are widening bacon and smoked ham applications in breakfast-all-day formats.
- Controlled-atmosphere packaging:Vacuum skin and high-barrier tray formats extend refrigerated shelf life, reducing retail shrink and enabling case-ready distribution.
Market Restraints
- Feed grain cost volatility:Corn and soybean meal price swings transmit directly into live hog production economics, compressing packer margins during drought cycles.
- Midwest packing concentration:Iowa and Illinois slaughter capacity dominance creates regional supply bottlenecks when plant downtime occurs.
- Antibiotic residue testing:USDA FSIS zero-tolerance enforcement for veterinary drug traces blocks export certification for non-compliant lots.
Strategic Opportunities
- Direct-to-consumer cured meat subscriptions:Specialty bacon and charcuterie clubs bypass conventional retail slotting fees in US coastal metro corridors.
- Carbon accounting integration:EPA greenhouse gas reporting protocols create premium positioning for verified lower-intensity pork supply chains.
- Clean-label fermentation:Natural curing cultures replace synthetic nitrites, aligning with FDA clean-label positioning in natural retail channels.
Industry Challenges
- Skilled maintenance technician scarcity:Automated cutting and sorting line complexity outpaces vocational training pipeline output in rural packing towns.
- Legacy ERP integration:Real-time yield tracking systems clash with decades-old plant floor data architectures, delaying traceability compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Processed Pork Meat Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $94.86 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacon, Sausage, Ham, Cured Meat End User: Households, Restaurants, Food Processing, Retailers Packaging Type: Vacuum Pack, Cans, Trays, Bags Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Tyson Foods Inc., Smithfield Foods Inc., Hormel Foods Corporation, JBS USA Holdings Inc., Maple Leaf Foods Inc., Seaboard Foods LLC, Clemens Food Group, Johnsonville LLC, OSI Group LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Processed Pork Meat Market Evolving Landscape
Processing technology, regulatory stringency, and channel fragmentation are converging to redefine how cured and smoked pork products move from slaughter floor to final plate.
Hyperspectral imaging systems for fat-to-lean ratio sorting are rewriting yield optimization protocols at high-speed bacon slicing operations. Foodservice distributors with automated portion-control contracts are adopting these units fastest. The technology is compressing variance in finished product weights, reducing customer chargeback exposure.
USDA's updated Listeria monocytogenes alternatives compliance guidelines impose stricter environmental monitoring frequencies for post-lethality exposed products. Plants must now validate intervention effectiveness against revised performance standards. Ready-to-eat ham and deli meat segments face the steepest compliance cost escalation.
Specialty retail buyers are consolidating procurement around single-source verified supply chains with full antibiotic-free documentation. Natural grocers in California and Pacific Northwest markets lead this specification tightening. Conventional broadline distribution is losing share to vertically integrated direct contracts in these corridors.
North America Processed Pork Meat Market Segmentation
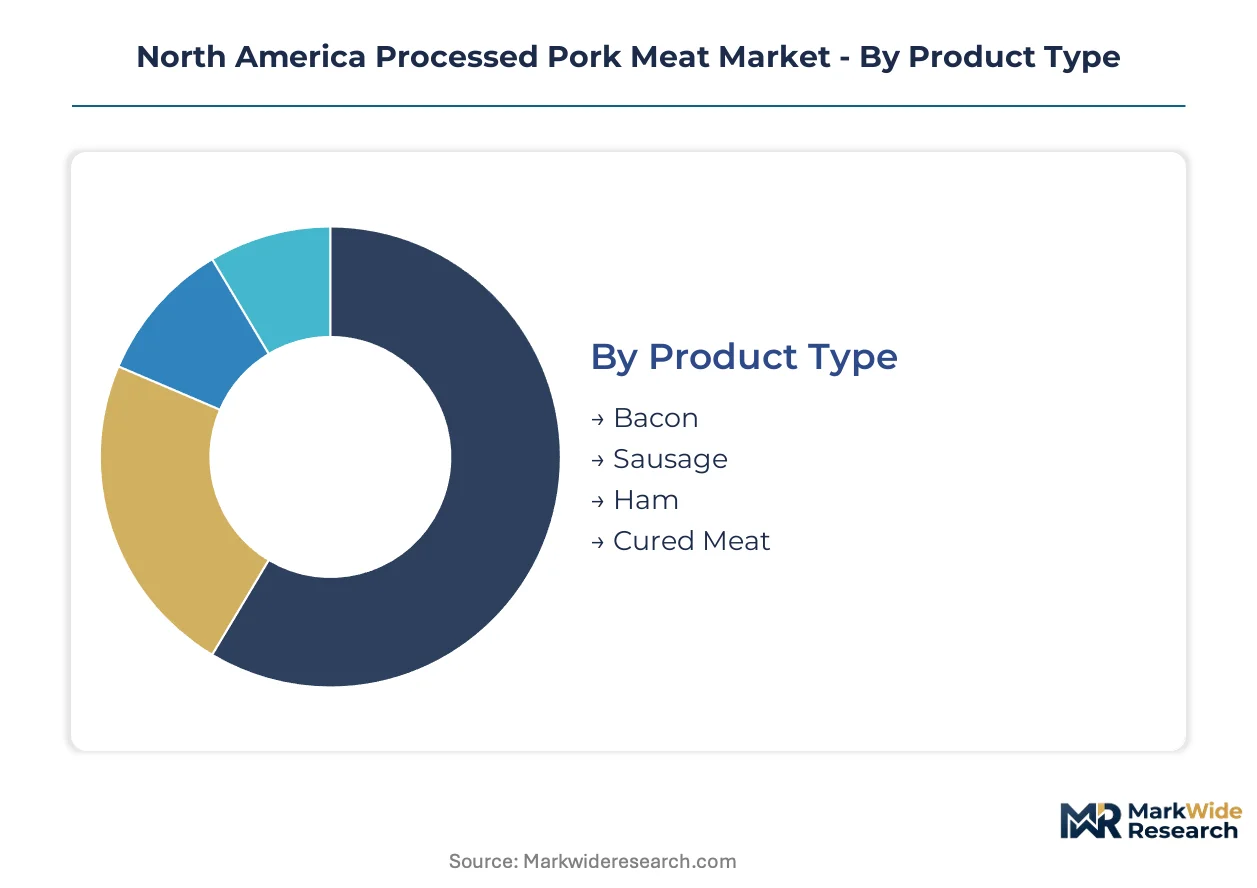
Processed pork meat flows through distinct product categories, packaging formats, and channel structures that each impose different capital requirements and margin profiles. Understanding these segment boundaries clarifies where investment dollars concentrate and where operational complexity escalates.
Product Type:
Capital intensity peaks in segments requiring controlled-environment curing infrastructure and extended aging protocols.
- Bacon:Belly cuts undergo thermal processing, pressing, and high-speed slicing to achieve standardized slice counts per pound. Iowa and Illinois packing plants command the densest concentration of automated belly slicing lines, though margin compression intensifies when feed grain costs spike.
- Sausage:Ground pork formulations incorporate spice matrices and casings through continuous stuffing and linking equipment. Fresh breakfast links dominate Midwest retail freezer cases, while smoked varieties capture foodservice portion-control contracts requiring precise weight tolerances.
- Ham:Cured and smoked hind leg products require brine injection, tumbling, and thermal processing cycles lasting multiple days.
- Cured Meat:Dry-cured and fermented products demand climate-controlled aging rooms with humidity management systems.
Most installed capacity flows through bacon and sausage operations. Expansion is steepest in cured meat segments serving specialty retail channels.
End User:
Volume scale versus margin capture diverges sharply across customer types, with institutional buyers demanding case-ready formats and households driving premium branded purchases.
- Households:Retail consumers purchase branded bacon and deli ham through supermarket refrigerated cases, prioritizing resealable packaging and clean-label ingredient declarations. California and Pacific Northwest natural grocery chains enforce the strictest antibiotic-free specifications.
- Restaurants:Foodservice operators specify pre-cooked bacon strips and portion-controlled ham steaks to reduce labor at the line. Breakfast-all-day menu expansion across US Midwest and Southeast quick-service chains accelerates demand for hold-stable products.
- Food Processing:Industrial buyers integrate diced ham and pre-cooked sausage crumbles into frozen entrees and prepared meals.
- Retailers:Private-label programs at major supermarket chains source directly from packing plants, bypassing branded intermediaries.
Restaurants and food processors absorb the highest volume tonnage. Direct-to-consumer subscription channels serving households are climbing the fastest.
Packaging Type:
Packaging technology investments determine shelf-life extension capabilities and retail visual presentation standards.
- Vacuum Pack:High-barrier films with oxygen scavenging layers extend refrigerated shelf life while enabling vertical merchandising. Bacon and sliced deli meat segments have nearly completed the transition from bulk service cases to vacuum-sealed retail packs.
- Trays:Modified atmosphere packaging with gas-flushed headspaces preserves color stability in fresh sausage and ground pork. Midwest supermarket chains specify tray formats with absorbent pads and clear lid films for case-ready meat programs.
- Cans:Retort-processed shelf-stable ham and luncheon meat persists in emergency preparedness and institutional feeding channels.
- Bags:Shrink and chub packaging serves foodservice bulk sausage and portion-control bacon applications.
Vacuum pack infrastructure dominates current capital deployment. Tray format expansion is gaining share fastest as case-ready distribution deepens.
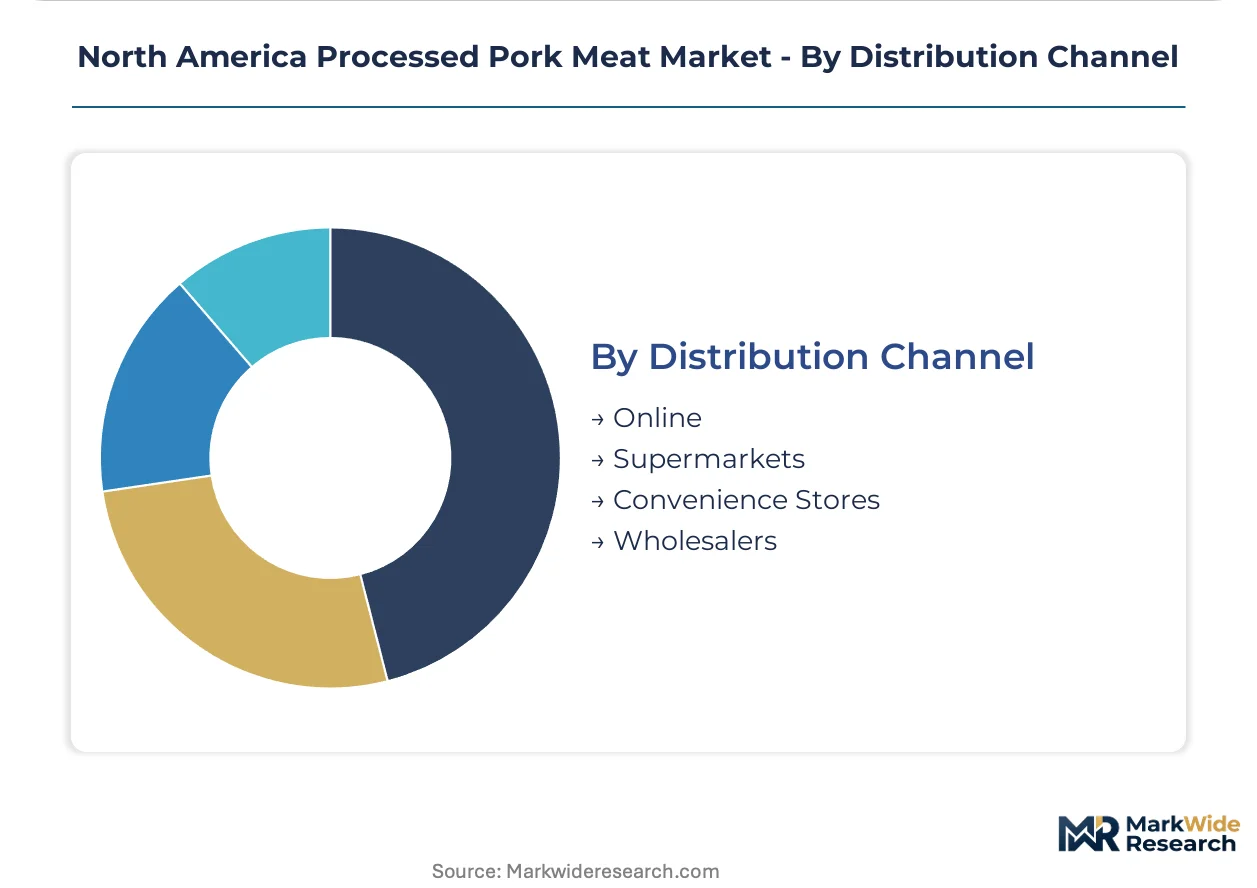
Distribution Channel:
Channel selection dictates cold-chain infrastructure requirements and working capital intensity through inventory velocity differences.
- Supermarkets:Traditional grocery chains maintain refrigerated meat cases with twice-weekly delivery schedules and strict temperature monitoring protocols. Slotting fees and promotional allowances compress net margins for branded processors competing for shelf position.
- Online:E-commerce fulfillment requires insulated packaging with gel packs and expedited shipping to maintain cold chain integrity. Specialty bacon and charcuterie subscriptions bypass conventional retail slotting structures in coastal metro corridors.
- Convenience Stores:Grab-and-go refrigerated sections stock pre-cooked bacon strips and single-serve ham portions for immediate consumption.
- Wholesalers:Broadline foodservice distributors aggregate volume from multiple packers for restaurant and institutional delivery.
Supermarket refrigerated infrastructure handles the majority of volume movement. Online direct-to-consumer channels are expanding most quickly as subscription models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where processing capacity lands, with cost-of-compliance gaps between US states and across the US-Canada border influencing plant location decisions. USDA FSIS inspection fees and state-level environmental permitting create measurable cost differentials that packers factor into capital allocation.
United States
Iowa and Illinois hog finishing density supports integrated packing complexes with automated cutting lines. USDA's updated HACCP pathogen reduction mandates force smaller plants to consolidate or exit. Sioux Falls and Sioux City anchor the densest slaughter capacity corridors in the upper Midwest.
Canada
Manitoba and Quebec hog production feeds specialized bacon and ham processing for US export markets. Health Canada and CFIA inspection protocols create dual-certification requirements that raise compliance costs but secure premium retail access. Brandon, Manitoba hosts concentrated rendering and further processing infrastructure.
Mexico
Sonora and Jalisco pork production supplies domestic sausage and cured meat demand while expanding US-bound fresh pork exports. SENASICA veterinary drug residue testing aligns with USDA FSIS zero-tolerance standards for cross-border shipments. Querétaro's industrial corridor is adding case-ready packaging capacity.
North America Processed Pork Meat Market Competitive Landscape
US Midwest producers anchor one tier; Canadian and Mexican specialists hold regional positions with export-focused configurations. The market structure concentrates around vertically integrated packers with captive hog supply and automated processing infrastructure. Three archetypes dominate: integrated protein conglomerates with feed-to-package control, branded value-added specialists commanding retail premium placement, and regional packers serving foodservice portion-control contracts. Competitive moves center on automated line upgrades that raise throughput thresholds and direct-to-consumer channel bypass of traditional retail slotting structures.
Among US-based integrated processors, Tyson Foods Inc., Smithfield Foods Inc., and Hormel Foods Corporation exemplify the tiered competitive structure. Tyson Foods Inc. represents the scale-driven archetype with multi-state complex networks. Smithfield Foods Inc. anchors the controlled-environment production model tied to large-scale plants. Hormel Foods Corporation occupies the branded premium position in retail deli cases. These three entities collectively illustrate how backward integration into hog production, captive supply of raw material, and in-house packaging capabilities separate market tiers.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| Smithfield Foods Inc. |
| Hormel Foods Corporation |
| JBS USA Holdings Inc. |
| Maple Leaf Foods Inc. |
| Seaboard Foods LLC |
| Clemens Food Group |
| Johnsonville LLC |
| OSI Group LLC |
| Others |
Value Network & Pricing Analysis
Foodservice distributors and quick-service chains in the US Midwest and Southeast concentrate procurement power around case-ready bacon and pre-cooked ham contracts, anchoring the market in volume-based contract pricing with formula adjustments tied to live hog futures. This buyer concentration compresses spot-market premiums and forces branded processors to defend shelf position through promotional allowances in retail channels.
Pricing Analysis
Distributor margin layers in broadline foodservice contracts absorb 12-18 points before product reaches restaurant kitchens, while retail slotting fees and trade promotions claim comparable shares in supermarket channels. Pricing stratifies across premium antibiotic-free tiers, standard USDA-inspected grades, and economy private-label programs, with differentiation driven by certification level and brand heritage. Cost compression in standard-grade bacon intensifies because feed grain volatility transmits directly into live hog economics. Quick-service chains exhibit the highest price sensitivity due to fixed-menu pricing constraints, while specialty retail buyers in coastal metros accept premiums for verified supply chain documentation.
Supply Chain Analysis
Dual-sourcing requirements in retail private-label programs mandate packers qualify backup plants for identical product specifications, stretching quality assurance resources across geographically dispersed facilities. Geographic supply concentration centers on Iowa, Illinois, and North Carolina, where integrated complexes control hog finishing through case-ready packaging. Raw material flows draw from corn and soybean meal inputs, veterinary drug inventories, and specialized curing cultures. Single-source vulnerability in automated belly slicing equipment creates downtime risk when maintenance technician scarcity delays repairs. Distribution runs through temperature-controlled networks serving supermarket refrigerated cases and foodservice redistribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where antibiotic-free and carbon-verified specifications command widening premiums as California and Pacific Northwest natural grocers tighten procurement standards.
For Market Incumbents: Anchor defensive positioning through captive hog supply expansion in Iowa and Illinois to insulate against feed cost volatility and plant downtime risk. Upgrade environmental monitoring infrastructure to meet USDA's revised Listeria monocytogenes compliance guidelines before enforcement deadlines tighten. Consolidate mid-scale competitors unable to fund automated cutting line investments required for throughput thresholds. For New Entrants and Emerging Players: EPA greenhouse gas reporting protocols in the United States open a window for carbon-accounting-verified supply chains to capture premium positioning in coastal metro direct-to-consumer channels. Target specialty bacon subscription models in Pacific Northwest and California natural grocery corridors where conventional broadline distribution loses share. Pursue clean-label fermentation technology partnerships to bypass synthetic nitrite dependencies in natural retail placement. For Investors and Strategic Acquirers: Protein conglomerates with feed-to-package control are the most active acquirer in this space, seeking automated processing assets and coastal distribution access. Five-to-ten-year viability hinges on antibiotic stewardship mandate compliance and carbon disclosure integration. Watch for EPA enforcement timing on livestock greenhouse gas reporting as the inflection indicator for capital allocation toward lower-intensity production systems.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cutting Line Deployment | Tyson Foods and Smithfield Foods compress labor costs while tightening USDA HACCP microbiological control standards. |
| Direct-to-Consumer Channel Launch | Specialty bacon subscriptions bypass supermarket slotting fees in California and Pacific Northwest metro corridors. |
| Carbon Accounting Integration | EPA greenhouse gas reporting protocols create premium positioning for verified lower-intensity pork supply chains. |
| Clean-Label Fermentation Investment | Natural curing cultures replace synthetic nitrites to align with FDA clean-label positioning in natural retail channels. |
| Backward Integration Expansion | Captive hog supply in Iowa and Illinois insulates packers from feed grain cost volatility and regional supply bottlenecks. |
Research Methodology
Direct dialogue with plant operations managers, foodservice procurement directors, retail category buyers, and USDA FSIS compliance officers grounded the qualitative foundation of this study. Secondary validation drew from USDA HACCP guidance documents, EPA greenhouse gas reporting protocols, FDA feed additive approvals, and SEC filings of publicly traded protein processors. Bottom-up volume estimates from plant-level throughput data triangulated against top-down consumer expenditure flows from Bureau of Economic Analysis food spending categories.
Bottom-up modeling tracked product flows across bacon, sausage, ham, and cured meat segments by packaging format and distribution channel. The analytical lens weighted foodservice portion-control contracts, retail case-ready programs, and direct-to-consumer subscription growth patterns throughout the forecast period. CAGRs derived from historical volume trajectories adjusted for regulatory compliance cost escalations and channel mix shifts. Feed grain price volatility curves and antibiotic stewardship mandate timelines served as industry-specific forecast inputs.
Revisions become necessary when EPA enforcement timing on livestock carbon reporting, USDA pathogen reduction standard updates, or feed grain drought cycles materialize outside baseline assumptions. Deviation in antibiotic-free certification adoption rates among major retail chains would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Germany Poultry Meat Market
Meat Products
Vegan Meatball Market
Meat Products
Pork Flavors Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Europe Bacon Market
Meat Products
Organic Halal Meat Market
Meat Products
GCC Edible Meat Market
Meat Products
United States Red Meat Market
Meat Products
Germany Meat Products Market
Meat Products
Global Processed Pork Meat Market
Meat Products
Reduced Fat Meat Market
Meat Products
United States Edible Meat Market
Meat Products
Chilled Meat Market
Meat Products
Global Edible Meat Market
Meat Products
Smokehouse Market
Meat Products
Meat Packaging Market