
 Emulsified Meat Market | 2026-2036
Emulsified Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsified Meat Market Foresight
Modular portion packs and single-serve emulsified meat configurations is recalibrating buyer choice across foodservice and retail channels. Cargill, Incorporated leverages its integrated protein supply chain to dominate North American emulsified beef and pork output. Kerry Group, Inc. differentiates through clean-label stabilizer systems that reduce phosphate dependence in sausage formulations. Hormel Foods anchors its position in shelf-stable spreadable meats through controlled distribution networks.
Emulsified meat refers to finely comminuted muscle tissue homogenized with fat, water, and functional binders to achieve a stable colloidal matrix, typically processed through bowl-chopper or high-shear emulsion systems at temperatures below 15°C to prevent protein denaturation. The primary commercial purpose is to deliver uniform texture, extended shelf life, and cost-efficient protein delivery in ready-to-cook and ready-to-eat formats. Frankfurters represent the mature volume base, while gluten-free and organic formulations capture expanding margin pools as retailers reposition shelf space. Poultry-based emulsified products lead ingredient growth due to cost positioning and perceived health alignment in Western European and North American supermarkets.
USDA inspection mandates and FSIS labeling standards govern emulsified meat production in the United States, while EFSA additive authorizations and EU MDR-related nutritional claims frameworks shape product development across Europe. China's SAMR enforces GB standards for composite meat products, restricting non-meat protein ratios in emulsified sausages sold domestically. Stakeholders must monitor evolving phosphate-limit regulations in multiple jurisdictions and calibrate formulation investments accordingly.
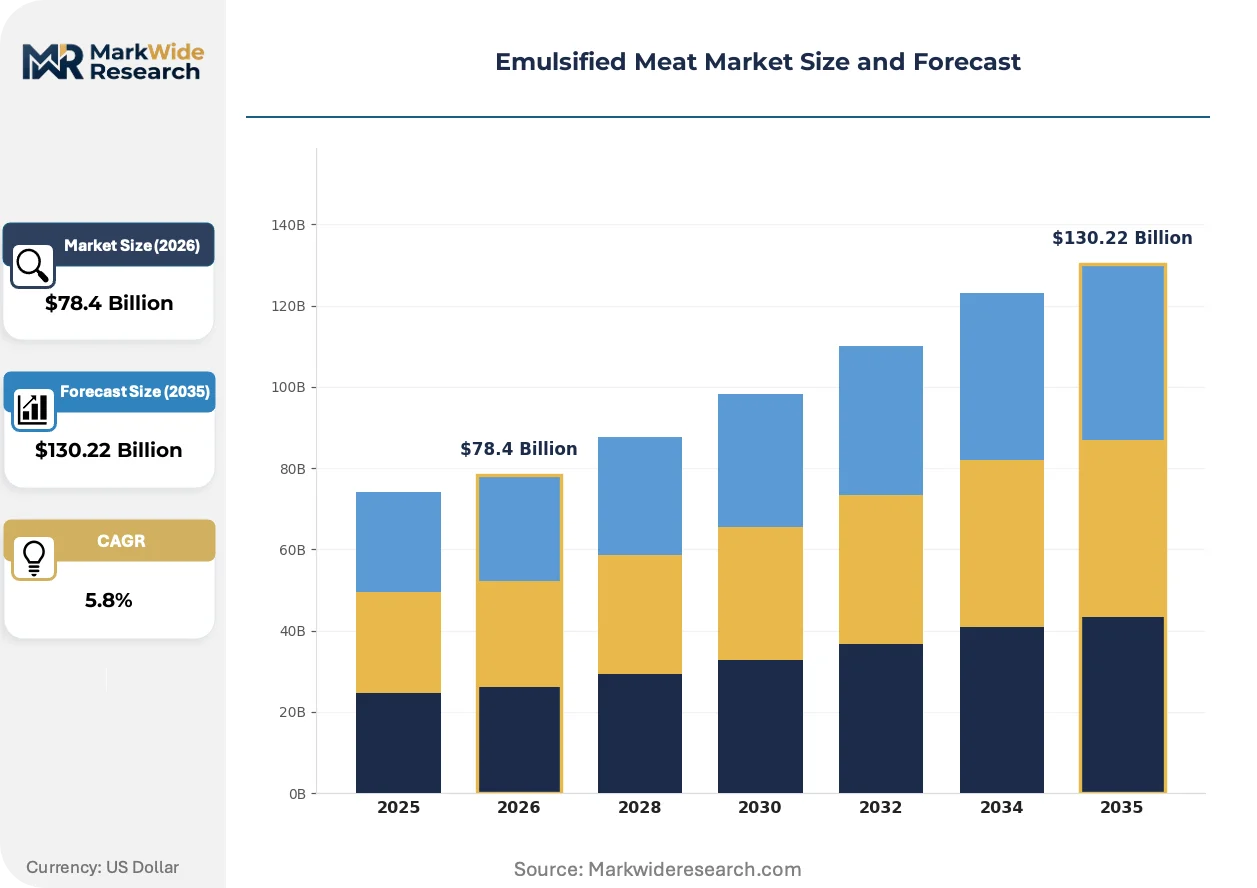
Market Dynamics
Phosphate-limit regulations across the European Union, United States, and Brazil are forcing processors to reformulate stabilizer systems while maintaining emulsion stability and shelf life. This regulatory compression is accelerating R&D investment in clean-label alternatives and reshaping supplier relationships across the value chain.
Growth Catalysts
- Quick-service restaurant expansion:Fast-casual chains in Brazil and Mexico are scaling emulsified meat procurement for processed menu items, driving volume commitments from ANVISA-aligned processors.
- EU MDR nutritional claims frameworks:Protein-content labeling incentives are pushing manufacturers to optimize meat-to-fat ratios in emulsified formulations for premium retail positioning.
- High-shear emulsion systems:Advanced bowl-chopper technology operating below 15°C is reducing protein denaturation rates and improving yield efficiency in commercial production.
Market Restraints
- Pork fat price volatility:Input cost swings in animal fat markets compress margin predictability for standard-grade sausage and pâté production.
- China SAMR disclosure mandates:Tightened food additive transparency rules for emulsified products sold domestically create compliance friction for imported formulations.
- Plant-based protein substitution:Pea and soy protein isolates are capturing shelf space in Western European supermarkets, pressuring conventional emulsified meat volume growth.
Strategic Opportunities
- India FSSAI modernization:Updated standards for processed meat products create entry pathways for export-grade emulsified formulations meeting international safety benchmarks.
- Modular portion-pack formats:Single-serve configurations are opening foodservice channels in Japan and South Korea where convenience-store meal demand concentrates.
- Clean-label stabilizer convergence:Carrageenan and citrus fiber blends are replacing phosphate-dependent systems, enabling premium positioning in EFSA-regulated markets.
Industry Challenges
- Protein functionality expertise gap:Formulation chemists capable of optimizing myosin extraction for emulsion stability remain scarce in emerging production regions.
- Legacy equipment retrofit costs:Cold-chain bowl-chopper upgrades to meet sub-15°C processing standards require substantial capital deployment at mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsified Meat Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pâté, Sausage, Spreadable, Frankfurters Ingredient: Pork, Beef, Poultry, Seafood Formulation: Traditional, Reduced-Fat, Gluten-Free, Organic Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Restaurants |
| Companies Covered | Kerry Group, Inc., Tate & Lyle, Cargill, Incorporated, Johnsonville Sausage, Hormel Foods, ADM, Ingredion Incorporated, Hydrosol GmbH & Co. KG, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsified Meat Market Shifts & Advancements
Processing technology and regulatory disclosure requirements are converging to reshape how emulsified meat products are formulated, labeled, and distributed across foodservice and retail channels.
High-pressure processing (HPP) technology is extending shelf life without thermal degradation of emulsion structure. Ready-to-eat manufacturers in Spain and Italy are adopting HPP lines at accelerating rates. This non-thermal approach is decentralizing cold-chain requirements and enabling regional processors to compete with centralized thermal-processing facilities.
EFSA additive reauthorization timelines are compressing the window for phosphate-dependent formulations in the European Union. Manufacturers must submit revised safety dossiers for existing emulsifier blends. Frankfurter and cooked sausage categories face the steepest compliance burden, with many processors accelerating citrus fiber and seaweed extract trials.
Buyers in Brazil and Mexico are consolidating procurement through direct processor relationships, bypassing traditional distributor intermediaries. Large retail chains now negotiate volume commitments directly with ANVISA-certified production facilities. This disintermediation concentrates negotiating leverage among the largest buyers while squeezing margin capture at mid-tier distribution layers.
Emulsified Meat Market Segmentation
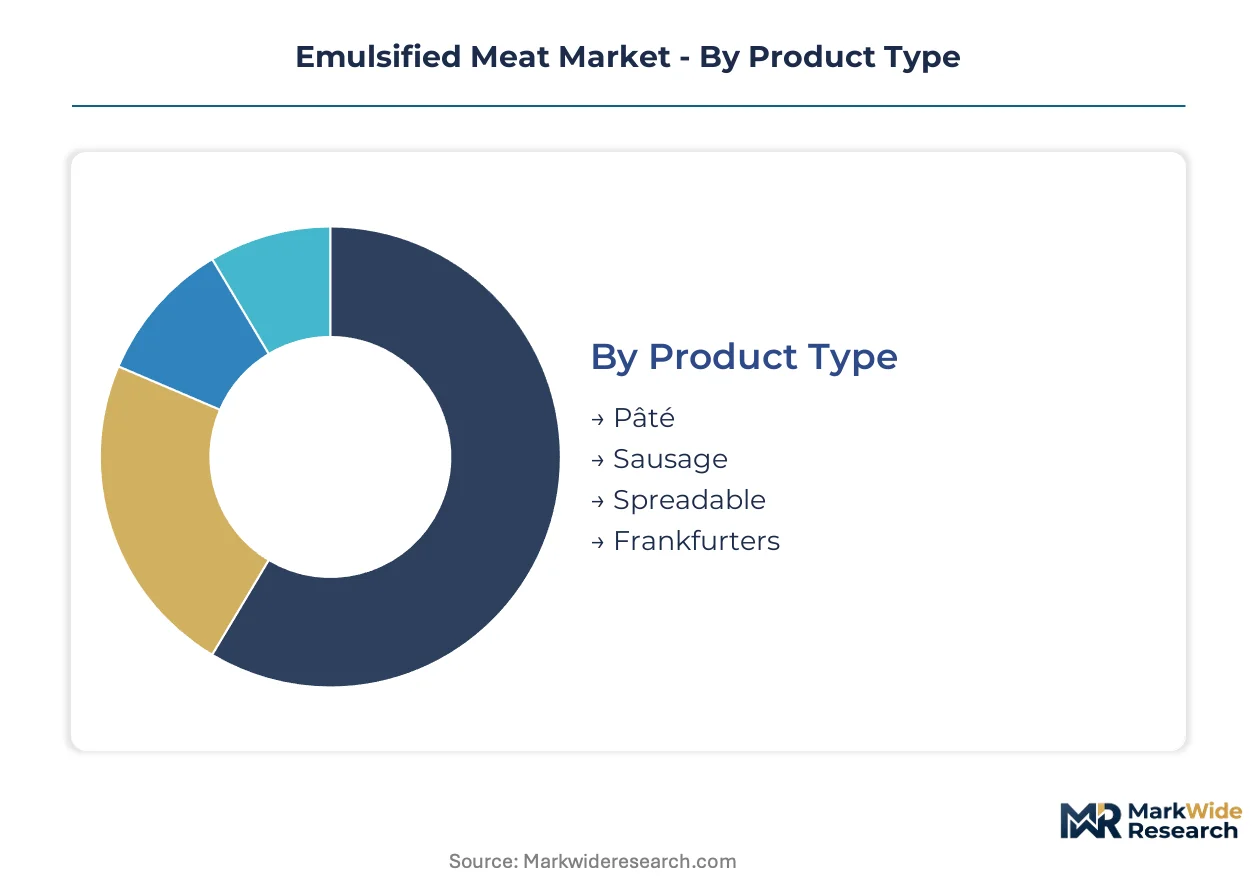
Emulsified meat segmentation reveals divergent profit pools across product formats and distribution channels. Formulation complexity and regulatory compliance costs fragment competitive positioning, while ingredient sourcing constraints reshape volume concentration across geographies.
Product Type:
Buyers differentiate by consumption occasion and shelf-life requirements, driving distinct procurement patterns across retail and foodservice channels.
- Sausage:Cased emulsions dominate volume throughput in Brazil and Mexico, where ANVISA-certified processors supply quick-service restaurant chains with extended shelf-life formats. Cold-chain bowl-chopper investments concentrate in São Paulo and Minas Gerais production corridors to meet export-grade specifications.
- Frankfurters:Fine-emulsion cooked products anchor mature retail volumes in US and German supermarkets, though phosphate-limit regulations under FSIS and EFSA frameworks are forcing stabilizer reformulations. Yield efficiency improvements from sub-15°C processing technology partially offset input cost pressure.
- Pâté:Shelf-stable spreadable formats rely on controlled distribution networks for margin capture.
- Spreadable:Portion-controlled configurations are gaining traction in Japanese convenience-store channels.
Sausage leads volumes today; spreadable formats are gaining share fastest.
Ingredient:
Cost positioning and protein functionality requirements segment procurement strategies across processor scale tiers.
- Poultry:Mechanically separated chicken and turkey deliver cost advantage and perceived health alignment in Western European and North American retail. Myosin extraction efficiency from poultry muscle tissue enables stable emulsion formation with reduced phosphate dependence.
- Pork:Traditional emulsion base faces fat price volatility compressing margin predictability for standard-grade production. Brazilian processors leverage domestic hog supply integration to anchor export competitiveness.
- Beef:Premium positioning in halal-certified markets drives selective demand concentration.
- Seafood:Surimi-derived emulsions capture niche positioning in East Asian foodservice.
Poultry dominates volume expansion; beef maintains premium price realization.
Formulation:
Regulatory disclosure mandates and retailer shelf-space repositioning fragment addressable market boundaries.
- Organic:Certified production commands shelf-space allocation in EFSA-regulated supermarkets, with citrus fiber and carrageenan stabilizer systems replacing phosphate-dependent alternatives. Compliance costs limit viable processor participation to integrated supply chain operators.
- Gluten-Free:Elimination of wheat-based fillers expands addressable consumer base in celiac-sensitive demographics across US and EU markets. Modified starch alternatives from tapioca and potato sources stabilize emulsion matrices without allergen declaration.
- Reduced-Fat:Water-binding technology investments enable meat-to-fat ratio optimization for EU MDR protein-content claims.
- Traditional:Standard formulations retain foodservice volume concentration in price-sensitive emerging markets.
Traditional formulations retain volume leadership; organic is climbing the fastest.
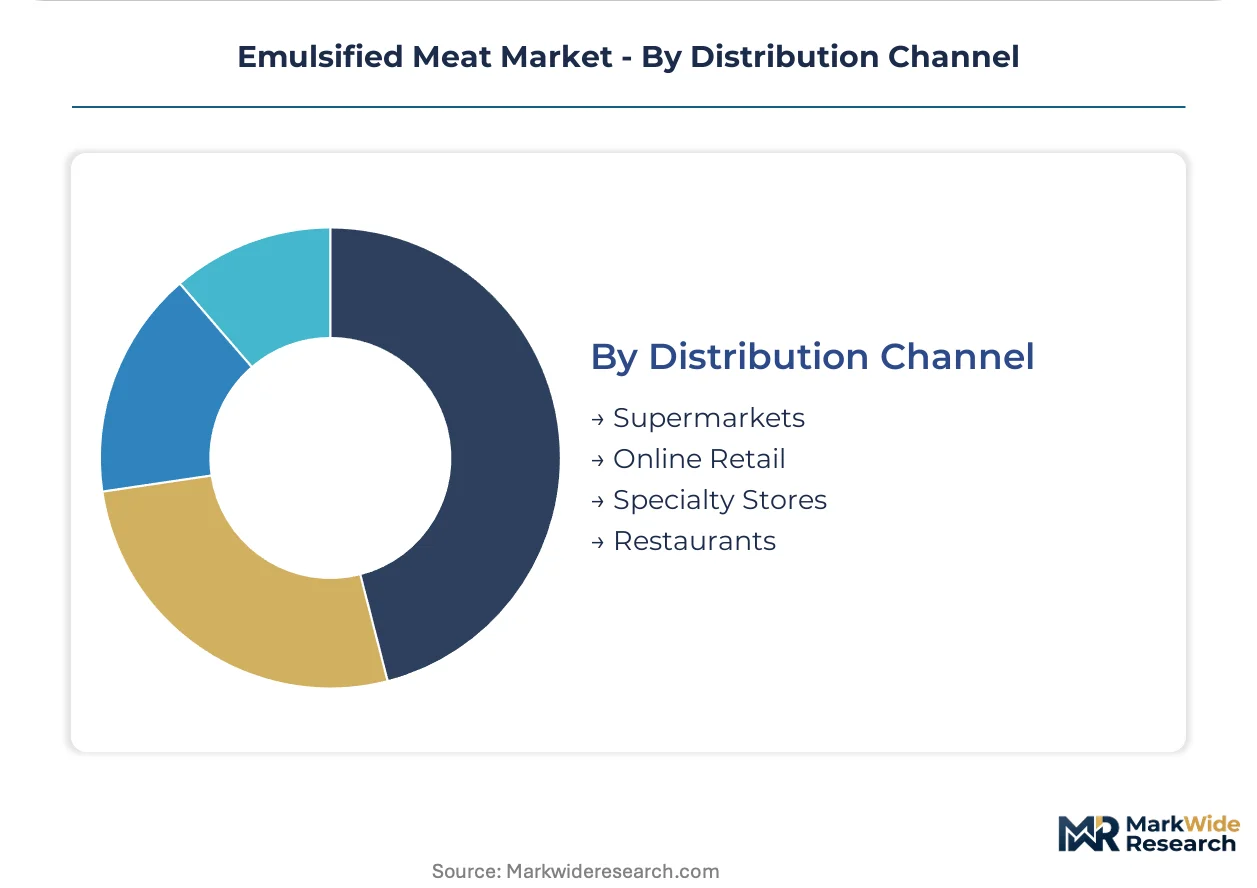
Distribution Channel:
Channel concentration determines margin capture and formulation specification requirements across buyer types.
- Supermarkets:Multi-format retail chains in Germany, France, and the United States negotiate direct processor relationships, bypassing traditional distributor intermediaries. Clean-label positioning and modular portion-pack configurations drive shelf-space competition.
- Restaurants:Quick-service chains in Brazil and Mexico consolidate procurement through volume commitments to ANVISA-aligned production facilities. Emulsified meat inputs for processed menu items require consistent texture specification and cold-chain reliability.
- Online Retail:Direct-to-consumer frozen delivery expands in South Korean and Japanese urban markets.
- Specialty Stores:Artisan positioning supports premium pâté and organic sausage segmentation in France and Italy.
Supermarkets dominate volume throughput; online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial sausage production in the 19th century, establishing emulsion-processing techniques that spread across Europe and the Americas. Today's production geography reflects this lineage while incorporating new regulatory and demand centers across four continents.
United States
Quick-service restaurant chains drive procurement volumes for processed menu items, particularly in the Southeast and Southwest corridors. USDA inspection mandates and FSIS labeling standards govern all commercial production, with phosphate-limit regulations forcing stabilizer reformulations. Cold-chain bowl-chopper investments concentrate in the Midwest protein-processing belt around Chicago and Omaha.
Germany
Fine-emulsion cooked products anchor mature retail volumes in national supermarket chains, though EU MDR nutritional claims frameworks are reshaping formulation priorities. EFSA additive reauthorization timelines compress the window for phosphate-dependent systems. Production corridors in Bavaria and North Rhine-Westphalia host the densest concentration of bowl-chopper capacity serving export markets.
Brazil
ANVISA-aligned processors scale capacity for export-grade sausage and pâté production, leveraging integrated hog supply chains for cost positioning. The regulator enforces disclosure standards aligned with Mercosur trade protocols. São Paulo and Minas Gerais production corridors dominate volume throughput for quick-service restaurant supply across Latin America.
China
Domestic demand concentrates in tier-one cities for premium emulsified sausage formats, though SAMR tightened food additive disclosure rules create compliance friction for imported formulations. GB standards for composite meat products restrict non-meat protein ratios. Yangtze River Delta processing clusters around Shanghai upgrade cold-chain infrastructure to meet sub-15°C processing standards.
Japan
Convenience-store meal demand concentrates procurement for modular portion-pack configurations in urban corridors. METI standards govern processed meat safety benchmarks. Kanto and Kansai production basins around Tokyo and Osaka deploy high-shear emulsion systems for yield efficiency in premium retail positioning.
Emulsified Meat Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory compliance capabilities. The vendor base stratifies into three tiers: integrated protein suppliers controlling upstream raw material flows, specialty ingredient houses commanding clean-label stabilizer technology, and mid-scale processors competing on volume throughput. Consolidation pressures concentrate among mid-tier distributors as large buyers bypass traditional intermediaries. Two dominant competitive moves reshape positioning: backward integration into captive protein supply and technology licensing partnerships for phosphate-replacement systems.
Among integrated protein suppliers, Cargill, Incorporated and Hormel Foods occupy positions defined by supply chain control and shelf-stable distribution networks respectively. Kerry Group, Inc. exemplifies the specialty-ingredient archetype, anchoring clean-label formulation capabilities that reduce phosphate dependence. These three entities represent distinct strategic vectors—upstream raw material dominance, controlled distribution for spreadable formats, and functional ingredient technology—rather than direct segment overlap.
| Leading Market Players |
|---|
| Kerry Group, Inc. |
| Tate & Lyle |
| Cargill, Incorporated |
| Johnsonville Sausage |
| Hormel Foods |
| ADM |
| Ingredion Incorporated |
| Hydrosol GmbH & Co. KG |
| DuPont |
| Others |
Supply & Pricing Matrix
Quick-service restaurant procurement consolidation across Brazil and Mexico is forcing mid-scale processors to absorb cold-chain bowl-chopper upgrade costs while ANVISA-aligned facilities extract volume discounts through direct contracting. This buyer-side concentration compresses margin capture at distribution layers and redirects pricing power toward integrated protein suppliers with captive hog supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs emulsified meat transactions. Premium tiers attach to organic certification and phosphate-free formulations targeting EFSA-regulated supermarkets; standard grades serve quick-service restaurant chains through contract-based long-term offtake; economy positioning captures price-sensitive foodservice buyers in emerging markets. Cost compression in standard-grade sausage runs through pork fat price volatility and legacy equipment retrofit requirements. Quick-service chains exhibit highest price sensitivity due to volume procurement leverage, while specialty retailers in France and Italy accept premium positioning for artisan pâté formats.
Supply Chain Analysis
Animal fat and mechanically separated poultry supply rests on integrated protein operations in the United States, Brazil, and Germany. Myosin-extraction chemistry, cold-chain logistics infrastructure, and phosphate-replacement stabilizer systems constitute critical input dependencies. Single-source vulnerability concentrates in specialty clean-label ingredient houses controlling citrus fiber and carrageenan formulations. Distribution runs through direct processor relationships with large retail chains, bypassing traditional distributor intermediaries in Brazil and Mexico while controlled networks anchor shelf-stable spreadable formats in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in emulsified meat hinges on phosphate-replacement formulation premiums and yield efficiency gains from sub-15°C processing technology adoption.
For Market Incumbents: Acquire captive hog supply operations in Brazil's Minas Gerais corridor to anchor cost positioning against pork fat volatility. Secure ANVISA certification for export-grade production capacity serving quick-service restaurant procurement consolidation in Latin America. Defend against plant-based protein substitution by accelerating citrus fiber and seaweed extract trials for clean-label positioning in EFSA-regulated markets. For New Entrants and Emerging Players: Enter via modular portion-pack configurations targeting Japanese convenience-store meal demand in Kanto and Kansai urban corridors. Exploit underdeveloped clean-label stabilizer supply in India as FSSAI modernization creates entry pathways for export-grade formulations. Pursue technology licensing partnerships with established phosphate-replacement system developers rather than proprietary R&D investment. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty ingredient houses commanding functional stabilizer technology for phosphate-dependent formulation transitions. Five-to-ten year viability favors operators with backward integration into protein supply and regulatory compliance capabilities across multiple jurisdictions. Watch EFSA additive reauthorization timelines as inflection indicator for accelerated citrus fiber adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hog Supply | Cargill's protein supply chain control anchors cost predictability against Brazilian ANVISA export requirements. |
| Clean-Label Stabilizer Licensing | Kerry Group's phosphate-replacement technology enables premium positioning under tightening EFSA disclosure mandates. |
| Cold-Chain Equipment Upgrade | Sub-15°C bowl-chopper deployment in São Paulo corridors meets export-grade texture specifications for quick-service procurement. |
| Direct Retail Procurement Relationships | Bypassing distributor intermediaries concentrates negotiating leverage with German and French supermarket chains. |
| Modular Portion-Pack Launch | Single-serve configurations capture Japanese convenience-store channel growth in Tokyo and Osaka metropolitan areas. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged protein processing executives, regulatory affairs specialists at ANVISA and EFSA, quick-service restaurant procurement directors, and cold-chain logistics operators. Secondary validation drew from USDA FSIS inspection records, SAMR GB standard filings, customs and trade data for emulsified meat exports, and SEC 10-K disclosures from integrated protein suppliers. Bottom-up volume modeling and top-down market sizing triangulated across these inputs to produce segment-level estimates.
Historical reference periods anchored the projection horizon to established production and consumption baselines in mature markets. Segmentation modeling spanned product type, protein source, formulation category, and distribution channel dimensions across the analysis window. CAGRs were derived from fitted growth curves incorporating regulatory phase-in timelines, equipment replacement cycles, and buyer consolidation patterns. Forecast inputs included phosphate-limit regulation enforcement schedules and high-shear emulsion system adoption rates by processor scale tier.
Inputs from regulatory filing databases and processor capacity announcements were available through the study window; gaps in real-time procurement contract terms introduce uncertainty bands around foodservice volume estimates. Forecasts reflect assumptions regarding EFSA additive reauthorization outcomes and ANVISA enforcement consistency. A small set of named triggers—EFSA citrus fiber approval timelines, SAMR disclosure mandate expansion, and Brazil quick-service chain procurement consolidation rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Grassfed Jerky Market
Meat Products
Smokehouse Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Organic Lamb Market
Meat Products
Organic Chicken Market
Meat Products
Germany Meat Products Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
Beef Bouillon Market
Meat Products
Organic Beef Meat Market
Meat Products
India Animal Protein Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
North America Poultry Meat Market
Meat Products
Organic Meat Market
Meat Products
Blended Meat Market
Meat Products
United States Poultry Meat Market
Meat Products
Europe Poultry Meat Market