
 Helicobacter Pylori Testing Market | 2026-2036
Helicobacter Pylori Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Helicobacter Pylori Testing Market Intelligence
East Asian diagnostic reagent production is hardening as regional manufacturers scale polymerase chain reaction enzyme output. Thermo Fisher Scientific leverages its Taq polymerase supply chain to sustain cost leadership in molecular H. pylori assays. Bio-Rad Laboratories anchors its position through droplet digital PCR platforms that compete on sensitivity thresholds for eradication confirmation testing.
Helicobacter pylori testing encompasses laboratory and point-of-care methods that detect active or past infection through antibody, antigen, urease, or nucleic acid targets, with urea breath tests requiring carbon-13 or carbon-14 labeled substrates and quantitative mass spectrometry or infrared spectroscopy readouts to measure bacterial urease activity. The primary purpose is to diagnose peptic ulcer disease, guide eradication therapy, and stratify gastric cancer risk in screened populations. Serology retains volume leadership in emerging markets where infrastructure limits breath or stool processing, while PCR-based techniques capture the fastest expansion as multiplex panels simultaneously genotype clarithromycin and levofloxacin resistance mutations. Endoscopic biopsy maintains margin concentration in oncology workflows where histopathology integrates H. pylori status with mucosal staging.
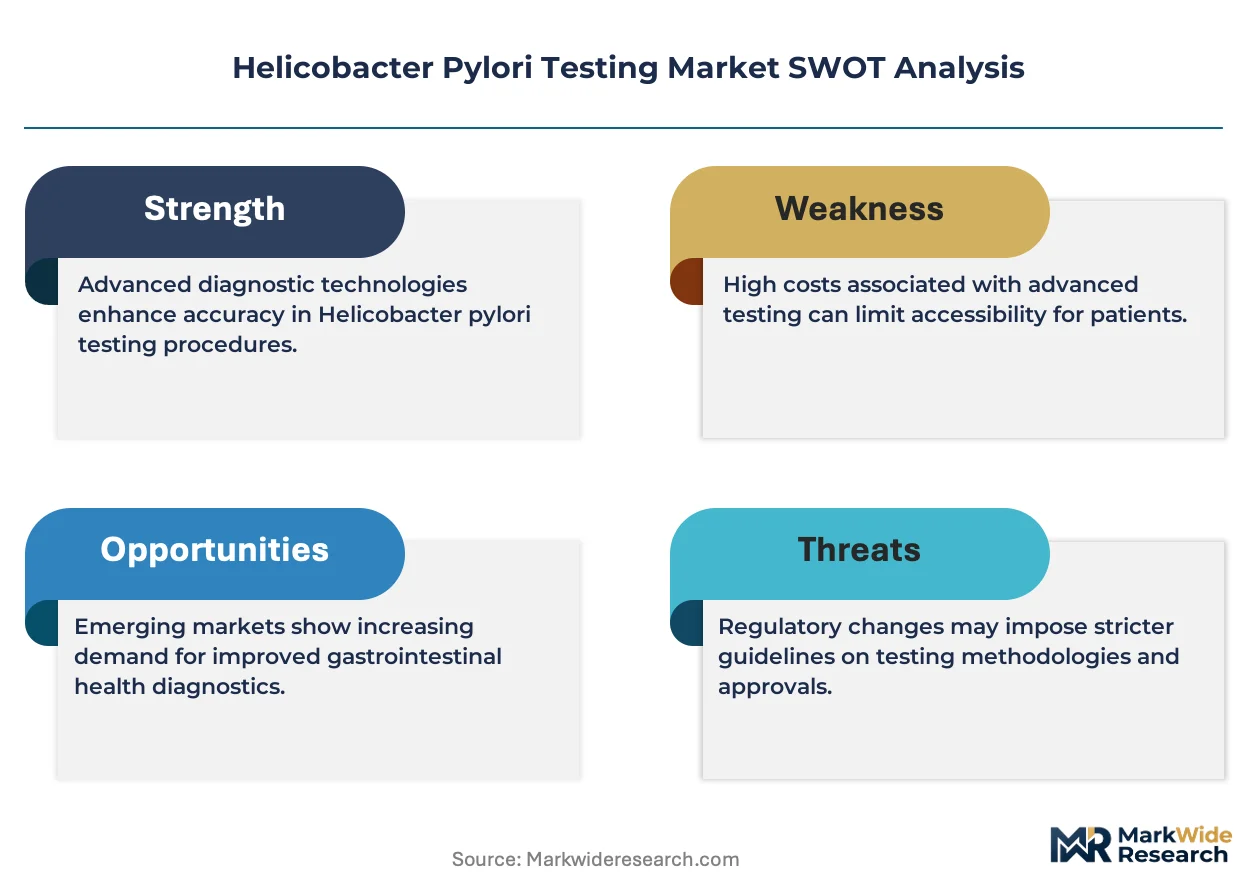
The FDA's 510(k) pathway and Clinical Laboratory Improvement Amendments govern U.S. assay commercialization and laboratory-developed test deployment, while the EMA's In Vitro Diagnostic Regulation imposes stricter post-market surveillance and performance documentation on European manufacturers. Japan's PMDA maintains distinct urea breath test reimbursement categories that shape product form factor requirements. Stakeholders must monitor how WHO Essential Diagnostics List inclusion criteria and national gastric cancer screening mandates redirect procurement volumes between serology, breath testing, and molecular platforms.
Market Dynamics
Multiplex molecular panels are compressing the diagnostic pathway by simultaneously detecting H. pylori presence and clarithromycin resistance mutations within a single workflow, forcing laboratories to retire standalone serology and urease-based methods that cannot deliver comparable turnaround times.
Growth Catalysts
- Gastric cancer screening mandates:Japan's national screening program and South Korea's biennial endoscopic surveillance protocols generate recurring demand for non-invasive H. pylori testing prior to referral.
- FDA's streamlined 510(k) pathway for stool antigen assays:Accelerated premarket review timelines enable diagnostic manufacturers to commercialize novel immunoassay formats faster than molecular alternatives.
- PCR enzyme supply chain regionalization:East Asian reagent producers are scaling thermostable polymerase output, reducing import dependency for molecular assay developers in China and India.
Market Restraints
- Carbon-13 isotope supply concentration:Breath test substrate production clusters among three European radiochemical suppliers, exposing assay manufacturers to price volatility and allocation risk.
- EMA's In Vitro Diagnostic Regulation documentation burden:Stricter post-market surveillance and performance validation requirements extend time-to-market for European manufacturers by 12-18 months relative to legacy frameworks.
- Serology substitution by antigen detection:Active infection confirmation tests are displacing antibody-based methods in reimbursed screening workflows, eroding volume in markets where serology previously dominated.
Strategic Opportunities
- Point-of-care molecular platforms:Battery-operated PCR devices are penetrating rural clinics in India and Southeast Asia where laboratory infrastructure cannot support centralized testing.
- Antibiotic stewardship integration:Resistance-guided therapy protocols in Germany and the Netherlands create procurement pull for genotyping-capable panels that inform clarithromycin, metronidazole, and levofloxacin selection.
- WHO Essential Diagnostics List inclusion:Formal classification of H. pylori testing as essential would unlock Global Fund and national health ministry procurement channels in low-income markets currently reliant on donor-funded serology.
Industry Challenges
- Clinical laboratory scientist training gaps:Molecular assay adoption outpaces accredited training program output in Brazil and Mexico, creating workflow bottlenecks for multiplex panel deployment.
- Legacy LIS integration complexity:Hospital information systems in the United States and United Kingdom require middleware development to ingest resistance mutation reports from novel PCR platforms, delaying go-live timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicobacter Pylori Testing Market |
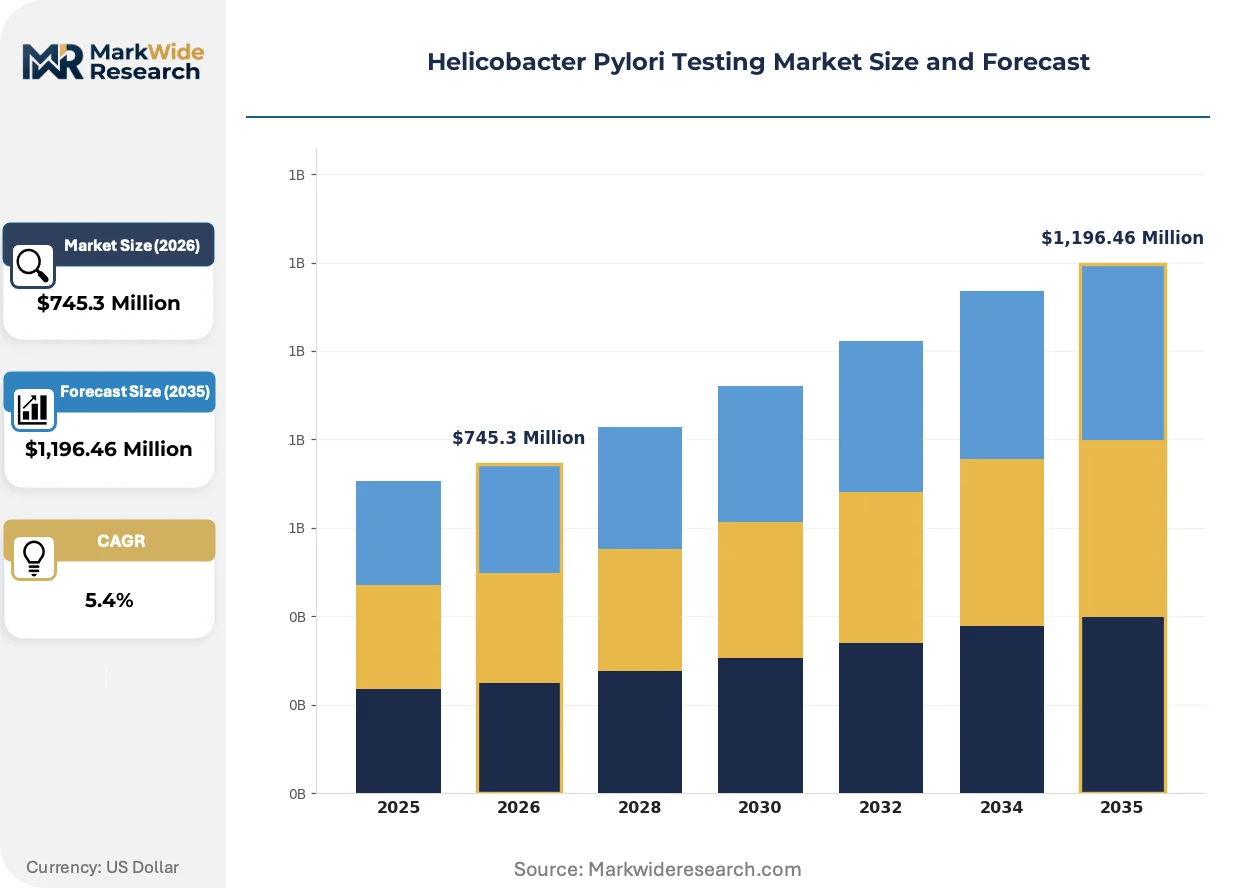
| Market Size in 2026 | $745.3 Million |
| Market Size in 2035 | $1,196.46 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Serology, Urea Breath Test, Stool Antigen Test, Endoscopic Biopsy Technique: Culture, PCR, Immunoassay, Histology End User: Hospitals, Diagnostic Laboratories, Research Institutions, Outpatient Clinics Sample Type: Blood, Stool, Gastric Biopsy, Breath Sample |
| Companies Covered | Thermo Fisher Scientific, Biohit Oyj, Quest Diagnostics Incorporated, Meridian Bioscience, Bio-Rad Laboratories, F. Hoffmann-La Roche Ltd, bioMérieux SA, Abbott Laboratories, Certest Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicobacter Pylori Testing Market Strategic Shifts & Innovations
Droplet digital PCR platforms are reshaping eradication confirmation testing by quantifying low-abundance bacterial DNA below conventional qPCR thresholds, while regulatory harmonization efforts across North America, Europe, and East Asia are compressing validation protocol divergence that previously fragmented product development roadmaps.
Digital PCR technology is consolidating the high-sensitivity segment of the H. pylori testing market by enabling absolute quantification without standard curve dependency. Oncology reference laboratories in Germany, Japan, and the United States are adopting these platforms for post-treatment monitoring where residual bacterial load must be distinguished from treatment failure. The technology is consolidating competitive positioning around sensitivity specifications rather than throughput metrics, compressing price premiums for conventional qPCR systems in this application niche.
The EMA's In Vitro Diagnostic Regulation is imposing unified post-market surveillance and clinical evidence requirements across European member states. Manufacturers must now maintain systematic performance monitoring and periodic safety reporting that previously varied by notified body jurisdiction. Small and mid-sized diagnostic firms in Italy and Spain are responding by consolidating regulatory affairs functions and outsourcing clinical validation to contract research organizations with pan-European investigator networks.
Hospital procurement departments are unbundling instrument placement contracts from reagent supply agreements that previously locked laboratories into single-vendor ecosystems. Academic medical centers in the United States and university hospitals in France are negotiating standalone pricing for molecular platforms while sourcing compatible reagents from third-party manufacturers. This shift is most visible in California and Île-de-France, where consolidated health systems have sufficient volume to justify multi-vendor standardization and internal assay verification laboratories.
Helicobacter Pylori Testing Market Segmentation
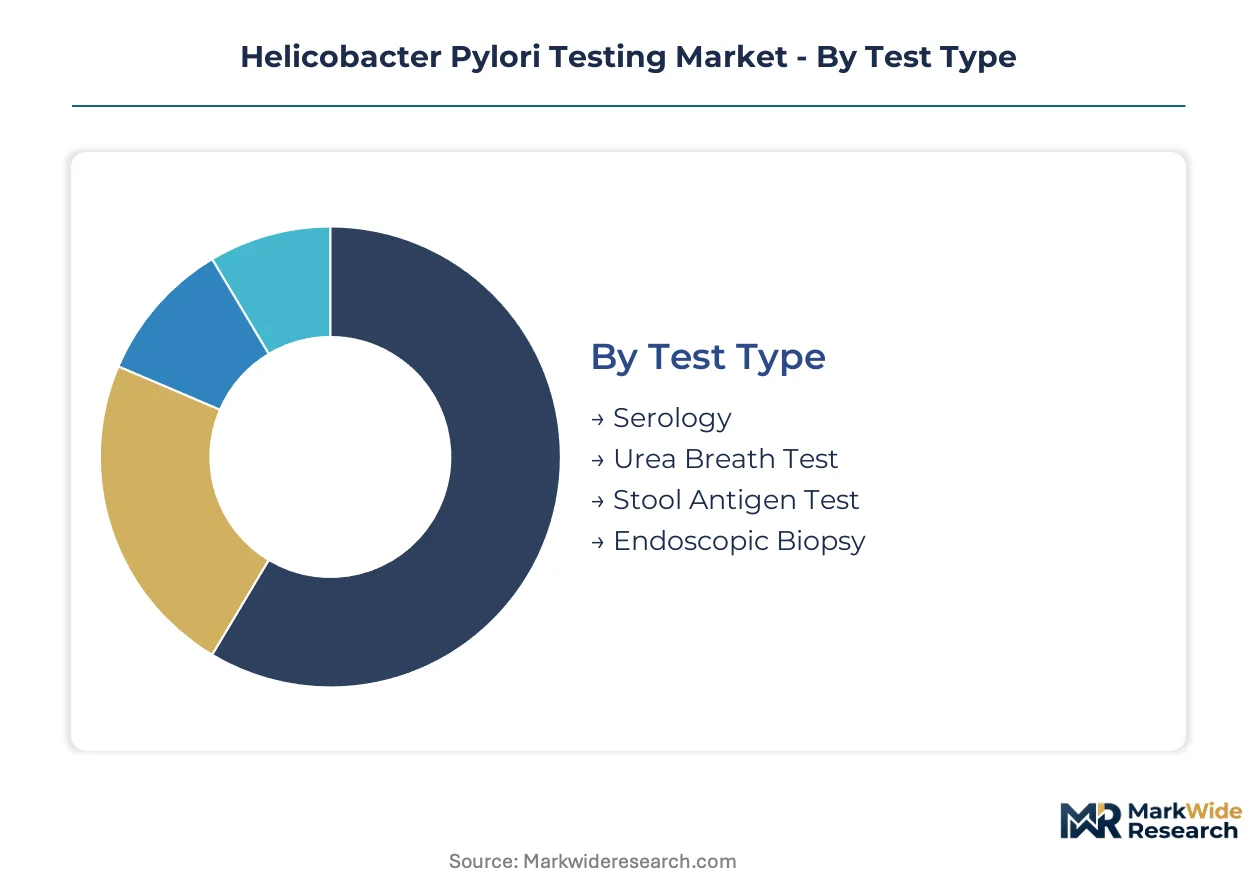
Test format selection in the Helicobacter pylori testing market hinges on clinical workflow requirements, infrastructure availability, and reimbursement pathways. Laboratories weigh sensitivity thresholds against turnaround times when configuring testing menus across screening, diagnosis, and eradication confirmation use cases.
Test Type:
Antibody detection versus active infection confirmation defines the core technology axis for clinical decision-making.
- Serology:Antibody detection assays identify past or present infection through serum IgG response. Volume concentrates in India and Brazil where point-of-care infrastructure favors capillary blood collection over cold-chain specimen transport.
- Urea Breath Test:Carbon-13 or carbon-14 labeled urea substrates measure bacterial urease activity via breath sample analysis. Japan's PMDA maintains distinct reimbursement categories that shape product form factor requirements for this modality.
- Stool Antigen Test:Fecal specimen immunoassays detect active infection with non-invasive collection. FDA streamlined 510(k) pathways are accelerating commercialization timelines for novel assay formats.
- Endoscopic Biopsy:Tissue sampling enables histopathological correlation with mucosal staging in oncology workflows. Germany's university hospitals anchor demand where gastric cancer screening integrates H. pylori status with tumor board protocols.
Serology leads on scale; stool antigen testing leads on momentum.
Technique:
Methodological sophistication determines laboratory capital requirements and personnel training intensity.
- PCR:Nucleic acid amplification enables simultaneous detection and clarithromycin resistance genotyping. East Asian reagent producers are scaling thermostable polymerase output to reduce import dependency for assay developers.
- Immunoassay:Antibody-antigen binding reactions power both serology and stool antigen platforms. Automated chemiluminescence analyzers in United States health systems are displacing manual ELISA workflows.
- Culture:Bacterial isolation from gastric biopsies supports antimicrobial susceptibility testing. France's academic medical centers maintain reference laboratory capacity for phenotypic resistance confirmation.
- Histology:Tissue staining integrates H. pylori visualization with dysplasia grading. South Korea's biennial endoscopic surveillance protocols generate recurring specimen volumes for pathology laboratories.
Immunoassay leads on installed base; PCR leads on capability expansion.
End User:
Site-of-care economics and reimbursement rates fragment procurement authority across healthcare settings.
- Diagnostic Laboratories:Centralized processing hubs aggregate specimens from multiple collection points. California and Île-de-France health systems are unbundling instrument contracts from reagent supply agreements.
- Hospitals:Inpatient and emergency departments require rapid turnaround for ulcer bleeding presentations. Japan's gastric cancer screening mandates drive routine surveillance testing through hospital-affiliated clinics.
- Outpatient Clinics:Primary care settings favor point-of-care platforms with immediate result reporting. India's rural health sub-centers are deploying battery-operated molecular devices where laboratory infrastructure is absent.
- Research Institutions:Academic centers validate novel biomarkers and resistance mutation panels. Netherlands antibiotic stewardship programs create procurement pull for genotyping-capable research assays.
Diagnostic laboratories lead on specimen volume; outpatient clinics lead on access expansion.
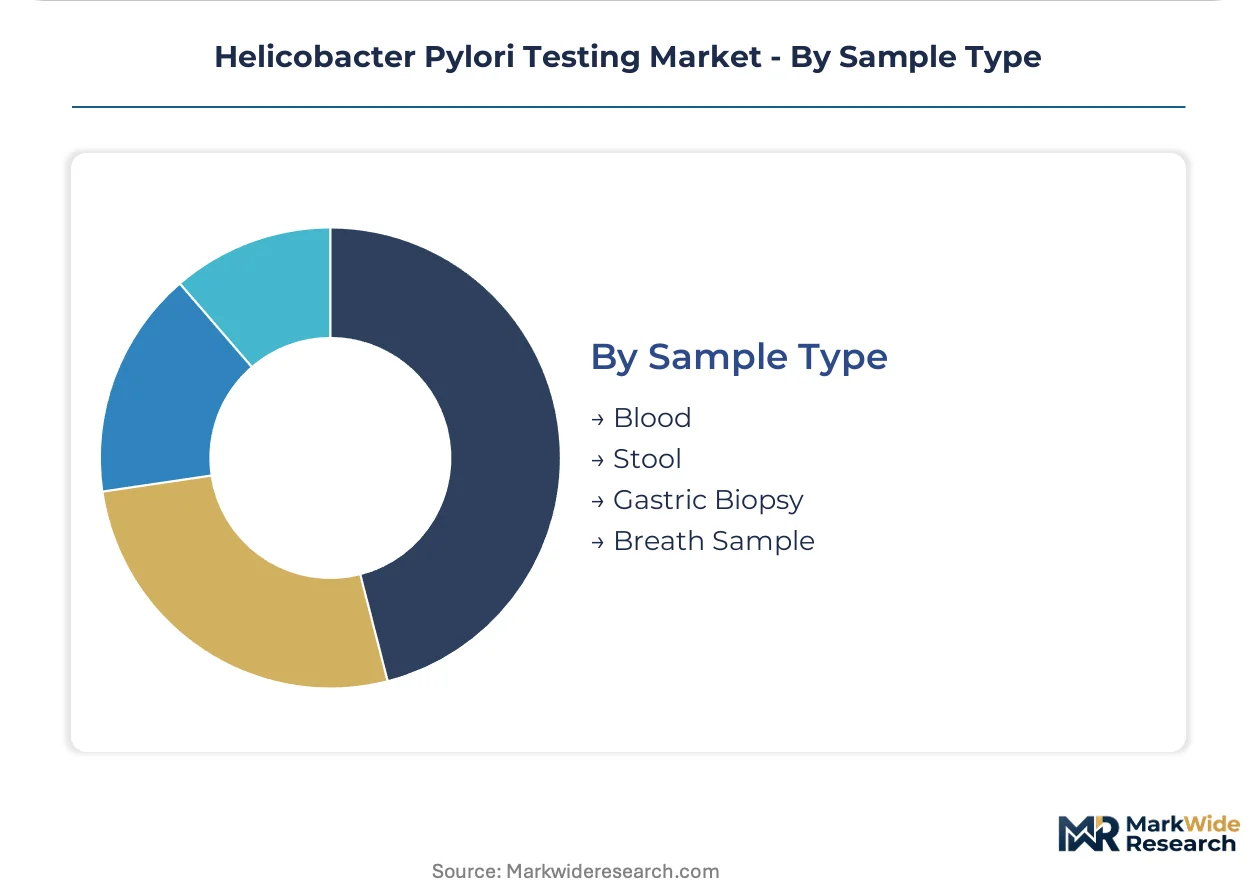
Sample Type:
Collection logistics and patient compliance shape test selection in population screening programs.
- Breath Sample:Non-invasive collection with immediate processing potential. Carbon-13 isotope supply concentrates among three European radiochemical suppliers, exposing manufacturers to allocation risk.
- Stool:Home collection kits expand screening reach in community-based programs. EMA's In Vitro Diagnostic Regulation imposes documentation burdens that extend time-to-market for European manufacturers.
- Blood:Capillary and venous collection supports both serology and molecular plasma assays. Brazil's clinical laboratory scientist training gaps create workflow bottlenecks for specimen processing.
- Gastric Biopsy:Endoscopic acquisition enables histopathological and microbiological correlation. United States hospital information systems require middleware development to integrate resistance reports from molecular platforms.
Blood collection leads on infrastructure ubiquity; breath sampling leads on patient acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's gastric cancer screening infrastructure processes triple the per-capita H. pylori tests of the United States, while Germany's antibiotic stewardship protocols drive resistance-guided therapy adoption faster than Southern European markets.
United States
Hospital-affiliated clinics in California and Texas generate substantial specimen volumes for centralized laboratory processing. FDA's streamlined 510(k) pathway accelerates stool antigen assay commercialization timelines relative to molecular alternatives. The Greater Boston corridor anchors reference laboratory capacity for droplet digital PCR eradication confirmation testing.
Germany
University hospitals in Bavaria and North Rhine-Westphalia integrate H. pylori status with tumor board protocols for gastric cancer staging. EMA's In Vitro Diagnostic Regulation imposes unified post-market surveillance requirements that extend validation timelines. The Rhine-Main cluster concentrates procurement authority for multiplex resistance panels among consolidated health systems.
Japan
PMDA maintains distinct reimbursement categories for urea breath test form factors that shape manufacturer product specifications. National screening program mandates drive routine surveillance testing through prefectural health centers. The Kanto region around Tokyo anchors diagnostic reagent production scale for regional self-sufficiency.
China
Domestic polymerase chain reaction enzyme manufacturers in the Yangtze River Delta reduce import dependency for molecular assay developers. NMPA regulatory pathways prioritize localized clinical validation data for commercial approval. Guangdong province's diagnostic device clusters scale point-of-care platform production for rural clinic deployment.
India
Rural health sub-centers in Maharashtra and Karnataka deploy battery-operated molecular devices where laboratory infrastructure remains absent. CDSCO streamlined pathways for IVD imports accelerate test menu expansion in private diagnostic chains. The Delhi-NCR corridor concentrates hospital procurement authority for resistance-guided therapy panels.
Helicobacter Pylori Testing Market Key Industry Players
United States producers anchor one tier; European specialists hold differentiated positions in oncology-integrated workflows. The vendor base stratifies across three tiers: diversified life science conglomerates with molecular platform ecosystems, mid-cap diagnostic firms with region-specific assay portfolios, and emerging point-of-care device manufacturers. Consolidation pressure concentrates among mid-tier players facing EMA documentation burdens. Dominant competitive moves include strategic partnerships for resistance panel development and geographic licensing agreements for breath test substrate supply.
Within the diversified conglomerate tier, Thermo Fisher Scientific and bioMérieux SA represent contrasting geographic anchors for molecular assay supply chains. Thermo Fisher leverages its polymerase enzyme manufacturing position to sustain cost structures in nucleic acid amplification testing. Bio-Rad Laboratories occupies a specialized position in high-sensitivity quantification platforms. Quest Diagnostics Incorporated exemplifies the integrated laboratory services archetype, combining specimen processing scale with proprietary assay development capacity.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Biohit Oyj |
| Quest Diagnostics Incorporated |
| Meridian Bioscience |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche Ltd |
| bioMérieux SA |
| Abbott Laboratories |
| Certest Biotec |
| Others |
Cost & Logistics Intelligence
Multiplex molecular panel premiumization against serology commoditization bifurcates procurement economics across the H. pylori testing landscape, with resistance-genotyping capabilities commanding three-to-five-fold reagent premiums while antibody-based methods face volume erosion in reimbursed workflows. This divergence concentrates margin capture among PCR enzyme manufacturers with captive polymerase supply chains, while breath test substrate scarcity from European radiochemical suppliers transmits cost volatility downstream to assay developers dependent on carbon-13 isotope allocation.
Pricing Analysis
Distributor margins on molecular platforms compress 15-25 points below immunoassay systems due to direct manufacturer-hospital contracting for high-throughput installations. Pricing stratifies across premium, standard, and economy tiers: droplet digital PCR systems anchor premium positioning through absolute quantification sensitivity, automated chemiluminescence analyzers occupy standard workflows, and manual ELISA kits serve economy procurement in emerging markets. Cost compression in serology intensifies as antigen detection displaces antibody methods in Japan and South Korea screening programs. Diagnostic laboratories in California and Île-de-France exhibit lowest price sensitivity for resistance-guided therapy panels, while India's rural health sub-centers prioritize per-test economics over sensitivity specifications.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States consolidate finished instrument inventory for just-in-time hospital deployment, with hub-and-spoke patterns radiating reagent cold-chain logistics to satellite laboratories. East Asian thermostable polymerase production in the Yangtze River Delta and Kanto region reduces import dependency for molecular assay developers, while carbon-13 isotope supply clusters among three European radiochemical suppliers exposes breath test manufacturers to allocation risk. Raw material dependencies center on recombinant polymerase enzymes, monoclonal antibody cell lines, and isotopically labeled urea substrates. Distribution runs through diagnostic laboratory GPO contracts in the United States and consolidated health system procurement in Germany, with single-source vulnerability concentrated in isotope supply and PCR enzyme master cell banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The H. pylori testing market compounds steadily as gastric cancer screening mandates in East Asia institutionalize recurring surveillance demand, embedding molecular and non-invasive modalities into national health infrastructure with limited cyclical exposure.
For Market Incumbents: To counter point-of-care molecular device penetration from emerging Asian manufacturers, Thermo Fisher Scientific and bioMérieux SA should deepen backward integration into thermostable polymerase production and secure exclusive carbon-13 isotope offtake agreements with European radiochemical suppliers. Channel control through multi-year reagent supply contracts with Japan's prefectural health centers and Germany's university hospital networks preserves installed base loyalty against unbundled procurement trends. For New Entrants and Emerging Players: The mid-tier pricing gap between premium digital PCR systems and economy serology kits creates entry space for battery-operated molecular platforms targeting India's rural health sub-centers and Southeast Asian primary care clinics. Maharashtra and Karnataka's laboratory infrastructure deficits represent the most penetrable geography, with antibiotic stewardship protocol adoption in the Netherlands and Germany offering parallel pull for resistance-genotyping assays. Go-to-market execution should prioritize CDSCO streamlined import pathways and localized clinical validation partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA In Vitro Diagnostic Regulation documentation burdens strain mid-cap diagnostic firms with limited regulatory affairs scale. The 5-10 year viability window favors platforms with dual-menu capability spanning screening and eradication confirmation, capturing revenue across the full patient journey. Acquisition targets should display installed base density in Japan's gastric cancer screening infrastructure or proprietary droplet digital PCR quantification IP. The signal to watch is WHO Essential Diagnostics List inclusion, which would unlock Global Fund procurement channels and redirect volume toward molecular platforms in low-income markets currently donor-dependent on serology.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Resistance Panel Development | Simultaneous H. pylori detection and clarithromycin genotyping compresses diagnostic pathways in Germany's stewardship programs. |
| Point-of-Care Molecular Platform Launch | Battery-operated PCR devices penetrate India's rural sub-centers where laboratory infrastructure remains absent. |
| Carbon-13 Isotope Supply Agreement | Long-term offtake contracts with European radiochemical suppliers mitigate allocation risk for breath test manufacturers. |
| CE Marking Pathway Acceleration | Streamlined EMA In Vitro Diagnostic Regulation compliance reduces time-to-market for European molecular assay commercialization. |
| Hospital System Partnership | Integrated laboratory services contracts with California and Île-de-France health systems secure high-throughput specimen volumes. |
Research Approach
Bottom-up diagnostic laboratory and hospital procurement modeling reconciled against top-down reagent production and instrument shipment tracking forms the analytical core of this study. Primary interviews with clinical laboratory directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, PMDA reimbursement category determinations, and hospital procurement database extracts. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified demand and supply-side estimates.
Input-output matrices map test volume flows across serology, urea breath, stool antigen, endoscopic biopsy, and molecular modalities against technique-specific reagent consumption rates and instrument placement cycles throughout the projection horizon. Segmentation dimensions include test type, technique sophistication, end-user setting, sample collection logistics, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to screening program enrollment trajectories and resistance-guided therapy protocol adoption rates, with polymerase chain reaction enzyme supply scaling and carbon-13 isotope production capacity serving as industry-specific forecast constraints.
Caveats apply where WHO Essential Diagnostics List reclassification, EMA post-market surveillance enforcement intensity, or carbon-13 supplier consolidation could materially shift the outlook for molecular versus non-invasive test modality shares. Forecasts reflect documented assumptions regarding gastric cancer screening program expansion timelines and antibiotic stewardship protocol penetration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
At-Home Testing Market
Testing Services
Point of Care Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Infusion Toxicology Services Market
Testing Services
INR Test Meter Market
Testing Services
Outsourced Testing Services Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
US Viral Clearance Market