
 Trichomonas Rapid Testing Market | 2026-2036
Trichomonas Rapid Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Trichomonas Rapid Testing Market Analytics
A capital-intensity divergence between automated molecular platforms and lateral-flow strip manufacturers is bifurcating competitive dynamics in the Trichomonas rapid testing landscape. Abbott Laboratories leverages its integrated diagnostics infrastructure to sustain high-throughput laboratory placements across developed markets. Quidel Corporation specializes in CLIA-waived immunoassay formats that anchor its position in urgent care and physician office settings. Thermo Fisher Scientific extends its reach through PCR-based nucleic acid test systems that dominate reference laboratory workflows.
Trichomonas rapid testing encompasses point-of-care and near-patient diagnostic methods designed to detect Trichomonas vaginalis antigens or nucleic acids within minutes, typically employing lateral-flow immunochromatography or isothermal amplification with sensitivity thresholds ranging from 10^3 to 10^4 organisms per sample. These tests serve primary clinical purposes including symptomatic patient triage, asymptomatic screening in high-prevalence populations, and same-day treatment initiation to reduce transmission chains. The antigen test segment occupies the largest installed base due to its minimal equipment requirements and compatibility with resource-limited settings, while nucleic acid test formats represent the fastest-expanding category as PCR and isothermal technologies penetrate outpatient clinics. Home care end users constitute an emerging demand pocket, though regulatory complexity around self-collection protocols constrains near-term margin pools relative to professional segments.
The FDA's CLIA waiver program and the Clinical Laboratory Improvement Amendments framework shape product development priorities by determining which platforms qualify for decentralized use without laboratory certification burdens. ISO 13485 quality management standards and WHO prequalification pathways govern international market access, particularly for manufacturers targeting procurement channels in endemic regions. Stakeholders must monitor evolving reimbursement codes for molecular versus immunoassay methodologies, as payer classification decisions will determine which technology formats capture volume in the expanding point-of-care segment.
Market Dynamics
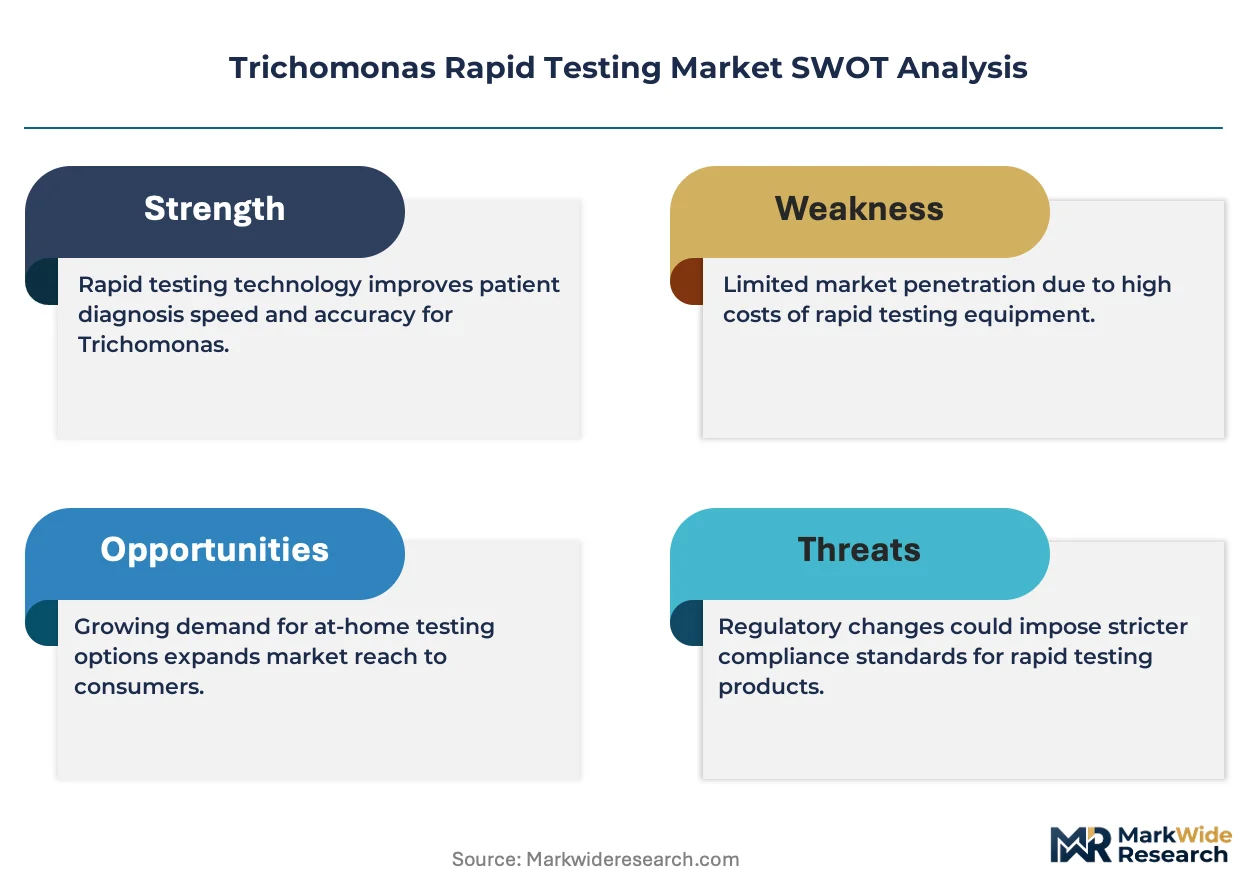
The FDA's CLIA waiver pathway is compressing the timeline for decentralized Trichomonas testing deployment, enabling antigen-based platforms to reach physician offices and urgent care clinics without laboratory certification burdens. This regulatory mechanism is redistributing testing volume from centralized laboratories toward point-of-care settings.
Growth Catalysts
- CLIA Waiver Expansion:The FDA's streamlined pathway for waived complexity testing eliminates laboratory director requirements, allowing antigen-based rapid tests to penetrate retail clinics and family planning centers.
- Isothermal Amplification:Loop-mediated isothermal amplification (LAMP) platforms are reducing equipment footprints and power requirements, enabling nucleic acid testing in resource-constrained outpatient environments.
- Reproductive Health Screening Mandates:United States Medicaid programs in high-prevalence states are incorporating Trichomonas screening into routine prenatal and STI prevention protocols.
Market Restraints
- Reimbursement Compression:Payer classification disputes between molecular and immunoassay methodologies create pricing uncertainty for manufacturers navigating CMS coding decisions.
- Specimen Stability Limitations:Antigen degradation in vaginal swab samples requires cold chain logistics or immediate processing, constraining deployment in tropical climates and remote settings.
- Substitution by Syndromic Panels:Multiplex STI platforms detecting chlamydia, gonorrhea, and Trichomonas simultaneously are capturing laboratory budgets that might otherwise fund standalone rapid tests.
Strategic Opportunities
- Home Collection Authorization:FDA clearance of self-collection protocols for nucleic acid tests would unlock direct-to-consumer channels currently blocked by specimen handling regulations.
- Telehealth Integration:Remote consultation platforms paired with mail-in rapid testing create synchronous diagnosis-treatment workflows for asymptomatic populations.
- WHO Prequalification:Endemic region procurement programs in sub-Saharan Africa and Southeast Asia favor prequalified manufacturers for public health distribution contracts.
Industry Challenges
- Cross-Reaction Engineering:Lateral-flow developers must eliminate false positives from commensal trichomonads and related protozoa through monoclonal antibody refinement.
- Legacy LIS Integration:Point-of-care devices require middleware solutions to transmit results into hospital electronic health record systems without dedicated laboratory information system infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trichomonas Rapid Testing Market |
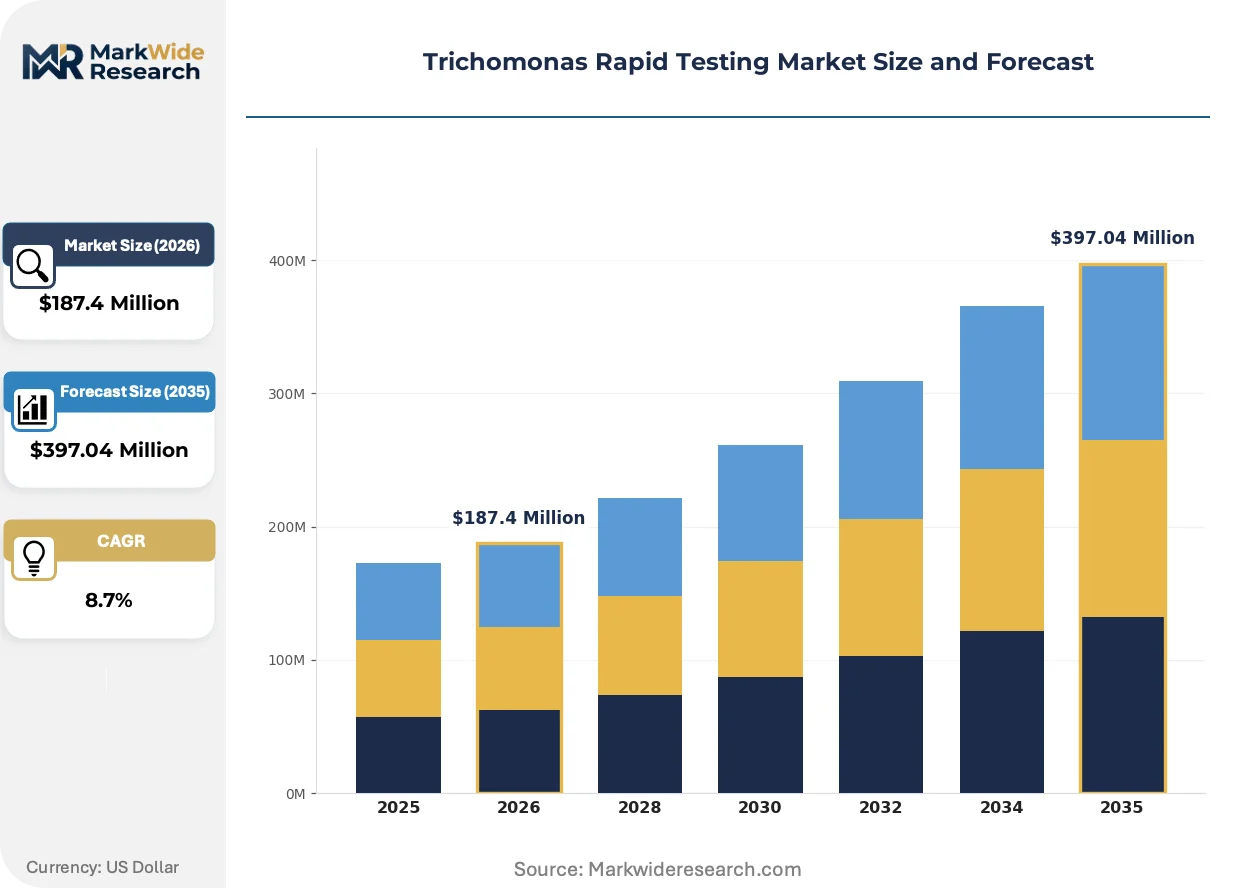
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antigen Test, Nucleic Acid Test, Culture Test, Microscopy End User: Clinics, Hospitals, Laboratories, Home Care Technology: PCR, Immunoassay, Rapid Testing, Electrophoresis Application: Screening, Diagnostic, Surveillance, Research |
| Companies Covered | Nanjing Liming Bio-Products, Abbott Laboratories, Quidel Corporation, Roche Diagnostics, Cepheid, Sekisui Diagnostics, BD (Becton, Dickinson and Company), Thermo Fisher Scientific, Hologic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trichomonas Rapid Testing Market Evolving Landscape
Technology convergence between smartphone-connected readers and disposable assay cartridges is redefining result documentation and epidemiological surveillance capabilities. Manufacturers are embedding connectivity features that transform standalone rapid tests into networked diagnostic nodes.
Isothermal amplification chemistry paired with fluorescence detection is bifurcating the point-of-care segment into minimal-equipment antigen strips and instrument-dependent molecular platforms. Community health centers in the United States are adopting hybrid workflows that deploy antigen tests for symptomatic triage while reserving LAMP-based systems for confirmatory testing. This dual-track approach is compressing average time-to-treatment intervals while preserving diagnostic accuracy.
The FDA's 2023 guidance on over-the-counter diagnostic authorization is expanding the addressable market beyond traditional clinical settings. Manufacturers are restructuring quality management systems to satisfy ISO 13485 requirements for lay-user labeling and error-proofing design controls. Home care segments in North American and European markets are responding with pilot programs testing supervised self-collection models.
Consolidated procurement by United States hospital networks and integrated delivery systems is concentrating purchasing authority among fewer procurement officers. Group purchasing organizations are negotiating exclusive vendor arrangements that displace smaller manufacturers from high-volume accounts. This buyer concentration is most visible in the southeastern United States, where large health systems operate extensive networks of affiliated urgent care facilities.
Trichomonas Rapid Testing Market Segmentation
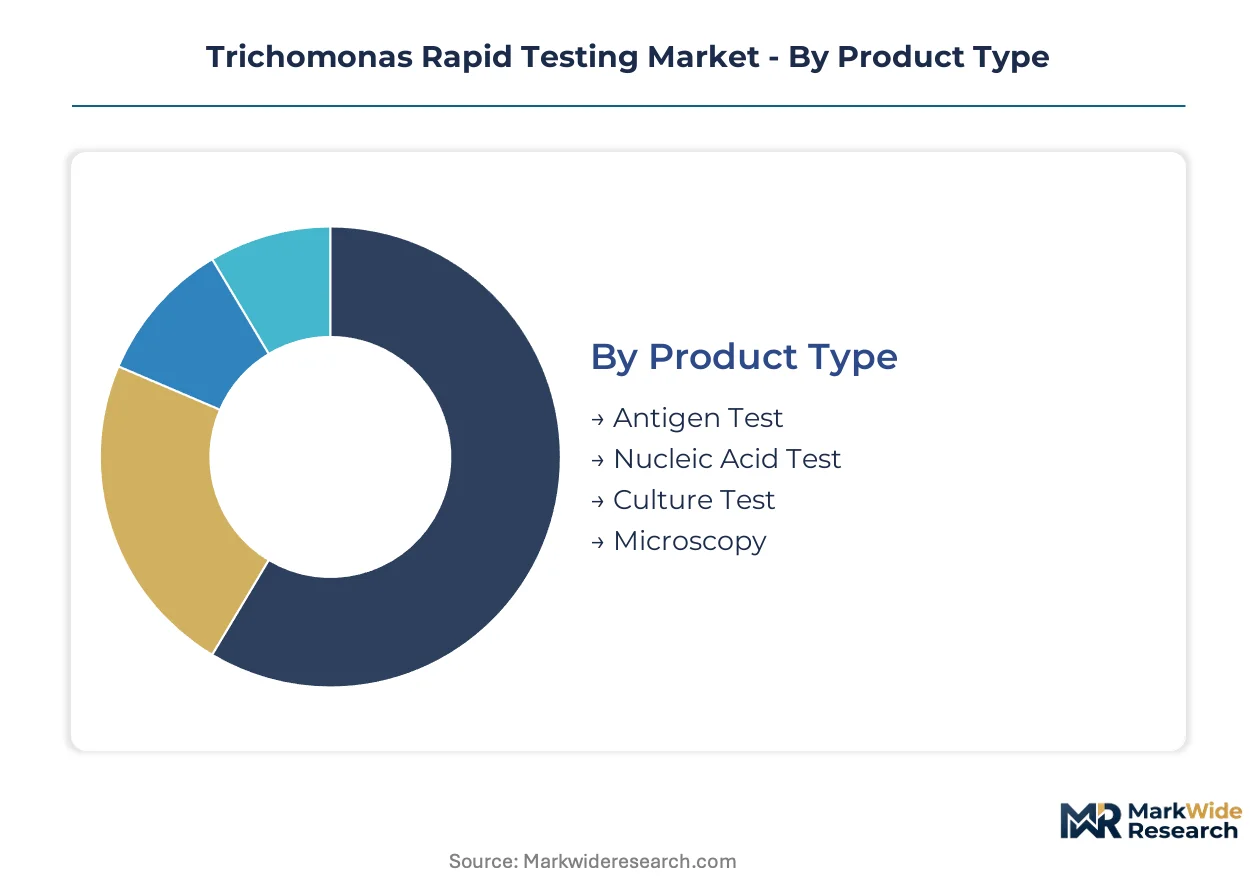
Segmentation in Trichomonas rapid testing reveals how technology choices, care settings, and use cases allocate capital across the value chain. Product format and end-user channel decisions determine regulatory pathway, reimbursement tier, and margin structure for manufacturers.
Product Type:
Antigen tests dominate domestic United States demand through CLIA-waived distribution, while nucleic acid formats anchor export-led expansion into European and Asia-Pacific reference laboratories.
- Antigen Test:Lateral-flow immunochromatography strips detect Trichomonas vaginalis surface proteins without thermal cycling equipment. United States urgent care chains and family planning clinics drive volume through waived-complexity protocols that eliminate laboratory director oversight. Cold chain requirements for specimen stability constrain deployment in tropical climates.
- Nucleic Acid Test:PCR and isothermal amplification platforms target organism-specific DNA or RNA sequences with analytical sensitivity below 10^3 organisms per sample. European hospital networks and Japanese reference laboratories absorb high instrument placements despite per-test reagent premiums. Reimbursement codes favor molecular sensitivity for asymptomatic screening protocols.
- Culture Test:Diamond's medium cultivation remains the historical gold standard for speciation confirmation in research settings.
- Microscopy:Wet mount visualization persists in resource-constrained settings lacking cold chain logistics for specimen transport.
Antigen tests command the established base. The steepest expansion runs through nucleic acid platforms.
End User:
Cost tier stratification separates capital-intensive hospital installations from minimal-equipment clinic deployments, with home care representing a premium-priced emerging channel.
- Clinics:Physician offices and urgent care centers prioritize CLIA-waived antigen formats that deliver results during single-visit encounters. United States retail health expansion through CVS MinuteClinic and Walgreens Healthcare embeds testing into routine STI screening workflows. Payer mix sensitivity to Medicaid reimbursement rates shapes product selection.
- Hospitals:Emergency departments and obstetrics units deploy multiplex PCR panels that consolidate Trichomonas detection with chlamydia and gonorrhea screening. Integrated delivery systems in the southeastern United States negotiate exclusive vendor contracts that concentrate purchasing authority. Laboratory information system integration requirements filter out point-of-care devices lacking middleware connectivity.
- Laboratories:Reference and public health laboratories process batched nucleic acid tests for epidemiological surveillance and confirmatory diagnosis.
- Home Care:Direct-to-consumer channels await FDA authorization of self-collection protocols for nucleic acid tests.
Hospitals anchor the revenue base. Home care represents the steepest volume climb if regulatory barriers fall.
Technology:
Application context determines whether thermal cycling precision or rapid visual interpretation takes priority in platform selection.
- PCR:Polymerase chain reaction achieves highest analytical sensitivity through thermal cycling amplification of target DNA sequences. Reference laboratories in Germany and France maintain installed bases of automated extractors and real-time detection systems. Capital equipment amortization schedules extend replacement cycles beyond five years.
- Immunoassay:Antibody-antigen binding reactions on porous membranes generate qualitative results without power requirements. Sub-Saharan African procurement programs through WHO prequalification pathways favor immunoassay formats for decentralized rural deployment. Shelf stability under ambient temperature conditions reduces logistics burden.
- Rapid Testing:Lateral-flow and flow-through architectures compress time-to-result below fifteen minutes.
- Electrophoresis:Gel-based separation supports research applications requiring amplicon size confirmation.
Immunoassay technology commands the installed base. PCR platforms are gaining share fastest in developed market laboratories.
Application:
Customer type differentiation separates high-volume screening programs from low-frequency research procurement with distinct pricing tolerance.
- Screening:Asymptomatic population testing in prenatal and high-prevalence community settings demands cost-minimized antigen formats. United States Medicaid programs in southern states mandate Trichomonas screening for pregnant enrollees, creating concentrated demand pockets. Pooling strategies for nucleic acid tests reduce per-patient cost in high-throughput public health laboratories.
- Diagnostic:Symptomatic patient triage in urgent care and emergency settings prioritizes same-day result turnaround for immediate treatment initiation. CLIA-waived antigen tests satisfy this workflow requirement without laboratory infrastructure. Diagnostic accuracy trade-offs against culture confirmation are accepted for clinical management purposes.
- Surveillance:Public health monitoring tracks prevalence trends and antimicrobial resistance patterns.
- Research:Academic and pharmaceutical studies require validated nucleic acid quantification for clinical trial endpoints.
Diagnostic applications command the transaction volume. Screening programs represent the steepest expansion trajectory as Medicaid mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: United States buyers absorb premium pricing for CLIA-waived molecular platforms, while procurement programs in sub-Saharan Africa and Southeast Asia prioritize cost-minimized antigen strips. Price-sensitive markets favor lateral-flow formats with minimal cold chain requirements.
United States
Medicaid screening mandates in high-prevalence southern states drive volume for point-of-care antigen tests. The FDA's CLIA waiver pathway enables deployment in retail clinics without laboratory certification. Texas and Florida health systems operate extensive urgent care networks adopting rapid Trichomonas testing for same-day treatment protocols.
Germany
Reference laboratories in Bavaria and North Rhine-Westphalia maintain installed bases of automated PCR systems for asymptomatic screening programs. EMA guidance on nucleic acid test validation shapes product registration requirements. Berlin-based hospital networks negotiate consolidated procurement contracts favoring multiplex STI panels over standalone rapid tests.
Japan
PMDA regulatory timelines extend market entry for foreign manufacturers, protecting domestic diagnostic companies. Tokyo and Osaka metropolitan areas concentrate demand in obstetrics and gynecology clinics. METI funding for infectious disease preparedness supports adoption of isothermal amplification platforms in prefectural health centers.
Brazil
ANVISA registration pathways for in vitro diagnostics create compliance barriers for smaller manufacturers. São Paulo and Rio de Janeiro public health laboratories process batched nucleic acid tests for epidemiological surveillance. Federal Ministry of Health procurement programs prioritize cost per test in family planning clinic distribution.
South Africa
WHO prequalification status determines eligibility for national tender processes in sub-Saharan African distribution. Gauteng and Western Cape provinces operate the continent's most extensive laboratory networks. Department of Health screening protocols for pregnant women concentrate demand in antenatal care settings.
Trichomonas Rapid Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Trichomonas rapid testing market. Abbott Laboratories, Roche Diagnostics, and Thermo Fisher Scientific leverage global distribution infrastructure and diversified diagnostic portfolios to secure high-throughput laboratory placements. Mid-sized specialists including Quidel Corporation and Cepheid compete on CLIA-waived platform specialization and rapid turnaround workflows. Competitive dynamics center on regulatory pathway speed and exclusive procurement contracts with integrated delivery systems.
Among integrated diagnostics conglomerates, Abbott Laboratories and Roche Diagnostics exemplify the capital-intensive tier pursuing automated molecular platform placements across developed market reference laboratories. Quidel Corporation occupies a distinct position within the CLIA-waived specialist archetype, anchoring point-of-care penetration in United States urgent care and retail clinic channels. Cepheid represents the molecular point-of-care convergence segment, bridging nucleic acid sensitivity with decentralized deployment formats. These three company patterns illustrate how technology format choices—antigen versus nucleic acid, waived versus moderate complexity—partition competitive terrain.
| Leading Market Players |
|---|
| Nanjing Liming Bio-Products |
| Abbott Laboratories |
| Quidel Corporation |
| Roche Diagnostics |
| Cepheid |
| Sekisui Diagnostics |
| BD (Becton, Dickinson and Company) |
| Thermo Fisher Scientific |
| Hologic Inc. |
| Others |
Value Network & Pricing Analysis
Automated PCR platform utilization rates above 70% in United States reference laboratories create fixed-cost absorption advantages that compress per-test price floors for molecular diagnostics. This scale dynamic concentrates supply-side power among instrument-reagent integrated manufacturers while squeezing margin pools for standalone antigen strip producers competing on CLIA-waived volume.
Pricing Analysis
After-sales reagent contracts and preventive service agreements generate lifetime value multiples exceeding three times initial instrument placement revenue for nucleic acid test manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by throughput commitment and certification requirements. Cost compression in the antigen segment is intensifying because retail clinic chains are consolidating procurement through exclusive vendor arrangements. Medicaid-funded family planning clinics exhibit highest price sensitivity, while integrated delivery systems in the southeastern United States absorb premium pricing for multiplex molecular platforms.
Supply Chain Analysis
Monoclonal antibody production for lateral-flow capture reagents hinges on bioreactor capacity concentrated in China, South Korea, and the United States. Nitrocellulose membrane substrates, fluorescence detection reagents, and isothermal amplification enzymes constitute critical input dependencies. Single-source vulnerability in specialized antibody clones creates supply continuity exposure during facility contamination events. Distribution runs through medical device distributors serving hospital networks and direct contracts with retail health chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory navigation capabilities—particularly FDA CLIA waiver pathway expertise and WHO prequalification documentation—represent scarce assets that determine market access velocity. Manufacturers lacking in-house quality management systems for ISO 13485 compliance face 18-24 month delays versus integrated competitors.
For Market Incumbents: Fortify installed base lock-in through middleware integration with Epic and Cerner electronic health record systems, blocking point-of-care devices from laboratory information system connectivity. Deepen backward integration into monoclonal antibody production to secure capture reagent supply against bioreactor capacity constraints. Priority lever: exclusive procurement contracts with southeastern United States health systems operating urgent care networks. For New Entrants and Emerging Players: Differentiate on telehealth-integrated specimen collection workflows that pair mail-in nucleic acid tests with synchronous remote consultation platforms. Target the home care segment awaiting FDA self-collection protocol authorization as the most penetrable white space. Go-to-market angle: supervised self-collection pilot programs with direct-to-consumer channels in North American metropolitan areas. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CLIA-waived molecular platform specialists bridging antigen simplicity with nucleic acid sensitivity. Long-term viability rests on dual-track regulatory capabilities spanning FDA and WHO pathways. Acquisition target archetype: isothermal amplification developers with pending 510(k) submissions. Signal to watch: CMS reimbursement code reclassification between molecular and immunoassay methodologies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA CLIA Waiver Submission | Unlocks physician office and urgent care deployment without laboratory director certification burdens. |
| Hospital System Partnership | Secures preferred vendor status within integrated delivery networks consolidating procurement authority. |
| Reimbursement Strategy Development | Positions molecular platforms for favorable CMS coding versus antigen alternatives in screening protocols. |
| Software Companion Development | Enables smartphone-connected result documentation and epidemiological surveillance for lateral-flow devices. |
| WHO Prequalification Pathway | Qualifies manufacturers for sub-Saharan African and Southeast Asian public health procurement tenders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CLIA-waived test developers, hospital laboratory directors, GPO contracts managers, and FDA regulatory consultants. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, WHO prequalification listings, and hospital procurement contract disclosures. Bottom-up volume estimates by product format and end-user channel were triangulated against top-down market sizing derived from instrument placement tracking and reagent consumption models.
Across the projection horizon, analytical frameworks modeled segmentation dimensions including technology format, care setting, application purpose, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating Medicaid screening mandate expansion rates, CLIA waiver approval velocity, and isothermal amplification platform adoption trajectories. Forecast inputs included United States retail clinic expansion plans and European reference laboratory automation replacement cycles.
The analysis sits within stated boundaries; outcomes outside sustained FDA waiver pathway efficiency or stable CMS reimbursement classifications would require recalibration. Forecasts reflect documented assumptions regarding specimen stability improvements and telehealth regulatory accommodation. Practitioners should keep alternative scenarios live as WHO prequalification timelines and multiplex STI panel substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Dengue Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Mono Rapid Testing Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Global Newborn Screening Market
Testing Services
Large Molecule Bioanalytical Testing Services Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Anti-Asthma TDM Assay Kits Market
Testing Services
Cannabis Testing Services Market
Testing Services
Tablet Hardness Testers Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
West Nile Virus Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Rapid Test Cards Market