
 Antibiotic Residue Test Kits Market | 2026-2036
Antibiotic Residue Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Antibiotic Residue Test Kits Market Analysis
Food processing units are broadening their internal quality control capabilities beyond traditional laboratory outsourcing. PerkinElmer leverages its chromatography instrumentation heritage to anchor high-throughput confirmatory workflows for meat packers. Neogen Corporation sustains geographic dominance in North American dairy testing through extensive distributor networks. R-Biopharm specializes in ELISA-based competitive tests that comply with European reference laboratory standards.
Antibiotic residue test kits are immunoassay and chromatographic systems designed to detect veterinary drug metabolites in edible tissues and fluids at parts-per-billion sensitivity thresholds. Their primary commercial purpose is to prevent violative residues from entering human food chains and to certify export compliance with importing jurisdiction maximum residue limits. Screening tests dominate routine volume due to lower per-unit cost and minimal operator training requirements, while confirmatory tests capture concentrated margin pools from regulatory enforcement actions and export certification. Chromatography segments lead in analytical specificity for complex seafood matrices, whereas lateral flow assays expand fastest in remote processing facilities lacking laboratory infrastructure.
The FDA and USDA FSIS enforce zero-tolerance policies for specific beta-lactam residues in domestic dairy, compelling processors to maintain continuous testing protocols. EFSA and EU reference laboratories under Regulation 37/2010 establish harmonized maximum residue limits that shape kit calibration standards for exporters. China's SAMR implements domestic GB standards that diverge from Codex Alimentarius thresholds, creating dual-certification requirements for multinational suppliers. Stakeholders must monitor divergence between national residue limit schedules when configuring kit sensitivity parameters for cross-border supply chains.
Market Dynamics
Processor consolidation across Germany's dairy belt is concentrating procurement power into fewer hands, forcing test kit suppliers to reconfigure pricing and service models around multi-site volume contracts rather than individual facility sales.
Growth Catalysts
- EU MDR Framework:The Medical Device Regulation mandates stricter residue thresholds for diagnostic platforms used in food safety applications, compelling processors to upgrade from basic screening to certified confirmatory systems.
- ELISA Platform Advancement:Competitive immunoassay formats now achieve parts-per-billion sensitivity previously requiring chromatography, expanding deployability to remote processing facilities lacking laboratory infrastructure.
- SAMR Certification Acceleration:China's State Administration for Market Regulation has compressed domestic kit approval timelines, enabling multinational suppliers to capture volume in the world's largest dairy production base.
Market Restraints
- Reference Standard Fragmentation:Divergence between Codex Alimentarius thresholds and China's GB standards forces manufacturers to maintain multiple calibration batches, elevating production complexity and inventory carrying costs.
- Chromatography Input Concentration:High-purity solvents and certified reference materials for LC-MS/MS workflows originate from a concentrated German and Swiss supplier base, exposing confirmatory test producers to supply disruption risk.
- Lateral Flow Specificity Ceiling:Antibody cross-reactivity limits in rapid screening formats generate false-positive rates that necessitate expensive confirmatory follow-up, constraining total cost-of-ownership advantages.
Strategic Opportunities
- India Dairy Belt Penetration:The National Dairy Development Board's quality modernization program creates first-mover advantage for suppliers establishing localized production and technical service networks in Gujarat and Punjab.
- Blockchain-Assay Convergence:Integration of immutable test result logging with distributed ledger systems enables premium pricing from exporters requiring tamper-proof compliance documentation for EU and Middle Eastern buyers.
- Direct Processor Channel Development:Bypassing traditional laboratory distributor networks through e-procurement platforms and technical service subscriptions captures margin previously allocated to intermediaries.
Industry Challenges
- Multiplex Assay Development Timeline:Engineering antibody panels that simultaneously detect beta-lactams, tetracyclines, and sulfonamides without cross-interference extends R&D cycles beyond typical agricultural input product development schedules.
- Legacy LIMS Integration Friction:Connecting new-generation rapid test readers with existing laboratory information management systems in established processing cooperatives demands customized middleware development that strains implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibiotic Residue Test Kits Market |
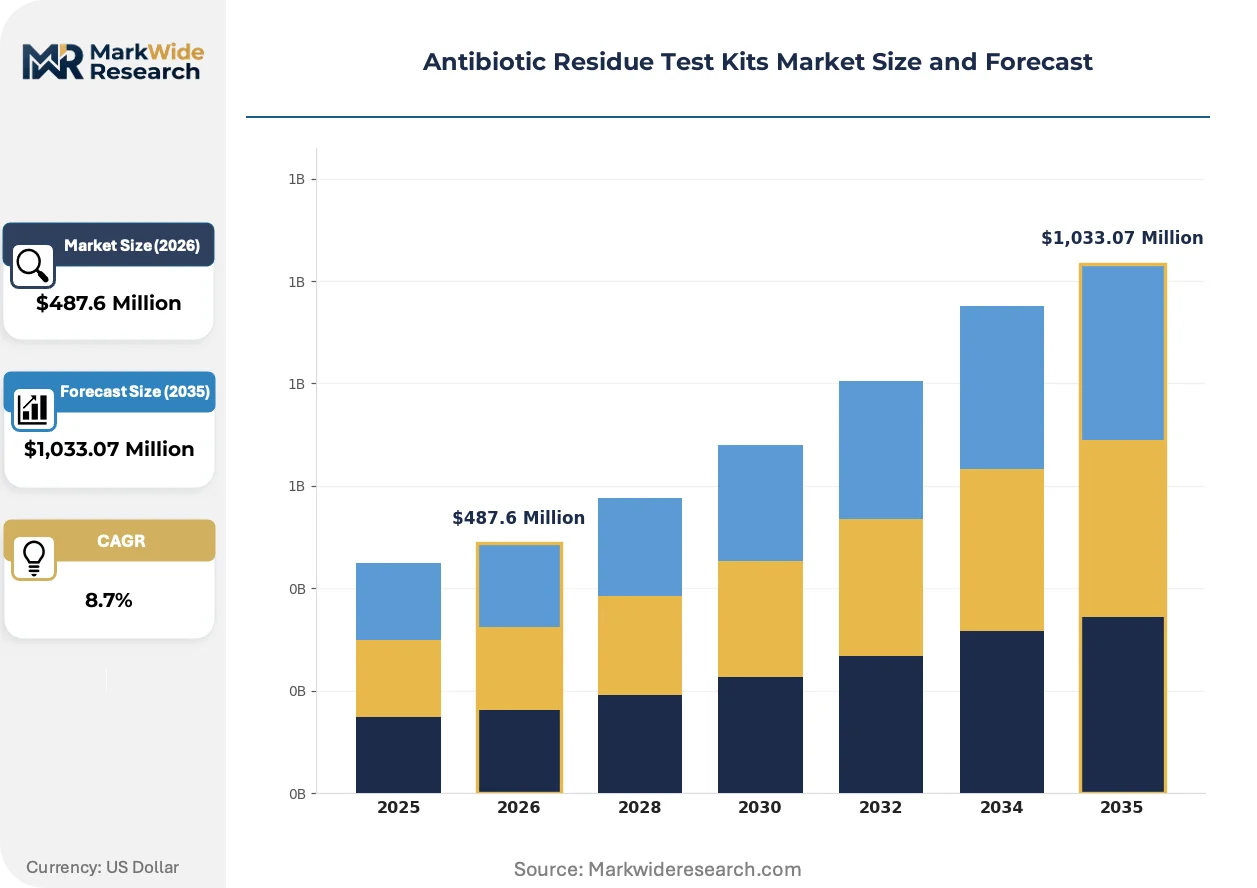
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Competitive Tests, Screening Tests, Confirmatory Tests, Multi-Analyte Kits Technology: ELISA, PCR, Lateral Flow Assays, Chromatography End User: Laboratories, Food Processing Units, Research Institutions, Quality Control Departments Application: Dairy Products, Meat Products, Seafood, Plant-Based Foods |
| Companies Covered | Bentley Instruments, Bioeasy, PerkinElmer, Agilent Technologies, Waters Corporation, Charm Sciences, Ringbio, Neogen Corporation, R-Biopharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibiotic Residue Test Kits Market Emerging Trajectories
Automation is compressing the time between sample collection and regulatory decision, while portable molecular platforms and AI-assisted result interpretation are redistributing analytical capability from centralized laboratories to production floor environments.
Microfluidic cartridge systems are automating sample preparation and reagent handling for beta-lactam screening in high-throughput dairy processing environments. Large cooperatives in Bavaria and Lower Saxony have adopted these platforms at central testing facilities, replacing manual pipetting workflows. This automation is compressing turnaround times from hours to minutes while reducing technician training requirements and error rates in 24-hour production cycles.
REACH framework amendments are tightening restrictions on chemical reagents used in chromatographic confirmatory methods, particularly affecting solvent classifications for LC-MS/MS workflows. Manufacturers serving European export certification markets must reformulate kit chemistries or source alternative reagent grades. The seafood testing segment faces the steepest compliance burden due to complex matrix requirements that demand high-solvent-consumption extraction protocols.
Processor procurement committees are consolidating testing contracts under multi-year technical service agreements that bundle equipment, consumables, and regulatory consulting. Traditional per-kit transactional purchasing is retreating in Germany's consolidated dairy sector. This contractual concentration is most pronounced among cooperatives processing over one million liters daily, where total cost of ownership models now dominate supplier selection criteria.
Antibiotic Residue Test Kits Market Segmentation
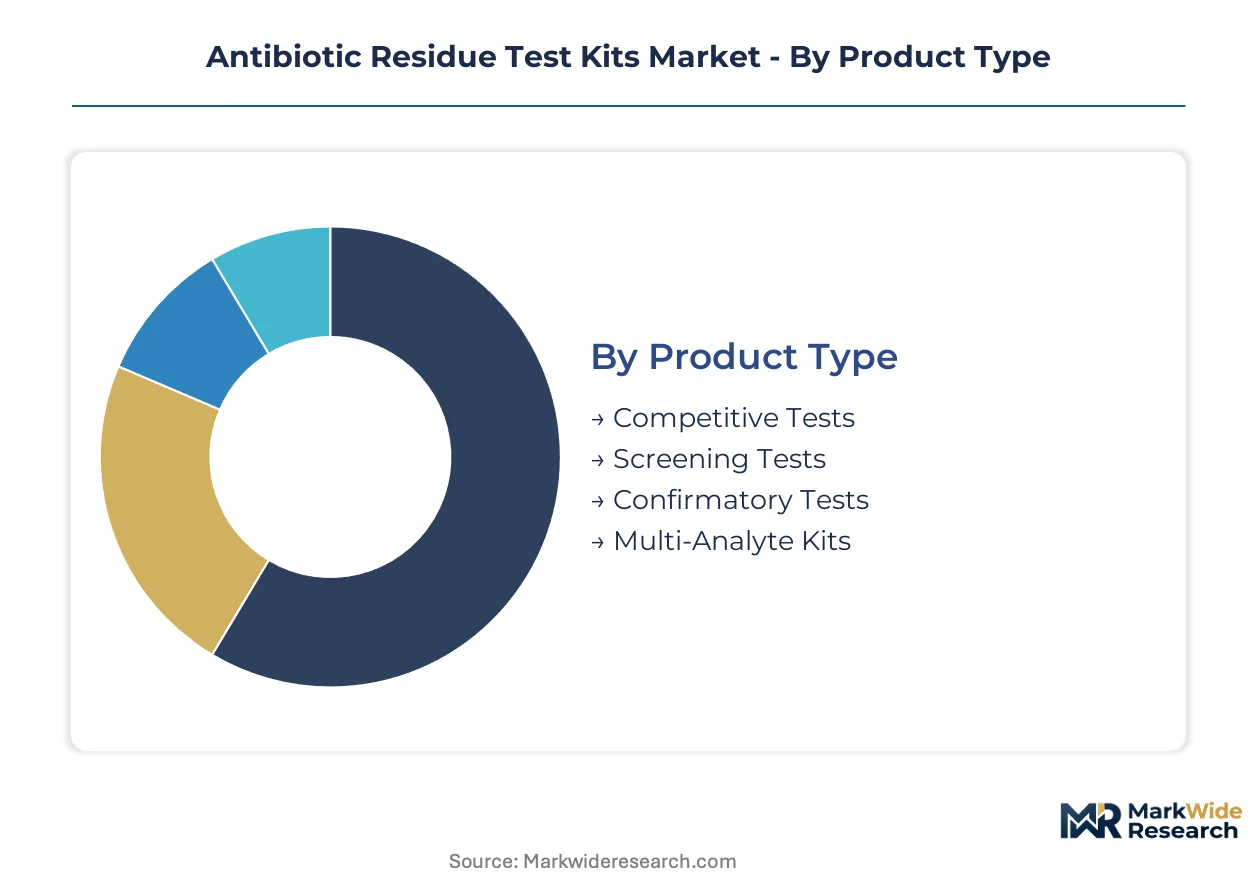
Antibiotic residue test kits fragment across four critical dimensions that determine procurement workflows, regulatory compliance pathways, and total cost structures for food safety operations. Each segmentation layer carries distinct margin profiles and technical service requirements that shape supplier competitive positioning.
Product Type:
Procurement committees weigh sensitivity thresholds against turnaround speed when allocating budget across testing tiers.
- Screening Tests:Rapid immunoassay formats deliver qualitative results within minutes for routine production floor monitoring. Dairy cooperatives in Bavaria deploy lateral flow screening at receiving stations to intercept tanker loads before unloading, driven by EU MDR documentation requirements for incoming raw milk.
- Confirmatory Tests:Chromatographic and mass spectrometry-based systems provide legally defensible quantitative data for regulatory enforcement and export certification. Meat packers facing USDA FSIS zero-tolerance enforcement maintain LC-MS/MS capacity for beta-lactam verification, constrained by concentrated German and Swiss solvent supply chains.
- Competitive Tests:ELISA-based competitive inhibition assays achieve quantitative detection without instrument capital expenditure.
- Multi-Analyte Kits:Single-sample panels simultaneously screen beta-lactams, tetracyclines, and sulfonamides.
Volume sits with Screening Tests; growth tilts toward Confirmatory Tests.
Technology:
Facility infrastructure and technician skill availability determine technology selection across processing environments.
- ELISA:Enzyme-linked immunosorbent assay platforms balance sensitivity with equipment accessibility, achieving parts-per-billion detection for tetracycline residues without chromatography infrastructure. Remote dairy collection centers in India's Gujarat dairy belt favor ELISA for its minimal cold chain and electricity requirements.
- Chromatography:High-performance liquid chromatography paired with tandem mass spectrometry delivers definitive identification for complex matrices. Seafood exporters to EU markets maintain LC-MS/MS capacity for sulfonamide verification in shrimp and finfish, pressured by REACH solvent reclassification compliance costs.
- Lateral Flow Assays:Immunochromatographic strips enable point-of-use screening without laboratory infrastructure.
- PCR:Nucleic acid amplification detects antibiotic resistance gene markers rather than parent compounds.
Deployment breadth favors Lateral Flow Assays; analytical specificity drives Chromatography expansion.
End User:
Organizational scale and regulatory exposure intensity shape purchasing authority and service expectations.
- Food Processing Units:In-house quality control departments at large cooperatives consolidate testing under multi-year technical service agreements bundling equipment, consumables, and regulatory consulting. Germany's consolidated dairy sector leads this shift, with processors exceeding one million liters daily demanding total cost of ownership models over per-kit transactions.
- Laboratories:Third-party testing facilities and government reference laboratories anchor confirmatory testing demand, serving enforcement actions and export certification workflows.
- Quality Control Departments:Embedded technical teams at mid-sized processors balance screening volume with selective confirmatory outsourcing.
- Research Institutions:Academic and government research centers drive assay development and validation studies.
Contract value concentrates in Food Processing Units; capability building targets Quality Control Departments.
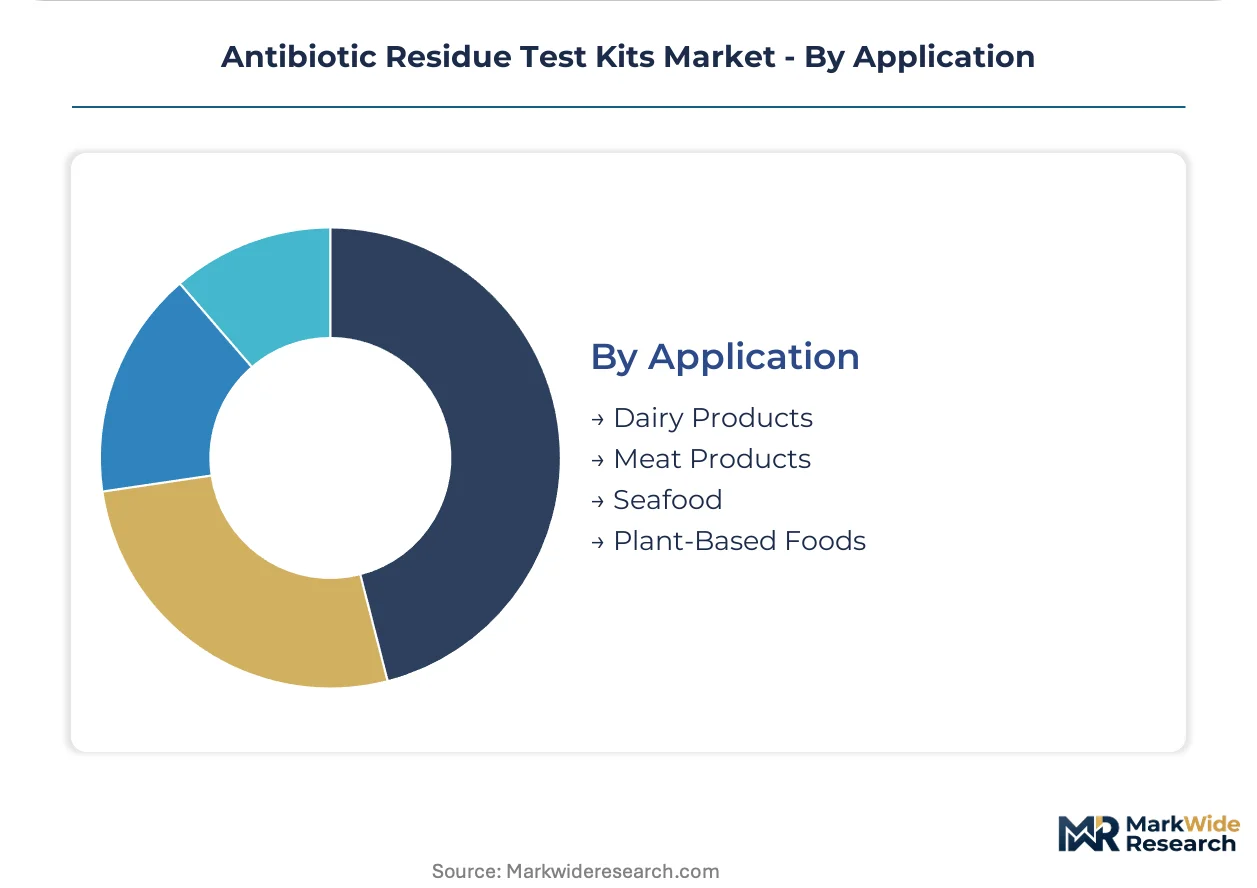
Application:
Matrix complexity and residue limit stringency vary sharply across food categories, dictating kit calibration requirements.
- Dairy Products:Fluid milk and cheese matrices dominate testing volume due to continuous production cycles and strict beta-lactam thresholds. Chinese SAMR domestic certification acceleration is expanding kit deployment across the world's largest dairy production base.
- Seafood:Complex lipid and protein matrices demand extraction-intensive protocols with elevated solvent consumption. REACH framework amendments impose the steepest compliance burden here, forcing reformulation of high-solvent chromatographic workflows.
- Meat Products:Muscle tissue and organ testing for pork, poultry, and beef slaughter operations.
- Plant-Based Foods:Emerging category addressing antibiotic transfer through manure fertilizer and irrigation water.
Test frequency peaks in Dairy Products; regulatory pressure intensifies in Seafood.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's dairy belt and India's cooperative networks, while consumption tilts toward Germany's consolidated processing sector and North American regulatory enforcement corridors.
China
Domestic dairy production scales drive kit procurement across Heilongjiang and Inner Mongolia milk belts. SAMR's compressed GB standard certification timelines enable faster multinational supplier entry. Yangtze River Delta processors deploy multi-analyte screening platforms at central laboratories serving regional cooperative networks.
Germany
Processor consolidation in Bavaria and Lower Saxony concentrates procurement power under multi-year technical service agreements. EU MDR mandates push cooperatives toward certified confirmatory systems from basic screening. The country's reference laboratory network calibrates kit sensitivity parameters for export certification across EU member states.
United States
USDA FSIS zero-tolerance enforcement compels meat packers to maintain continuous beta-lactam testing protocols. FDA dairy safety directives drive volume procurement among large-scale fluid milk processors. Midwest dairy cooperatives anchor domestic demand for high-throughput screening automation.
India
The National Dairy Development Board's quality modernization program expands kit deployment across Gujarat and Punjab collection centers. FSSAI residue limit harmonization with Codex Alimentarius reduces calibration complexity for multinational suppliers. Remote dairy facilities favor ELISA platforms requiring minimal laboratory infrastructure.
United Kingdom
Post-Brexit divergence from EU reference laboratory standards creates dual-certification requirements for export-oriented processors. EFSA-aligned maximum residue limits still shape domestic kit calibration for Irish Sea trade corridors. Scottish dairy cooperatives pilot blockchain-integrated testing documentation for premium export markets.
Antibiotic Residue Test Kits Market Vendor Landscape
Top-tier vendors anchor chromatography and mass spectrometry workflows for confirmatory testing, while mid-tier specialists occupy ELISA and lateral flow screening segments. The vendor base stratifies across analytical instrumentation conglomerates, dedicated diagnostics firms, and regional reagent suppliers. Three archetypes dominate: chromatography platform providers, immunoassay kit specialists, and integrated service contractors bundling equipment with regulatory consulting. Competitive positioning hardens around multi-year technical service agreements and geographic exclusivity arrangements with distributor networks.
Among analytical instrumentation providers, PerkinElmer and Agilent Technologies occupy positions anchoring high-throughput confirmatory workflows for meat packers and seafood exporters. Waters Corporation exemplifies the chromatography-focused archetype serving complex matrix requirements. Within the immunoassay tier, Neogen Corporation and R-Biopharm represent geographic specialization patterns—North American dairy networks versus European reference laboratory compliance. Bentley Instruments and Charm Sciences sit within the dairy-specific equipment-integrated testing segment. Chinese suppliers including Bioeasy and Ringbio capture volume in domestic certification-accelerated procurement channels.
| Leading Market Players |
|---|
| Bentley Instruments |
| Bioeasy |
| PerkinElmer |
| Agilent Technologies |
| Waters Corporation |
| Charm Sciences |
| Ringbio |
| Neogen Corporation |
| R-Biopharm |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EU MDR-compliant confirmatory systems and basic screening kits generates parallel pricing ladders and divergent supply chain footprints across the antibiotic residue testing landscape. Premium-tier chromatography platforms command extended production cycles anchored in German and Swiss solvent supply bases, while economy lateral flow strips source antibody reagents through distributed Asian bioproduction networks.
Pricing Analysis
Lead-time compression commands measurable price premiums in the confirmatory tier, with processors paying elevated rates for expedited LC-MS/MS consumable delivery during regulatory enforcement windows. Three-tier pricing structure across premium, standard, and economy levels reflects calibration complexity, after-sales technical bundling, and volume scale. Cost compression in the screening tier intensifies because Chinese domestic manufacturers exploit SAMR-accelerated certification pathways to undercut incumbent ELISA suppliers. Small-scale dairy cooperatives in India's Gujarat belt exhibit highest price sensitivity, whereas Germany's consolidated processors prioritize total cost of ownership over per-unit kit economics.
Supply Chain Analysis
China's domestic-content mandates under quality modernization programs are reshaping sourcing patterns for multinational kit suppliers seeking SAMR certification. High-purity solvents and certified reference materials draw from concentrated German and Swiss production bases, while antibody reagents feed from Chinese and South Korean bioproduction facilities. Single-source vulnerability concentrates in the chromatography solvent tier, where REACH reclassification threatens disruption. Distribution runs through laboratory distributor networks in North America and direct technical service contracts in Germany's consolidated dairy sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antibiotic residue test kits market sits in a technology-transition phase as microfluidic automation displaces manual pipetting workflows across high-throughput dairy processing environments.
For Market Incumbents: Hedge against ELISA margin erosion by deepening captive supply of high-purity solvents through backward integration into German chemical supply chains, while accelerating blockchain-integrated documentation platforms to capture premium pricing from EU export certification demand. Microfluidic cartridge standardization represents the priority R&D lever for defending installed base positions against lateral flow commoditization. For New Entrants and Emerging Players: The mid-tier price-point gap between PerkinElmer-class chromatography systems and commodity lateral flow strips opens white-space opportunity for portable molecular platforms with AI-assisted interpretation. India's Gujarat and Punjab dairy collection centers offer the most penetrable geography, given FSSAI harmonization reducing calibration complexity and minimal incumbent technical service presence. A subscription-based equipment-plus-consumables model bypasses capital-constrained cooperative procurement committees. For Investors and Strategic Acquirers: Re-rating potential sits with integrated service contractors bundling regulatory consulting with hardware, given EU MDR documentation complexity expanding customer lifetime value. Long-term viability favors targets with SAMR-certified production capacity in China and established technical service networks across Germany's dairy belt. The signal to watch is processor consolidation velocity in Bavaria and Lower Saxony, as million-liter-daily cooperatives accelerate multi-year contract aggregation.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Platform Integration | Bavarian cooperatives compress turnaround from hours to minutes in 24-hour production cycles. |
| Blockchain-Assay Convergence | Scottish dairy pilots enable tamper-proof compliance documentation for premium Middle Eastern export markets. |
| Backward Integration into Solvents | REACH reclassification exposure in seafood testing drives captive supply strategies for LC-MS/MS workflows. |
| SAMR Certification Acceleration | Compressed GB standard timelines enable multinational suppliers to capture volume in Heilongjiang milk belts. |
| Direct Processor Channel Development | E-procurement platforms bypass laboratory distributor margins in North American dairy networks. |
Methodological Framework
Document review covered EU MDR implementation guidance, SAMR GB standard certification protocols, and REACH solvent reclassification amendments, complemented by interviews with dairy quality control directors, chromatography platform engineers, and laboratory procurement managers at German cooperatives. Secondary validation drew from EFSA residue limit databases, FDA dairy safety directive filings, and FSSAI harmonization circulars. Bottom-up kit volume estimates triangulated against top-down processor consolidation data across the analysis window.
Segment-level outputs reflect disaggregation across product type, technology platform, end-user organizational scale, and application matrix complexity throughout the forecast period. CAGRs were derived from processor procurement cycle analysis and regulatory enforcement intensity modeling. Forecast inputs incorporated ELISA sensitivity advancement curves, microfluidic adoption rates in Bavarian facilities, and SAMR certification pipeline velocity for multinational entrants.
Inputs from cooperative procurement committees and reference laboratory directors were available through the study window; gaps in real-time processor consolidation transaction data introduce uncertainty bands around multi-year contract value estimates. Forecasts reflect documented assumptions regarding EU MDR enforcement consistency and SAMR certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Esoteric Testing Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Global Lipid Panel Testing Market
Testing Services
Pyrogen Testing Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Global Direct-To-Consumer (DTC)Testing Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Global Forensic Testing Services Market
Testing Services
Active B12 Test Market