
 Bitumen Testing Equipment Market | 2026-2036
Bitumen Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Bitumen Testing Equipment Market Analysis
Software-enabled calibration and remote diagnostics is recalibrating how bitumen testing equipment generates recurring revenue. Controls Group leverages its service infrastructure across European asphalt laboratories to sustain long-term client relationships. Anton Paar GmbH anchors its position through precision rheology systems that dominate high-specification pavement research. Aimil Ltd. competes on localized support networks within India's expanding road construction quality ecosystem.
Bitumen testing equipment comprises instruments that measure viscosity, penetration resistance, softening temperature, and ductility under standardized thermal and mechanical conditions, typically operating between 5°C and 180°C to simulate field performance. These systems verify binder grade compliance for hot-mix asphalt design and long-term pavement durability forecasting. Automated technology commands premium positioning as laboratories prioritize throughput and data traceability, while manual systems retain share in emerging markets with constrained capital budgets. Quality Assurance applications concentrate margin pools where contractors face penalty clauses for non-compliant material supply.
The EU Green Deal and F-Gas Regulation shape product design requirements for temperature-controlled testing chambers across European member states. India's BIS and CEA enforce equipment certification protocols for infrastructure project eligibility, filtering market access to compliant suppliers. Stakeholders must monitor how digital twin integration in pavement management systems redirects equipment procurement criteria toward interoperable data formats.
Market Dynamics
Software-enabled calibration and remote diagnostics is recalibrating how bitumen testing equipment generates recurring revenue, shifting capital equipment vendors toward service-based retention models. Road maintenance agencies in Germany are expanding their testing protocols under the EU Green Deal's sustainable infrastructure mandates, while India's PLI scheme for construction equipment accelerates domestic laboratory buildouts.
Growth Catalysts
- EU Green Deal mandates:Road maintenance agencies in Germany are expanding testing protocols for sustainable infrastructure verification, creating compliance-driven equipment refresh cycles.
- India's PLI scheme:Domestic construction equipment incentives are accelerating laboratory buildouts across state highway departments and private contractors.
- Digital twin integration:Pavement management systems are redirecting procurement criteria toward interoperable data formats, favoring connected testing platforms.
Market Restraints
- Temperature chamber fluorinated gas restrictions:The EU F-Gas Regulation limits refrigerant options for precision thermal control systems, constraining chamber design flexibility.
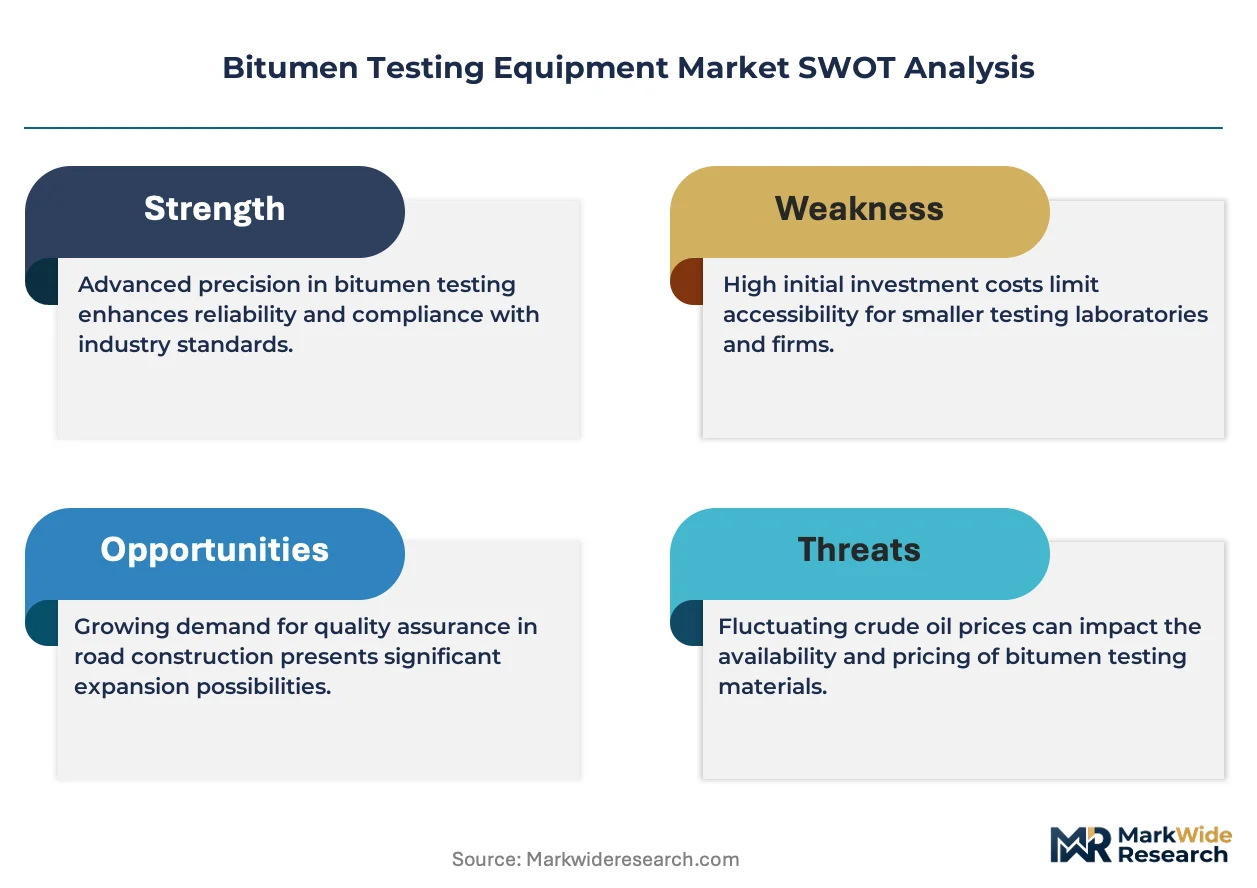
- Capital intensity of automation:Automated testing platforms require substantial upfront investment, excluding smaller laboratories in emerging markets with constrained budgets.
- Specialized technician scarcity:Rheology interpretation and calibration expertise concentrates in established testing hubs, limiting operational scaling.
Strategic Opportunities
- Quality Assurance penalty clauses:Contractor-facing compliance verification creates margin pools where equipment suppliers can bundle testing services with hardware.
- Remote diagnostics convergence:IoT-enabled calibration and cloud-based data traceability are opening subscription revenue streams for established service networks.
- BIS-CEA certification pathways:India's equipment certification protocols for infrastructure project eligibility filter market access toward compliant suppliers with localized support.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory certification for pavement binder testing extends procurement cycles and delays revenue recognition for equipment vendors.
- Legacy system integration friction:Automated platforms must interface with existing laboratory information management systems, complicating deployment.
- Skilled rheologist recruitment:Precision binder characterization requires specialized expertise that outpaces training pipeline capacity in expanding markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitumen Testing Equipment Market |
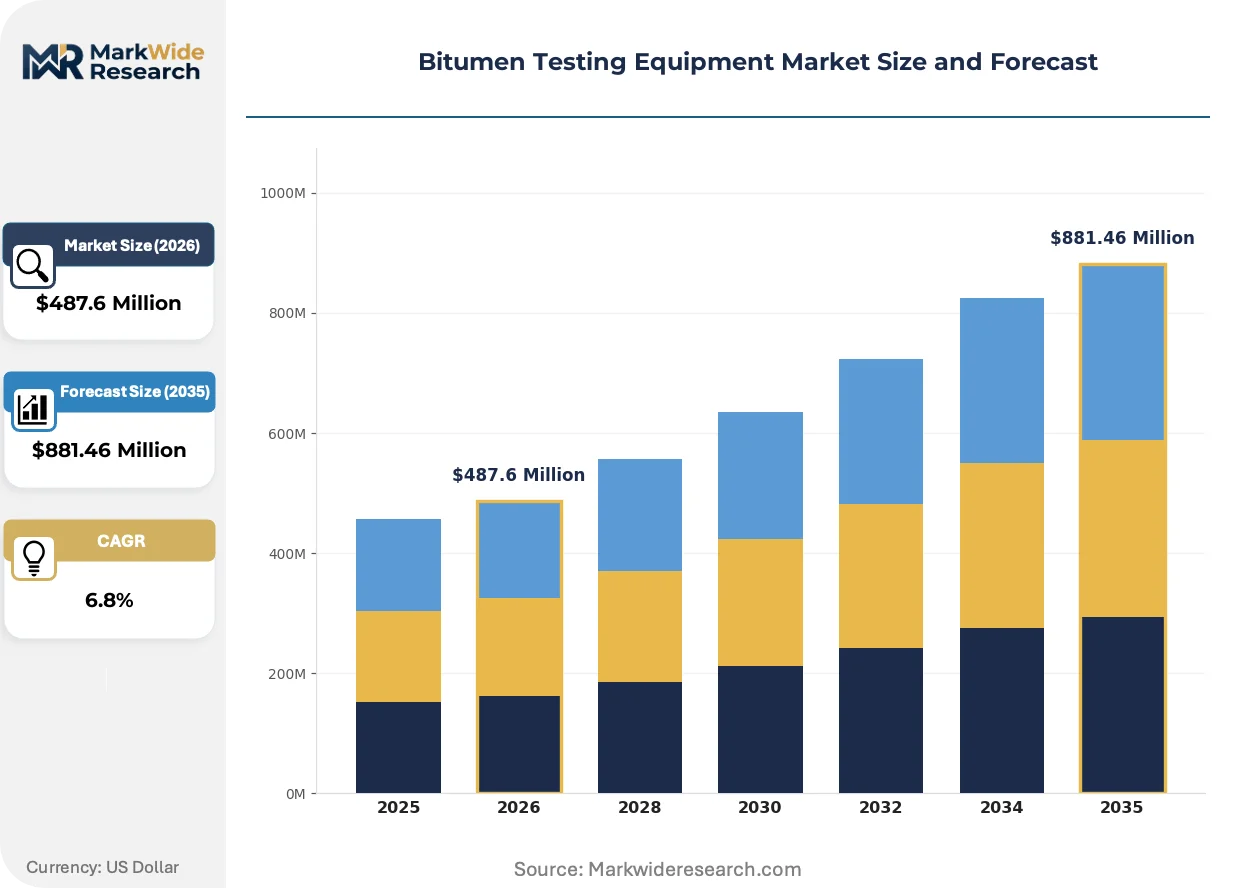
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscosity Testers, Penetration Testers, Softening Point Apparatus, Ductility Testers End User: Construction, Road Maintenance, Research Laboratories, Quality Control Facilities Technology: Digital, Manual, Automated, Hybrid Application: Pavement Analysis, Material Evaluation, Quality Assurance, Laboratory Testing |
| Companies Covered | Matest S.p.A., Controls Group, Humboldt Mfg. Co., Elcometer Ltd., Cooper Technology, Aimil Ltd., Anton Paar GmbH, CANNON Instrument Company, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitumen Testing Equipment Market Emerging Trajectories
Automation architecture is modularizing across bitumen testing workflows, enabling laboratories to phase capital deployment while preserving upgrade pathways. Three developments are restructuring competitive positioning and procurement patterns.
Portable viscometer platforms with embedded temperature control are modularizing field-based binder verification, allowing highway agencies to deploy rapid-grade confirmation at mixing plants rather than central laboratories. State departments of transportation in the US are piloting these units for project-level compliance spot-checks. The shift is compressing the traditional sample-to-laboratory logistics chain and expanding addressable volume beyond permanent facility installations.
The EU F-Gas Regulation is forcing refrigerant transitions in temperature-controlled testing chambers, compelling chamber manufacturers to redesign thermal systems around lower-global-warming-potential alternatives. European asphalt laboratories face compliance deadlines that accelerate equipment replacement cycles. German road research institutes are prioritizing suppliers with verified alternative-refrigerant performance data, creating certification-based supplier selection.
After-sales service unbundling is separating calibration contracts from equipment purchase, with laboratories procuring multi-vendor maintenance through specialized metrology service providers. This procurement model change is disrupting traditional manufacturer-captive service relationships. The pattern is most visible in India's expanding private testing laboratory sector, where capital constraints favor operational expenditure structures over bundled capital-service packages.
Bitumen Testing Equipment Market Segmentation
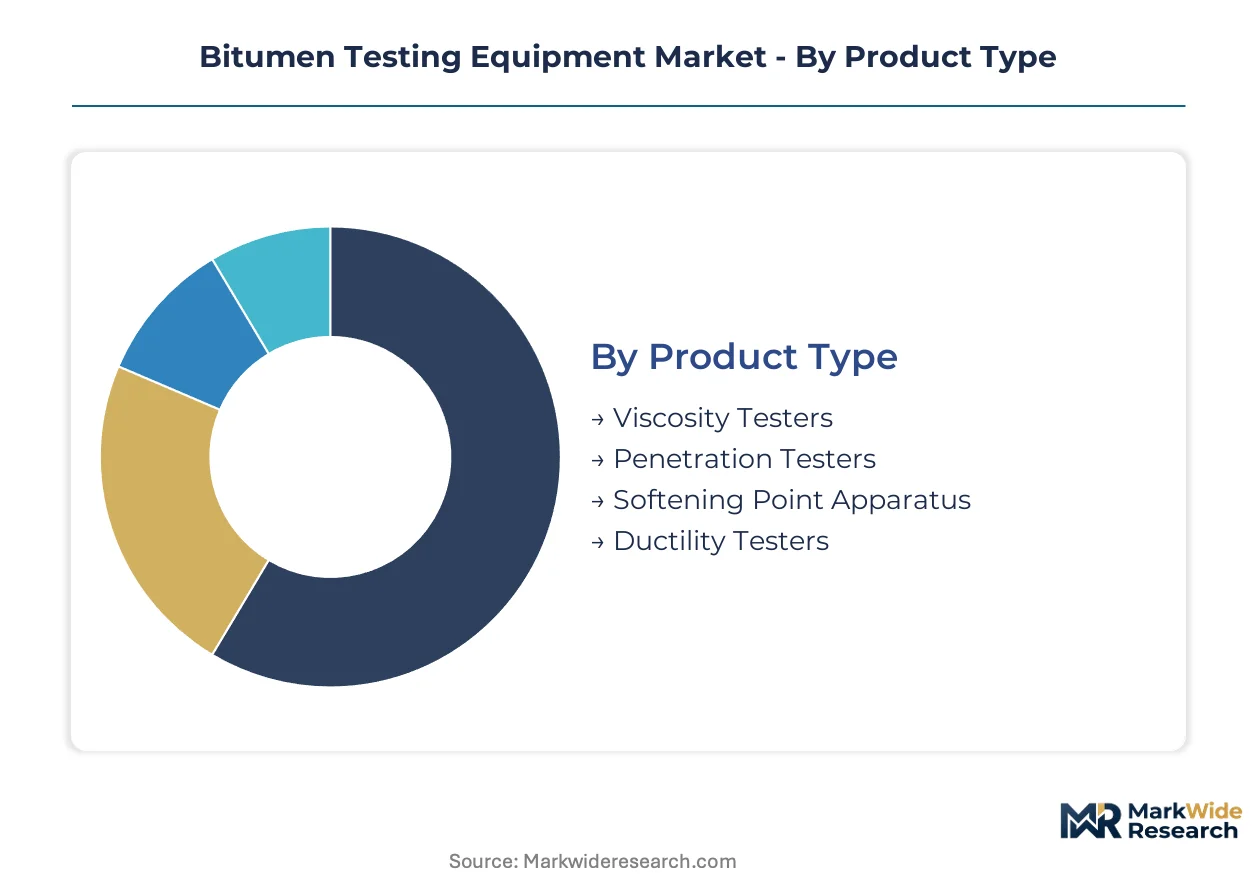
Equipment segmentation in bitumen testing reveals how laboratories prioritize capital deployment across precision tiers. Specification requirements from Germany's road research institutes and India's state highway departments create divergent demand profiles that reshape category performance.
Product Type:
Viscosity measurement systems anchor specification-grade procurement decisions for high-volume pavement design laboratories.
- Viscosity Testers:Rotational and capillary systems measure binder flow characteristics across temperature ranges from 60°C to 135°C. German road maintenance agencies under EU Green Deal mandates are refreshing these systems for sustainable infrastructure verification protocols.
- Penetration Testers:Standardized needle penetration apparatus evaluates binder consistency at 25°C per ASTM and EN norms. India's PLI scheme beneficiaries are equipping state highway department laboratories with digital penetration units for BIS certification compliance.
- Softening Point Apparatus:Ring-and-ball testers determine temperature susceptibility for binder grade classification. Municipal testing facilities in emerging markets favor manual configurations for capital efficiency.
- Ductility Testers:Elongation measurement systems assess binder deformation capacity under controlled temperature and extension rates. Research institutes specify these for polymer-modified binder characterization.
Viscosity testers lead on scale; penetration testers lead on momentum from India's infrastructure buildout.
End User:
Customer type segmentation tracks how procurement authority distributes across public agencies, private contractors, and research institutions.
- Construction:Hot-mix asphalt producers deploy rapid-testing configurations at batching plants for real-time binder grade verification. Indian private contractors under quality assurance penalty clauses are investing in portable viscosity platforms.
- Road Maintenance:Highway agencies operate central laboratories with full rheology suites for forensic pavement analysis. German state road authorities are expanding testing protocols under sustainable infrastructure mandates.
- Research Laboratories:University and institute facilities require precision rheometers for binder modification research. These sites prioritize安东 Paar-grade systems with temperature control precision to 0.01°C.
- Quality Control Facilities:Third-party testing laboratories serve contractor compliance verification with ISO 17025-accredited operations. India's expanding private laboratory sector favors service-unbundled procurement models.
Road maintenance agencies lead on scale; quality control facilities lead on momentum from certification requirements.
Technology:
Automation level determines capital intensity and operational expenditure structure for laboratory operators.
- Digital:Microprocessor-controlled instruments with data logging and basic connectivity. These systems balance precision with capital accessibility for mid-tier laboratories upgrading from manual platforms.
- Manual:Operator-dependent mechanical systems with minimal electronic components. Smaller laboratories in budget-constrained markets retain these for penetration and softening point testing.
- Automated:Robotic sample handling with integrated temperature control and cloud-connected data traceability. Premium positioning targets high-throughput facilities facing ISO 17025 audit requirements.
- Hybrid:Modular architectures allowing manual operation with digital upgrade pathways. This configuration supports phased capital deployment for expanding laboratory networks.
Digital systems lead on scale; automated platforms lead on momentum from data traceability mandates.
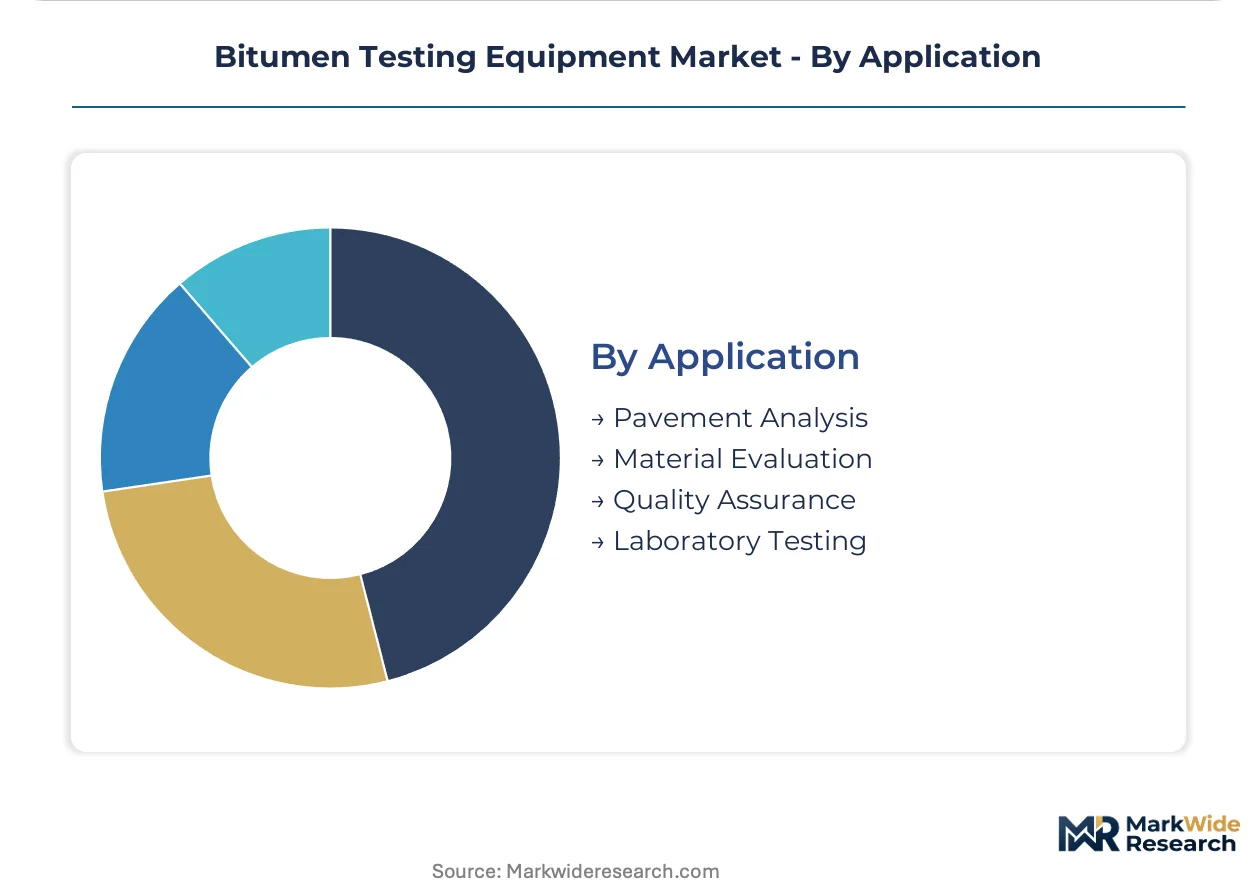
Application:
Use-case segmentation aligns equipment specification with decision points in pavement lifecycle management.
- Pavement Analysis:Forensic binder extraction and recovery systems evaluate field-aged material performance. Highway agencies deploy these for rehabilitation project design.
- Material Evaluation:New binder certification testing verifies supplier compliance with job mix formulas. Contractor laboratories concentrate procurement here for penalty clause protection.
- Quality Assurance:Statistical process control testing at mixing plants ensures continuous compliance. German agencies are piloting portable units for project-level spot-checks.
- Laboratory Testing:Central facility operations with full specification suites for research and dispute resolution. These installations require comprehensive temperature chamber capabilities.
Material evaluation leads on scale; quality assurance leads on momentum from field-deployment innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing bitumen testing equipment procurement as compliance cost differentials widen between jurisdictions with stringent environmental mandates and those prioritizing infrastructure velocity.
Germany
Road maintenance agencies under the EU Green Deal are expanding binder verification protocols for sustainable infrastructure certification. The EU F-Gas Regulation is accelerating replacement cycles for temperature-controlled testing chambers in German asphalt laboratories. Research institutes in Munich and Stuttgart are prioritizing suppliers with verified low-global-warming-potential refrigerant performance data.
India
State highway departments and private contractors are equipping laboratories under the PLI scheme for construction equipment. BIS and CEA certification protocols are filtering market access toward compliant suppliers with localized service networks. Laboratory buildouts concentrate in Maharashtra and Gujarat where highway construction quality mandates are tightening.
United States
State departments of transportation are piloting portable viscometer platforms for project-level compliance spot-checks at hot-mix asphalt plants. Federal Highway Administration guidelines on pavement management systems are redirecting procurement toward interoperable data formats. Deployment clusters form in Texas and California where highway agency laboratory networks are densifying.
China
National expressway construction programs are sustaining demand for high-throughput binder testing systems in provincial quality control facilities. Dual carbon goals under the 14th Five-Year Plan are beginning to shape equipment efficiency specifications. Equipment procurement concentrates in Jiangsu and Shandong provinces where road construction material testing infrastructure is expanding fastest.
United Arab Emirates
Federal infrastructure agencies are mandating enhanced binder characterization for desert climate pavement durability. The country's national standards body is aligning equipment certification with Gulf Cooperation Council harmonization initiatives. Testing laboratory investments cluster in Dubai and Abu Dhabi where quality assurance requirements for megaproject delivery are most stringent.
Bitumen Testing Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision instrumentation vendors commanding premium positioning in research-grade applications while regional fabricators compete on capital accessibility for routine compliance testing. The vendor base concentrates around three strategic archetypes: European precision-system specialists with established service infrastructure, Asian manufacturers scaling through public-sector procurement channels, and diversified laboratory equipment conglomerates leveraging cross-selling into asphalt testing workflows. Dominant competitive moves include backward integration into temperature control subsystems and geographic expansion through localized calibration service partnerships.
Among European precision-system specialists, Anton Paar GmbH and Controls Group occupy positions anchored by service infrastructure density across mature asphalt laboratory networks. Aimil Ltd. exemplifies the regional-fabricant archetype competing through localized support networks within India's expanding road construction quality ecosystem. These three companies represent distinct strategic postures: precision rheology specialization, service-based client retention, and emerging-market penetration through certification compliance.
| Leading Market Players |
|---|
| Matest S.p.A. |
| Controls Group |
| Humboldt Mfg. Co. |
| Elcometer Ltd. |
| Cooper Technology |
| Aimil Ltd. |
| Anton Paar GmbH |
| CANNON Instrument Company |
| Thermo Fisher Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
Crude bitumen benchmark pricing cascades through equipment manufacturing tiers, with thermal control subsystems and precision sensor modules absorbing petroleum-derived polymer and rare-earth magnet cost volatility before reaching laboratory procurement budgets.
Pricing Analysis
Distributor margins of 18-25% separate factory gate from laboratory procurement in European markets, compressing to 12-15% in India's PLI-accelerated direct-purchase channels. Three-tier pricing stratifies across automated premium platforms with ISO 17025 traceability, digital mid-range systems for state highway departments, and manual economy configurations for municipal facilities. Pricing pressure stems from India's BIS-CEA certification requirements forcing compliance investment without corresponding budget expansion. State highway departments exhibit highest price sensitivity; research institutes anchored by Anton Paar-grade precision specifications show lowest.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds are redirecting component sourcing from German and Italian precision-system specialists toward local fabrication partnerships for temperature chambers and mechanical frames. Critical inputs draw from China's rare-earth magnet supply for rheometer motors, German refrigerant compressor technology for thermal control, and Japanese load-cell sensors for precision measurement. Single-source vulnerability concentrates in EU F-Gas Regulation-compliant refrigerant alternatives, where verified performance data limits supplier pools. Distribution runs through Controls Group's European service infrastructure and Aimil Ltd.'s India-centric calibration networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Germany's EU Green Deal-mandated equipment refresh cycles and India's PLI-subsidized laboratory buildouts creates divergent margin structures for suppliers with dual-hemisphere capabilities.
For Market Incumbents: Extend service infrastructure density into India's expanding state highway department networks before PLI scheme maturation consolidates vendor relationships. Backward integration into temperature control subsystem production mitigates EU F-Gas Regulation refrigerant transition risks. Anton Paar-grade precision positioning requires calibration technician training pipelines that outpace competitor replication in emerging markets. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany opens a window for alternative-refrigerant chamber specialists to displace incumbent suppliers lacking verified low-GWP performance data. Portable viscometer platforms for US state DOT project-level spot-checks represent the most penetrable white-space segment. Go-to-market through specialized metrology service providers in India's unbundled procurement environment bypasses capital-intensive direct sales cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with regional fabricators possessing BIS-CEA certification pathways and established calibration service networks in India's quality control facility expansion. Long-term viability hinges on recurring revenue from IoT-enabled remote diagnostics subscriptions rather than transactional equipment sales. Watch for ISO 17025 accreditation timeline compression as inflection signal for laboratory procurement velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Temperature Control Subsystems | EU F-Gas Regulation compliance secures refrigerant transition positioning for German laboratory refresh cycles. |
| Calibration Service Network Geographic Expansion | Localized BIS-CEA certification support captures India's PLI-accelerated state highway department procurement. |
| IoT-Enabled Remote Diagnostics Platform Launch | Cloud-based data traceability opens subscription revenue streams from ISO 17025-accredited quality control facilities. |
| Portable Viscometer Product Line Introduction | Field-deployable binder verification addresses US state DOT pilot programs for project-level compliance spot-checks. |
| Alternative Refrigerant Chamber Certification Program | Verified low-GWP performance data filters supplier selection for German road research institute procurement. |
Methodological Framework
Bottom-up laboratory equipment procurement modeling reconciled against top-down asphalt testing infrastructure investment tracking forms the analytical core of this study. Primary interviews with state highway department procurement officers, private contractor quality control managers, research institute laboratory directors, and calibration service technicians combined with secondary validation from BIS certification registries, EU Green Deal implementation reports, PLI scheme beneficiary disclosures, and FHWA pavement management system guidelines. Trade data from construction equipment import records and laboratory accreditation body databases anchored supply-side triangulation.
Historical trendline analysis of equipment refresh cycles in German road maintenance agencies and laboratory buildout velocity in Indian state highway departments established baseline growth parameters across the projection horizon. Segmentation modeling incorporated product type automation level, end-user procurement authority, technology tier, and application use-case dimensions. CAGRs derived from equipment unit deployment rates reconciled against binder testing volume forecasts from asphalt consumption projections. EU F-Gas Regulation compliance deadlines and India's PLI scheme phase-out timelines served as industry-specific forecast boundary conditions.
Revisions become necessary when EU Green Deal implementation intensity shifts, PLI scheme eligibility criteria tighten, or refrigerant alternative performance data invalidates temperature chamber replacement assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Light Towers Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
France Metal Fabrication Equipment Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Solar Pile Driving Equipment Market