
 North America: Heavy Construction Equipment Market | 2026-2036
North America: Heavy Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America: Heavy Construction Equipment Market Outlook
Market Context
Mexico is rewriting production geography for heavy construction equipment as OEMs expand assembly capacity near Monterrey and Saltillo to serve US demand with reduced logistics exposure. Caterpillar Inc. leverages its extensive dealer network and remanufacturing infrastructure to sustain aftermarket revenue streams across the continent. Deere & Company anchors its position in road-building applications through integrated precision grading technology and fleet management platforms. Komatsu Ltd. differentiates via autonomous haulage systems that compete directly in mining-adjacent construction segments.
Technical Definition and Segment Structure
Heavy construction equipment encompasses self-propelled machines exceeding 12,000 pounds operating weight, engineered for earthmoving, lifting, and material placement through diesel, hydraulic, or electric power transmission systems, primarily serving capital-intensive civil engineering and resource extraction projects. Excavators and loaders command the largest installed base due to versatility across road construction and site preparation workflows, while hybrid and electric technology segments attract disproportionate R&D allocation as contractors face Scope 1 emissions accounting pressure. Diesel-powered equipment retains margin concentration in remote mining and demolition applications where charging infrastructure remains uneconomical.
Regulatory Framework and Outlook
EPA Tier 4 Final and California Air Resources Board off-road regulations are accelerating powertrain diversification timelines, forcing manufacturers to certify zero-emission variants for public-sector procurement eligibility. OSHA crane operator certification requirements and FAA coordination protocols for aerial work platforms shape product design standards and training service attach rates. Stakeholders must monitor state-level Buy Clean procurement mandates and evolving federal infrastructure funding disbursement rhythms to align fleet positioning with project pipeline visibility.
Market Dynamics
EPA Tier 4 Final emissions standards are compressing diesel equipment margins while forcing manufacturers to recertify entire product lines for zero-emission variants. This regulatory pressure intersects with concentrated demand from the Texas-Louisiana petrochemical corridor, creating a bifurcated market where electric powertrains dominate public procurement and diesel retains mining and demolition applications.
Growth Catalysts
- IIJA Bridge Formula Program:Federal highway and bridge renewal timelines are compressing contractor procurement cycles, forcing fleet expansion decisions ahead of traditional replacement schedules.
- Texas-Louisiana Energy Corridor:Sustained petrochemical construction activity and LNG export facility development are absorbing high-tonnage excavators and crawler cranes at above-replacement rates.
- Monterrey-Saltillo Assembly Zone:Mexican production capacity expansion is reducing logistics exposure for US-bound equipment, shortening lead times for just-in-time fleet scaling.
Market Restraints
- Steel and Hydraulics Input Volatility:Structural steel and high-pressure hydraulic component costs fluctuate with energy prices, compressing OEM margins on fixed-price municipal contracts.
- Charging Infrastructure Gaps:Remote mining and demolition sites lack grid connectivity for electric equipment, forcing diesel retention where electrification economics are technically viable.
- OSHA Certification Bottlenecks:Crane operator certification delays extend project startup timelines, constraining equipment utilization rates during peak construction seasons.
Strategic Opportunities
- California Buy Clean Procurement:State-level embodied carbon mandates for public infrastructure are creating preferential market access for OEMs with verified low-carbon supply chains.
- Autonomous Haulage Convergence:Integration of autonomous control systems with conventional construction workflows opens mining-adjacent segments to technology-forward fleet operators.
- Remanufacturing-as-a-Service:Dealer networks are unbundling powertrain rebuilds from new equipment sales, capturing aftermarket revenue through subscription-based component refresh programs.
Industry Challenges
- Electrical Technician Scarcity:Fleet maintenance departments lack sufficient high-voltage systems training to support hybrid and electric equipment field repairs, extending downtime.
- Multi-Standard Certification Complexity:Equipment must simultaneously satisfy EPA Tier 4 Final, CARB off-road regulations, and emerging state-level zero-emission mandates, multiplying compliance engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America: Heavy Construction Equipment Market |
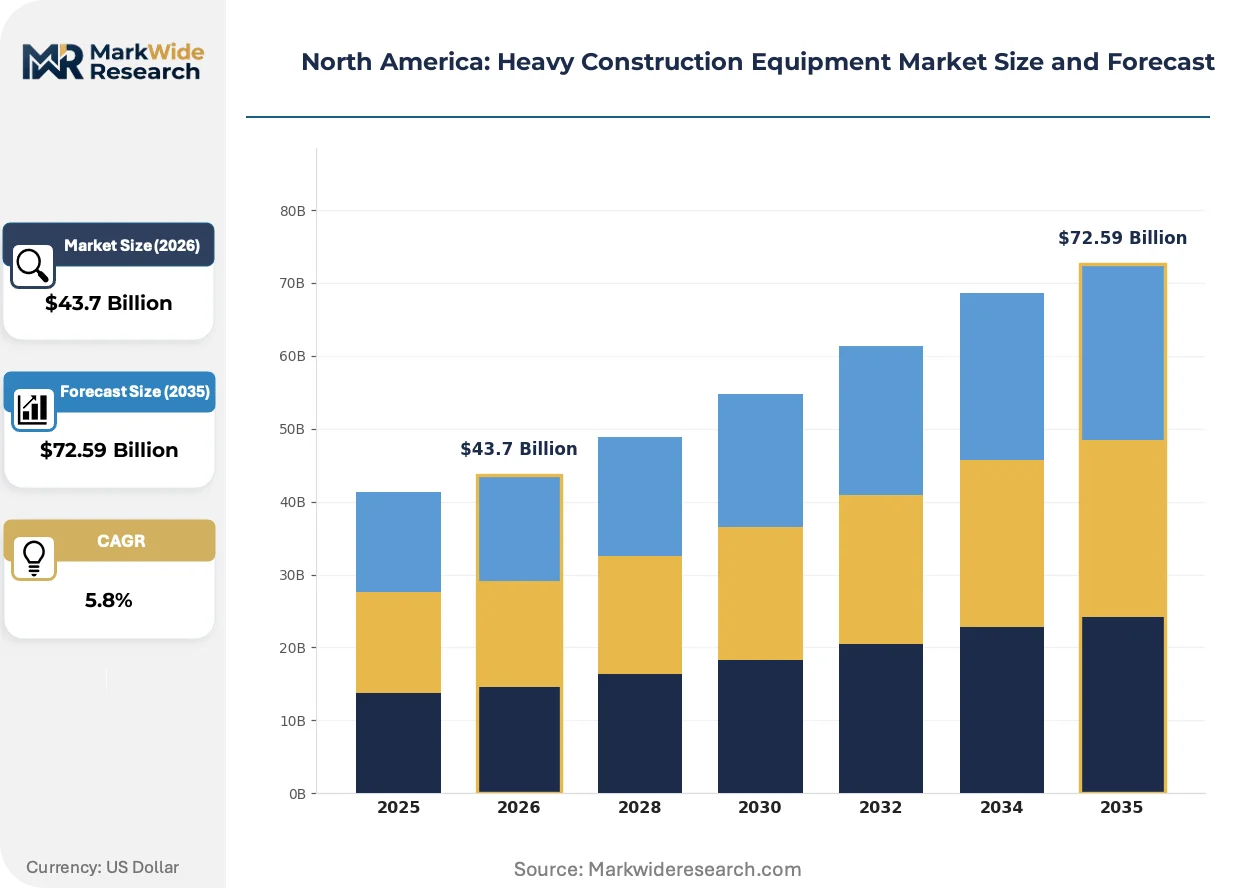
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $72.59 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Loaders Technology: Hybrid, Electric, Diesel, Hydraulic End User: Contractors, Government Agencies, Mining Firms, Infrastructure Developers Application: Road Construction, Site Preparation, Demolition, Material Handling |
| Companies Covered | Caterpillar Inc., Deere & Company, Komatsu Ltd., Volvo Construction Equipment, CNH Industrial N.V., Hitachi Construction Machinery Co., Ltd., Liebherr Group, Terex Corporation, Doosan Infracore, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America: Heavy Construction Equipment Market Strategic Shifts
Powertrain electrification is collapsing the historical separation between on-road and off-road equipment engineering, forcing OEMs to source battery systems from automotive suppliers. This convergence is reshaping competitive positioning around energy management software rather than mechanical durability alone.
Electric drivetrain architecture is collapsing the cost premium between hybrid and full-electric configurations in the 12-20 ton excavator class. Municipal contractors in California and New York are specifying battery-electric loaders for urban infrastructure work, compressing payback periods through fuel cost avoidance and reduced maintenance intervals. Equipment financing structures are adapting to recognize residual value uncertainty in first-generation electric platforms.
EPA Tier 4 Final and CARB off-road regulations are accelerating powertrain diversification timelines beyond manufacturer R&D cycles. OEMs must certify zero-emission variants to maintain public-sector procurement eligibility, forcing parallel development tracks that strain engineering resources. The Texas-Louisiana corridor retains diesel concentration due to remote site logistics, creating a geographic split in technology adoption.
Rental channel consolidation is compressing contractor equipment ownership cycles, shifting capital deployment from fleet acquisition to operational technology. Large regional rental houses are bundling telematics and fleet management platforms with hourly equipment rates, displacing traditional dealer relationships in the Southeast and Midwest. This model concentrates purchasing power among fewer buyers, pressuring OEM pricing discipline.
North America: Heavy Construction Equipment Market Segmentation
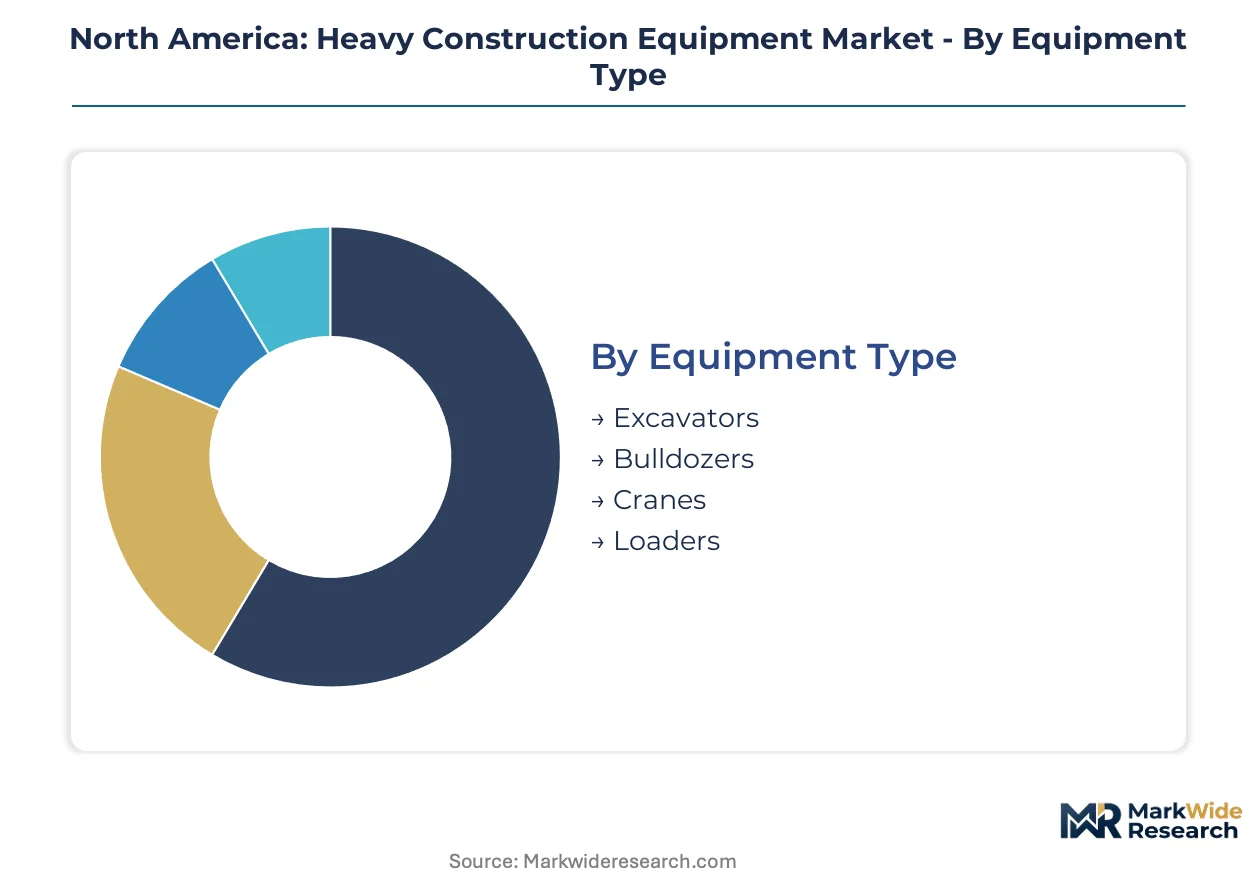
Segmentation reveals how EPA Tier 4 Final compliance costs and electrification timelines fragment procurement patterns across customer types and applications. Contractors, government agencies, and mining firms now source from diverging technology portfolios shaped by site access to charging infrastructure and public-sector zero-emission mandates.
Equipment Type:
Mature earthmoving platforms anchor replacement demand while emerging autonomous-capable units reshape fleet composition in mining-adjacent construction.
- Excavators:Tracked and wheeled configurations dominate site preparation and utility trenching workflows across the Texas-Louisiana corridor. Municipal contractors in California specify compact electric models for urban infrastructure where emissions compliance intersects with noise restrictions.
- Loaders:Wheel loaders integrate precision grading technology for road construction finish work, with integrated fleet management platforms now standard on mid-size units. Demand concentrates in highway renewal projects where IIJA funding compresses procurement timelines.
- Bulldozers:Crawler dozers retain diesel concentration in remote mining site development where grid connectivity remains uneconomical for electrification.
- Cranes:Crawler and rough-terrain configurations serve LNG export facility construction along the Gulf Coast, with OSHA certification requirements extending project startup timelines.
Excavators handle the majority of throughput; electric loaders are expanding most quickly on share.
Technology:
Cost tiers separate proven diesel infrastructure from emerging powertrain architectures requiring new dealer service capabilities and financing structures.
- Diesel:Tier 4 Final-compliant engines retain margin concentration in demolition and remote mining applications where charging infrastructure gaps persist. The Texas-Louisiana energy corridor absorbs high-horsepower diesel excavators and crawler cranes at above-replacement rates.
- Electric:Battery-electric architectures collapse operating cost premiums in the 12-20 ton excavator class, with California and New York municipalities specifying zero-emission loaders for urban work. Residual value uncertainty in first-generation platforms complicates equipment financing structures.
- Hybrid:Parallel hybrid systems bridge diesel reliability with fuel cost avoidance in intermittent-duty road construction applications.
- Hydraulic:Conventional hydraulic power transmission retains installed base in legacy fleet maintenance and remanufacturing programs.
Diesel retains volume leadership; electric configurations are climbing the fastest as public procurement eligibility tightens.
End User:
Customer type determines technology access, with government procurement eligibility rules and mining firm autonomy requirements driving divergent fleet specifications.
- Contractors:Regional construction firms face compressed procurement cycles from IIJA bridge and highway renewal timelines, forcing fleet expansion ahead of traditional replacement schedules. Rental channel consolidation shifts capital deployment from ownership to operational technology subscriptions.
- Government Agencies:State transportation departments and municipal authorities enforce zero-emission mandates through Buy Clean procurement policies, restricting eligible equipment to certified low-carbon supply chains. California and New York specifications now exclude non-electric loaders from urban infrastructure bids.
- Mining Firms:Autonomous haulage system integration opens mining-adjacent construction segments to technology-forward fleet operators with captive maintenance capabilities.
- Infrastructure Developers:Federal funding recipients align fleet positioning with project pipeline visibility, prioritizing equipment availability over technology novelty.
Contractors deploy the largest fleet volume; government agencies are gaining share fastest through electrification mandates.
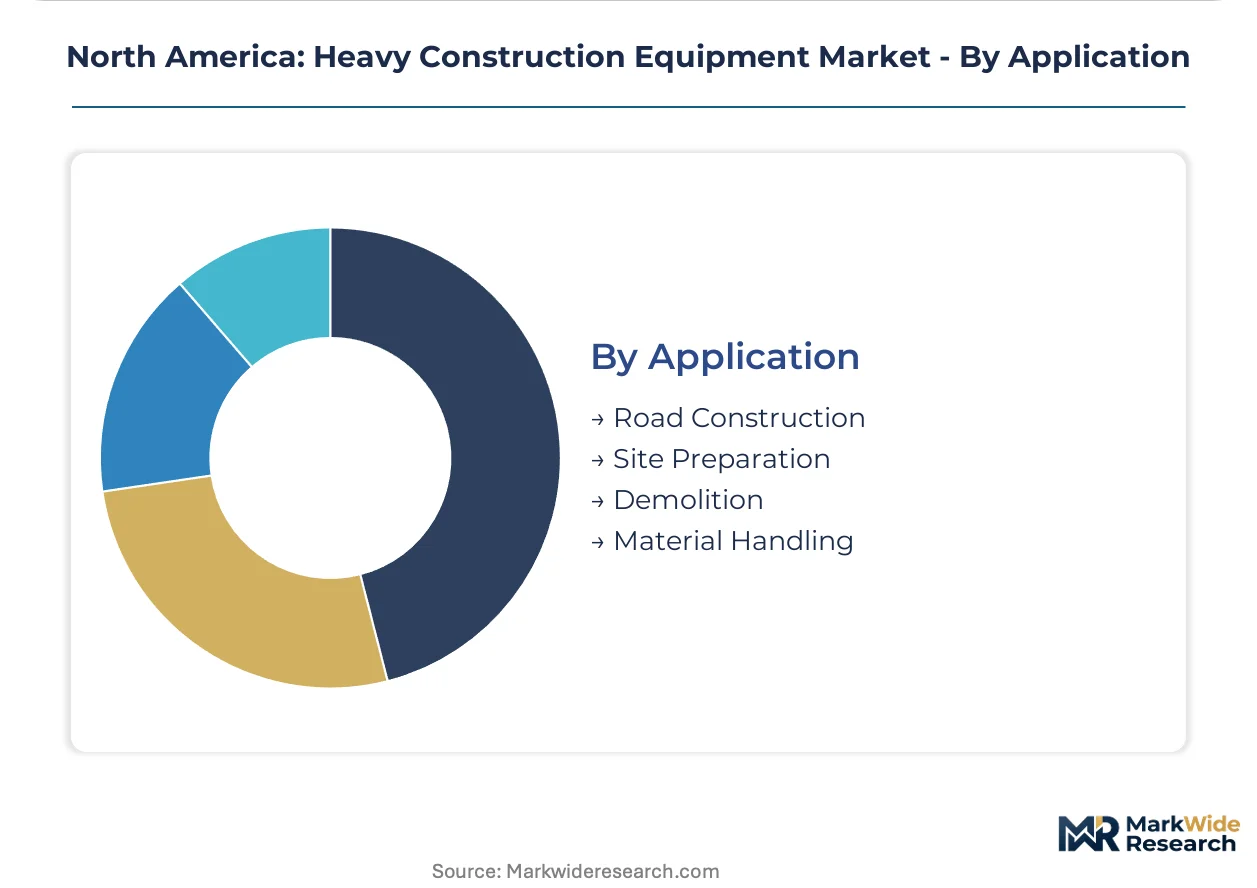
Application:
Geography and site characteristics segment demand, with urban infrastructure work favoring electric configurations and remote resource extraction retaining diesel concentration.
- Road Construction:Highway renewal and bridge replacement projects absorb high-tonnage excavators and wheel loaders, with precision grading technology now standard on mid-size units. IIJA funding disbursement rhythms create lumpy demand patterns across state transportation departments.
- Site Preparation:Earthmoving and grading workflows in the Texas-Louisiana petrochemical corridor require continuous-duty equipment specifications that strain electric platform duty cycles.
- Demolition:High-impact hydraulic attachments and remote site logistics favor diesel retention where electrification economics are technically viable but infrastructure-constrained.
- Material Handling:Loader and forklift applications in LNG export facility construction concentrate demand for rough-terrain material handlers with extended reach specifications.
Road construction commands the largest equipment allocation; site preparation applications are expanding most quickly with energy corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly capacity clusters near Monterrey and Saltillo are shortening logistics pipelines for US-bound equipment, while Canadian mining operations and American infrastructure corridors sustain differentiated demand profiles across the continent.
United States
The Texas-Louisiana petrochemical corridor absorbs high-tonnage excavators and crawler cranes at above-replacement rates, driven by LNG export facility construction and sustained energy infrastructure development. EPA Tier 4 Final emissions standards compress diesel equipment margins while forcing zero-emission certification for public-sector procurement eligibility. California and New York municipalities now specify battery-electric loaders for urban infrastructure bids, creating a coastal-interior technology divide.
Canada
Remote mining site development in Alberta and British Columbia retains diesel concentration where grid connectivity remains uneconomical for electrification. Natural Resources Canada clean technology funding accelerates pilot deployments of hybrid powertrains in intermittent-duty applications. The Prairie Provinces anchor replacement demand for high-horsepower bulldozers serving oil sands and mineral extraction workflows.
Mexico
OEMs are expanding assembly capacity near Monterrey and Saltillo to serve US demand with reduced logistics exposure and shortened lead times for just-in-time fleet scaling. Mexican federal manufacturing incentives under the IMMEX program support component supplier co-location. The Bajío Region concentrates precision machining capacity for hydraulic systems and powertrain components bound for North American final assembly.
North America: Heavy Construction Equipment Market Competitive Environment
Integrated full-line manufacturers and specialized technology providers split the market into distinct competitive spheres, with scale advantages in distribution networks confronting agility in autonomous and electrified subsystems. The vendor base stratifies across three archetypes: diversified industrial conglomerates with captive financing arms, construction-equipment pure-plays with precision technology integration, and mining-technology specialists extending into adjacent construction workflows. Dominant competitive moves include backward integration into battery supply chains and geographic consolidation of remanufacturing infrastructure to capture aftermarket revenue streams.
Among diversified industrial conglomerates, Caterpillar Inc. and Deere & Company exemplify archetypes built on dealer network density and integrated precision technology platforms. Komatsu Ltd. occupies a position bridging construction and mining applications through autonomous system development. These three anchors demonstrate how scale-driven service infrastructure and technology-forward product portfolios define sustainable positioning against rental channel consolidation and electrification compliance costs.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Deere & Company |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| CNH Industrial N.V. |
| Hitachi Construction Machinery Co., Ltd. |
| Liebherr Group |
| Terex Corporation |
| Doosan Infracore |
| Others |
Value Chain & Pricing Dynamics
Steel mills in the US Midwest and hydraulic component foundries in Mexico's Bajío Region anchor cost structures that cascade through OEM pricing tiers, concentrating margin capture among integrated manufacturers with captive forging capacity.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across the North American heavy construction equipment market, separating Tier 4-compliant diesel platforms from zero-emission electric variants through certification cost layering. Three-tier pricing stratifies across premium autonomous-capable units, standard connected equipment with telematics integration, and economy-grade mechanical configurations for rental fleet turnover. Cost compression in the mid-tier standard segment intensifies because Mexican assembly expansion shortens logistics pipelines and compresses landed cost premiums. Municipal procurement teams exhibit highest price sensitivity due to fixed-budget constraints, while mining firms demonstrate lowest sensitivity given captive maintenance capabilities and uptime-driven total cost of ownership calculations.
Supply Chain Analysis
High-grade structural steel from US mini-mills, precision hydraulic castings from Mexico, and battery cell assemblies from South Korean suppliers feed North American final assembly. OEMs draw from dual-source arrangements for engines and drivetrains to mitigate tariff exposure at component tiers. Distribution runs through consolidated rental houses in the Southeast and Midwest, displacing traditional dealer relationships and concentrating purchasing power among fewer volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rental channel consolidation across the Southeast and Midwest has shifted buyer power toward fewer volume purchasers, compressing OEM pricing discipline and elevating procurement sophistication among fleet operators.
For Market Incumbents: Entrench aftermarket revenue through remanufacturing-as-a-service subscriptions that lock in fleet operators with powertrain refresh programs. Deepen backward integration into battery supply chains to secure cell allocation ahead of zero-emission procurement mandates. Defend against technology-forward entrants by accelerating autonomous haulage system certification for mining-adjacent construction segments.
For New Entrants and Emerging Players: The Canadian Prairie Provinces present underpenetrated terrain for hybrid powertrain specialists serving oil sands site development where grid connectivity remains uneconomical for full electrification. Target demolition contractors in remote jurisdictions with diesel-retention solutions that address charging infrastructure gaps. Enter through telematics-integrated service bundling that matches rental house platform offerings without requiring fleet ownership.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional rental houses consolidating across the Midwest and Southeast. Long-term viability hinges on fleet technology refresh capabilities and software platform ownership rather than equipment volume alone. Watch for California Buy Clean procurement mandate expansion into additional state transportation departments as the signal for accelerated electric platform valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captures cell allocation priority ahead of EPA zero-emission certification deadlines. |
| Autonomous Haulage System Certification | Opens mining-adjacent construction segments to technology-forward fleet operators. |
| Remanufacturing-as-a-Service Launch | Converts aftermarket service into recurring subscription revenue with dealer network leverage. |
| Monterrey-Saltillo Capacity Expansion | Shortens lead times for just-in-time fleet scaling while reducing logistics exposure. |
| California Buy Clean Supply Chain Verification | Secures preferential procurement eligibility for public-sector infrastructure bids. |
Study Parameters
A standing panel of fleet maintenance directors, OEM procurement managers, rental house operations heads, and aftermarket service technicians provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with equipment operators and dealer network principals, validated against secondary sources including EPA certification filings, OSHA crane operator training records, and IIJA funding disbursement databases. Bottom-up equipment shipment tallies from Mexican assembly zones triangulated against top-down infrastructure spending projections from state transportation departments.
Scenario bracketing anchored volume and value outputs across the projection horizon, with segmentation modeling spanning equipment type, powertrain technology, end-user archetype, and application intensity. CAGRs derived from regression analysis of replacement cycle compression against federal funding timelines, with cross-checks against steel price indices and hydraulic component trade flows. Forecast inputs incorporated electrification adoption curves calibrated to CARB off-road regulation precedents and charging infrastructure deployment maps.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric pure-plays or autonomous system specialists would shift outcomes beyond modeled ranges. Cross-checking against National Association of Manufacturers capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Construction Equipment Market
Construction Equipment
Rotomolding Market
Construction Equipment
Ultrasonic Welding Machine Market
Construction Equipment
Bitumen Sprayer Market
Construction Equipment
Roadheaders Market
Construction Equipment
Rough Terrain Crane Market
Construction Equipment
Vibratory Rammer Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Winch Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Industrial Agitators Market