
 Indonesia Data Center Physical Security Market | 2026-2036
Indonesia Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Physical Security Market Insights
Modular security bundling is decoupling traditional all-in-one physical protection contracts into separable components buyers can mix across vendors. Honeywell International Inc. leverages its building automation heritage to anchor integrated access control offerings in Indonesian hyperscale projects. Axis Communications AB specializes in edge-enabled surveillance architectures that compete on latency-sensitive monitoring for financial services data halls. Bosch Sicherheitssysteme GmbH dominates perimeter detection systems through its manufacturing scale across Southeast Asian supply channels.
Indonesia Data Center Physical Security encompasses layered protection systems—biometric readers, video analytics platforms, intrusion detection sensors, and guard-force coordination software—engineered to prevent unauthorized physical access, environmental sabotage, and equipment theft at facilities housing critical computing infrastructure. The primary commercial purpose centers on ensuring continuous uptime for cloud, colocation, and enterprise server operations where even brief physical breaches trigger cascading financial and reputational damage. Surveillance cameras lead technology investment as AI-powered video analytics displace passive recording systems across Tier III and IV facilities. Installation services capture disproportionate margin pools due to complex integration with existing building management systems and Indonesia's fragmented contractor landscape. Cloud providers represent the fastest-growing end-user segment as foreign hyperscalers commit to local data residency requirements.
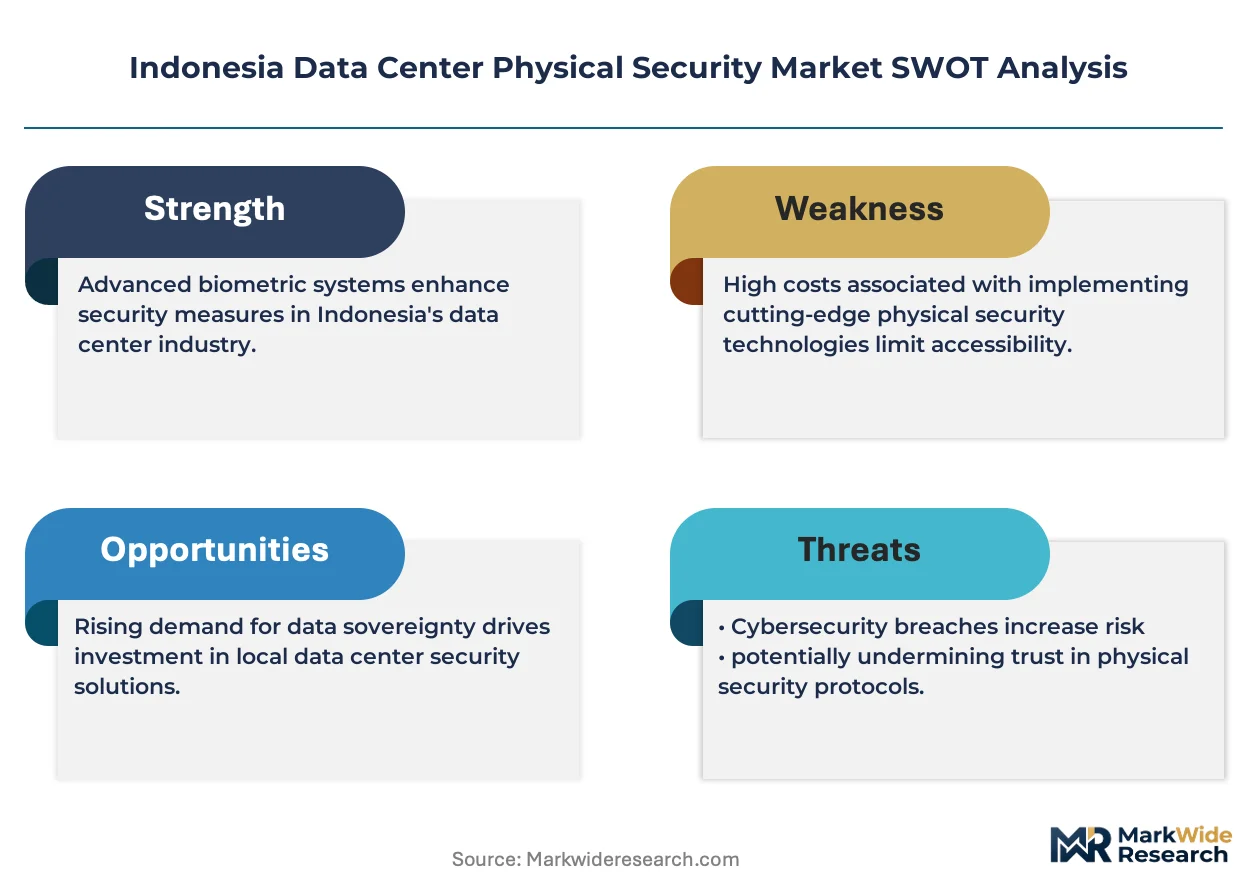
BSSN, Indonesia's national cyber and encryption agency, mandates physical security baselines for critical information infrastructure operators through sector-specific implementation guidelines. The country's PLI scheme incentives and Ministry of Communication and Informatics data localization rules compound compliance complexity by requiring demonstrable access control and audit trails for domestically stored data. Stakeholders must monitor evolving enforcement patterns around certification requirements that determine market access for imported security hardware and software platforms.
Market Dynamics
Modular security bundling is fragmenting traditional integrated contracts across Indonesian hyperscale campuses, as cloud operators demand separable components they can source across specialized vendors rather than single-source turnkey solutions.
Growth Catalysts
- BSSN Critical Infrastructure Mandates:Indonesia's national cyber and encryption agency mandates physical security baselines for operators of critical information infrastructure, forcing facility upgrades across Tier III and IV data centers.
- Foreign Hyperscaler Facility Expansion:Cloud providers in Jakarta and Batam are scaling campus footprints to meet data residency requirements, directly driving demand for biometric access control and perimeter detection systems.
- AI-Powered Video Analytics:Edge-enabled surveillance architectures with real-time threat detection are displacing passive recording systems in financial services data halls where latency-sensitive monitoring commands premium positioning.
Market Restraints
- Imported Hardware Certification Friction:BSSN and Ministry of Communication and Informatics certification requirements for security hardware create extended approval timelines that delay project commissioning.
- Fragmented Contractor Landscape:Complex integration with existing building management systems requires specialized installation expertise that concentrates among a limited pool of qualified local integrators.
- High Capex Intensity for Tier IV Compliance:Multi-layered biometric, surveillance, and intrusion detection systems impose substantial upfront investment that filters out smaller colocation operators.
Strategic Opportunities
- Edge Computing Facility Proliferation:Distributed edge nodes outside Jakarta's core hyperscale clusters present underpenetrated demand for compact, rapidly deployable physical security modules.
- Convergence of Physical-Cyber Security Platforms:Integration of access control systems with SIEM and SOAR cybersecurity tools creates bundled value propositions for enterprise data center operators.
- PLI Scheme Incentives:Indonesia's domestic manufacturing incentives for electronic components encourage local assembly of surveillance and sensor hardware, reducing import dependency.
Industry Challenges
- Integration Complexity with Legacy Building Systems:Retrofitting modern biometric readers and video analytics into existing facility management infrastructure requires custom middleware development that extends deployment timelines.
- Specialized Technician Scarcity:Shortage of certified professionals capable of calibrating multi-factor authentication systems and AI-enabled surveillance platforms constrains installation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Physical Security Market |
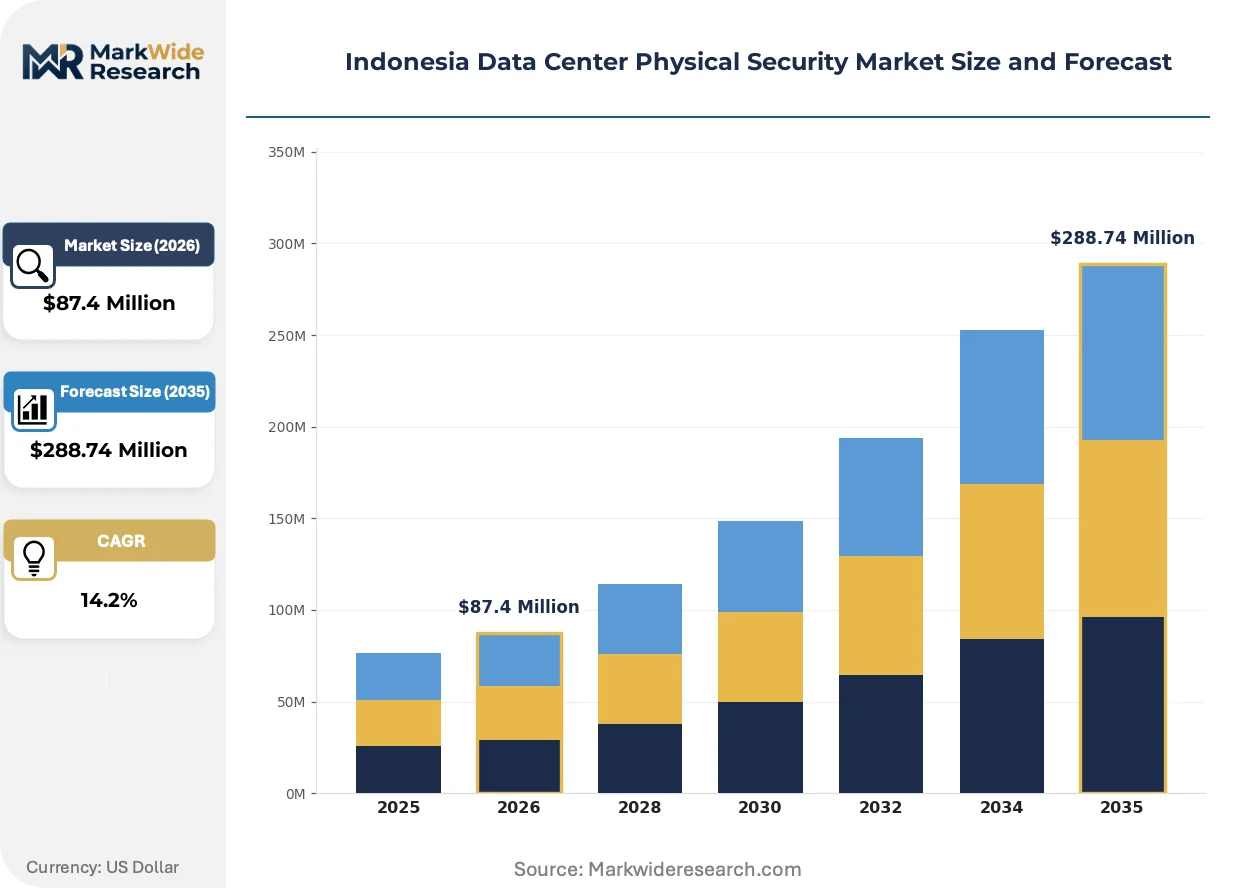
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $288.74 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Technology: Access Control, Surveillance Cameras, Perimeter Security, Alarm Systems Service Type: Installation, Maintenance, Consulting, Monitoring End User: Telecommunication, Cloud Providers, Enterprises, Government Deployment: On-premise, Hybrid, Cloud-based, Dedicated |
| Companies Covered | Bosch Sicherheitssysteme GmbH, Honeywell International Inc., Axis Communications AB, ABB Ltd, Johnson Controls, Cisco Systems Inc., Schneider Electric, ASSA ABLOY, Convergint Technologies LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Physical Security Market Trends and Innovations
Edge-native security architectures are compressing response times for threat detection while regulatory pressure tightens compliance frameworks around critical data infrastructure protection.
AI-powered video analytics with embedded GPU processing is electrifying surveillance deployment models across Indonesian financial services data halls. Tier III and IV facilities in Jakarta are adopting these systems within eighteen-month refresh cycles. The technology is electrifying competitive positioning by enabling real-time behavioral analysis that passive recording systems cannot replicate.
BSSN's sector-specific implementation guidelines for critical information infrastructure operators mandate demonstrable access control and audit trail capabilities. The regulation forces facility operators to document physical security posture to maintain operational licenses. Cloud providers building hyperscale campuses face the steepest compliance burden as they scale to meet data localization rules.
Buyer preference is gravitating toward outcome-based service contracts where vendors guarantee uptime-linked performance rather than equipment-only procurement. System integrators are displacing traditional hardware distributors as the primary channel for large campus deployments. This pattern concentrates in Java-based hyperscale projects where foreign operators prioritize risk transfer over capital ownership.
Indonesia Data Center Physical Security Market Segmentation
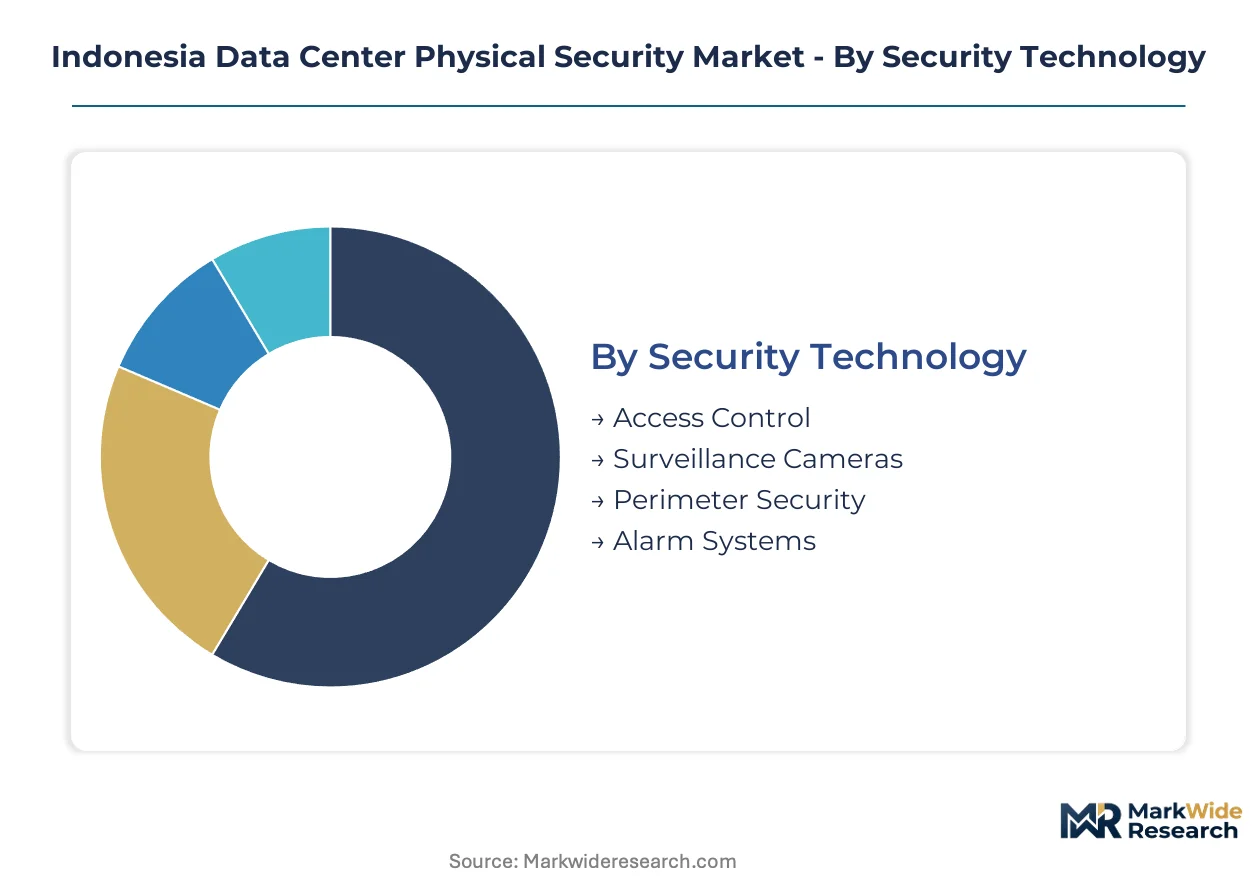
Indonesia's data center physical security market fragments across technology maturity, service delivery models, and facility ownership structures. Buyers mix standardized hardware with customized integration to balance compliance mandates against capital efficiency.
Security Technology:
Customization intensity varies sharply across this category, with biometric and AI-enabled systems demanding bespoke calibration while perimeter sensors deploy in standardized configurations.
- Surveillance Cameras:AI-powered video analytics platforms with embedded GPU processing enable real-time behavioral analysis in financial services data halls. Jakarta's Tier III and IV facilities are refreshing these systems within compressed cycles to meet BSSN audit requirements for continuous monitoring documentation.
- Access Control:Multi-factor biometric readers combining fingerprint, iris, and facial recognition dominate hyperscale campus deployments. Cloud providers in Batam and Jakarta demand separable components they can source across specialized vendors rather than single-source turnkey solutions.
- Perimeter Security:Intrusion detection sensors and physical barriers protect facility boundaries against unauthorized entry attempts.
- Alarm Systems:Environmental and intrusion alert networks integrate with building management systems for coordinated response protocols.
Most installed capacity flows through Surveillance Cameras. Expansion is steepest in Access Control.
Service Type:
Margin capture concentrates in high-touch integration work where fragmented local contractor capacity creates supply bottlenecks.
- Installation:Complex integration with legacy building management systems and multi-vendor security stacks requires specialized middleware development. Indonesia's limited pool of certified integrators extends project timelines and concentrates margin among qualified providers.
- Consulting:Compliance architecture design for BSSN and Ministry of Communication and Informatics certification requirements commands premium positioning. Foreign hyperscalers building Jakarta campuses prioritize risk transfer through outcome-based contracts over equipment-only procurement.
- Maintenance:Recurring service agreements ensure system uptime and firmware updates for AI-enabled surveillance platforms.
- Monitoring:Guard-force coordination software and centralized alert management support 24/7 physical security operations.
Installation captures the dominant share of service revenue. Consulting is climbing the fastest as regulatory complexity intensifies.
End User:
Facility ownership type determines procurement sophistication, with foreign capital driving modular sourcing patterns distinct from domestic enterprise preferences.
- Cloud Providers:Foreign hyperscalers expanding Jakarta and Batam footprints to satisfy data residency mandates represent the steepest expansion trajectory. These buyers decouple traditional all-in-one physical protection contracts into separable components sourced across specialized vendors.
- Telecommunication:Established operators upgrading legacy facilities face retrofit complexity when integrating modern biometric readers into existing infrastructure. Java-based campuses concentrate demand for perimeter detection systems compliant with national critical infrastructure directives.
- Enterprises:Domestic corporations building private data halls prioritize standardized security bundles over customized architectures.
- Government:Public sector facilities follow BSSN-mandated baselines for critical information infrastructure protection.
Telecommunication maintains the largest installed base. Cloud Providers are gaining share fastest.
Deployment:
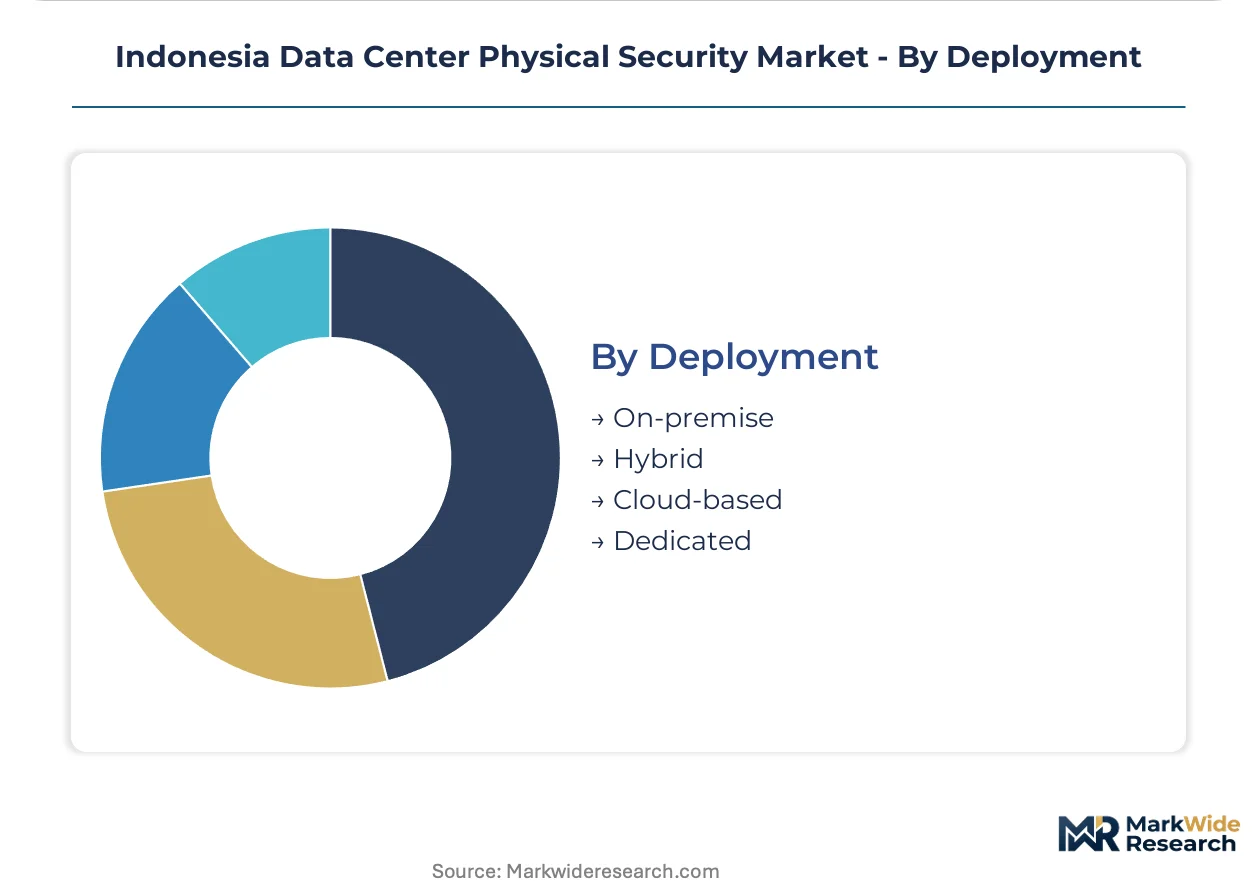
Architecture choice reflects latency requirements and data sovereignty pressures, with hybrid models emerging as the compromise position.
- On-premise:Dedicated physical security infrastructure within facility boundaries dominates Tier III and IV compliance-sensitive installations. Java-based hyperscale clusters require localized biometric and surveillance systems to satisfy audit trail mandates.
- Hybrid:Edge-native security architectures combining on-site sensors with cloud-based analytics compress threat detection response times. Distributed edge nodes outside Jakarta's core present underpenetrated demand for rapidly deployable physical security modules.
- Cloud-based:Centralized monitoring platforms aggregate alerts from multiple facility locations.
- Dedicated:Single-tenant security stacks serve operators with isolated compliance requirements.
On-premise retains the dominant deployment share. Hybrid architectures show the steepest adoption curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Indonesia data center physical security industry traces its commercial roots to Jakarta's early 2010s cloud infrastructure buildouts, when foreign operators first established local presence under emerging data residency frameworks.
Java
Java hosts the nation's densest concentration of Tier III and IV facilities, with hyperscale campuses clustering around Jakarta and Batam. BSSN's critical infrastructure mandates force continuous security upgrades across these installations. Cloud providers in Cikarang and Tangerang are expanding biometric access control footprints to satisfy audit trail requirements for data localization compliance.
Sumatra
Sumatra's emerging data center corridor leverages Batam's free trade zone status and submarine cable landing points to attract foreign investment. The Ministry of Communication and Informatics enforces physical security baselines for operators handling cross-border data flows. Medan and Palembang are developing smaller colocation facilities with modular perimeter detection systems.
Sulawesi
Sulawesi represents an underpenetrated expansion frontier as national connectivity infrastructure improves. The national cyber agency's sector guidelines extend to new critical information infrastructure designations in provincial capitals. Makassar is piloting hybrid security architectures combining on-site sensors with centralized monitoring for government data facilities.
Kalimantan
Kalimantan's industrial zones are attracting edge computing deployments to support resource extraction and logistics operations. Indonesia's PLI scheme incentives encourage domestic assembly of surveillance hardware for regional distribution. Balikpapan and Samarinda are seeing initial security system installations at enterprise data halls serving the mining sector.
Bali and Eastern Indonesia
Bali and the eastern archipelago concentrate demand in tourism-related digital infrastructure and government service delivery platforms. Local regulations require documented physical access controls for public sector data storage. Denpasar and Mataram are deploying compact security modules at distributed edge nodes outside core hyperscale clusters.
Indonesia Data Center Physical Security Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with building automation heritage rather than pure-play security specialists. Market concentration remains moderate, with global technology groups competing alongside regional system integrators for large campus contracts. Two strategic archetypes dominate: integrated building technology providers leveraging cross-selling synergies, and specialized surveillance vendors competing on edge-native processing capabilities. Capacity expansion and modular component unbundling represent the prevailing competitive vectors as buyers fragment sourcing across multiple vendors.
Within the integrated technology tier, Honeywell International Inc. and Bosch Sicherheitssysteme GmbH occupy positions anchored by manufacturing scale and building management system integration capabilities. Axis Communications AB exemplifies the specialized surveillance archetype, competing on latency-sensitive monitoring architectures. These three companies represent distinct strategic postures: building automation heritage, perimeter detection manufacturing scale, and edge-enabled video analytics specialization respectively.
| Leading Market Players |
|---|
| Bosch Sicherheitssysteme GmbH |
| Honeywell International Inc. |
| Axis Communications AB |
| ABB Ltd |
| Johnson Controls |
| Cisco Systems Inc. |
| Schneider Electric |
| ASSA ABLOY |
| Convergint Technologies LLC |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed hyperscale operators and foreign cloud providers rolling up facility investments across Java and Batam are compressing procurement timelines while fragmenting vendor relationships, forcing pricing discipline onto security integrators who must absorb integration complexity without margin recovery.
Pricing Analysis
Project-based contracting with outcome-linked performance guarantees dominates large campus deployments, separating premium-tier biometric systems with BSSN audit documentation from standard surveillance bundles and economy perimeter sensor packages. Price differentiation rests on certification grade for critical infrastructure compliance and customization depth for legacy building integration. Cost compression in the economy tier is intensifying as domestic contractors compete on installation speed. Foreign hyperscalers exhibit lowest price sensitivity; domestic colocation operators face the tightest budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated access control stacks, while system integrators serve mid-tier installations through project-specific procurement. Manufacturing concentrates in China, Taiwan, and South Korea for GPU-enabled video analytics hardware and biometric sensor components. The supply chain draws from imported semiconductor chips, optical sensors, and edge processing units. Single-source vulnerability around AI chip supply creates commissioning delays. Distribution runs through certified security integrators who manage BSSN compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Indonesia's data center physical security market stems from outcome-based service contracts displacing equipment-only sales, allowing integrators to capture recurring revenue streams.
For Market Incumbents: Anchor integrated building technology portfolios through backward integration into local installation capacity, defending against modular unbundling by foreign hyperscalers who fragment sourcing across specialized vendors. Deepen certification investment for BSSN critical infrastructure compliance to maintain tier-1 positioning as regulatory enforcement tightens. For New Entrants and Emerging Players: Launch via edge-native security modules targeting distributed computing nodes outside Jakarta's core hyperscale clusters, where underpenetrated demand for rapid-deployment physical protection creates white-space opportunity. Pursue hybrid deployment architectures combining on-site sensors with cloud-based analytics as the fastest-adoption segment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional system integrators with certified BSSN compliance capabilities and established hyperscale relationships. The long-term viability window favors consolidation plays as foreign operators prioritize risk transfer over capital ownership. Monitor PLI scheme incentive disbursement patterns as the signal for domestic manufacturing pivot timing.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Service Contracting | Recurring revenue capture from foreign hyperscalers in Jakarta and Batam campuses replaces one-time hardware margins. |
| Backward Integration into Installation | In-house middleware development for legacy building system integration compresses deployment timelines and protects margin pools. |
| BSSN Certification Investment | Critical infrastructure compliance documentation secures tier-1 positioning for Tier III and IV facility contracts. |
| Edge-Native Module Development | Compact rapidly deployable security stacks address distributed computing nodes beyond core Java hyperscale clusters. |
| Physical-Cyber Platform Convergence | SIEM and SOAR integration creates bundled value propositions for enterprise operators seeking unified threat management. |
Research Methodology
Bottom-up facility deployment modeling reconciled against top-down security technology shipment tracking forms the analytical core. Primary interviews with data center facility managers, security system integrators, BSSN compliance officers, and cloud provider procurement leads combined with secondary validation from Ministry of Communication and Informatics regulatory filings, customs import records for security hardware, and hyperscaler capital expenditure disclosures. Triangulation across stakeholder perspectives and data sources ensures consistency in market sizing.
Historical trendline analysis of facility buildout patterns and security technology refresh cycles established baseline growth trajectories. The projection framework models across deployment architecture, facility tier classification, end-user ownership type, and service delivery model dimensions. CAGRs derive from fitted growth curves adjusted for regulatory enforcement intensity and foreign direct investment flows into digital infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under BSSN certification timeline delays or import restriction escalations. Projections reflect assumptions about hyperscaler commitment continuity and PLI scheme manufacturing incentives. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Mexico Data Center Physical Security Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Poland Data Center Market
Data Center Infrastructure
Russia Data Center Rack Market