
 Dried Beet Pulp Market | 2026-2036
Dried Beet Pulp Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Beet Pulp Market Insights
France is rewriting capacity dynamics across the beet pulp processing belt. Tereos Group leverages its cooperative sugar-beet network to secure captive pulp volumes from Normandy and Picardy. Südzucker AG anchors Central European supply through its German and Polish beet sugar operations. British Sugar competes on island logistics, controlling coastal distribution channels that bypass cross-border bulk handling.
Dried beet pulp consists of the desugared, pressed, and dehydrated fibrous residue remaining after sucrose extraction from sugar beet roots, typically containing 8-10% moisture and 8-10% residual protein by weight. Pellet and granule product types dominate volume throughput due to superior flowability in automated feed handling systems. Animal feed end users generate the deepest margin pools, particularly dairy and beef livestock nutrient applications where beet pulp replaces starch energy without rumen acidosis risk. Powder and flake formats occupy niche positions in nutraceutical and organic farming segments where premium pricing offsets higher packaging costs.
EU Green Deal sustainability criteria and REACH chemical safety standards shape feed ingredient sourcing across member states. EFSA nutritional guidelines influence maximum inclusion rates in compound feed formulations. USDA grading protocols affect North American export acceptance thresholds. Stakeholders must monitor evolving carbon accounting methodologies for co-product valorization as biogas and biofuel applications compete for pulp diversion.
Market Dynamics
EU Green Deal carbon accounting rules are forcing beet pulp processors to document co-product valorization pathways or lose access to subsidized feed compounders. This pressure is restructuring supply allocation between traditional livestock feed and emerging biogas feedstock markets.
Growth Catalysts
- EFSA Nutritional Guidelines:Maximum inclusion rate relaxations for dairy cattle rations are expanding addressable feed volume across member states. Compounders reformulate to capture pulp's rumen-friendly energy profile.
- Pellet Handling Automation:Dairy cooperatives in France and Germany are retrofitting feed mills with pneumatic conveyance systems that require dust-free pellet flowability. This equipment preference locks in pellet procurement specifications.
- Biogas Subsidy Tiers:German and Polish renewable energy credit structures now weight agricultural residue inputs more favorably than maize silage. Beet pulp diversion to anaerobic digesters competes directly with feed allocation.
Market Restraints
- Sugar Beet Cultivation Concentration:Processing capacity clusters in northern France, Belgium, and Germany's Saxony-Anhalt region. Weather shocks or disease in these narrow production belts transmit immediately to pulp availability.
- Residual Protein Variability:Desugaring efficiency fluctuates with factory equipment age and beet quality. Inconsistent 8-10% protein specification complicates precision ration formulation for high-performance dairy genetics.
- Soybean Meal Substitution:South American oilseed crush expansions periodically compress soybean meal pricing into beet pulp's historical energy-value niche. Feed buyers arbitrage between starch sources based on spot protein spreads.
Strategic Opportunities
- Organic Certification Premiums:EU organic livestock herd expansions outpace certified feed ingredient supply. Beet pulp from non-GMO beet varieties commands 15-25% price elevation in this channel.
- CSRD Supply Chain Disclosure:Corporate sustainability reporting mandates require Scope 3 feed emissions documentation. Beet pulp's lower carbon intensity versus grain imports positions it as a compliance-friendly ingredient.
- Nutraceutical Fiber Extraction:Soluble fiber concentration in beet pulp residue supports prebiotic supplement applications. Pharmaceutical and functional food formulators represent margin expansion beyond commodity feed pricing.
Industry Challenges
- Moisture Specification Enforcement:8-10% moisture targets require precise kiln control. Energy cost spikes degrade drying economics and threaten contract fulfillment during natural gas price volatility.
- REACH Co-Product Classification:ECHA guidance ambiguity on whether desugared pulp qualifies as waste or product creates customs and liability exposure for cross-border bulk shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Beet Pulp Market |
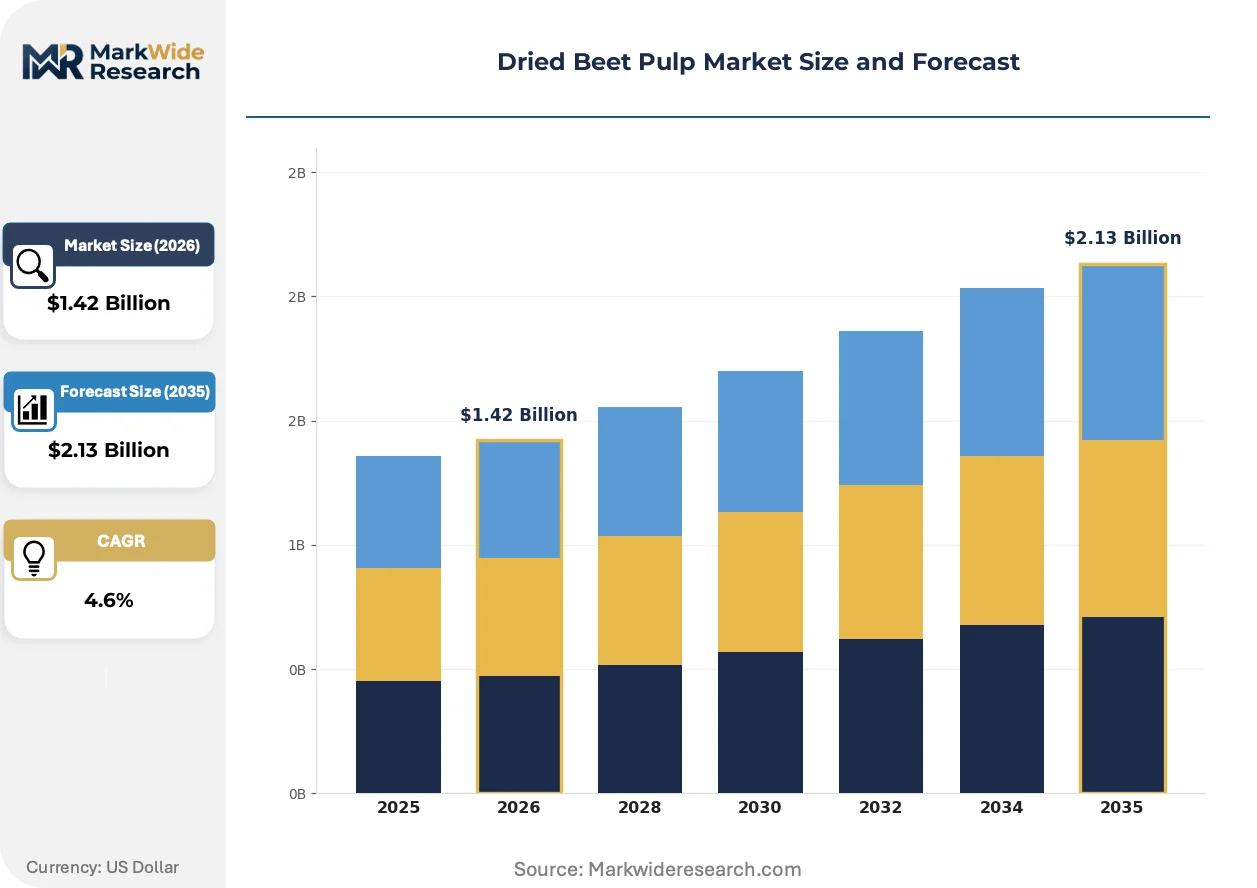
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Pellets, Powder, Flakes End User: Animal Feed, Food Industry, Nutraceuticals, Organic Farming Application: Livestock Nutrient, Horse Feed, Dog Food, Biofuel Packaging Type: Bags, Bulk, Boxes, Pallets |
| Companies Covered | Tereos Group, Südzucker AG, Nordzucker AG, Amalgamated Sugar, American Crystal Sugar, Michigan Sugar Company, British Sugar, Ontario Dehy Inc., Midwest Agri-Commodities, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Beet Pulp Market Trends and Innovations
Processing technology and regulatory disclosure requirements are converging to alter how beet pulp moves from sugar factory to end-use. Equipment investments and carbon tracking systems now determine competitive access to premium market tiers.
Steam-explosion pre-treatment is migrating from pilot-scale demonstration to commercial deployment at Tereos and Südzucker facilities. This thermal-mechanical process ruptures cell walls to improve rumen degradability and biogas conversion rates. Dairy nutritionists and digester operators are both specifying treated pulp in procurement tenders, compressing margins for untreated commodity grades.
EU Green Deal farm-to-fork methane reduction targets are tightening maximum livestock emission intensities per kilogram of output. Member state feed regulators are translating these caps into approved ingredient lists and inclusion ceilings. Beet pulp's fermentation profile—slower starch release, reduced enteric methane—positions it favorably in these reformulations, particularly in Denmark and the Netherlands where dairy sector climate plans are most advanced.
Compound feed procurement is consolidating through cooperative purchasing platforms that aggregate volume from multiple dairy operations. These platforms standardize specifications and squeeze supplier margins through tender transparency. French and German cooperatives are most active in this channel shift, displacing traditional broker-mediated spot purchasing with annual framework agreements that lock in pellet quality and sustainability documentation.
Dried Beet Pulp Market Segmentation
Dried beet pulp moves through multiple channel configurations before reaching end-use, with physical form, customer sophistication, and handling infrastructure each filtering procurement options. Understanding how these dimensions intersect reveals where margin pools concentrate and where commoditization pressure intensifies.
Product Type:
Physical form determines handling infrastructure compatibility and dust exposure liability across the value chain.
- Pellets:Compressed cylindrical forms with density advantages for pneumatic conveyance systems. Dairy cooperatives in France and Germany specify pellet-only procurement as they retrofit feed mills with automated handling equipment that jams on irregular particles. REACH dust-exposure thresholds in bulk handling facilities reinforce this specification lock-in.
- Granules:Irregular crushed particles offering faster hydration in ration mixing. Beef feedlot operations in Poland and Hungary prefer granules where manual shovel feeding persists and capital investment in automation remains limited.
- Powder:Fine-milled residue with expanded surface area for prebiotic extraction. Nutraceutical formulators in Denmark and the Netherlands source powder grades for soluble fiber concentration processes.
- Flakes:Thin dehydrated sheets with visual differentiation for premium organic channels. German organic dairy associations specify flake appearance in certification standards.
Pellets command the established base. The steepest expansion runs through granules as Central European feedlots defer automation investment.
End User:
Customer sophistication and regulatory exposure create tiered pricing power across downstream channels.
- Animal Feed:Compound feed manufacturers and livestock operations consuming beet pulp as rumen-fermentable energy. CSRD Scope 3 disclosure requirements drive German and French dairy cooperatives toward documented low-carbon ingredients, positioning beet pulp favorably against imported grain.
- Organic Farming:Certified operations commanding 15-25% price premiums for non-GMO verification and restricted-input compliance. EU organic herd expansions in Austria and Switzerland outpace certified feed supply, tightening availability.
- Nutraceuticals:Pharmaceutical and functional food extractors isolating soluble fiber fractions for prebiotic applications. Danish biotech clusters source desugared pulp as raw material for gut-health formulations.
- Food Industry:Specialty bakeries and meat processors using pulp as moisture-binding fiber. Niche penetration in German whole-grain bread segments where labeling regulations permit vegetable fiber claims.
Animal feed commands the established base. The steepest expansion runs through organic farming as certification premiums attract supply diversion from conventional channels.
Application:
Species-specific nutritional requirements and digestive physiology filter product suitability and formulation complexity.
- Livestock Nutrient:Dairy and beef cattle rations leveraging beet pulp's slow-release fermentation profile to maintain rumen pH. EFSA maximum inclusion rate relaxations for dairy cattle expand addressable volume across member states.
- Horse Feed:Equine rations requiring low-starch, high-fiber energy sources to prevent metabolic disorders. German and Dutch sport horse stables specify beet pulp for conditioning without excitability.
- Dog Food:Premium pet formulations incorporating pulp as stool-conditioning fiber. Private label manufacturers in Poland and Czech Republic source pellet grades for extrusion compatibility.
- Biofuel:Anaerobic digester feedstock competing directly with livestock allocation. German renewable energy credit structures now weight agricultural residue inputs more favorably than maize silage.
Livestock nutrient commands the established base. The steepest expansion runs through biofuel as energy subsidy tiers restructure supply allocation.
Packaging Type:
Unit size and material configuration align with customer scale, handling equipment, and inventory turnover requirements.
- Bulk:Unpackaged loose shipment in dedicated vessels or pneumatic trailers. Large compounders in northern France and Belgium with dedicated unloading infrastructure capture cost savings.
- Bags:25-50kg woven polypropylene sacks for mid-scale operations lacking bulk handling. Polish and Hungarian distributors maintain bagged inventory for fragmented farm customer bases.
- Pallets:Unitized loads of bagged product for mechanized warehouse handling. German agricultural cooperatives specify palletized delivery to align with automated storage systems.
- Boxes:Corrugated containers for specialty organic and nutraceutical channels requiring lot traceability. Swiss organic distributors use box packaging for retail-facing presentation.
Bulk commands the established base. The steepest expansion runs through pallets as cooperative purchasing platforms standardize logistics specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beet pulp processing capacity clusters in a narrow band of northern European sugar beet cultivation, with factory locations determining regional supply economics and cross-border trade flows. This geographic concentration creates weather and disease transmission risks that ripple through livestock feed and biogas markets simultaneously.
Germany
Dairy cooperatives in Lower Saxony and Bavaria are expanding beet pulp inclusion rates as EU Green Deal feed sustainability criteria tighten procurement standards. The KBA agricultural regulator monitors transport emissions documentation for bulk shipments crossing state lines. Saxony-Anhalt processing clusters near Magdeburg anchor Central European supply volumes for both domestic compounders and Polish export buyers.
France
Pellet form factors now dominate procurement in Normandy and Picardy as handlers seek dust-reduced logistics for automated feed mill retrofits. ANSM workplace safety inspectors enforce REACH exposure thresholds in bulk handling facilities along the northern processing belt. Tereos cooperative operations in the Hauts-de-France region control captive pulp flows from beet sugar factories to regional dairy nutritionists.
United Kingdom
British Sugar competes on island logistics advantages, controlling coastal distribution channels that bypass cross-border bulk handling complexity post-Brexit. The Environment Agency enforces waste-derived product classifications for desugared pulp shipments to Irish compounders. East Anglia processing sites in Norfolk maintain dedicated vessel loading for Scottish and Northern Irish livestock operations.
Poland
Beef feedlot operations in Greater Poland and Silesia prefer granule formats where manual shovel feeding persists and automation investment remains limited. The country's national agricultural regulator weights renewable energy credit structures toward agricultural residue inputs for anaerobic digesters. Südzucker facilities near Poznań divert increasing pulp volumes to biogas feedstock markets competing directly with livestock allocation.
United States
Michigan and North Dakota sugar beet regions supply domestic dairy and beef operations through regional cooperatives. USDA grading protocols determine export acceptance thresholds for Canadian and Mexican cross-border shipments. American Crystal Sugar processing in the Red River Valley anchors upper Midwest supply for organic farming channels commanding certification premiums.
Dried Beet Pulp Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in captive pulp offtake arrangements with sugar processors. The market structure consolidates around cooperative-owned sugar groups with integrated feed ingredient divisions, while independent traders and regional compounders occupy fragmented downstream positions. Three archetypes dominate: vertically integrated sugar cooperatives controlling captive pulp volumes, regional feed ingredient distributors aggregating spot supply, and biogas operators bidding directly for digester feedstock. Capacity expansion and sustainability documentation partnerships constitute the dominant competitive moves as EU Green Deal compliance requirements harden.
Among European cooperative sugar groups, Tereos Group, Südzucker AG, and Nordzucker AG occupy positions as platform integrators with captive pulp access from factory networks. Tereos exemplifies the Normandy-Picardy concentration archetype through its cooperative beet supply base. Südzucker AG anchors Central European positioning across German and Polish processing footprints. Nordzucker AG represents the northern German specialist model with focused Baltic region supply integration. British Sugar sits within the island-market defensive positioning archetype, leveraging coastal logistics control against cross-border competitors.
| Leading Market Players |
|---|
| Tereos Group |
| Südzucker AG |
| Nordzucker AG |
| Amalgamated Sugar |
| American Crystal Sugar |
| Michigan Sugar Company |
| British Sugar |
| Ontario Dehy Inc. |
| Midwest Agri-Commodities |
| Others |
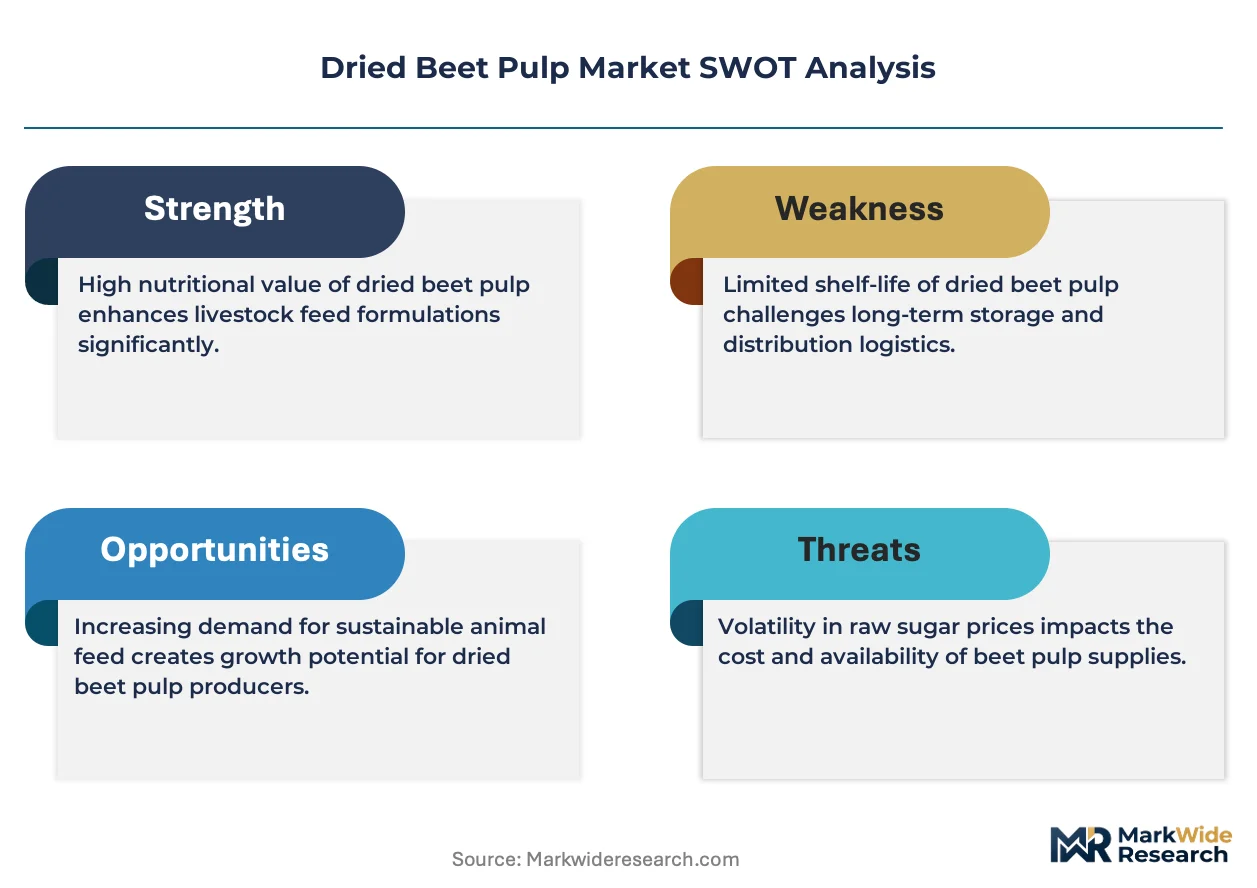
Pricing and Supply Chain Analysis
Undercapacity in Saxony-Anhalt processing clusters during the beet campaign window concentrates supplier leverage, forcing compound feed manufacturers to accept formula-price linkages that escalate with natural gas kiln costs and sugar factory desugaring efficiency.
Pricing Analysis
EU Green Deal carbon accounting rules dictate the pricing tier structure across the dried beet pulp value chain. Three-tier pricing separates organic-certified flakes from standard pellets from untreated granules, with CSRD documentation requirements adding compliance premiums to the top tier. Cost compression in standard pellets is intensifying because Tereos and Südzucker cooperative buyers aggregate volumes through tender platforms that expose supplier margins. Dairy cooperatives in Denmark and the Netherlands exhibit the lowest price sensitivity due to sustainability mandate lock-in, while Polish beef feedlots arbitrage spot protein spreads between beet pulp and soybean meal.
Supply Chain Analysis
Extended payment terms from French dairy cooperatives now stretch to 90 days, forcing Tereos and Südzucker to deploy supply-chain finance facilities to maintain working capital through the beet processing season. Geographic supply concentration centers on northern France, Germany, and Poland, where sugar beet cultivation belts feed captive pulp flows into integrated compound feed operations. Raw material dependencies draw from sugar beet root supply, natural gas for kiln drying, and lignosulfonate binding agents for pellet formation. Single-source vulnerability runs through the narrow Normandy-Picardy-Saxony-Anhalt processing corridor, where weather shocks transmit immediately to pulp availability. Distribution runs through cooperative purchasing platforms that displace traditional broker-mediated spot purchasing with annual framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through cooperative purchasing platforms in France and Germany, fragmenting supplier leverage and compressing margins for independent traders unable to match sustainability documentation scale.
For Market Incumbents: Insulate pellet-grade margin pools by deepening captive beet supply integration through cooperative ownership structures, while accelerating steam-explosion pre-treatment capacity to meet dairy nutritionist specifications that lock out untreated commodity competitors. Biogas diversion threats from German renewable energy credit structures require dual-market allocation discipline to prevent feed channel supply erosion. For New Entrants and Emerging Players: Organic-certified flake production for Austrian and Swiss livestock associations represents the most penetrable entry point, given 15-25% price premiums and supply deficits outpacing certified herd expansion. Nutraceutical fiber extraction for Danish prebiotic formulators offers a second white-space avenue with margin expansion beyond commodity feed pricing. A go-to-market angle anchored in CSRD Scope 3 emissions documentation partnerships with corporate sustainability officers bypasses established cooperative procurement channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative sugar groups with integrated feed ingredient divisions and multi-year framework agreements with dairy cooperatives. Long-term viability over the five-to-ten year window rests on carbon intensity positioning as EU methane reduction targets harden feed ingredient specifications. Acquisition targets should display captive pulp access from factory networks and steam-explosion processing capability. The signal to watch is German biogas subsidy tier adjustments that restructure supply allocation between livestock feed and anaerobic digester markets.| Strategic Initiative | Industry Significance |
|---|---|
| Steam-Explosion Processing Scale-Up | Tereos and Südzucker deployments improve rumen degradability to capture dairy nutritionist procurement specifications. |
| Organic Certification Expansion | Non-GMO beet variety sourcing captures 15-25% price elevation in Austrian and Swiss certified channels. |
| CSRD Documentation Partnerships | Scope 3 emissions reporting integration positions beet pulp against higher-carbon grain imports in corporate feed sourcing. |
| Biogas Feedstock Allocation Discipline | German and Polish renewable energy credit optimization prevents livestock channel supply erosion from digester diversion. |
| Cooperative Purchasing Platform Integration | Annual framework agreements with French and German dairy aggregators displace spot broker intermediation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU customs trade data, sugar industry association reports, and EFSA regulatory filings. Primary interviews engaged sugar factory operations managers, compound feed procurement leads at dairy cooperatives, biogas digester operators, and agricultural cooperative purchasing platform directors. Secondary validation drew from ECHA REACH guidance documents, EU Green Deal implementation texts, and national agricultural regulator interpretations across Germany, France, and Poland. Bottom-up volume modeling from processing facility outputs triangulates against top-down demand aggregation from livestock census data and feed formulation surveys.
Forecast inputs incorporate product type segmentation across pellets, granules, powder, and flakes; end-user channels spanning animal feed, organic farming, nutraceuticals, and biofuel; and application categories including livestock nutrient, horse feed, and anaerobic digestion. CAGRs derive from historical processing capacity utilization trends, EU organic herd expansion trajectories, and biogas subsidy tier evolution across the projection horizon. Industry-specific inputs include sugar beet cultivation yield variability, natural gas price volatility impact on drying economics, and EFSA maximum inclusion rate relaxation schedules for dairy cattle rations.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, sugar beet harvest volumes, or EU renewable energy credit structures would shift the trajectory. Forecasts assume documented co-product valorization pathways remain eligible for subsidized feed compounder access, with regulatory reclassification under REACH or biogas market expansion prompting revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Australia Soy Protein Market
Ingredients
North America Gluten Free Flour Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Cocoa Derivatives Market
Ingredients
Mustard Oil Market
Ingredients
Alkalized Cocoa Powder Market
Ingredients
Global Cocoa Products Market
Ingredients
Europe Brewers Spent Yeast Market
Ingredients
Xylooligosaccharide Market
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
North America Protein Ingredients Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
Bakery Ingredients Market
Ingredients
Soy Lecithin Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Mung Bean Protein Market