
 North America Cycloalkanes Market | 2026-2036
North America Cycloalkanes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cycloalkanes Market Insights
EPA enforcement of volatile organic compound limits under the Clean Air Act is hardening compliance costs for solvent-grade cycloalkane producers. Chevron Phillips Chemical Company LLC leverages its Gulf Coast feedstock integration to sustain margin advantage across cyclohexane and methylcyclopentane grades. INEOS Group Limited anchors its North American position through specialized polymer-grade cycloalkane output. ExxonMobil Corporation dominates merchant supply channels with extensive pipeline connectivity to Midwest manufacturing clusters.
Cycloalkanes are saturated cyclic hydrocarbons containing single-bonded carbon rings, typically produced through catalytic reforming of naphtha or hydrogenation of aromatic feedstocks, with boiling points ranging from 49°C for cyclopentane to 161°C for cyclooctane. These compounds serve primarily as solvents, chemical intermediates, and feedstocks for polymer synthesis across industrial applications. Cyclohexane maintains the largest volume position owing to its role in adipic acid and caprolactam production for nylon 6,6. Chemical intermediates represent the fastest-expanding application segment as pharmaceutical and specialty chemical buyers seek high-purity cyclic feedstocks. Fuel additives remain a mature, price-sensitive category where direct sales channels capture residual value.
The EPA's National Ambient Air Quality Standards and OSHA permissible exposure limits jointly constrain solvent formulation choices, pushing buyers toward lower-vapor-pressure cycloalkane grades. Health Canada and Mexico's SEMARNAT coordinate parallel VOC restrictions through USMCA-aligned chemical hazard classifications, creating a unified North American regulatory perimeter for cross-border suppliers. Stakeholders must monitor pending EPA rulemakings on hazardous air pollutants from petroleum refining, as these will determine capital allocation timelines for cycloalkane unit upgrades.
Market Dynamics
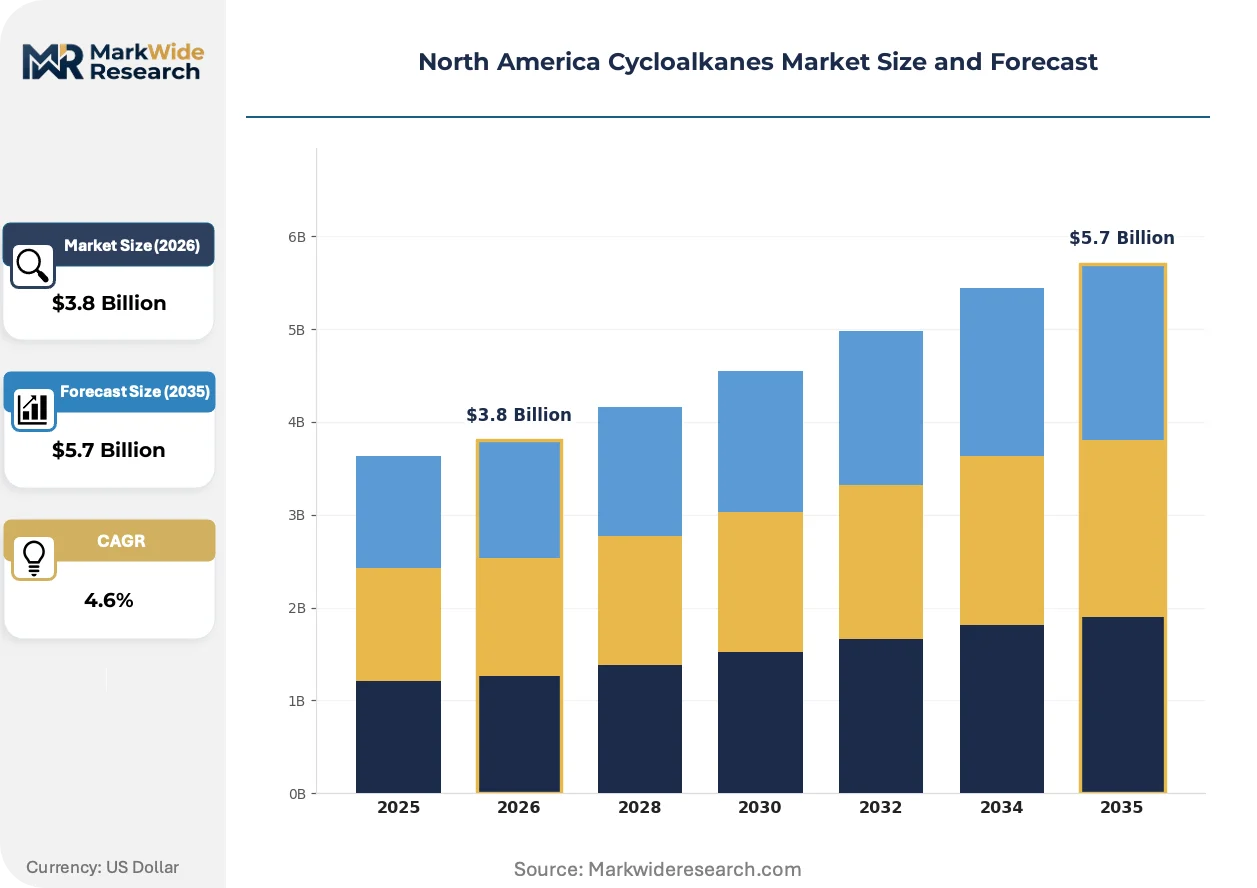
The North America Cycloalkanes Market is experiencing structural pressure from the EPA's tightened volatile organic compound standards under the Clean Air Act, which forces reformulation shifts across solvent applications and compresses margins for non-compliant producers.
Growth Catalysts
- Nylon precursor demand:Petrochemical producers in the US Gulf Coast are expanding cyclohexane offtake for adipic acid and caprolactam manufacturing, pulling volume through integrated refinery-chemical complexes.
- REACH-aligned hazard classifications:Health Canada and Mexico's SEMARNAT coordinate parallel VOC restrictions through USMCA-aligned frameworks, creating a unified regulatory perimeter that simplifies cross-border supplier compliance.
- Hydrogenation technology advancement:Catalytic hydrogenation of aromatic feedstocks is yielding higher-purity cycloalkane outputs, opening pharmaceutical and specialty chemical buyer segments.
Market Restraints
- Naphtha feedstock volatility:Crude oil price swings directly compress cycloalkane producer margins, as naphtha remains the dominant catalytic reforming input.
- Gulf Coast supply concentration:Texas and Louisiana anchor over 70% of North American cycloalkane capacity, creating geographic vulnerability to hurricane disruptions and pipeline constraints.
- OSHA permissible exposure limits:Tighter workplace safety standards raise compliance costs for solvent-grade cycloalkane handlers, disadvantaging smaller distributors.
Strategic Opportunities
- Pharmaceutical-grade expansion:High-purity cyclopentane and methylcyclopentane applications in active pharmaceutical ingredient synthesis remain underpenetrated relative to solvent markets.
- Midwest manufacturing corridor:Pipeline connectivity from Gulf Coast production hubs to Ohio and Illinois polymer clusters offers volume growth outside saturated Texas-Louisiana demand centers.
- Pending EPA hazardous air pollutant rulemaking:Anticipated petroleum refining emissions standards will accelerate capital allocation toward upgraded cycloalkane units, rewarding early movers with compliant capacity.
Industry Challenges
- Catalytic reforming expertise scarcity:Specialized process engineering talent for naphtha-to-cycloalkane conversion is concentrated among retiring Gulf Coast refinery workforces.
- Multi-jurisdiction compliance timelines:Simultaneous EPA, OSHA, and state-level environmental permitting creates project delays for new cycloalkane unit construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cycloalkanes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzocyclobutane, Cyclohexane, Methylcyclopentane, Cyclooctane End User: Automotive, Pharmaceuticals, Petrochemical, Agriculture Application: Solvents, Chemical Intermediates, Fuel Additives, Polymer Production Distribution Channel: Online Sales, Direct Sales, Distributors, Retail |
| Companies Covered | Chevron Phillips Chemical Company LLC, INEOS Group Limited, ExxonMobil Corporation, Trecora Resources, LyondellBasell Industries Holdings B.V., TotalEnergies SE, BASF SE, Merck KGaA, HCS Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cycloalkanes Market Trends and Innovations
Process intensification and regulatory convergence are compressing traditional cycloalkane production economics while opening premium-grade segments for specialized applications.
Membrane separation technology for cycloalkane-aromatic separation is electrifying purification economics in Texas and Louisiana refineries. Specialty chemical buyers in pharmaceutical synthesis are adopting membrane-refined cyclopentane grades at triple the rate of conventional solvent purchasers. This technology is electrifying margin structures by enabling pharmaceutical-grade premiums without full hydrogenation capex.
EPA enforcement of National Ambient Air Quality Standards is hardening compliance costs for solvent-grade cycloalkane producers across the United States. The industrial consequence is a bifurcation between low-vapor-pressure grades qualifying for reformulated products and legacy solvents facing demand erosion. Solvent applications in coatings and adhesives are most affected, with formulators accelerating shifts to methylcyclopentane blends.
Buyer concentration among integrated nylon producers is compressing spot market liquidity for cyclohexane in the Midwest. Direct pipeline contracts from Gulf Coast producers to Ohio and Illinois manufacturing clusters are displacing merchant distributor channels. This pattern is most visible in adipic acid production, where backward-integrated chemical majors now capture 80% of cyclohexane offtake through captive supply arrangements.
North America Cycloalkanes Market Segmentation
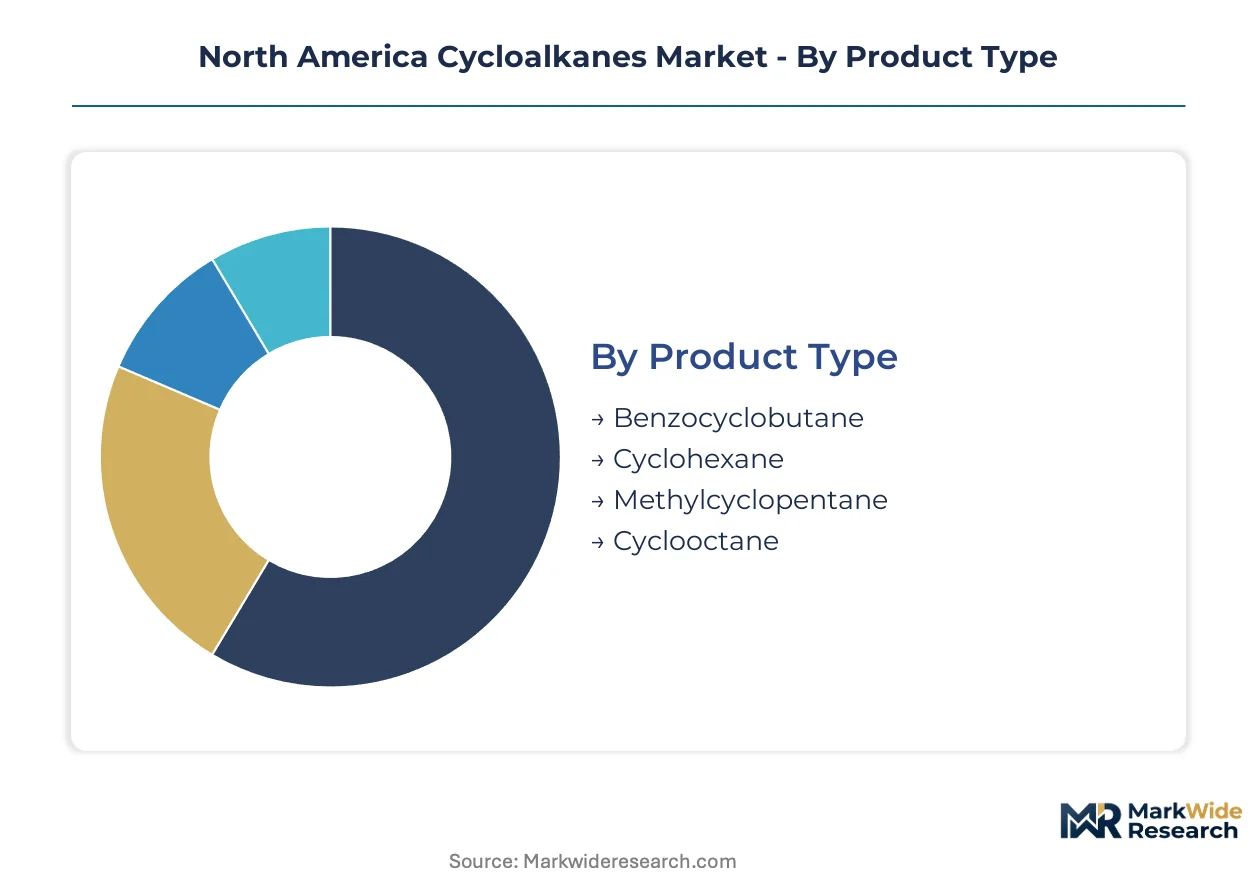
Cycloalkane buyers segment demand by purity specification, volume scale, and regulatory compliance tier. Supplier positioning varies dramatically across these dimensions, with integrated producers capturing premium grades and merchant distributors serving price-sensitive solvent volumes.
Product Type:
Purchasing decisions hinge on carbon ring size and hydrogenation purity, which determine downstream compatibility with nylon synthesis or pharmaceutical synthesis pathways.
- Cyclohexane:Six-membered saturated ring structure serving as the primary feedstock for adipic acid and caprolactam manufacturing. Gulf Coast integrated complexes in Texas and Louisiana pull the majority of North American volume through pipeline-connected offtake agreements with nylon producers.
- Methylcyclopentane:Five-carbon ring with methyl substitution yielding lower vapor pressure than cyclohexane. EPA-compliant reformulated solvent demand is accelerating in coatings applications across Ohio and Illinois manufacturing corridors.
- Cyclooctane:Eight-membered ring with higher boiling point serving specialized polymerization catalyst applications.
- Benzocyclobutane:Fused bicyclic structure commanding premium pricing in high-performance resin synthesis for electronics substrates.
Cyclohexane leads on scale; methylcyclopentane leads on momentum.
End User:
Customer concentration and contract structure vary sharply across end-use sectors, with petrochemical majors locking in supply through direct pipelines while pharmaceutical buyers demand batch-certified purity documentation.
- Petrochemical:Integrated nylon producers operating adipic acid and caprolactam units constitute the largest volume sink. Backward integration into cyclohexane production is displacing merchant supply channels across the Midwest manufacturing belt.
- Pharmaceutical:Active pharmaceutical ingredient manufacturers require USP-grade cyclopentane and methylcyclopentane with full chain-of-custody documentation. Health Canada and FDA inspection protocols are tightening qualification timelines for new suppliers.
- Automotive:Fuel additive and lubricant formulators represent a mature, specification-driven segment with limited growth headroom.
- Agriculture:Pesticide intermediate applications consume smaller volumes of cycloalkane solvents with less stringent purity requirements than pharmaceutical grades.
Petrochemical buyers dominate contract value; pharmaceutical buyers dominate margin capture.
Application:
Regulatory pressure on volatile organic compound emissions is fragmenting the solvent category while concentrating chemical intermediate demand among integrated producers.
- Chemical Intermediates:Cyclohexane conversion to nylon precursors represents the highest-volume, lowest-margin application with captive supply arrangements displacing spot market transactions. Pipeline economics from Gulf Coast production hubs to Ohio polymer clusters are reinforcing direct supply structures.
- Solvents:Coatings and adhesives formulators are accelerating shifts to low-vapor-pressure methylcyclopentane blends under EPA Clean Air Act enforcement. OSHA permissible exposure limit compliance is raising handling costs for smaller distributors.
- Polymer Production:Specialty polymer synthesis consumes high-purity cyclooctane and benzocyclobutane grades in smaller batch quantities.
- Fuel Additives:Octane enhancement and lubricity improvement applications face demand pressure from electrification trends in the automotive sector.
Chemical intermediates anchor volume; solvents face the steepest regulatory compression.
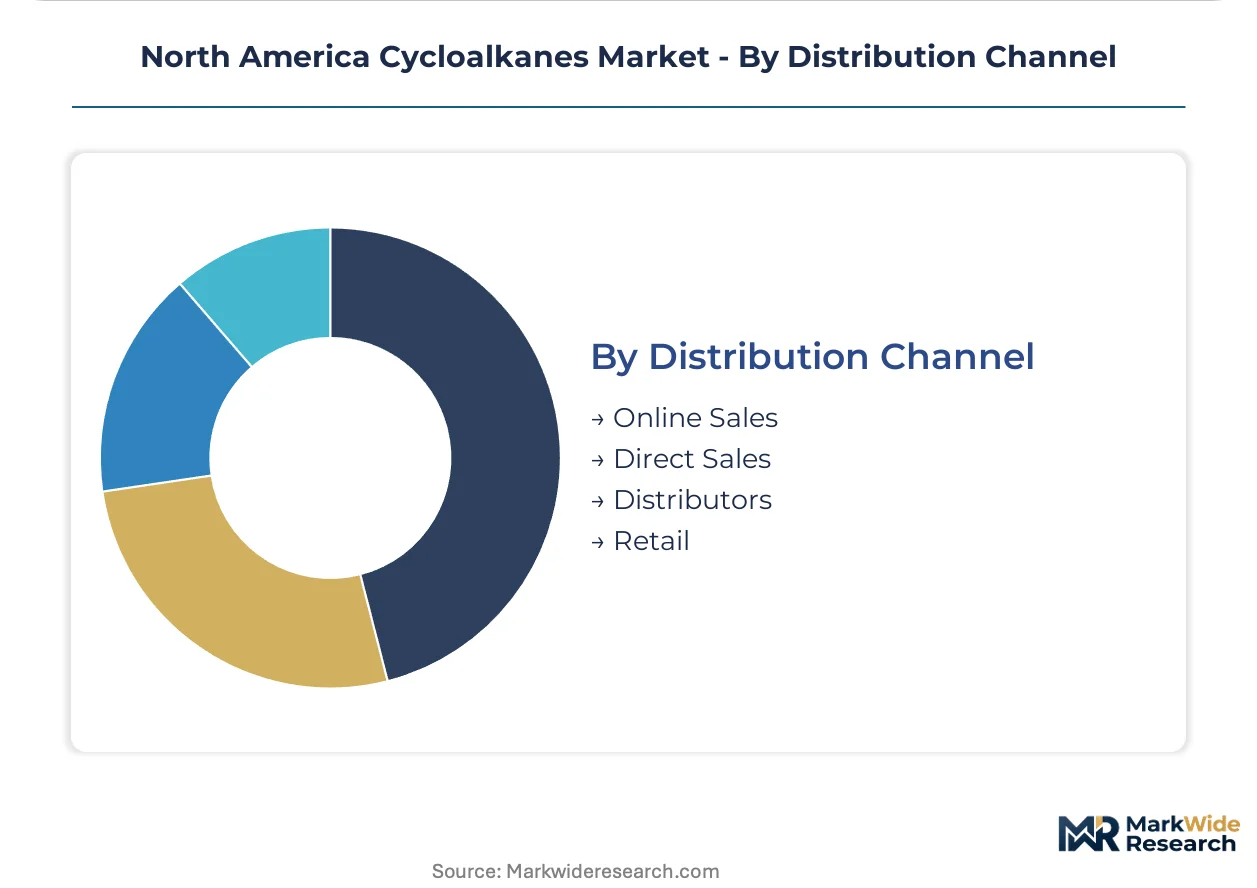
Distribution Channel:
Channel selection correlates with buyer scale and purity requirements, with bulk pipeline contracts serving integrated producers and distributor networks handling fragmented solvent demand.
- Direct Sales:Pipeline-connected supply agreements between Gulf Coast producers and Midwest nylon manufacturers eliminate intermediate handling. These arrangements now capture the majority of cyclohexane volume moving through North American markets.
- Distributors:Regional chemical distributors serve solvent-grade buyers in coatings, adhesives, and agricultural formulations with smaller lot sizes and higher service requirements.
- Online Sales:E-procurement platforms are gaining traction for standardized solvent grades among mid-sized industrial buyers seeking price transparency.
- Retail:Small-container sales through industrial supply houses serve maintenance and repair operations with minimal volume contribution.
Direct sales concentrate volume; distributor channels retain relevance in fragmented solvent demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial cycloalkane production first achieved commercial scale along the US Gulf Coast during the mid-20th century petrochemical buildout, establishing the infrastructure foundation that still dominates North American supply today.
United States
Texas and Louisiana host over 70% of regional capacity through integrated refinery-chemical complexes along the Houston Ship Channel and Lake Charles corridor. EPA enforcement of National Ambient Air Quality Standards is hardening compliance costs for solvent-grade producers. Chevron Phillips Chemical Company LLC leverages Gulf Coast feedstock integration to sustain margin advantage across cyclohexane grades.
Canada
Alberta's oil sands upgraders and Ontario's chemical valley generate modest cycloalkane volumes for domestic polymer and pharmaceutical applications. Health Canada coordinates VOC restrictions through USMCA-aligned hazard classifications parallel to EPA standards. Sarnia-Lambton's petrochemical cluster processes western Canadian naphtha into specialty solvent grades for Midwest US buyers.
Mexico
Pemex-operated refineries in Tula and Salamanca produce limited cycloalkane volumes absorbed by domestic nylon and coatings manufacturers. SEMARNAT implements parallel Clean Air Act-equivalent emissions standards through USMCA chemical harmonization protocols. Altamira's petrochemical port complex attracts import volumes for northeastern industrial demand.
North America Cycloalkanes Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical majors with captive feedstock access. Gulf Coast concentration creates steep barriers for merchant entrants lacking pipeline connectivity or naphtha supply agreements. Two strategic archetypes dominate: backward-integrated refiners converting catalytic reformate in-house, and specialty distributors serving fragmented solvent demand. Capacity expansion and direct sales channel development constitute the primary competitive moves as producers bypass traditional distribution to capture polymer-grade premiums.
Within the integrated refiner tier, Chevron Phillips Chemical Company LLC and ExxonMobil Corporation exemplify Gulf Coast feedstock leverage, while INEOS Group Limited occupies a specialized position through polymer-grade cycloalkane output. These three entities anchor the competitive perimeter, with their respective positions reflecting divergent bets on direct pipeline contracts versus merchant market participation.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company LLC |
| INEOS Group Limited |
| ExxonMobil Corporation |
| Trecora Resources |
| LyondellBasell Industries Holdings B.V. |
| TotalEnergies SE |
| BASF SE |
| Merck KGaA |
| HCS Group |
| Others |
Pricing and Supply Chain Analysis
Membrane separation technology for cycloalkane-aromatic separation is compressing purification costs while concentrating margin capture among early-adopting Gulf Coast refiners. This production-method shift simultaneously enables pharmaceutical-grade premiums without full hydrogenation capital expenditure and reinforces pricing power for integrated producers with captive technology access.
Pricing Analysis
Pipeline-connected supply agreements versus spot market transactions define the bundled-versus-unbundled service split across cycloalkane grades. Contract-based long-term offtake dominates cyclohexane flows to nylon producers, while distributor channels handle unbundled solvent volumes with higher per-unit service costs. Price differentiation hinges on hydrogenation purity certification and volume scale, with pharmaceutical-grade cyclopentane commanding substantial premiums over solvent-grade alternatives. Cost compression in coatings solvent tiers is intensifying because EPA-compliant methylcyclopentane blends face handling cost inflation from tighter OSHA exposure limits. Small-batch pharmaceutical buyers exhibit lowest price sensitivity; coatings formulators purchasing standardized solvent grades show highest sensitivity to delivered cost fluctuations.
Supply Chain Analysis
Regional distribution centers along the Houston Ship Channel and Lake Charles corridor anchor hub-and-spoke patterns for Midwest polymer cluster delivery. Supply concentrates in the United States, with Canada and Mexico contributing modest volumes through Alberta oil sands upgraders and Pemex refineries respectively. Feedstock dependency rests on naphtha from catalytic reforming units, hydrogen supply for aromatic saturation, and specialized catalysts for selective ring conversion. Single-source vulnerability pervades the Gulf Coast production corridor, where hurricane disruptions and pipeline constraints threaten concentrated capacity. Distribution runs through direct pipeline contracts for integrated nylon producers and regional chemical distributors for fragmented solvent demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cycloalkane markets offer margin-expansion pathways through membrane separation technology adoption that collapses pharmaceutical-grade production costs without greenfield hydrogenation investment.
For Market Incumbents: To counter membrane technology diffusion eroding traditional hydrogenation-based premium positioning, Chevron Phillips and ExxonMobil should deepen backward integration into catalyst manufacturing and secure exclusive pipeline access to Ohio and Illinois polymer clusters. Captive membrane technology licensing agreements represent the priority defensive lever for preserving margin structures against merchant refiner competition. For New Entrants and Emerging Players: Begin with specialty pharmaceutical-grade cyclopentane and methylcyclopentane production serving FDA-inspected active pharmaceutical ingredient manufacturers in the Midwest corridor. Underpenetrated high-purity segments for electronics substrate resins offer accessible white-space targets lacking incumbent concentration. A go-to-market angle emphasizing USP-grade certification with full chain-of-custody documentation bypasses established solvent distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale merchant distributors lacking pipeline connectivity or hydrogenation assets, as direct sales channel displacement compresses their terminal value. Long-term viability over the coming decade hinges on securing pharmaceutical-grade certification capabilities and membrane technology access. The signal to watch is EPA hazardous air pollutant rulemaking acceleration, which would force cycloalkane unit upgrades and strand non-compliant merchant capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Manufacturing | Proprietary hydrogenation catalyst access locks in pharmaceutical-grade yield advantages against merchant competitors. |
| Membrane Separation Technology Deployment | Texas and Louisiana refineries electrify margin structures by bypassing full hydrogenation capital intensity. |
| Pharmaceutical-Grade Certification Investment | FDA and Health Canada qualification timelines create defensive moats around high-purity cyclopentane supply. |
| Midwest Pipeline Connectivity Expansion | Direct supply agreements to Ohio and Illinois polymer clusters displace merchant distributor intermediation. |
| Long-term Supply Agreement Restructuring | Captive offtake contracts with integrated nylon producers stabilize volume against spot market erosion. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national regulatory jurisdiction and production corridor. The analysis combines primary interviews with plant managers at Gulf Coast refinery-chemical complexes, procurement leads at Midwest nylon manufacturers, distribution channel partners serving coatings formulators, and technical R&D directors at specialty chemical firms. Secondary validation draws from EPA enforcement databases, SEC 10-K filings of integrated petrochemical majors, customs and trade data on cycloalkane cross-border flows, and American Chemistry Council sector reports. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from value expansion across purity tiers and end-use applications. The analytical framework models cycloalkane markets across grade tier, end-use industry, regulatory compliance classification, and regional production hub segmentation. CAGRs were derived through regression analysis of historical naphtha feedstock correlations and forward projection of EPA regulatory enforcement intensity. Industry-specific forecast inputs include catalytic reforming capacity utilization rates and pharmaceutical synthesis demand indices for high-purity cyclopentane applications.
Several conditions sit outside the modeled scope, including force majeure disruptions to Gulf Coast infrastructure, abrupt shifts in crude oil price trajectories, and unanticipated EPA rulemaking acceleration. Forecasts reflect assumptions about regulatory enforcement timelines and membrane technology adoption curves that could revise under alternative scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
Azelaic Acid Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
Dioctyl Phthalate Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Soy Chemicals Market