
 Azelaic Acid Market | 2026-2036
Azelaic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Azelaic Acid Market Analysis
REACH is hardening the cost-of-entry calculus for azelaic acid suppliers serving European pharmaceutical and cosmetic buyers. Croda Sipo leverages its integrated oleochemical feedstock position to sustain margin stability under stricter purity mandates. Jiangsu Senxuan Pharmaceutical and Chemical Co Ltd anchors regional supply through specialized fermentation-derived production capabilities. BASF competes on technical-grade scale while navigating divergent cosmetic and pharmaceutical compliance pathways.
Azelaic acid is a saturated dicarboxylic acid (C9H16O4) typically manufactured via ozonolysis of oleic acid or fermentation of oleic acid derivatives, with pharmaceutical grades requiring purity levels exceeding 99.5% and tight control of azelaic acid-related impurities per pharmacopeial standards. The compound functions primarily as a topical therapeutic agent with dual keratolytic and anti-inflammatory properties, plus emerging utility in polymer intermediates and lubricant applications. Topical creams and gels dominate prescription volumes, while foams represent the fastest-growing delivery format driven by patient compliance advantages and dermatologist preference for non-greasy vehicles. E-Commerce channels are capturing disproportionate growth in the distribution channel landscape as direct-to-consumer skincare brands bypass traditional pharmacy networks.
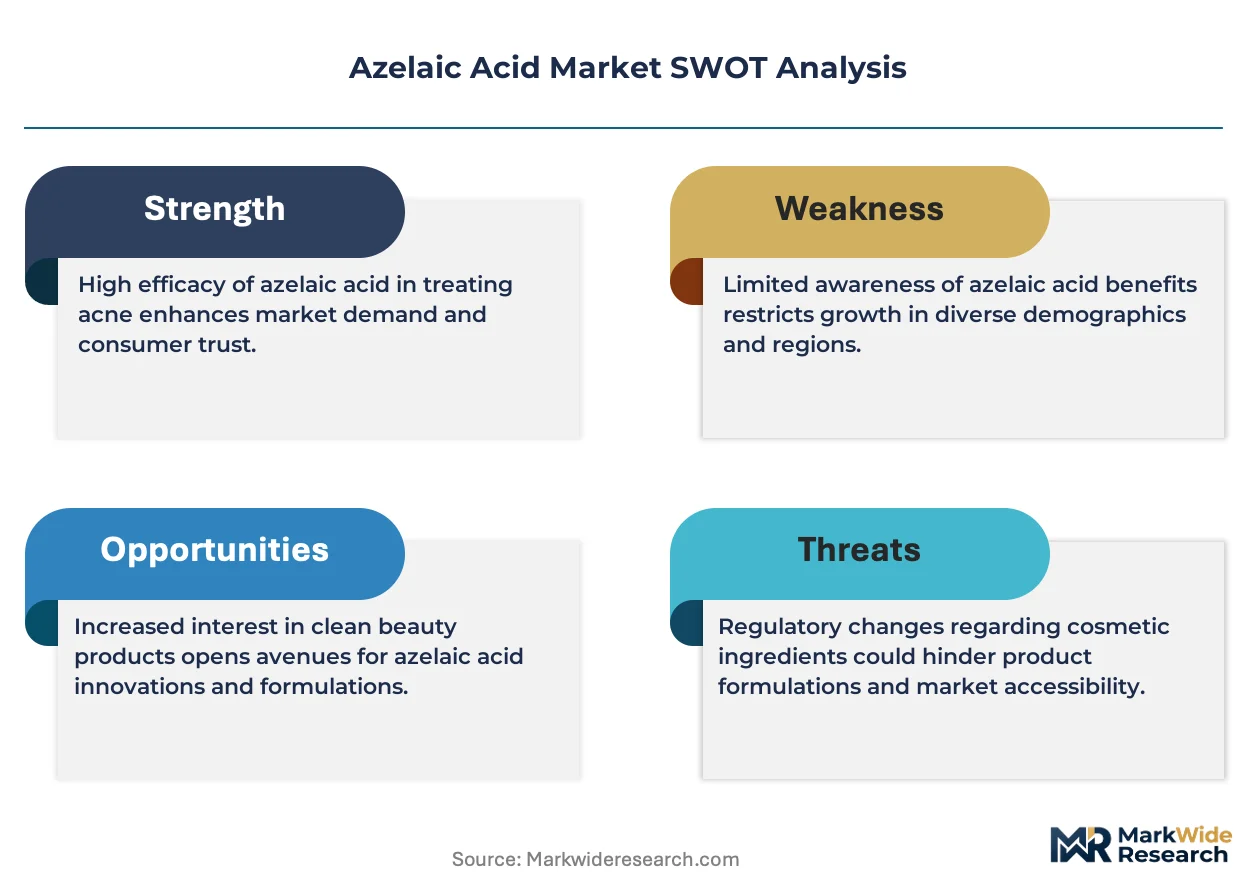
FDA oversight of over-the-counter acne monographs and EPA industrial chemical reporting requirements shape product classification and environmental liability exposure for U.S. market participants. EMA's updated quality guidelines for topical actives and China's NMPA pharmaceutical registration reforms are synchronizing upward pressure on analytical method validation and impurity profiling across major jurisdictions. Stakeholders must monitor regulatory divergence between cosmetic and pharmaceutical classification thresholds, as reclassification risk threatens existing formulation portfolios and channel access strategies.
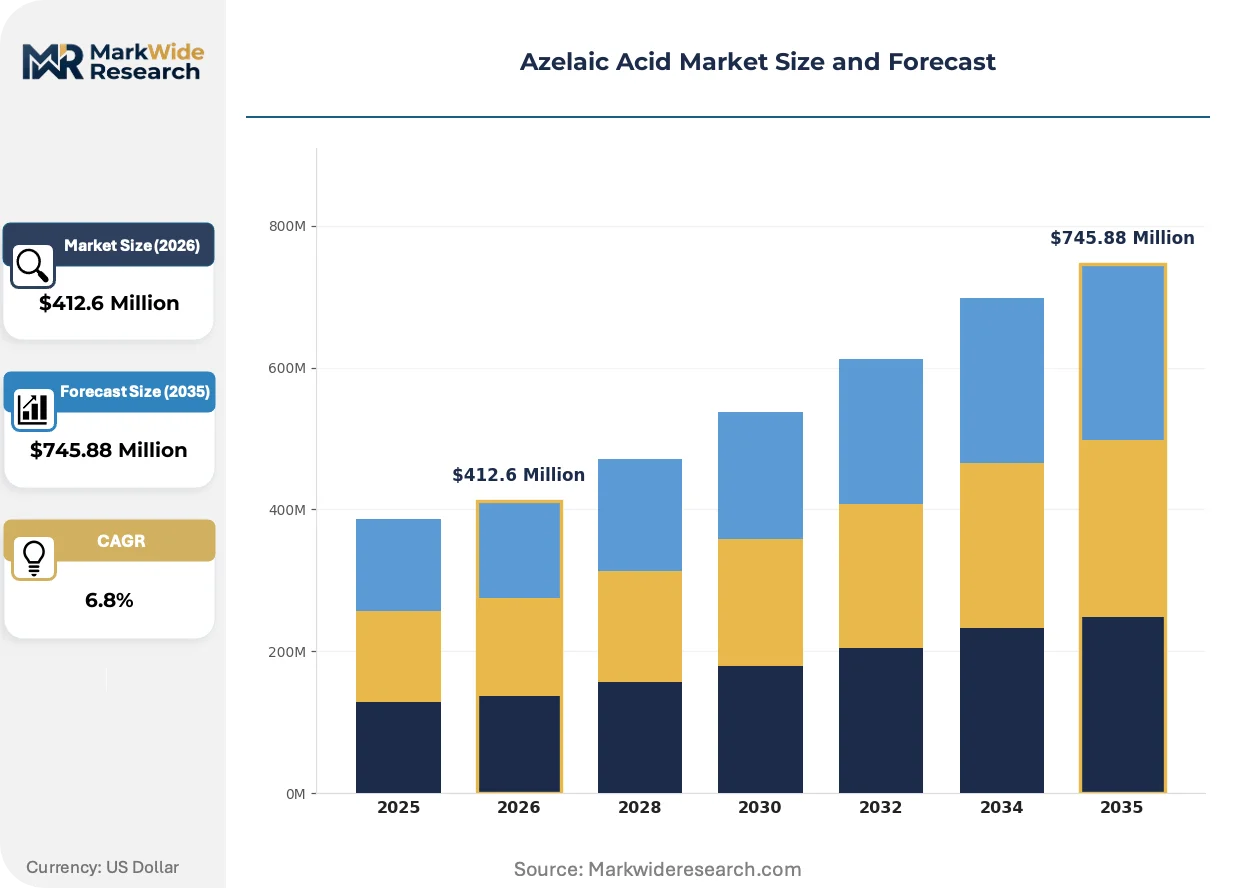
Market Dynamics
Pharmaceutical-grade purity mandates are compressing supplier margins while concentrating production among integrated oleochemical specialists with captive feedstock access. REACH compliance costs and FDA monograph updates are forcing dual-track analytical investments that smaller fermentation-based producers struggle to amortize.
Growth Catalysts
- Acne prescription volumes:Dermatology clinics are expanding topical retinoid combination therapies where azelaic acid serves as the anti-inflammatory anchor, driving API demand from compounding pharmacies.
- REACH authorization timelines:ECHA's tightened substance evaluation schedules are accelerating qualification contracts with pre-registered suppliers who hold valid safety data dossiers.
- Ozonolysis yield improvements:Continuous-flow reactor designs at Jiangsu and Shandong manufacturing clusters are reducing oleic acid feedstock waste rates below batch-process benchmarks.
Market Restraints
- Oleic acid price volatility:Palm and tallow feedstock fluctuations transmit directly to azelaic acid variable costs, squeezing contract manufacturers without backward integration into oleochemicals.
- Jiangsu-Shandong supply concentration:Over 60% of fermentation-derived capacity sits within 400 kilometers in eastern China, creating geographic risk exposure for European and North American formulators.
- Salicylic acid substitution:OTC acne segments retain price-sensitive positioning where salicylic acid formulations undercut azelaic acid on cost-per-treatment metrics.
Strategic Opportunities
- Rosacea indication expansion:Off-label dermatology prescribing for inflammatory rosacea is creating volume growth outside traditional acne labeling, particularly in cash-pay aesthetic clinics.
- Direct-to-consumer foams:E-commerce skincare brands are bypassing pharmacy networks with subscription-model prescription foam deliveries, capturing patient compliance premiums.
- EU Green Deal bio-based mandates:Fermentation-derived azelaic acid qualifies for preferred procurement status under emerging EU public hospital pharmaceutical purchasing guidelines.
Industry Challenges
- Pharmacopeial method validation:USP and EP impurity profiling requirements demand specialized HPLC-MS capability that mid-scale producers lack in-house, forcing expensive third-party analytical outsourcing.
- Cosmetic-pharmaceutical classification ambiguity:Borderline concentration thresholds in EU member state cosmetics regulations create reclassification risk for existing formulation portfolios, threatening channel access strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Azelaic Acid Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Gels, Foams, Powders Application: Acne Treatment, Rosacea Management, Skin Lightening, Anti-Aging End User: Dermatology Clinics, Retail Pharmacies, E-Commerce, Hospitals Distribution Channel: Online, Drugstores, Specialty Stores, Direct Sales |
| Companies Covered | Croda Sipo, Jiangsu Senxuan Pharmaceutical and Chemical Co Ltd, Emery Oleochemicals, Shandong Clearwill, Ninghai Zhonglong, Matrica S.p.A., Nantong Hengxing Electronic Materials Co Ltd, Hubei TuoChu Kangyuan Pharmaceutical Co Ltd, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Azelaic Acid Market Emerging Trajectories
Foam-based delivery vehicles are capturing dermatologist preference while regulatory synchronization across FDA, EMA, and NMPA is elevating analytical burden. Procurement patterns are fragmenting as direct-to-consumer brands disintermediate traditional pharmacy distribution.
Microencapsulated azelaic acid suspensions are overtaking conventional cream formulations in premium dermatology prescribing. Aesthetic clinic chains in South Korea and the United States are adopting these systems for controlled-release rosacea protocols. The technology is overtaking standard emulsion chemistry by enabling combination with retinoids without oxidation degradation, compressing R&D cycles for multi-active pipelines.
EMA's updated quality guidelines for topical actives are mandating enhanced impurity profiling for nitrosamine and elemental contaminants. European contract manufacturers are retrofitting QC laboratories with ICP-MS capability to meet the new specifications. Pharmaceutical-grade azelaic acid suppliers serving EU hospital formulators face the steepest compliance investments, with several redirecting technical-grade output to cosmetic channels to avoid validation costs.
Subscription-based prescription fulfillment is displacing traditional pharmacy pickup for chronic acne patients. Direct-to-consumer platforms in the United States and United Kingdom are capturing recurring revenue through automated refill algorithms tied to treatment cycle data. This channel shift is most visible among 18-34 demographic segments where telehealth dermatology consultations have normalized, forcing legacy distributors to build last-mile cold-chain partnerships or cede volume.
Azelaic Acid Market Segmentation
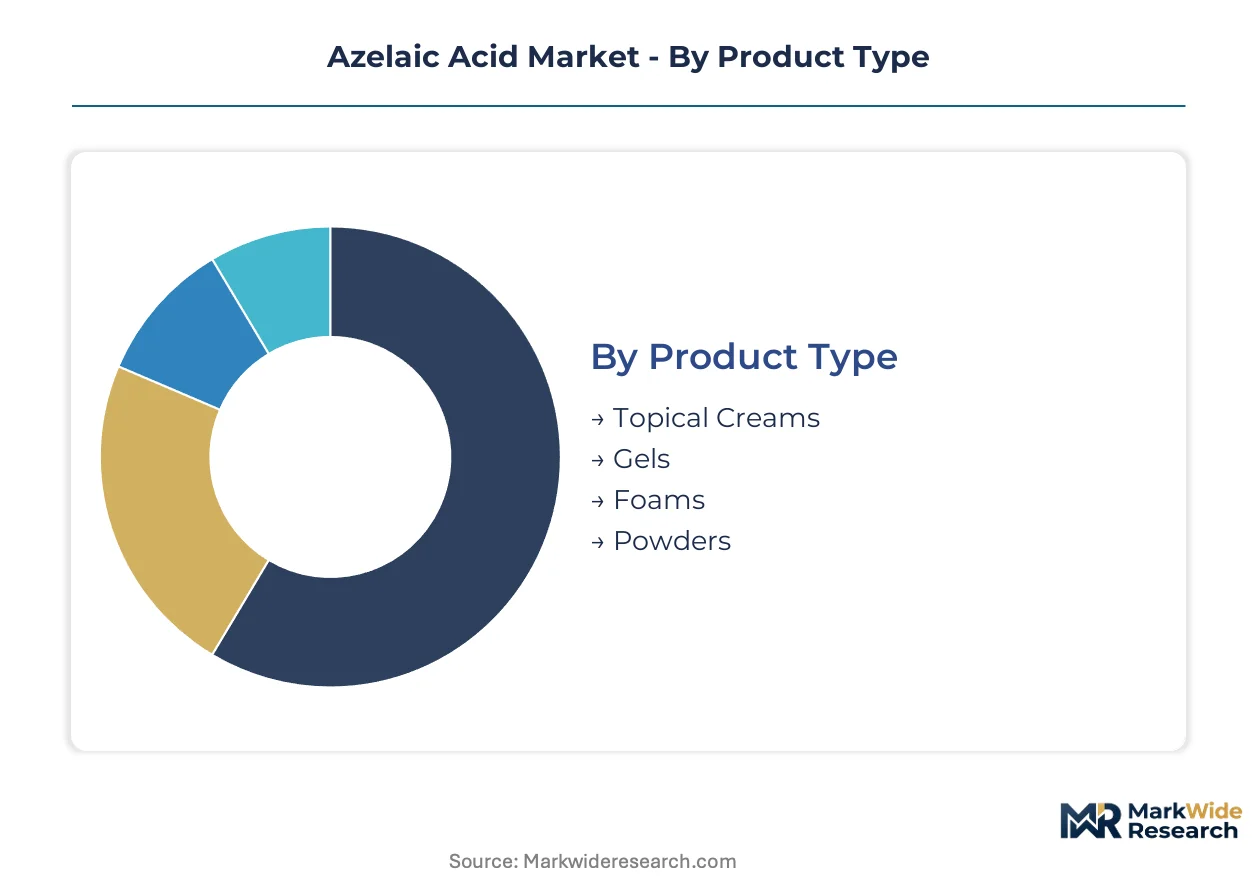
Azelaic acid formulation portfolios fragment across pharmaceutical, cosmetic, and industrial qualification tiers. Each segment carries distinct regulatory filing burdens and margin profiles that reshape supplier positioning.
Product Type:
Pharmaceutical-grade foams require FDA monograph compliance and EMA quality guideline adherence, while cosmetic powders face lighter notification frameworks.
- Topical Creams:Emulsion-based vehicles with 15-20% azelaic acid concentration dominate prescription volumes in dermatology clinics. Demand concentrates in the United States and Germany where reimbursement pathways for acne vulgaris treatment remain established.
- Gels:Aqueous-alcohol formulations offer faster absorption profiles preferred for oily skin phenotypes. South Korean aesthetic clinics are expanding gel adoption for combination therapy protocols with retinoids.
- Foams:Non-greasy delivery vehicles capture patient compliance premiums through direct-to-consumer subscription channels. E-commerce skincare brands in the United Kingdom and United States bypass traditional pharmacy networks with automated refill systems.
- Powders:Technical-grade material serves polymer intermediate and lubricant applications with lower purity thresholds than pharmaceutical specifications.
Leading the category by volume: Topical Creams. Growing fastest: Foams.
Application:
Acne and rosacea indications require prescription drug registration, while skin lightening and anti-aging segments navigate cosmetic-drug borderline classifications.
- Acne Treatment:FDA-regulated monograph indications drive the largest prescription volumes through dermatology clinics and retail pharmacies. Combination therapies with topical retinoids expand compounding pharmacy API demand.
- Rosacea Management:Off-label prescribing for inflammatory subtypes creates volume growth in cash-pay aesthetic clinics, particularly in South Korea and the United States.
- Skin Lightening:Cosmetic classification in most jurisdictions limits medical claims but enables broader channel access through e-commerce platforms.
- Anti-Aging:Premium positioning in direct-to-consumer channels leverages azelaic acid's antioxidant properties for photoaging protocols.
Acne Treatment holds the largest revenue base. Rosacea Management climbs the fastest as aesthetic clinic chains expand service menus.
End User:
Dermatology clinics and hospitals demand pharmaceutical-grade documentation, while e-commerce channels absorb cosmetic-grade volumes with lighter qualification requirements.
- Dermatology Clinics:Specialized prescribing of prescription foams and microencapsulated suspensions commands premium pricing. United States and German clinic chains are consolidating procurement through group purchasing organizations.
- Retail Pharmacies:Traditional pickup channels face displacement from subscription-based fulfillment models among chronic acne patient cohorts.
- E-Commerce:Direct-to-consumer platforms capture recurring revenue through telehealth-integrated prescription workflows. Automated refill algorithms tied to treatment cycle data dominate the 18-34 demographic segment.
- Hospitals:EU public hospital procurement under Green Deal bio-based mandates favors fermentation-derived azelaic acid suppliers.
Dermatology Clinics anchor category volume. E-Commerce gains share fastest as telehealth consultations normalize.
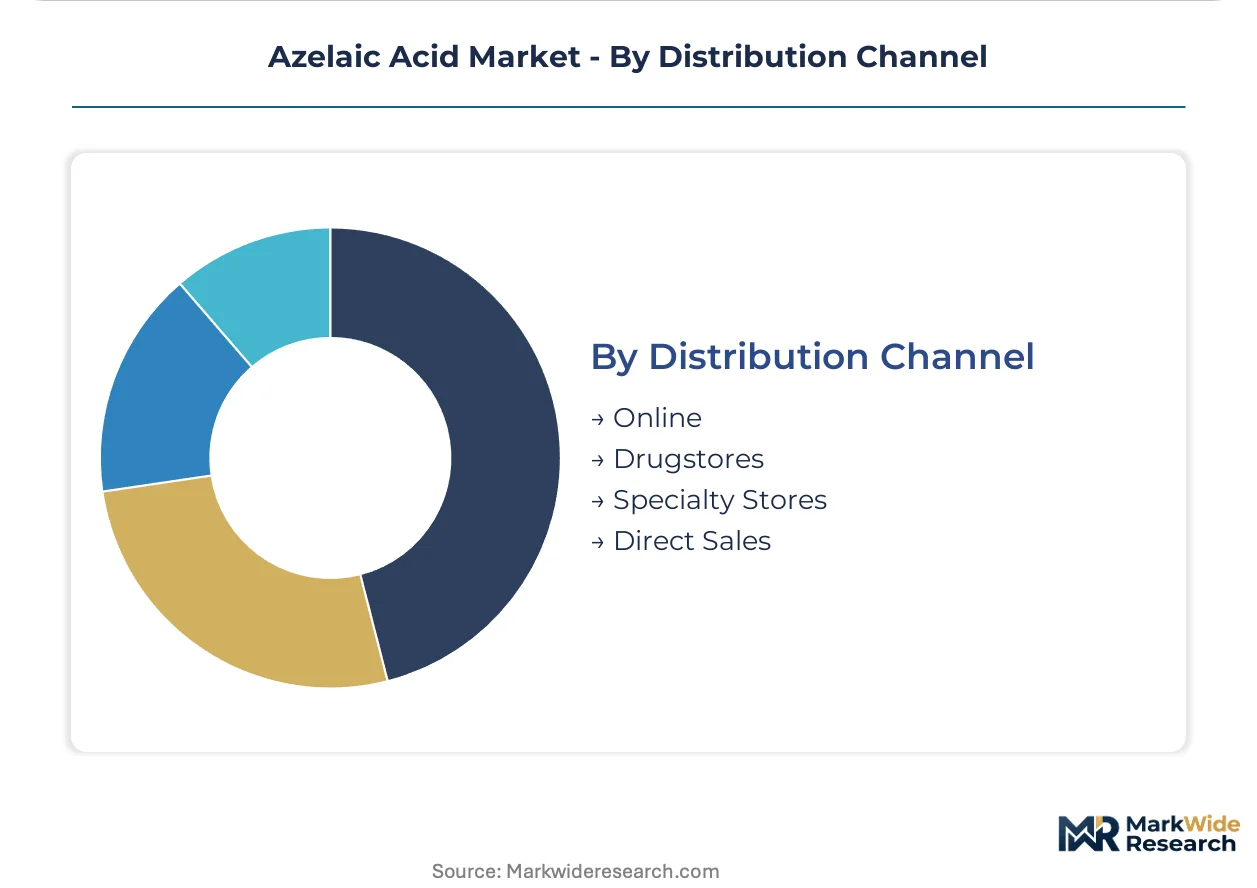
Distribution Channel:
Online and direct sales channels fragment traditional pharmacy dominance while specialty stores capture premium cosmetic positioning.
- Online:Subscription-model platforms in the United States and United Kingdom disintermediate legacy distributors. Cold-chain last-mile partnerships become critical for temperature-sensitive foam formulations.
- Drugstores:Mass-market OTC positioning competes with salicylic acid alternatives on cost-per-treatment metrics.
- Specialty Stores:Premium cosmetic retail in South Korea and France commands higher margins for skin lightening and anti-aging serums.
- Direct Sales:B2B supply contracts from Jiangsu and Shandong manufacturing clusters serve European and North American formulators with concentrated geographic risk exposure.
Online channels lead expansion velocity. Drugstores retain the largest transaction volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Shandong provinces anchor global azelaic acid production through concentrated specialty chemical manufacturing clusters, while regulatory divergence across FDA, EMA, and NMPA jurisdictions reshapes qualification requirements for pharmaceutical-grade supply.
China
Dermatology clinics in Shanghai and Beijing drive prescription foam demand through telehealth-integrated platforms. NMPA pharmaceutical registration reforms mandate enhanced impurity profiling for API exports. Jiangsu and Shandong fermentation-derived manufacturing clusters supply over sixty percent of global pharmaceutical-grade volume.
United States
FDA-regulated acne monographs sustain compounding pharmacy API demand from dermatology clinic chains. EPA industrial chemical reporting requirements shape environmental liability exposure for ozonolysis-based producers. Texas and New Jersey host contract manufacturing organizations serving direct-to-consumer subscription channels.
Germany
EMA quality guidelines for topical actives drive ICP-MS laboratory retrofits among EU hospital formulators. REACH authorization timelines accelerate qualification contracts with pre-registered suppliers holding valid safety data dossiers. North Rhine-Westphalia's chemical corridor concentrates pharmaceutical-grade distribution to European hospital networks.
South Korea
Aesthetic clinic chains in Seoul expand microencapsulated suspension adoption for rosacea combination protocols. MFDS pharmaceutical registration aligns with EMA impurity standards for nitrosamine screening. Busan-Ulsan manufacturing bases serve domestic dermatology brands with fermentation-derived API.
United Kingdom
Telehealth dermatology consultations normalize subscription-model prescription fulfillment among 18-34 demographic segments. MHRA post-Brexit regulatory divergence from EMA creates dual-track filing burdens for pharmaceutical-grade importers. Southeast England e-commerce platforms bypass traditional pharmacy networks with automated refill algorithms.
Azelaic Acid Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Integrated oleochemical majors leverage captive feedstock access to sustain margin stability under tightening purity mandates. Fermentation-derived specialists anchor regional supply through specialized production capabilities. Contract manufacturers without backward integration face margin compression from oleic acid price volatility. Strategic moves concentrate on capacity expansion in Jiangsu-Shandong clusters and technology licensing for continuous-flow reactor designs.
Among Chinese fermentation-based producers, Jiangsu Senxuan Pharmaceutical and Chemical Co Ltd and Shandong Clearwill occupy positions within the regional supply tier. Croda Sipo represents the integrated oleochemical archetype with backward control over feedstock chains. BASF exemplifies diversified chemical conglomerate positioning across technical and pharmaceutical qualification tiers.
| Leading Market Players |
|---|
| Croda Sipo |
| Jiangsu Senxuan Pharmaceutical and Chemical Co Ltd |
| Emery Oleochemicals |
| Shandong Clearwill |
| Ninghai Zhonglong |
| Matrica S.p.A. |
| Nantong Hengxing Electronic Materials Co Ltd |
| Hubei TuoChu Kangyuan Pharmaceutical Co Ltd |
| BASF |
| Others |
Supply Flow & Price Mechanics
Continuous-flow reactor designs in Jiangsu and Shandong manufacturing clusters simultaneously compress production costs and entrench geographic supply concentration among fermentation-derived specialists with captive oleochemical access. This technology transition rewards integrated players while squeezing contract manufacturers lacking backward feedstock control.
Pricing Analysis
Short lead-time premiums for REACH-compliant pharmaceutical-grade batches separate emergency procurement pricing from standard contract schedules. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects purity thresholds and analytical documentation burdens. Pricing pressure stems from oleic acid feedstock volatility transmitting directly to variable costs. Retail pharmacy buyers exhibit highest price sensitivity to salicylic acid substitution, while dermatology clinics absorb premiums for microencapsulated suspension formats.
Supply Chain Analysis
Dual-sourcing mandates from European hospital formulators force qualification contracts with both Jiangsu-Shandong fermentation clusters and integrated oleochemical majors. Raw material dependencies center on palm and tallow-derived oleic acid, plus specialized nitrogen sources for fermentation media. Single-source vulnerability concentrates in the 400-kilometer eastern China manufacturing corridor. Distribution runs through B2B supply contracts serving North American and European formulators, with direct-to-consumer channels bypassing traditional pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The azelaic acid market functions as a vertical-integration race where captive oleochemical feedstock access determines margin survival under tightening pharmacopeial purity mandates.
For Market Incumbents: Extend fermentation capacity in Jiangsu-Shandong clusters to capture EU Green Deal bio-based procurement preferences. Lock in long-term oleic acid offtake agreements before palm price volatility intensifies. Defend against salicylic acid substitution in OTC segments by co-developing retinoid combination protocols with dermatology clinic chains. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to patient access without pharmacy network buildout. Target cash-pay aesthetic clinics in South Korea and the United States for rosacea indication expansion. Pursue telehealth-integrated prescription fulfillment as the primary go-to-market vector. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified chemical conglomerates seeking pharmaceutical-grade API capabilities. Long-term viability hinges on backward integration into oleochemicals or proprietary continuous-flow reactor licensing. Watch for NMPA export registration reform as the signal for Chinese supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Feedstock | Croda Sipo's captive supply chain insulates margins from palm price volatility. |
| Continuous-Flow Reactor Licensing | Jiangsu manufacturers license yield-optimized designs to European contract manufacturers. |
| EU Green Deal Bio-Based Certification | Fermentation-derived suppliers qualify for preferred hospital procurement status. |
| Direct-to-Consumer Channel Launch | Subscription platforms bypass pharmacy networks with automated refill algorithms. |
| Microencapsulation Technology Partnership | South Korean aesthetic clinics adopt controlled-release rosacea protocols. |
Methodological Framework
Trade databases, pharmacopeial filing records, and customs export declarations formed the secondary backbone of this analysis. Primary interviews with plant managers at Jiangsu-Shandong manufacturing clusters, procurement leads at European dermatology clinic chains, regulatory affairs specialists navigating REACH authorization timelines, and distribution channel partners supplying direct-to-consumer platforms validated quantitative assumptions. Bottom-up and top-down triangulation reconciled fermentation capacity estimates with prescription volume data.
Bottom-up modeling built volume projections from individual segment trajectories across formulation types, application indications, and end-user channels. The analytical framework incorporated pharmaceutical-grade purity tier adoption, cosmetic-pharmaceutical classification boundary shifts, and regional regulatory divergence as core segmentation dimensions. CAGRs emerged from iterative reconciliation of oleic acid feedstock cost curves, EMA quality guideline implementation timelines, and telehealth dermatology consultation growth patterns.
The model holds under stable REACH authorization timelines and NMPA export registration continuity; deviation in oleic acid supply disruption or pharmacopeial impurity threshold revision would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
Dimethylformamide (DMF) Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Europe Lactic Acid Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Phenol Market
Organic Chemicals
Humic Acid Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Terephthalic Aldehyde Market