
 Organocatalyst Market | 2026-2036
Organocatalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Organocatalyst Market Analytics
Pharmaceutical-grade enantioselectivity is collapsing the gap between laboratory performance and commercial viability. BASF SE leverages integrated catalyst manufacturing to sustain cost positions across fine chemical supply chains. Evonik Industries AG anchors European demand through specialized asymmetric synthesis portfolios. Codexis, Inc. differentiates via enzyme-compatible organocatalyst platforms that bridge biocatalytic and purely chemical routes.
Organocatalysts are small organic molecules that accelerate chemical reactions without containing metal atoms, typically operating through hydrogen bonding, enamine, or iminium ion mechanisms with loadings between 1-20 mol%. These catalysts enable stereoselective transformations critical to pharmaceutical active pharmaceutical ingredient synthesis and high-performance polymer production. Amino acid-based variants lead product type demand due to established chirality control and scalable feedstock access from fermentation streams. Asymmetric synthesis applications command the deepest margin pools within the application landscape, reflecting the premium placed on single-enantiomer drug substances by regulators and originator firms. Solid-phase delivery dominates commercial deployment where catalyst recovery and recyclability determine process economics.
REACH registration requirements and EPA toxic substance controls are elevating analytical documentation burdens for catalyst impurities in downstream pharmaceutical applications. EMA quality guidelines and FDA ICH Q3D standards on elemental impurities indirectly favor metal-free organocatalysts over traditional transition-metal alternatives in synthetic route selection. Stakeholders must monitor evolving green chemistry procurement mandates from large pharmaceutical manufacturers, as these specifications increasingly dictate supplier qualification and long-term contract viability.
Market Dynamics
REACH and EPA frameworks are tightening purity thresholds for catalyst residues in drug substances, forcing pharmaceutical manufacturers to requalify synthetic routes around metal-free alternatives. This regulatory compression is accelerating the displacement of transition-metal catalysts across asymmetric synthesis workflows.
Growth Catalysts
- Chiral API Demand:Pharmaceutical manufacturers are scaling organocatalyst adoption for asymmetric synthesis of chiral intermediates. Single-enantiomer drug substances command premium pricing from originator firms.
- REACH Registration:ECHA's elevated analytical documentation burdens for catalyst impurities indirectly favor metal-free organocatalysts over traditional transition-metal alternatives in synthetic route selection.
- Feedstock Scalability:Amino acid-based variants lead product type demand due to established chirality control and scalable feedstock access from fermentation streams.
Market Restraints
- High Catalyst Loadings:Organocatalysts typically operate at 1-20 mol% loadings versus ppm levels for transition-metal alternatives, inflating raw material costs per kilogram of product output.
- Recovery Economics:Solid-phase delivery dominates commercial deployment where catalyst recovery and recyclability determine process economics, yet separation technologies remain capital-intensive.
- Performance Gaps:Certain enantioselective transformations still require transition-metal catalysis, limiting organocatalyst applicability in specific pharmaceutical intermediate classes.
Strategic Opportunities
- Biocatalytic Convergence:Enzyme-compatible organocatalyst platforms that bridge biocatalytic and purely chemical routes are opening hybrid process development contracts with large pharmaceutical manufacturers.
- Green Chemistry Mandates:Evolving green chemistry procurement specifications from large pharmaceutical manufacturers increasingly dictate supplier qualification and long-term contract viability.
- Polymer Applications:High-performance polymer production represents an underpenetrated application vertical where stereoselective ring-opening polymerization could drive new demand pools.
Industry Challenges
- Specialized Talent Scarcity:Asymmetric synthesis process development requires rare expertise in both organocatalytic mechanism design and pharmaceutical regulatory filing requirements.
- Validation Timelines:FDA ICH Q3D compliance documentation for new catalyst systems extends qualification cycles by 18-36 months versus established metal-catalyst routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organocatalyst Market |
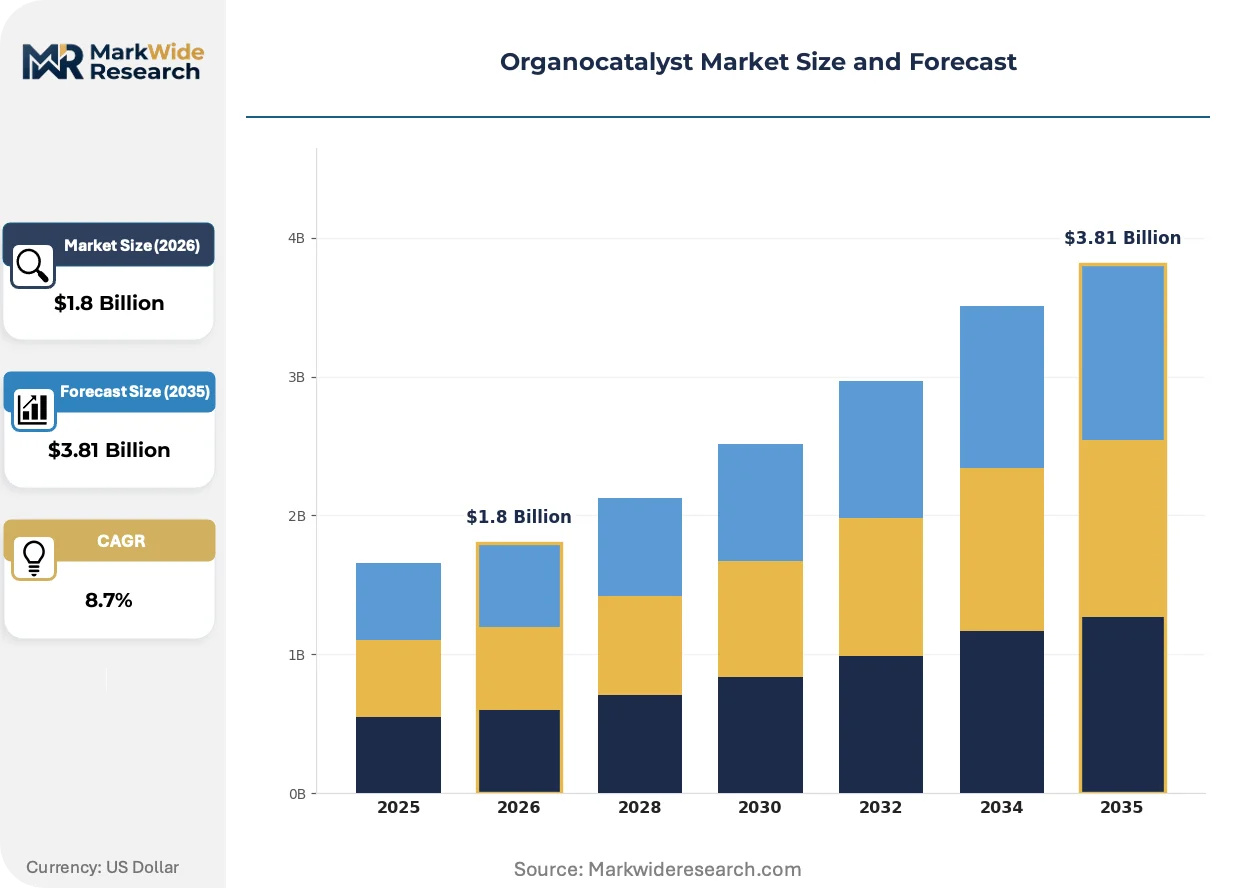
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomass-derived, Amino Acid-based, Hydrocarbon-based, Others Application: Polymerization, Asymmetric Synthesis, Organic Reactions, Fine Chemicals End User: Chemical Industry, Pharmaceutical Manufacturers, Academic Research, Agrochemical Firms Delivery Mode: Solid Phase, Liquid Phase, Gas Phase, Others |
| Companies Covered | BASF SE, Evonik Industries AG, Codexis, Inc., Strem Chemicals, Inc., Johnson Matthey, Solvias AG, Chiral Technologies, Sigma-Aldrich, TCI Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organocatalyst Market Evolving Landscape
Continuous flow chemistry is rewriting process economics for organocatalytic transformations. Equipment miniaturization and real-time analytics are compressing development cycles while improving stereoselectivity control.
Immobilized organocatalyst systems on magnetic nanoparticles are displacing conventional solid-phase supports in pharmaceutical manufacturing. Merck KGaA and contract manufacturers are piloting these systems for multi-kilogram API batches. The technology is displacing traditional filtration-based recovery methods by enabling magnetic separation with 99%+ catalyst retention.
EPA toxic substance controls are tightening residual metal thresholds in drug substances. The agency's updated guidance on elemental impurities is forcing originator firms to document catalyst fate maps through complete synthetic sequences. Small-molecule API producers are responding by front-loading organocatalyst screening in route selection protocols.
Pharmaceutical procurement teams are consolidating qualified catalyst suppliers into preferred vendor panels with multi-year volume commitments. This concentration is displacing spot-market purchasing for critical asymmetric steps. The shift is most visible in Germany, where BASF SE and Evonik Industries anchor specialized production clusters with integrated analytical services.
Organocatalyst Market Segmentation
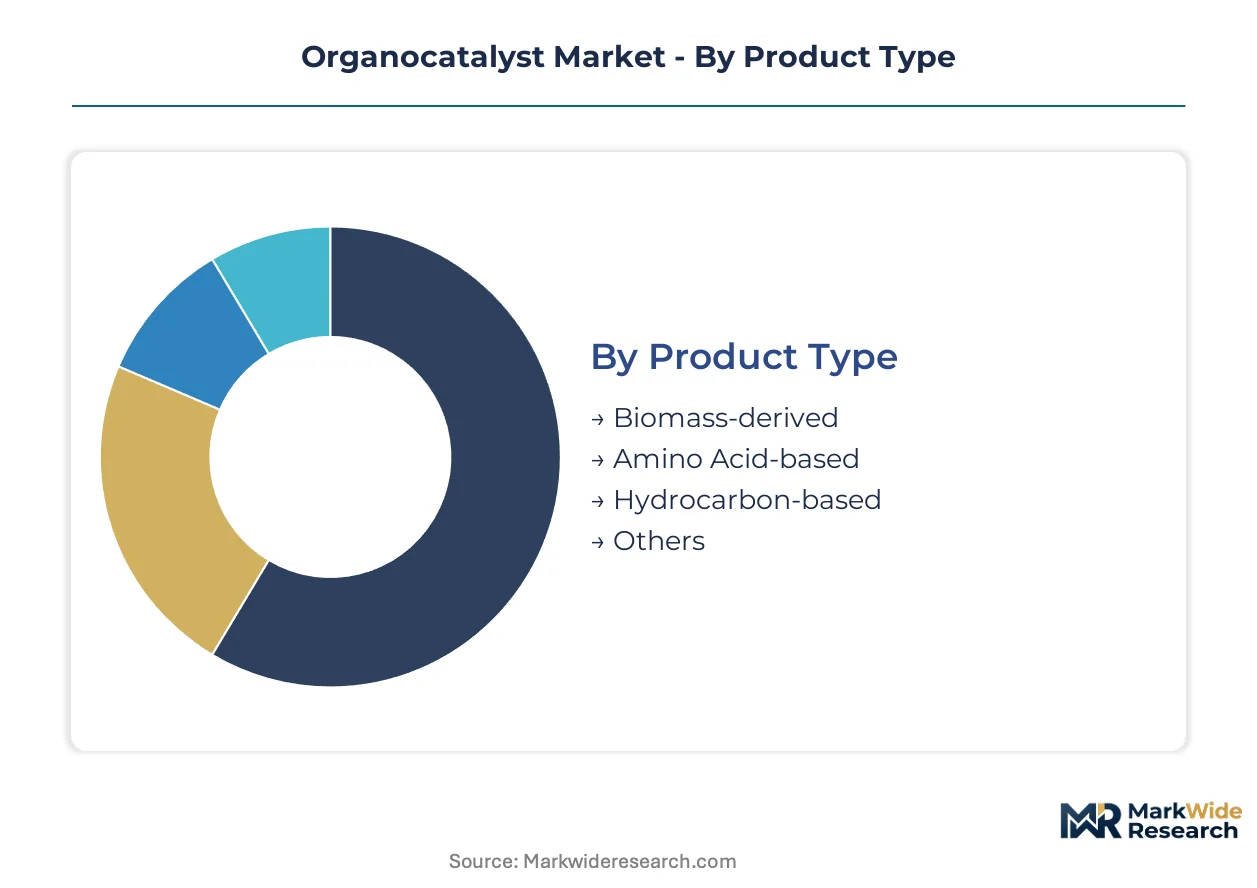
Organocatalyst procurement channels diverge sharply across product types and end-use specifications. Pharmaceutical manufacturers route amino acid-based catalysts through qualified supplier panels with integrated analytical services, while chemical industry buyers access hydrocarbon-based variants through broader distribution networks.
Product Type:
Channel access varies by feedstock origin and purity certification requirements. Biomass-derived and amino acid-based variants flow through specialized fine chemical distributors with fermentation supply chain integration, while hydrocarbon-based products reach broader industrial chemical channels.
- Amino Acid-based:These catalysts leverage established chirality control from fermentation-derived feedstocks. Pharmaceutical manufacturers in Germany and Switzerland concentrate procurement here, driven by REACH registration requirements for metal-free synthetic routes. EMA quality guidelines favor these variants for API production.
- Biomass-derived:Emerging from agricultural waste streams and lignocellulosic sources, these catalysts address green chemistry mandates from large pharmaceutical procurement teams. Supply channels remain limited to specialty biochemical distributors with sustainability certification capabilities.
- Hydrocarbon-based:Petrochemical-derived structures serve bulk chemical applications through standard industrial chemical distribution. Cost positions compete with traditional acid-base catalysts in non-chiral transformations.
- Others:Synthetic peptide and nucleobase-derived catalysts occupy niche academic and early-stage pharmaceutical research channels.
By volume, amino acid-based leads. By growth pace, biomass-derived is expanding most quickly.
Application:
Margin structures stratify across application tiers. Asymmetric synthesis commands premium pricing through pharmaceutical contract manufacturing channels, while polymerization applications access volume-driven pricing through petrochemical procurement frameworks.
- Asymmetric Synthesis:Enantioselective transformations for chiral API intermediates generate the deepest margin pools. FDA ICH Q3D compliance documentation and EPA residual metal thresholds drive displacement of transition-metal alternatives here. Single-enantiomer drug substance demand from originator firms sustains pricing power.
- Polymerization:Stereoselective ring-opening polymerization for high-performance polymers represents an underpenetrated vertical. Process economics depend on catalyst recovery rates in continuous flow systems.
- Fine Chemicals:Fragrance and agrochemical intermediate production utilizes organocatalysts where metal residue specifications from EU F-Gas Regulation and national chemical registries restrict traditional options.
- Organic Reactions:General synthetic methodology applications span academic research procurement and early-stage pharmaceutical route scouting with lower volume concentration.
Asymmetric synthesis dominates revenue contribution. Polymerization shows the steepest expansion trajectory as specialty polymer demand climbs.
End User:
Customer sophistication determines service bundling and contract structures. Pharmaceutical manufacturers demand integrated analytical and regulatory documentation, while academic buyers prioritize catalog breadth and rapid fulfillment.
- Pharmaceutical Manufacturers:These buyers consolidate qualified suppliers into preferred vendor panels with multi-year volume commitments. FDA and EMA filing requirements extend qualification cycles, locking in supplier relationships.
- Chemical Industry:Bulk chemical producers access organocatalysts through spot-market and annual contract purchasing with less stringent purity documentation.
- Agrochemical Firms:Chiral crop protection intermediate synthesis drives selective adoption where EPA toxic substance controls restrict metal catalyst residues.
- Academic Research:University and institutional laboratories source through scientific distributors with broad catalog offerings and grant-funded procurement flexibility.
Pharmaceutical manufacturers anchor revenue concentration. Agrochemical firms are gaining share fastest as chiral pesticide registration expands.
Delivery Mode:
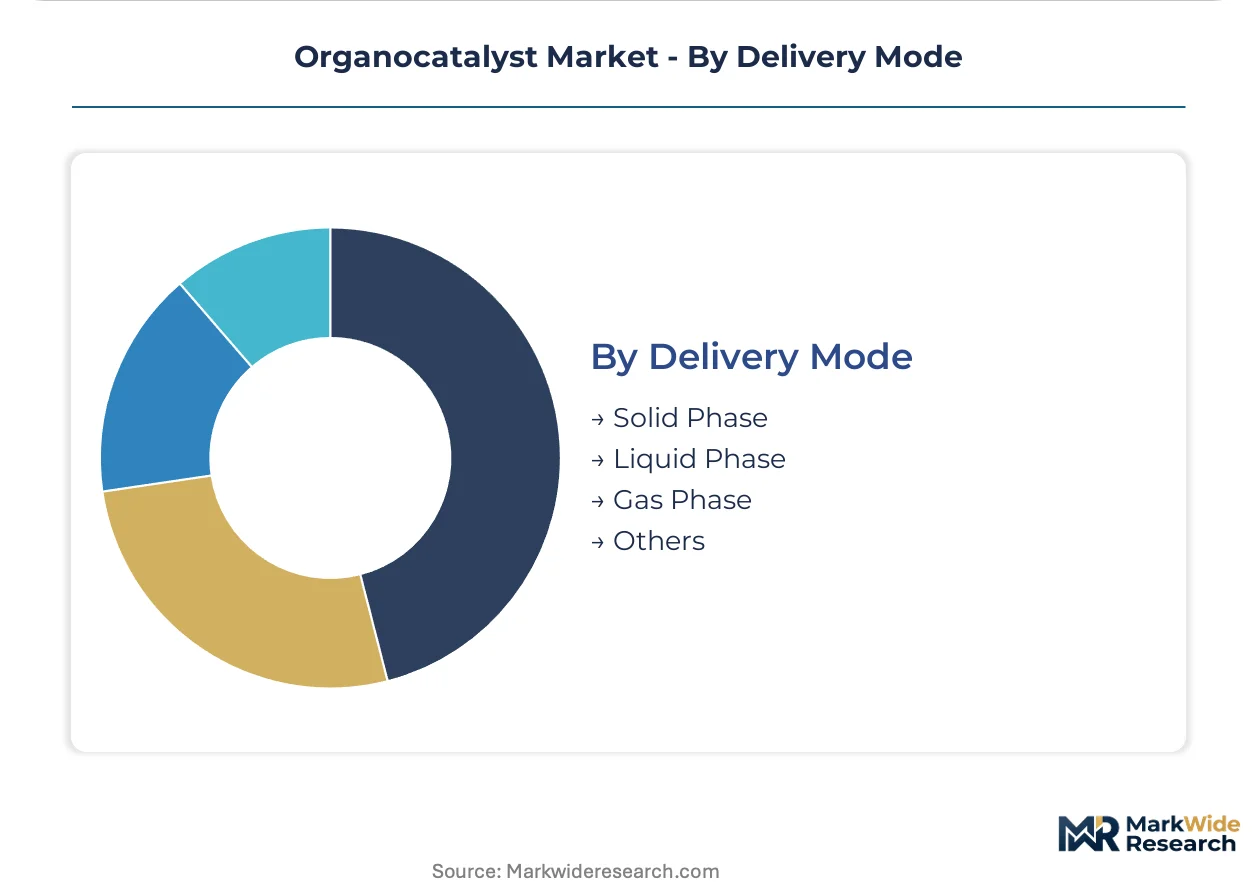
Process economics hinge on separation technology compatibility. Solid-phase delivery dominates where catalyst recovery and recyclability determine manufacturing cost structures.
- Solid Phase:Immobilized catalysts on magnetic nanoparticles and conventional supports enable filtration or magnetic separation with high retention rates. Merck KGaA and contract manufacturers pilot these systems for multi-kilogram API batches.
- Liquid Phase:Homogeneous catalysis in solution simplifies reaction engineering but complicates downstream purification. Typical loadings of 1-20 mol% inflate raw material costs versus heterogeneous alternatives.
- Gas Phase:Vapor-phase organocatalytic transformations remain limited to specialized petrochemical and polymerization applications with dedicated reactor infrastructure.
- Others:Supercritical fluid and ionic liquid delivery modes occupy experimental and pilot-scale process development channels.
Solid phase leads by installed manufacturing volume. Liquid phase is climbing the fastest as continuous flow chemistry rewrites process economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in Switzerland and Singapore absorb premium pricing for catalyst purity certification, whereas bulk chemical buyers in India and Brazil negotiate aggressively on amino acid-based feedstock costs. This demand-elasticity split shapes regional supplier strategies and contract structures.
Germany
BASF SE and Evonik Industries anchor specialized production clusters in Ludwigshafen and Marl, supplying asymmetric synthesis catalysts to European pharmaceutical contract manufacturers. REACH registration requirements from ECHA elevate analytical documentation burdens for catalyst impurities, favoring metal-free organocatalysts over transition-metal alternatives. The Rhine-Neckar metropolitan region concentrates fermentation-derived amino acid feedstock integration with catalyst finishing capabilities.
United States
FDA ICH Q3D standards on elemental impurities drive pharmaceutical manufacturers toward organocatalyst screening in early route selection protocols. EPA toxic substance controls tighten residual metal thresholds in drug substances, forcing originator firms to document catalyst fate maps. The Boston-Cambridge biotech corridor and New Jersey pharmaceutical belt concentrate demand for enantioselective synthesis catalysts with integrated regulatory filing support.
Switzerland
Swissmedic quality guidelines and premium pricing for single-enantiomer drug substances sustain deep margin pools for pharmaceutical-grade organocatalysts. Basel anchors specialized fine chemical manufacturing with integrated catalyst production and analytical services. Roche and Novartis procurement teams consolidate qualified suppliers into preferred vendor panels with multi-year volume commitments.
India
CDSCO filing requirements and PLI scheme incentives for active pharmaceutical ingredient production accelerate organocatalyst adoption in generic drug manufacturing. Hyderabad and Ahmedabad clusters specialize in cost-optimized asymmetric synthesis for export markets. Fermentation-based amino acid feedstock availability from Maharashtra and Gujarat supports domestic catalyst manufacturing scale-up.
China
NMPA pharmaceutical quality standards and dual carbon goals from MEE elevate metal-free catalyst preferences in synthetic route selection. The Yangtze River Delta concentrates contract manufacturing demand for chiral intermediates with stringent impurity specifications. Shanghai and Suzhou industrial parks host pilot-scale continuous flow organocatalytic transformations for multi-ton API batches.
Organocatalyst Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the organocatalyst market. Integrated chemical conglomerates with fermentation feedstock control compete against specialized asymmetric synthesis boutiques with regulatory filing expertise. The structure segments into three tiers: global diversified chemical majors, regional fine chemical specialists, and enzyme-biocatalysis hybrid platforms. Dominant competitive moves include backward integration into amino acid fermentation streams and strategic partnerships with pharmaceutical contract manufacturers for co-development of immobilized catalyst systems.
Among German-based chemical majors, BASF SE and Evonik Industries AG exemplify integrated production archetypes with captive supply of fermentation-derived chirality sources. Codexis, Inc. occupies a position bridging biocatalytic and purely chemical catalysis platforms. These three entities represent distinct strategic postures: diversified chemical integration, specialized asymmetric synthesis services, and enzyme-compatible hybrid technology development.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Codexis, Inc. |
| Strem Chemicals, Inc. |
| Johnson Matthey |
| Solvias AG |
| Chiral Technologies |
| Sigma-Aldrich |
| TCI Chemicals |
| Others |
Value Network & Pricing Analysis
REACH registration requirements from ECHA gate both supplier qualification and price differentiation simultaneously, forcing pharmaceutical manufacturers to absorb premium certification costs for metal-free catalyst routes while squeezing hydrocarbon-based variants in bulk chemical channels.
Pricing Analysis
After-sales revenue from multi-year analytical service contracts drives lifetime value for qualified suppliers. Three-tier pricing structure across pharmaceutical-grade, fine-chemical-grade, and industrial-grade certification levels stratifies the market. Cost compression in industrial-grade amino acid-based catalysts is intensifying because fermentation feedstock competition from food and feed sectors constrains supply elasticity. Generic drug manufacturers in India exhibit the highest price sensitivity, while Swiss originator firms absorb premium pricing for integrated regulatory filing support.
Supply Chain Analysis
Inbound logistics costs from Shanghai port congestion and container availability constraints on Asia-Europe trade lanes elevate working capital requirements for catalyst importers. Supply concentrates in Germany, China, and India, with Ludwigshafen, Shanghai, and Hyderabad anchoring specialized production clusters. Raw material dependencies center on fermentation-derived L-proline, L-valine, and petrochemical-derived pyrrolidine derivatives. Single-source vulnerability in magnetic nanoparticle support materials from Chinese rare earth processors creates chokepoint exposure. Distribution runs through qualified supplier panels with integrated analytical services for pharmaceutical manufacturers, while chemical industry buyers access broader distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organocatalyst demand is accelerating as FDA ICH Q3D and REACH frameworks displace transition-metal alternatives, creating a high-growth disruption anchored in regulatory inflection rather than technological substitution alone.
For Market Incumbents: Secure captive fermentation supply chains for amino acid feedstocks to defend against specialty biochemical distributors entering catalyst finishing. Deepen analytical service bundling to lock in pharmaceutical contract manufacturing relationships against enzyme-biocatalysis hybrid platforms. For New Entrants and Emerging Players: Anchor in stereoselective polymerization applications for high-performance materials, where organocatalyst penetration remains underdeveloped relative to pharmaceutical asymmetric synthesis. Target agrochemical chiral intermediate synthesis as the fastest-expanding procurement segment. Lead with continuous flow-compatible immobilized catalyst systems to differentiate from established homogeneous alternatives. For Investors and Strategic Acquirers: FDA ICH Q3D implementation reshapes the acquisition landscape by elevating regulatory documentation capabilities above pure manufacturing scale. Five-to-ten year viability favors targets with integrated REACH registration expertise and pharmaceutical filing track records. Watch for CDSCO and NMPA alignment with ICH Q3D standards as the signal indicating accelerated Asian market premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | Captive L-proline supply from Maharashtra fermentation clusters secures cost positions against petrochemical-derived alternatives. |
| Immobilized Catalyst Platform Development | Magnetic nanoparticle support systems enable 99% catalyst retention, displacing filtration-based recovery in multi-kilogram API batches. |
| Continuous Flow Chemistry Partnerships | Equipment miniaturization alliances with pharmaceutical contract manufacturers compress development cycles for asymmetric synthesis routes. |
| Green Chemistry Certification Program | Sustainability credentials from agricultural waste stream biomass-derived catalysts unlock preferred vendor status with ESG-mandated procurement teams. |
| Regulatory Filing Service Expansion | Integrated FDA and EMA documentation capabilities extend customer lock-in through 18-36 month qualification cycles. |
Research Methodology
The analysis maps amino acid-based, biomass-derived, hydrocarbon-based, and synthetic peptide catalyst sub-sectors, each validated through synthesis chemists, pharmaceutical procurement managers, regulatory affairs specialists, and contract manufacturing executives. Primary interviews with plant managers at German chemical majors, technical R&D directors at Indian API producers, and distribution channel partners in Swiss fine chemical networks combined with secondary validation from ECHA REACH registrations, FDA drug master files, SEC 10-K chemical segment disclosures, and customs trade data. Bottom-up catalyst volume modeling and top-down pharmaceutical intermediate demand triangulation anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product feedstock origin, application end-use, delivery mode, and customer regulatory sophistication tier. CAGRs derived from pharmaceutical pipeline analysis for chiral API candidates and polymerization technology adoption curves. Industry-specific forecast inputs incorporated green chemistry procurement mandate diffusion rates and continuous flow reactor installation trajectories at contract manufacturers.
Underlying assumptions cover sustained REACH and FDA ICH Q3D enforcement stringency, with deviation risk concentrated in potential harmonization delays for NMPA and CDSCO standards. Forecasts reflect these conditions; outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Acetaldehyde Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Organic Binders Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Chloroethylene Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Phenolic Board Market
Organic Chemicals
Bromobenzene Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
North America Humic Acid Market
Organic Chemicals
Aspartic Acid Market