
 2-Methylbutanoic Acid Market | 2026-2036
2-Methylbutanoic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
2-Methylbutanoic Acid Market Analysis
Custom synthesis and contract manufacturing services is repositioning how 2-methylbutanoic acid reaches end-users, shifting volume from spot chemical trading to long-term supply agreements. Merck KGaA leverages its pharmaceutical-grade certification network to anchor premium positioning in European and North American markets. UBE Industries sustains backward integration into petrochemical feedstocks, securing cost advantages for bulk ester production. Shanghai Aladdin Biological Technology Co., Ltd. competes through extensive catalog breadth and rapid sample fulfillment for research-scale buyers.
2-Methylbutanoic acid is a branched-chain carboxylic acid with the molecular formula C5H10O2, typically synthesized via oxo-chemistry or fermentation routes and valued for its chiral properties in fine chemical applications. The esters segment dominates commercial volume, serving as flavor and fragrance intermediates where odor profiles command specification premiums. Pharmaceutical-grade acids attract the fastest expansion, driven by API manufacturers seeking enantiomerically pure building blocks. Liquid form leads packaging throughput, though crystalline grades capture disproportionate margin in high-purity pharmaceutical contracts.
EPA oversight in the United States and REACH registration in Europe enforce rigorous substance documentation and purity thresholds that filter out non-compliant suppliers. China's SAMR and India's CDSCO impose parallel pharmaceutical excipient standards that shape import eligibility and local manufacturing investment. Japan's PMDA maintains additional GMP alignment requirements for API-grade materials entering its domestic supply chain. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate compliance cost shifts and qualification timeline extensions.
Market Dynamics
Pharmaceutical formulators in India and China are consolidating purchases of high-purity 2-methylbutanoic acid grades, compressing qualification timelines and forcing suppliers to restructure certification investments around dual-jurisdiction compliance.
Growth Catalysts
- API-grade demand surge:Active pharmaceutical ingredient manufacturers in the Mumbai-Pune industrial corridor are expanding enantiomerically pure building block procurement, pulling volume toward chiral-specific synthesis routes.
- REACH compliance premium:European REACH registration requirements for substance documentation are filtering out non-compliant traders, concentrating volume among certified suppliers who can deliver batch-level purity certificates.
- Esterification technology advancement:Continuous-flow reactor systems are reducing solvent waste in flavor and fragrance intermediate production, improving yield economics for branched-chain carboxylic acid derivatives.
Market Restraints
- Petrochemical feedstock volatility:Propylene and syngas price swings directly impact oxo-chemistry production economics, squeezing margin for bulk ester manufacturers without backward integration.
- Zhejiang supply concentration:Chemical manufacturing clusters in Zhejiang Province handle disproportionate global volume, creating geographic vulnerability to regional environmental enforcement actions or logistics disruptions.
- Fermentation route yield ceiling:Microbial production of chiral 2-methylbutanoic acid remains trapped below commercial scale thresholds, limiting alternative sourcing for pharmaceutical-grade material.
Strategic Opportunities
- Brazilian flavor market penetration:ANVISA regulatory alignment with ICH guidelines is opening import pathways for certified pharmaceutical-grade acids into Latin American fragrance formulation.
- Biocatalytic chiral resolution:Lipase-mediated kinetic resolution is converging with continuous processing to enable single-enantiomer production at intermediate scale, bridging the gap between fermentation and chemical synthesis.
- CDSCO excipient standardization:India's pharmaceutical regulator is harmonizing import testing protocols, creating first-mover advantage for suppliers who pre-qualify laboratory facilities in Hyderabad and Ahmedabad.
Industry Challenges
- Multi-jurisdiction dossier management:API manufacturers must maintain parallel EPA, REACH, and SAMR substance files, stretching regulatory affairs capacity and extending qualification cycles.
- High-purity crystallization capex:Pharmaceutical-grade solid form production requires GMP-aligned isolation equipment and dedicated cleanroom suites, blocking mid-scale entrants from margin-rich contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Methylbutanoic Acid Market |
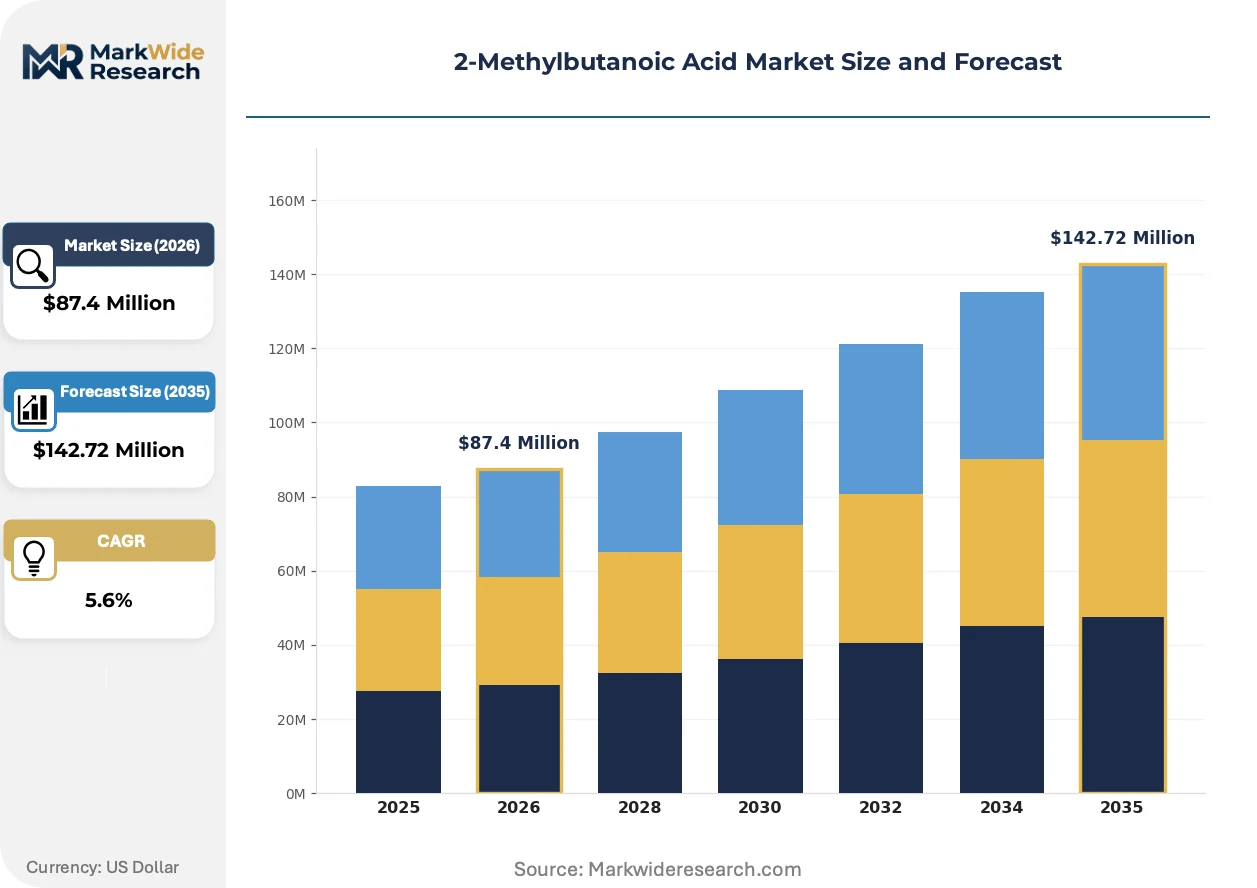
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $142.72 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amines, Esters, Acids, Alcohols End Use Industry: Pharmaceuticals, Agrochemicals, Food & Beverages, Cosmetics Form: Liquid, Solid, Powder, Crystalline Packaging Type: Drums, Bags, Containers, Cylinders |
| Companies Covered | TCI Chemicals (India) Pvt. Ltd., Zhejiang Unipharma-Chem, UBE Industries, Shanghai Aladdin Biological Technology Co., Ltd., Carbosynth Limited, Merck KGaA, Chemwill Asia, Univar Solutions Inc., Hangzhou Dayangchem Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Methylbutanoic Acid Market Emerging Trajectories
Process intensification and regulatory harmonization are compressing the traditional separation between commodity ester production and pharmaceutical-grade acid supply, forcing technology choices that serve both specification tiers.
Continuous-flow biocatalysis is unifying chiral resolution with real-time quality monitoring, embedding enzymatic selectivity into plug-flow reactor architectures. Pharmaceutical contract manufacturers in Switzerland and Singapore are piloting these systems for multi-kilogram API precursor batches. The technology is unifying previously separate upstream synthesis and downstream purification steps, collapsing facility footprint requirements.
EPA's evolving New Chemicals Program guidelines are tightening pre-manufacture notification thresholds for branched-chain carboxylic acid derivatives, extending review timelines for novel ester introductions. Specialty chemical importers are responding by prioritizing existing chemical inventory listings over new substance development. Food-contact and fragrance applications face the most acute compliance timeline extensions.
Long-term supply agreements are displacing spot chemical trading as the dominant procurement mode for pharmaceutical-grade material. API manufacturers in Germany and Japan are locking in three-to-five-year contracts with fixed price adjustment mechanisms, transferring inventory carrying costs upstream. This concentration is most visible in enantiomerically pure acid categories where qualification investments create switching friction.
2-Methylbutanoic Acid Market Segmentation
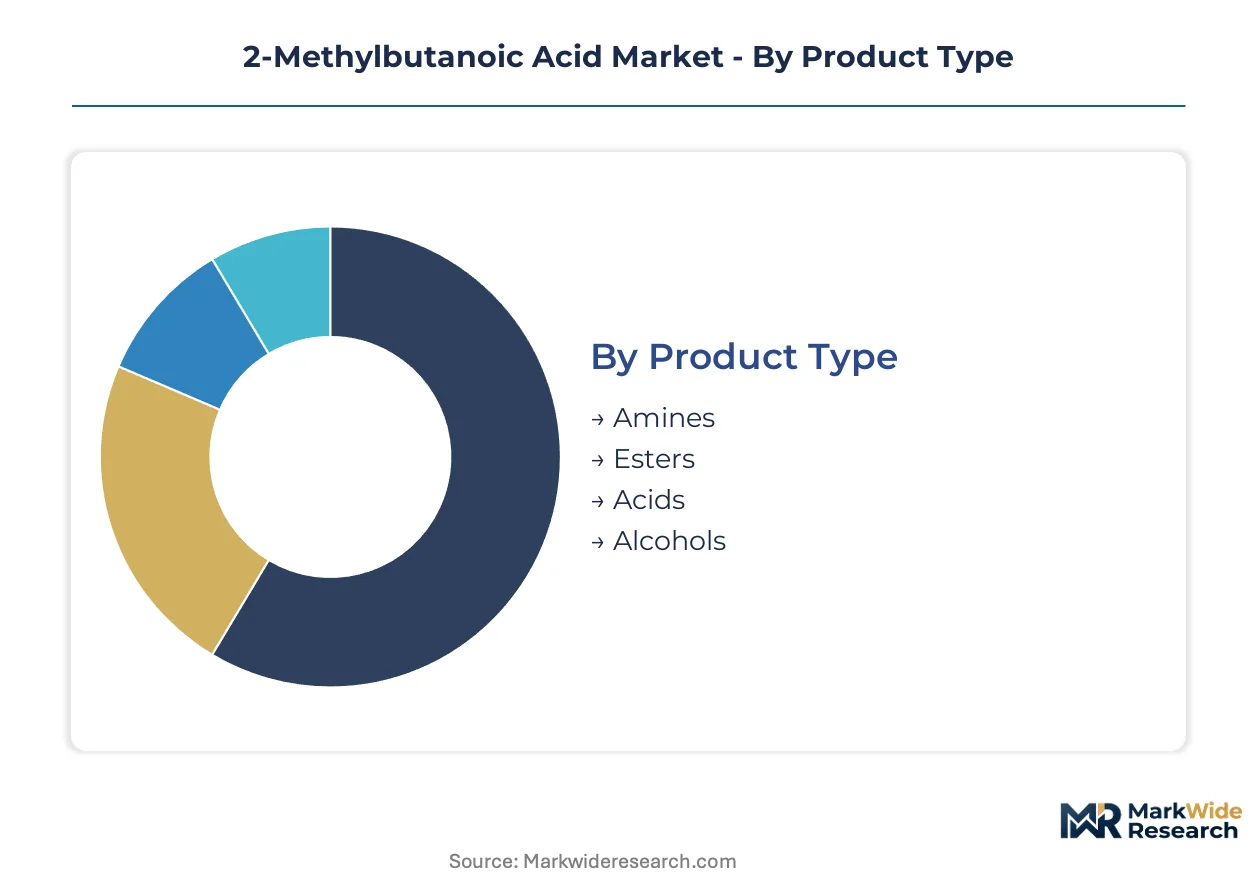
Segmentation in 2-methylbutanoic acid markets reveals how specification tiers map to divergent compliance burdens and margin structures. Pharmaceutical-grade material commands batch-level documentation that commodity ester producers rarely maintain.
Product Type:
Certification requirements fragment sharply across this dimension, with pharmaceutical and food-contact applications demanding REACH registration or FDA food additive status that industrial grades bypass entirely.
- Amines:Derivatives formed through reductive amination of the parent acid, serving as chiral building blocks for agrochemical active ingredients. Demand clusters with herbicide manufacturers in the Mumbai-Pune corridor facing CDSCO import testing protocols.
- Esters:The commercial volume anchor, produced via acid-catalyzed condensation with C1-C4 alcohols for flavor and fragrance applications. Odor profile specificity drives specification premiums among European fragrance houses navigating REACH substance documentation.
- Acids:Chiral resolution of the free acid supplies API precursors for cardiovascular and anti-inflammatory drug classes. PMDA-aligned GMP certification gates entry into Japanese pharmaceutical supply chains.
- Alcohols:Reduction products finding niche solvent applications and specialty polymer plasticizer feedstocks.
Esters sit at the top of the volume ranking, with acids climbing the fastest as enantiomerically pure API building blocks gain procurement priority.
End Use Industry:
Cost-to-serve economics separate these verticals, with pharmaceutical qualification cycles stretching 18-24 months against 4-6 week food additive approvals.
- Pharmaceuticals:API manufacturers source high-purity chiral grades for enantioselective synthesis routes. EMA and FDA dual-filing requirements concentrate procurement among suppliers with established DMF repositories.
- Agrochemicals:Herbicide and fungicide formulators in Brazil and India consume technical-grade material for amidation reactions. ANVISA alignment with ICH guidelines is streamlining import pathways for certified grades.
- Food & Beverages:Flavor esters face FEMA GRAS or EFSA food additive evaluations, with documentation burdens lighter than pharmaceutical tiers but stricter than industrial applications.
- Cosmetics:Fragrance intermediates require IFRA compliance for allergen thresholds, particularly in EU and Japanese personal care markets.
Pharmaceuticals command the steepest expansion trajectory, with agrochemicals holding the broadest geographic footprint.
Form:
Physical state determines logistics economics and purity preservation, with hygroscopic crystalline grades demanding controlled-atmosphere handling that liquid bulk shipments avoid.
- Liquid:Standard industrial grade shipped in bulk ISO-tanks for esterification feedstock. Zhejiang Province producers dominate spot market liquidity through tank farm infrastructure.
- Solid:Flaked or pastille forms for automated handling in flavor compound manufacturing. Melting point control preserves odor profile integrity during storage.
- Powder:Spray-dried grades for rapid dissolution in aqueous formulation systems.
- Crystalline:Enantiomerically pure material isolated through fractional crystallization or simulated moving bed chromatography. GMP-aligned cleanroom packaging commands 3-4x liquid grade pricing.
Liquid form leads throughput volumes, with crystalline grades gaining share fastest in high-purity pharmaceutical contracts.
Packaging Type:
Container specification scales with customer concentration and contamination sensitivity, from multi-ton bulk to single-kilogram amber glass for analytical standards.
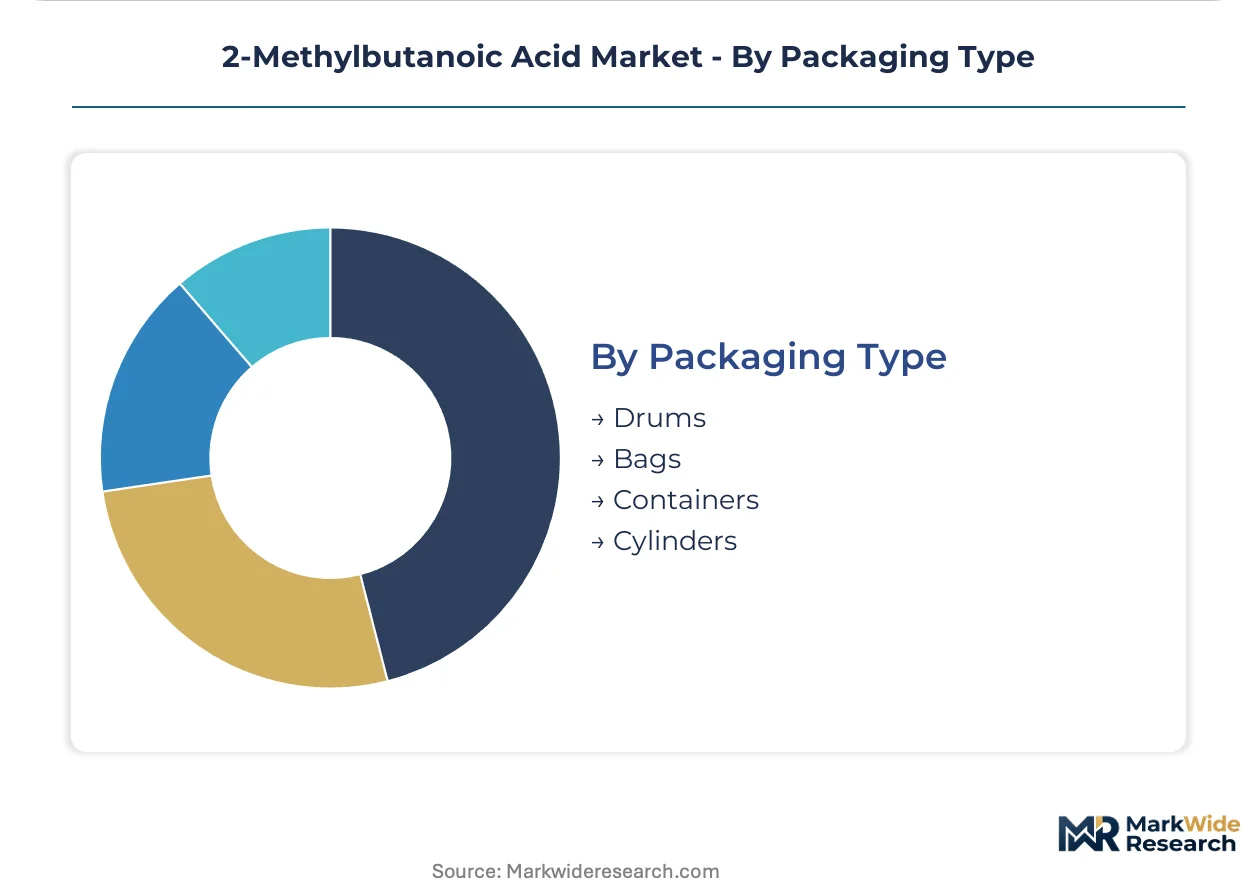
- Drums:200-liter steel or HDPE containers for mid-scale chemical manufacturing. UN-certified designs dominate cross-border chemical trade.
- Bags:Multi-layer laminated sacks for solid-form material in food and feed additive applications. Moisture barrier properties determine shelf-life guarantees.
- Containers:Intermediate bulk containers and flexitanks for continuous-flow esterification operations.
- Cylinders:Pressurized or inert-atmosphere vessels for oxygen-sensitive chiral grades. Pharmaceutical contract manufacturers in Singapore and Switzerland specify nitrogen backfill protocols.
Drums anchor procurement volumes, with cylinders expanding most quickly in API-grade supply chains requiring atmospheric integrity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China handles bulk ester production volumes while Switzerland concentrates pharmaceutical-grade refinement, illustrating how specification tiers map to geographic specialization in this market.
China
Zhejiang Province chemical clusters supply the majority of global flavor and fragrance ester intermediates, with oxo-chemistry facilities optimized for continuous-flow production. SAMR pharmaceutical excipient standards are tightening documentation requirements for API-grade exports. Hangzhou and Ningbo industrial zones are consolidating capacity under stricter MEE environmental enforcement protocols.
United States
Specialty chemical distributors serve fragrance compounders in New Jersey and Pennsylvania with REACH-registered ester grades. EPA New Chemicals Program reviews are extending timelines for novel branched-chain derivative introductions. Gulf Coast petrochemical corridors provide propylene feedstock proximity for oxo-synthesis operations.
India
API manufacturers in the Mumbai-Pune corridor are consolidating high-purity acid procurement for cardiovascular drug synthesis routes. CDSCO excipient standardization is harmonizing import testing protocols across Hyderabad and Ahmedabad laboratory networks. Maharashtra's pharmaceutical manufacturing zones are attracting pre-qualified supplier investments.
Germany
Merck KGaA anchors European pharmaceutical-grade certification networks from Darmstadt, serving EMA-aligned API manufacturers. REACH substance documentation requirements filter non-compliant traders from the regional supply base. Bavarian chemical distributors specialize in enantiomerically pure building blocks for contract synthesis.
Japan
PMDA GMP alignment requirements gate API-grade material entry into domestic pharmaceutical supply chains. Osaka-based fragrance houses specify enantiomeric purity thresholds for chiral ester intermediates. METI industrial standards shape specification negotiations for food-contact and cosmetic applications.
2-Methylbutanoic Acid Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade supply consolidating around certification-holders while commodity esters fragment across regional traders. Three archetypes dominate: backward-integrated petrochemical producers, catalog-breadth research chemical distributors, and GMP-certified pharmaceutical excipient specialists. Capacity expansion in Zhejiang Province and strategic partnerships for dual-jurisdiction compliance represent the dominant competitive moves reshaping supply relationships.
Within the GMP-certified tier, Merck KGaA exemplifies European pharmaceutical-grade positioning through its Darmstadt-based certification network. UBE Industries represents backward-integrated petrochemical production with captive feedstock control. Shanghai Aladdin Biological Technology Co., Ltd. occupies the research-scale distribution archetype, competing through catalog breadth and rapid sample fulfillment. These three anchors illustrate how specification tier and geographic origin stratify competitive positioning across pharmaceutical, industrial, and research end-use segments.
| Leading Market Players |
|---|
| TCI Chemicals (India) Pvt. Ltd. |
| Zhejiang Unipharma-Chem |
| UBE Industries |
| Shanghai Aladdin Biological Technology Co., Ltd. |
| Carbosynth Limited |
| Merck KGaA |
| Chemwill Asia |
| Univar Solutions Inc. |
| Hangzhou Dayangchem Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between pharmaceutical and industrial tiers splits pricing power along compliance investment lines, with REACH-registered suppliers in Germany and FDA-aligned producers in the United States commanding 3-4x liquid-grade spot pricing while Zhejiang bulk ester manufacturers compete on throughput volume. This bifurcation feeds directly into supply chain configuration: high-purity crystalline grades demand nitrogen-backfill cylinder logistics and GMP-aligned cleanroom packaging, whereas liquid bulk moves through standard ISO-tank infrastructure with minimal documentation overhead.
Pricing Analysis
Capacity additions in Zhejiang Province are reshaping price floors for commodity ester grades even as pharmaceutical-tier premiums widen. Three-tier pricing structure across premium, standard, and economy levels anchors the market: enantiomerically pure crystalline material for API synthesis commands top tier, REACH-registered industrial acids occupy mid-tier, and unregistered bulk esters populate spot-traded economy tier. Price differentiation hinges on certification level (EMA/FDA dual-filing versus single-jurisdiction registration) and volume scale (long-term offtake agreements versus spot procurement). Cost compression in bulk ester segments is intensifying because propylene feedstock volatility squeezes non-integrated producers. Research-scale buyers through catalog distributors exhibit highest price sensitivity; Japanese pharmaceutical contract manufacturers show lowest sensitivity due to PMDA-mandated qualification switching costs.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical manufacturing zones are reshaping sourcing patterns for API-grade material, pushing suppliers toward Hyderabad and Ahmedabad laboratory pre-qualification. Supply concentrates in China, India, and Germany: Zhejiang Province handles bulk ester volume, the Mumbai-Pune corridor processes high-purity acid for cardiovascular APIs, and Darmstadt anchors European pharmaceutical-grade refinement. Raw material dependencies draw from Gulf Coast propylene corridors, syngas from coal-chemical complexes in Inner Mongolia, and chiral resolution enzymes from Danish biocatalysis specialists. Single-source vulnerability runs through Zhejiang environmental enforcement actions that disrupt global flavor intermediate availability. Distribution runs through specialty chemical distributors in New Jersey and Bavaria for certified grades, with direct mill-to-plant relationships dominating bulk ester procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-grade demand from cardiovascular and anti-inflammatory drug synthesis provides steady compounding fundamentals, with regulatory qualification friction protecting incumbent positions and fermentation-route yield ceilings delaying disruptive entry.
For Market Incumbents: Extend certification coverage into dual-jurisdiction dossiers spanning EPA, REACH, and CDSCO requirements to lock in API manufacturer switching costs. Deepen backward integration into propylene feedstocks or syngas supply to defend margin position against petrochemical volatility. Threat vector: continuous-flow biocatalysis pilots in Switzerland and Singapore could collapse the synthesis-purification step separation that underpins current facility economics. For New Entrants and Emerging Players: Launch via research-scale catalog distribution with rapid sample fulfillment protocols to build specification familiarity before pharmaceutical qualification cycles. Target Brazilian fragrance formulation market where ANVISA-ICH alignment opens import pathways for certified grades with lighter incumbent presence than European or Asian markets. White-space opportunity: biocatalytic chiral resolution at intermediate scale bridges fermentation yield ceilings and chemical synthesis cost floors. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction dossier management stretches mid-scale regulatory affairs capacity beyond sustainable overhead. Long-term viability favors GMP-certified excipient specialists with established DMF repositories and cleanroom isolation assets over commodity traders. Acquisition target archetype: regional distributors with pre-qualified laboratory networks in India or Latin America. Signal to watch: CDSCO harmonization completion triggering qualification timeline compression and supplier shakeout.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | API manufacturers in Germany and Japan are locking in three-to-five-year contracts with fixed price adjustment mechanisms. |
| Backward Integration | UBE Industries sustains captive feedstock control over propylene and syngas to secure cost advantages for bulk ester production. |
| Biocatalytic Chiral Resolution | Lipase-mediated kinetic resolution converging with continuous processing enables single-enantiomer production at intermediate scale. |
| Dual-Jurisdiction Compliance Investment | Suppliers pre-qualifying laboratory facilities in Hyderabad and Ahmedabad capture first-mover advantage under CDSCO standardization. |
| Continuous-Flow Reactor Deployment | Continuous-flow systems reduce solvent waste in flavor and fragrance intermediate production, improving yield economics for derivatives. |
Methodological Framework
Multiple input streams — regulatory filing databases, customs trade records, and primary stakeholder interviews — were reconciled to construct supply-demand balances across specification tiers. Conversations with pharmaceutical procurement managers at API manufacturers, regulatory affairs leads navigating EPA and REACH dossier requirements, plant managers at Zhejiang oxo-chemistry facilities, and fragrance house technical directors informed qualification timeline and switching cost estimates. Secondary validation drew from EMA submission databases, FDA inactive ingredient listings, CDSCO import testing protocols, and SEC filings from disclosed chemical producers. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across identified manufacturing clusters.
Cross-referencing historical price series against expert panel inputs anchored the projection framework across the analysis window. Segmentation dimensions modeled include product grade tier (pharmaceutical, food-contact, industrial), end-use industry (pharmaceuticals, agrochemicals, flavor and fragrance), physical form (liquid, solid, crystalline), and regional production hub configuration. CAGRs were derived from elasticity-adjusted demand curves incorporating API pipeline growth, regulatory harmonization schedules, and feedstock cost trajectories. Industry-specific forecast inputs encompassed fermentation-route yield improvement timelines and continuous-flow biocatalysis adoption curves at contract manufacturing organizations.
Several conditions sit outside the modeled scope, including breakthrough fermentation scale-up achieving commercial viability, abrupt environmental enforcement suspensions in Zhejiang Province, and unscheduled REACH registration fee restructuring. Forecasts reflect assumptions around regulatory timeline stability, feedstock price band persistence, and qualification friction maintenance. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
DMDM Hydantoin Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Cyclic Ketones Market
Organic Chemicals
US Humate Market
Organic Chemicals
Ethyl Levulinate Market
Organic Chemicals
Alanine Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Methacrylic Acid Market
Organic Chemicals
Azelaic Acid Market