
 Pyridine Derivatives Market | 2026-2036
Pyridine Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Pyridine Derivatives Market Analytics
REACH is decoupling European agrochemical buyers from non-compliant pyridine derivative suppliers. Jubilant Ingrevia leverages its integrated acetic acid-to-pyridine pipeline to sustain cost leadership in agrochemical-grade output. Lonza Group AG anchors pharmaceutical-grade production through FDA-inspected sites in Switzerland and the United States. Vertellus Holdings LLC specializes in high-purity picolines for electronic chemicals, competing on specification rather than volume.
Pyridine derivatives are nitrogen-containing heterocyclic aromatic compounds synthesized via aldehyde-ammonia condensation or vapor-phase cyclization, serving as essential intermediates for agrochemicals, pharmaceuticals, and specialty solvents. Industrial-grade pyridine dominates volume flows into herbicide manufacturing, while reagent-grade 3-methylpyridine commands premium pricing from pharmaceutical API contracts. The agrochemicals application segment leads absolute consumption, though healthcare end-use is expanding fastest as pyridoxine and antihistamine synthesis scales in regulated markets.
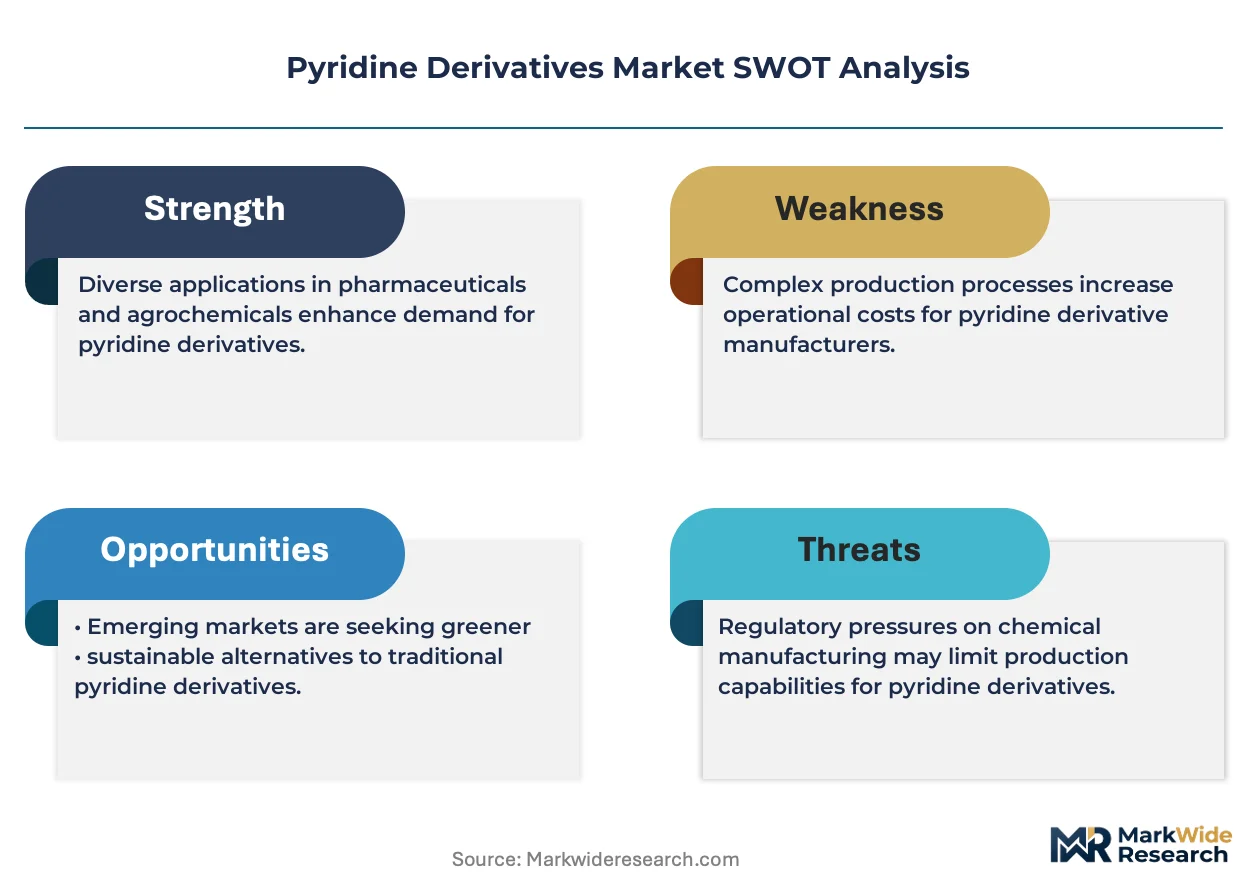
EPA registration requirements for pesticide intermediates in the United States, REACH substance authorization in Europe, and CDSCO active pharmaceutical ingredient guidelines in India collectively elevate purity documentation burdens across export channels. EMA's evolving nitrosamine impurity standards are forcing batch-level testing investments that favor integrated manufacturers over traders. Stakeholders must monitor regulatory divergence between OECD-aligned jurisdictions and emerging chemical governance frameworks to anticipate qualification timeline shifts.
Market Dynamics
REACH substance authorization in Europe is decoupling agrochemical formulators from non-compliant pyridine derivative suppliers, forcing qualification investments that favor integrated manufacturers with captive acetic acid-to-pyridine pipelines over merchant traders.
Growth Catalysts
- Herbicide synthesis scaling:Indian and Chinese agrochemical formulators are expanding pyridine derivative uptake for paraquat and diquat manufacturing, driving volume demand for industrial-grade intermediates.
- REACH compliance mandates:European substance authorization requirements are concentrating qualified supplier lists around manufacturers with documented purity certification and batch-level nitrosamine testing protocols.
- Pharmaceutical API contracts:Synthesis of pyridoxine and antihistamine active ingredients is pulling reagent-grade 3-methylpyridine demand in regulated markets.
Market Restraints
- Acetic acid feedstock volatility:Pyridine synthesis depends on acetaldehyde and formaldehyde inputs tied to petrochemical pricing cycles, compressing margin predictability for non-integrated producers.
- Supply concentration in South Asia:Merchant pyridine derivative output concentrates among Indian and Chinese manufacturers, creating single-source vulnerability for European and North American formulators.
- Nitrosamine impurity detection limits:EMA's evolving batch-testing standards are forcing capital expenditure on analytical equipment that smaller traders cannot absorb.
Strategic Opportunities
- Electronic chemicals specification:High-purity picolines for semiconductor etching and lithium-ion battery electrolyte additives command premium pricing outside commodity agrochemical channels.
- CDSCO alignment in India:Active pharmaceutical ingredient guidelines are creating pathways for domestic manufacturers to qualify for export contracts to regulated markets.
- Continuous vapor-phase cyclization:Adoption of flow chemistry reactor designs is enabling smaller batch sizes with higher purity yields for pharmaceutical-grade output.
Industry Challenges
- Analytical chemist scarcity:Nitrosamine testing protocol implementation requires specialized chromatography expertise that contract manufacturers struggle to recruit.
- Multi-jurisdiction dossier compilation:EPA registration, REACH authorization, and CDSCO filing requirements demand parallel documentation streams that extend qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyridine Derivatives Market |
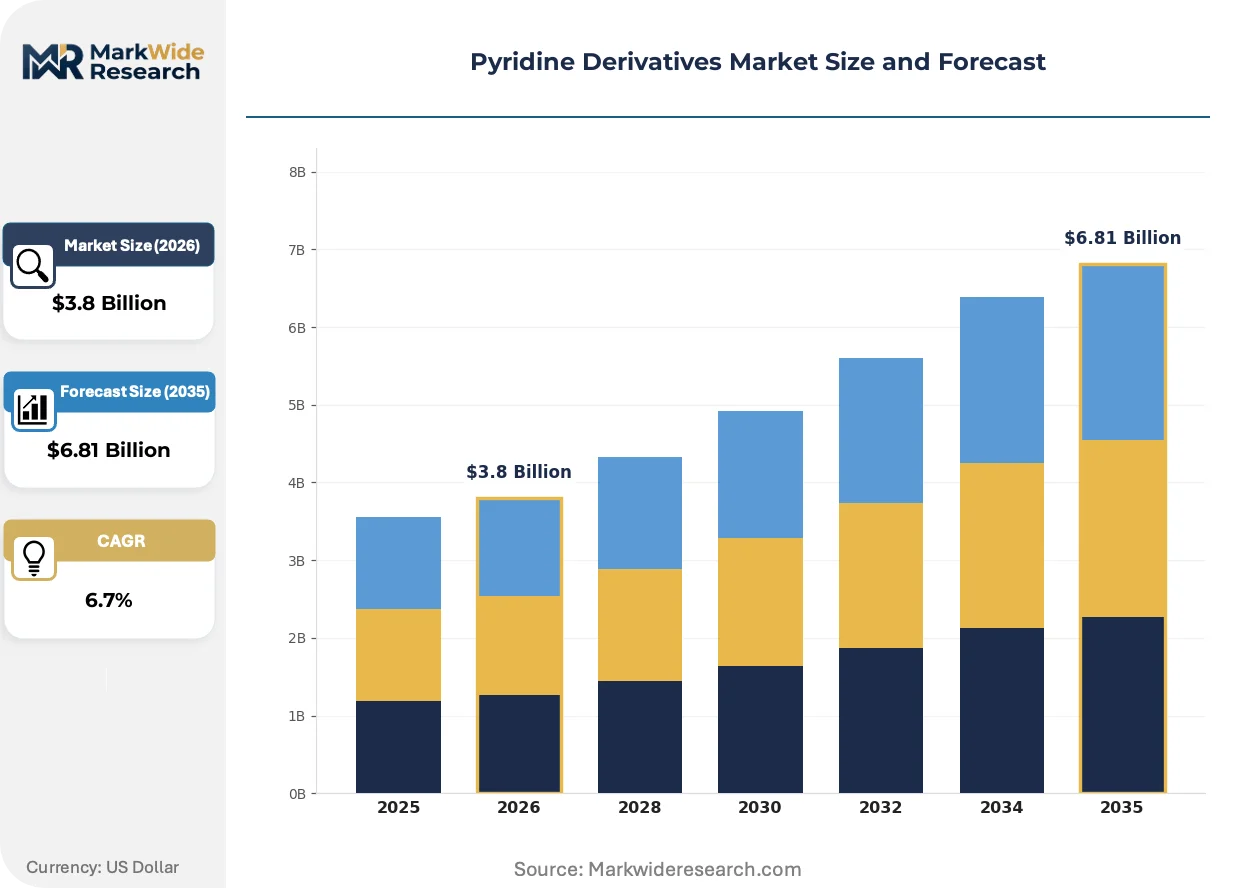
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pyridine, 2-Methylpyridine, 3-Methylpyridine, 4-Methylpyridine Application: Pharmaceuticals, Agrochemicals, Dyes, Adhesives End Use Industry: Chemicals, Agriculture, Healthcare, Paints Purity Grade: Reagent Grade, Industrial Grade, Technical Grade, Others |
| Companies Covered | Jubilant Ingrevia, Vertellus Holdings LLC, Lonza Group AG, Nanjing Redsun Co. Ltd., Resonance Specialties Ltd., Shandong Luba Chemical Co. Ltd., Hubei Sanonda Co. Ltd., Chang Chun Petrochemical Co. Ltd., Koei Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyridine Derivatives Market Evolving Landscape
Process intensification and regulatory digitization are compressing the gap between commodity agrochemical-grade output and pharmaceutical-grade certification, enabling supplier mobility across end-use verticals.
Continuous flow reactor technology for vapor-phase cyclization is unifying pyridine synthesis steps previously executed in batch mode. Pharmaceutical API manufacturers in Switzerland and the United States are adopting these systems to reduce solvent waste and improve nitrosamine control. This unification is collapsing the traditional separation between industrial-grade and reagent-grade production infrastructure.
EMA's nitrosamine impurity assessment framework is forcing batch-level testing investments across all pyridine derivative export channels to Europe. Manufacturers must now submit elemental impurity risk assessments and control strategy documentation prior to qualification. Agrochemical intermediate suppliers without in-house analytical capabilities are exiting the European market rather than absorbing compliance costs.
Formulators are consolidating procurement around qualified supplier lists with pre-submitted regulatory dossiers rather than spot-market purchasing. Large agrochemical multinationals in Germany and the United States are requiring three-year supply agreements with locked purity specifications and audit rights. This consolidation is visible most acutely in herbicide manufacturing, where paraquat registration holders are reducing approved intermediate vendors from dozens to single-digit panels.
Pyridine Derivatives Market Segmentation
Pyridine derivative buyers face divergent specification demands across agrochemical and pharmaceutical channels, forcing suppliers to maintain parallel production lines. Segmentation clarity enables formulators to match purity grades against regulatory filing requirements while optimizing procurement costs.
Product Type:
Buyers differentiate primarily by substitution pattern and downstream reactivity requirements.
- Pyridine:The unsubstituted heterocycle serves as the foundational building block for paraquat and diquat herbicide synthesis. Indian agrochemical formulators consume the largest volumes, though REACH-compliant European buyers now demand documented nitrosamine testing protocols that favor integrated manufacturers.
- 3-Methylpyridine:This isomer commands premium pricing from pharmaceutical API contracts due to its role in pyridoxine and antihistamine synthesis. Swiss and German manufacturers specify reagent-grade material with batch-level impurity certificates for regulated markets.
- 2-Methylpyridine:Picoline derivative used in specialty solvent applications and nicotine-based agrochemical intermediates.
- 4-Methylpyridine:Isomer employed in pharmaceutical synthesis and as a precursor for isoniazid derivatives.
Pyridine leads volumes today; 3-methylpyridine is gaining share fastest.
Application:
End-use specifications range from industrial-grade commodity volumes to reagent-grade pharmaceutical certifications.
- Agrochemicals:Herbicide and insecticide synthesis consumes industrial-grade pyridine derivatives at scale. Chinese and Indian formulators drive absolute demand for paraquat intermediates, while EPA registration requirements in the United States restrict qualified supplier panels.
- Pharmaceuticals:API manufacturing for vitamins, antihistamines, and tuberculosis treatments requires reagent-grade 3-methylpyridine with documented elemental impurity controls. EMA's evolving nitrosamine standards are forcing batch-testing investments that favor manufacturers with in-house analytical capabilities.
- Dyes:Synthetic colorant intermediates utilize technical-grade picolines for azo coupling reactions.
- Adhesives:Specialty solvent applications in polymer systems employ pyridine bases for controlled curing.
Agrochemicals leads volumes today; pharmaceuticals is climbing the fastest.
End Use Industry:
Industry verticals impose distinct purity thresholds and documentation burdens on suppliers.
- Chemicals:Broad intermediate consumption spans industrial solvents, specialty reagents, and polymer additives. Technical-grade material dominates this channel, with buyers prioritizing cost efficiency over certification depth.
- Agriculture:Crop protection formulators in India and China specify industrial-grade pyridine for herbicide manufacturing. CDSCO alignment is creating pathways for domestic Indian manufacturers to qualify for export contracts.
- Healthcare:Pharmaceutical manufacturing demands reagent-grade derivatives with FDA-inspected site documentation. Swissmedic and EMA requirements concentrate procurement around qualified supplier lists with pre-submitted dossiers.
- Paints:Coating applications utilize pyridine derivatives as flow-control agents and adhesion promoters.
Chemicals leads volumes today; healthcare shows the steepest expansion trajectory.
Purity Grade:
Grade selection determines regulatory qualification pathways and pricing tiers.
- Industrial Grade:Standard specification for agrochemical intermediate manufacturing. Indian and Chinese producers supply this tier at volume, though REACH compliance is decoupling non-certified suppliers from European buyer lists.
- Reagent Grade:Highest purity tier for pharmaceutical API synthesis. Lonza Group AG and Vertellus Holdings LLC compete on specification rather than volume, serving Swiss and German pharmaceutical manufacturers with batch-level nitrosamine testing.
- Technical Grade:Intermediate purity for dyes and adhesives applications where functional performance exceeds regulatory filing requirements.
- Others:Custom specifications for electronic chemicals and lithium-ion battery electrolyte additives commanding premium pricing outside commodity channels.
Industrial grade leads volumes today; reagent grade is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and analytical chemists concentrate in Basel, Ludwigshafen, and Mumbai, anchoring pharmaceutical-grade pyridine derivative production. These talent clusters enable manufacturers to meet divergent regulatory filing requirements across agrochemical and healthcare end-uses.
United States
EPA registration requirements for pesticide intermediates restrict qualified supplier panels for herbicide manufacturers. The agency maintains batch-level documentation standards that favor producers with in-house analytical capabilities. Houston and Gulf Coast chemical corridors host formulators scaling paraquat intermediate production under tightened environmental enforcement.
Germany
Bayer and BASF procurement teams demand REACH-compliant pyridine derivatives with pre-submitted nitrosamine risk assessments. ECHA substance authorization timelines extend qualification periods for new suppliers. Ludwigshafen's integrated chemical complex sustains captive acetic acid-to-pyridine pipelines that compress cost structures for agrochemical-grade output.
Switzerland
Swissmedic inspections anchor pharmaceutical-grade production for vitamin and antihistamine API synthesis. Basel's contract manufacturing cluster specializes in reagent-grade 3-methylpyridine with batch-level impurity certificates. Lonza Group AG leverages FDA-inspected sites to serve German and US pharmaceutical formulators under mutual recognition agreements.
India
CDSCO active pharmaceutical ingredient guidelines create export qualification pathways for domestic manufacturers. Maharashtra and Gujarat chemical belts expand industrial-grade pyridine output for herbicide synthesis. Jubilant Ingrevia's integrated pipeline from acetic acid derivatives sustains cost leadership in agrochemical intermediate supply.
China
MIIT industrial chemical standards and MEE environmental enforcement reshape producer compliance burdens. Jiangsu and Shandong provinces concentrate merchant pyridine derivative manufacturing for both domestic agrochemical formulators and export markets. NMPA alignment efforts enable select manufacturers to qualify for pharmaceutical API contract opportunities.
Pyridine Derivatives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers. The supplier base stratifies between integrated chemical majors with captive feedstock control and merchant traders dependent on spot-market acetaldehyde sourcing. Three archetypes dominate: acetic acid-integrated agrochemical suppliers, FDA-inspected pharmaceutical-grade specialists, and high-purity electronic chemical niche players. Competitive moves center on backward integration into acetic acid derivatives and analytical capability investments for nitrosamine testing protocols.
Among Indian integrated producers, Jubilant Ingrevia exemplifies the acetic acid-coupled archetype with cost-optimized agrochemical-grade pipelines. Vertellus Holdings LLC occupies the high-purity specification tier, competing on electronic chemical and pharmaceutical reagent standards rather than commodity volumes. Lonza Group AG anchors the regulated-market pharmaceutical segment through Swiss and US manufacturing infrastructure. These three entities represent divergent strategic positions across purity grades and end-use verticals.
| Leading Market Players |
|---|
| Jubilant Ingrevia |
| Vertellus Holdings LLC |
| Lonza Group AG |
| Nanjing Redsun Co. Ltd. |
| Resonance Specialties Ltd. |
| Shandong Luba Chemical Co. Ltd. |
| Hubei Sanonda Co. Ltd. |
| Chang Chun Petrochemical Co. Ltd. |
| Koei Chemical Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Captive acetic acid-to-pyridine integration anchors both supply security and margin control for Indian and Chinese manufacturers serving agrochemical formulators. REACH compliance costs in Europe and EPA registration burdens in the United States are decoupling non-integrated traders from qualified buyer lists, concentrating pricing power among producers with backward feedstock control.
Pricing Analysis
Reagent-grade material with bundled nitrosamine testing protocols commands substantial premiums over industrial-grade commodity volumes. Price differentiation hinges on EMA batch-certification depth and FDA-inspected site documentation for pharmaceutical API contracts. Cost compression in agrochemical-grade tiers is intensifying because Jubilant Ingrevia's integrated pipeline sustains cost leadership that merchant traders cannot match. Indian herbicide formulators exhibit highest price sensitivity, while Swiss and German pharmaceutical manufacturers prioritize specification certainty over unit economics.
Supply Chain Analysis
Freight cost differentials between Indian merchant exporters and European captive producers are reshaping procurement geography for REACH-compliant buyers. Supply concentrates in Maharashtra and Gujarat chemical belts, with Jiangsu and Shandong provinces feeding parallel export channels. Raw material flows draw from acetaldehyde and formaldehyde streams tethered to petrochemical pricing cycles. Single-source vulnerability pervades European and North American formulator procurement, as qualified supplier panels shrink under nitrosamine testing mandates. Distribution runs through long-term offtake agreements with locked purity specifications rather than spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pyridine derivatives market represents a late-cycle quality story as pharmaceutical API contracts displace commodity agrochemical volumes in value contribution. EMA nitrosamine standards and FDA site inspection requirements are concentrating procurement around manufacturers with in-house analytical capabilities.
For Market Incumbents: Anchor qualification timelines through pre-submitted REACH dossiers and CDSCO alignment investments that lock out merchant traders. Defend margin position by expanding captive acetic acid capacity in India and Switzerland while exiting industrial-grade tiers where Chinese overcapacity erodes returns. Threat substitution from continuous flow reactor technology demands R&D partnerships with pharmaceutical formulators seeking solvent waste reduction. For New Entrants and Emerging Players: Digital-channel qualification platforms offer low-friction entry into electronic chemicals specifications where Vertellus Holdings LLC competes on purity rather than volume. White-space targets include high-purity picolines for lithium-ion battery electrolyte additives and semiconductor etching applications. The most penetrable segment is CDSCO-aligned Indian pharmaceutical API export channels, where domestic manufacturers lack batch-level nitrosamine testing infrastructure. Go-to-market positioning should emphasize continuous vapor-phase cyclization technology partnerships with Basel contract manufacturers. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap Indian agrochemical-grade producers because CDSCO export qualification creates scalable platform value for regulated-market access. Long-term viability centers on backward integration into acetic acid derivatives and analytical capability buildout for EMA compliance. Acquisition target archetype: Indian chemical manufacturers with existing paraquat intermediate relationships and underinvested nitrosamine testing infrastructure. The inflection signal to watch is EPA registration holder consolidation from dozens to single-digit approved vendor panels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Jubilant Ingrevia's captive pipeline compresses cost structures for agrochemical-grade output. |
| Continuous Flow Reactor Adoption | Swiss pharmaceutical manufacturers adopt flow chemistry to reduce solvent waste and improve nitrosamine control. |
| EMA Nitrosamine Testing Investment | Batch-level analytical capability separates qualified suppliers from exiting merchant traders in Europe. |
| CDSCO Export Qualification Pathway | Domestic Indian manufacturers leverage API guidelines to access regulated pharmaceutical contracts. |
| Long-term Supply Agreement Lock-in | Bayer and BASF procurement teams demand three-year contracts with audit rights and fixed purity specifications. |
Research Methodology
Direct dialogue with plant managers at integrated pyridine manufacturers, procurement leads at German agrochemical formulators, distribution channel partners in Indian chemical belts, and technical R&D directors specializing in vapor-phase cyclization grounded this analysis. Secondary validation drew from ECHA substance authorization databases, CDSCO API filing records, SEC 10-K disclosures from listed chemical producers, and customs trade data tracking pyridine derivative flows. Bottom-up capacity estimates and top-down demand triangulation from end-use consumption models were reconciled to ensure consistency.
Segmented projections across purity grades, application verticals, and regional production hubs were generated through the analysis window. The modeling framework incorporated pharmaceutical API contract pricing trajectories, agrochemical intermediate volume cycles, and regulatory qualification timeline assumptions. CAGRs were derived from compound growth pathing across these segmented demand drivers. Industry-specific inputs included EMA nitrosamine testing adoption curves and EPA registration holder vendor consolidation patterns.
Feedstock price volatility, regulatory timeline slippage, and analytical chemist labor scarcity are the dominant revision risks that could compress or extend projected growth trajectories. Forecasts reflect documented assumptions about REACH enforcement intensity and CDSCO alignment progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Bromobenzene Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Dimethyl Carbonate Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Organocatalyst Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
Nonylphenol Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Phenol Market
Organic Chemicals
Para-Tert-Octylphenol (POTP) Market