
 High Purity Metal Organics Market | 2026-2036
High Purity Metal Organics Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Metal Organics Market Outlook
The EU Green Deal is decoupling high purity metal organics procurement from legacy supply chains by embedding carbon footprint thresholds into precursor qualification. Albemarle Corporation leverages its bromine-derived vertical integration to secure feedstock positions for gallium and indium compounds. Merck KGaA sustains European supply continuity through its Gelest acquisition, while Sumitomo Chemical anchors Asia-Pacific demand with localized production serving Japanese and Korean semiconductor fabs.
High purity metal organics are organometallic compounds synthesized to 99.9999% purity or higher, typically via fractional distillation and sublimation under inert atmosphere, serving as essential precursors for atomic layer deposition and metal-organic chemical vapor deposition in semiconductor fabrication. Gallium organics dominate revenue among product types due to irreplaceable roles in GaN power electronics and RF devices, while indium organics represent the fastest-growing category driven by InP photonics and micro-LED display pivots. Semiconductor applications command the largest margin pools, though photovoltaics applications absorb significant volume through perovskite and CIGS cell architectures.
REACH in Europe, China's GB standards under SAMR oversight, and the US EPA toxic substance reporting framework collectively elevate analytical certification burdens and restrict unqualified market entrants. Korea's MFDS and Japan's METI coordinate regional alignment on precursor impurity thresholds, creating transnational compliance friction for non-integrated distributors. Stakeholders must monitor regulatory divergence between EU chemical safety expansion and China's domestic standard acceleration to anticipate qualification cost shifts and supply exclusion risks.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are consolidating precursor procurement around six-nines purity specifications, compressing supplier qualification timelines while fragmenting feedstock access for second-tier compounders.
Growth Catalysts
- GaN-on-SiC power electronics:Electric vehicle inverters and 5G base stations consume trimethylgallium at volumes that justify dedicated precursor synthesis lines.
- REACH compliance expansion:ECHA substance evaluation protocols are accelerating substitution of legacy halogenated precursors with metal-organic alternatives in European deposition tools.
- Micro-LED display pivots:Samsung Display and AUO are qualifying indium organics for blue emitter layers, pulling capacity from traditional phosphor applications.
Market Restraints
- Gallium metal supply concentration:Chinese smelters control approximately 90% of primary gallium feedstock, exposing non-integrated precursor manufacturers to export license volatility.
- Fractional distillation capex intensity:Six-nines purification requires stainless steel columns with tantalum linings, pushing unit capital costs beyond 40 million dollars per train.
- Perovskite solar substitution threat:Tin-based organometallics are displacing indium precursors in academic research lines, though commercial CIGS fabs remain committed.
Strategic Opportunities
- Indian semiconductor subsidy corridors:Gujarat and Tamil Nadu fabs under the PLI scheme will require localized precursor blending facilities to avoid import duty penalties.
- Dual carbon goals in China:SAMR carbon intensity benchmarks are creating preference for metal-organic precursors over halogenated alternatives in domestic LED epitaxy.
- Atomic layer deposition tool convergence:Lam Research and ASM International are qualifying universal bubbler designs that reduce precursor changeover downtime by half.
Industry Challenges
- Organometallic chemist scarcity:Synthesis of pyrophoric gallium and indium compounds requires PhD-level expertise in air-free techniques that university programs are not replenishing.
- Multi-jurisdiction certification timelines:Simultaneous qualification under REACH, China's GB standards, and Korea's MFDS extends product launch cycles to 18-24 months.
- Legacy MOCVD tool incompatibility:Older Aixtron and Veeco systems lack precision mass flow controllers for low-vapor-pressure precursors, forcing fab retrofit investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Metal Organics Market |
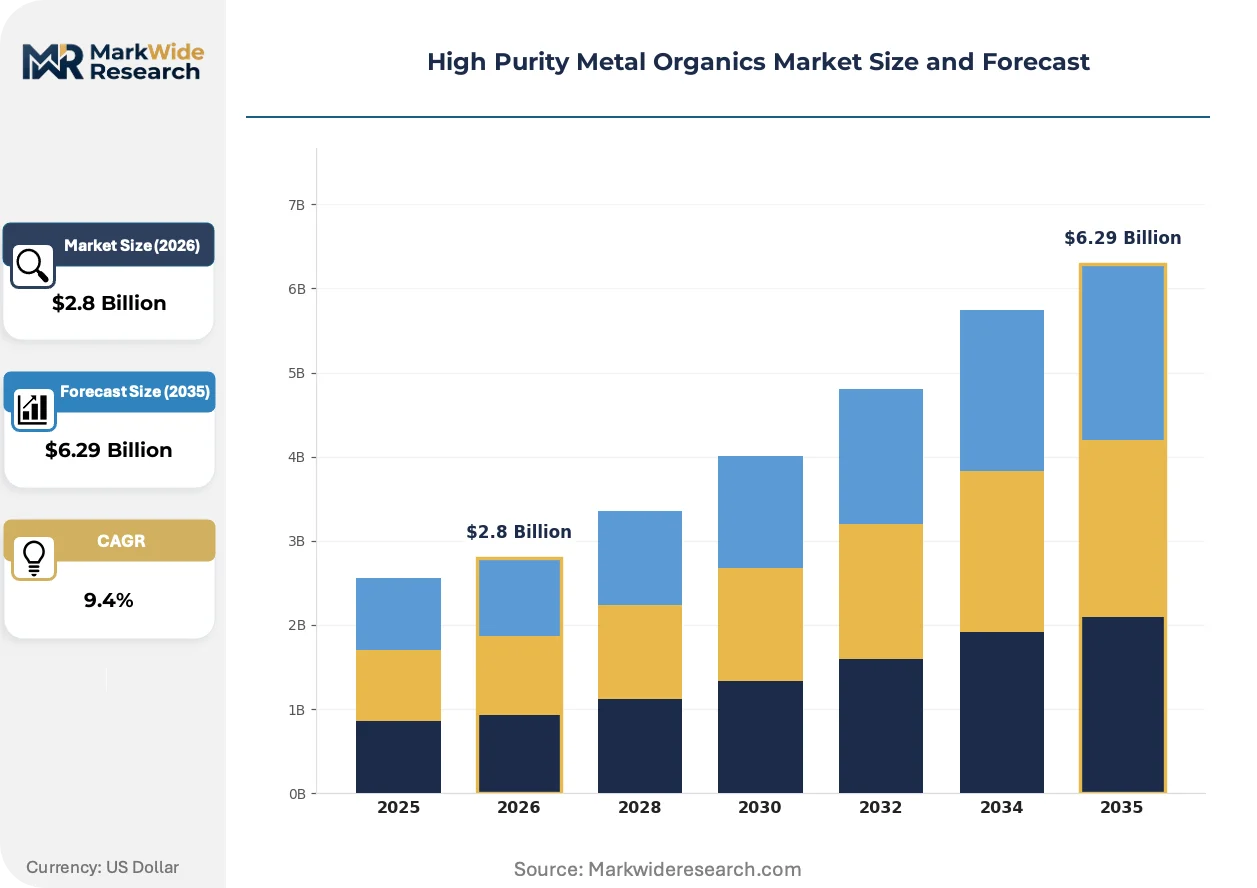
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
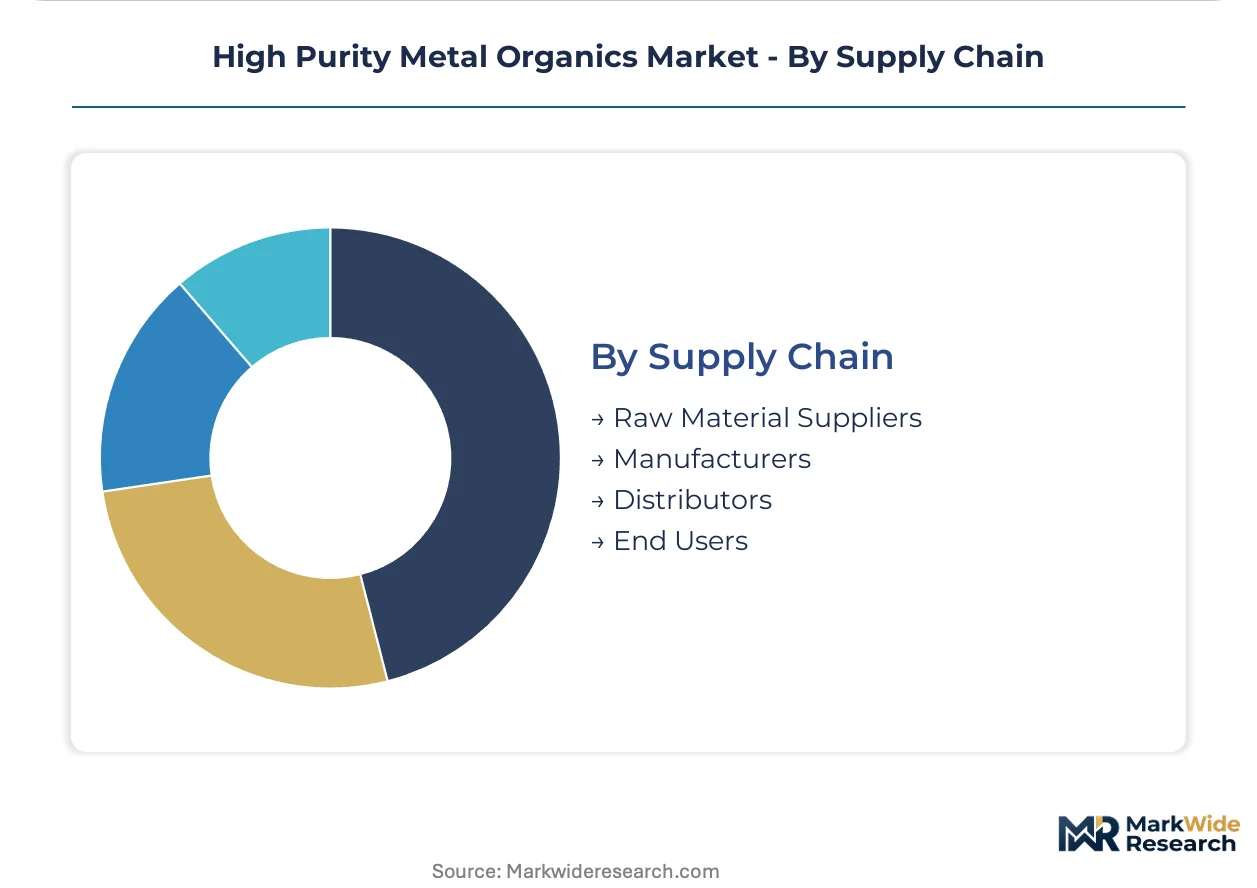
| Segmentation | Product Type: Gallium Organics, Indium Organics, Tin Organics, Zinc Organics Application: Semiconductors, Photovoltaics, Catalysts, Coatings End User: Electronics, Automotive Components, Renewable Energy, Chemicals Supply Chain: Raw Material Suppliers, Manufacturers, Distributors, End Users |
| Companies Covered | Nouryon, Albemarle Corporation, Umicore, Merck KGaA, Sumitomo Chemical, American Elements, BASF SE, Azelis, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Metal Organics Market Strategic Shifts
Deposition chemistry is fragmenting into application-specific precursor families as node shrinkage and compound semiconductor heterostructures impose divergent thermal stability and vapor pressure requirements.
Continuous flow microreactor synthesis is decentralizing trimethylindium production from centralized batch plants to point-of-use generation modules. Taiwan Semiconductor Manufacturing Company is piloting on-site synthesis pods at its Tainan fab complex, eliminating precursor transport hazards while compressing inventory carrying costs. This architecture is decentralizing supply chain risk from maritime chokepoints to captive island production.
EU Green Deal carbon border adjustments are embedding Scope 3 emission thresholds into precursor qualification protocols. European compound semiconductor foundries now require supplier disclosure of gallium ore smelting energy intensity, with penalties for coal-powered reduction. German and French IDMs are prioritizing precursors synthesized with hydroelectric-powered feedstock, reshaping procurement scoring matrices.
Integrated device manufacturers are consolidating purchase orders under multi-year take-or-pay contracts that shift volume risk onto precursor suppliers. Samsung and SK Hynix are negotiating five-year gallium precursor agreements with fixed minimum offtake, displacing spot market transactions that previously balanced supply. This concentration is most visible in Korean memory and logic fabs, where procurement teams now demand dedicated synthesis lines as a qualification prerequisite.
High Purity Metal Organics Market Segmentation
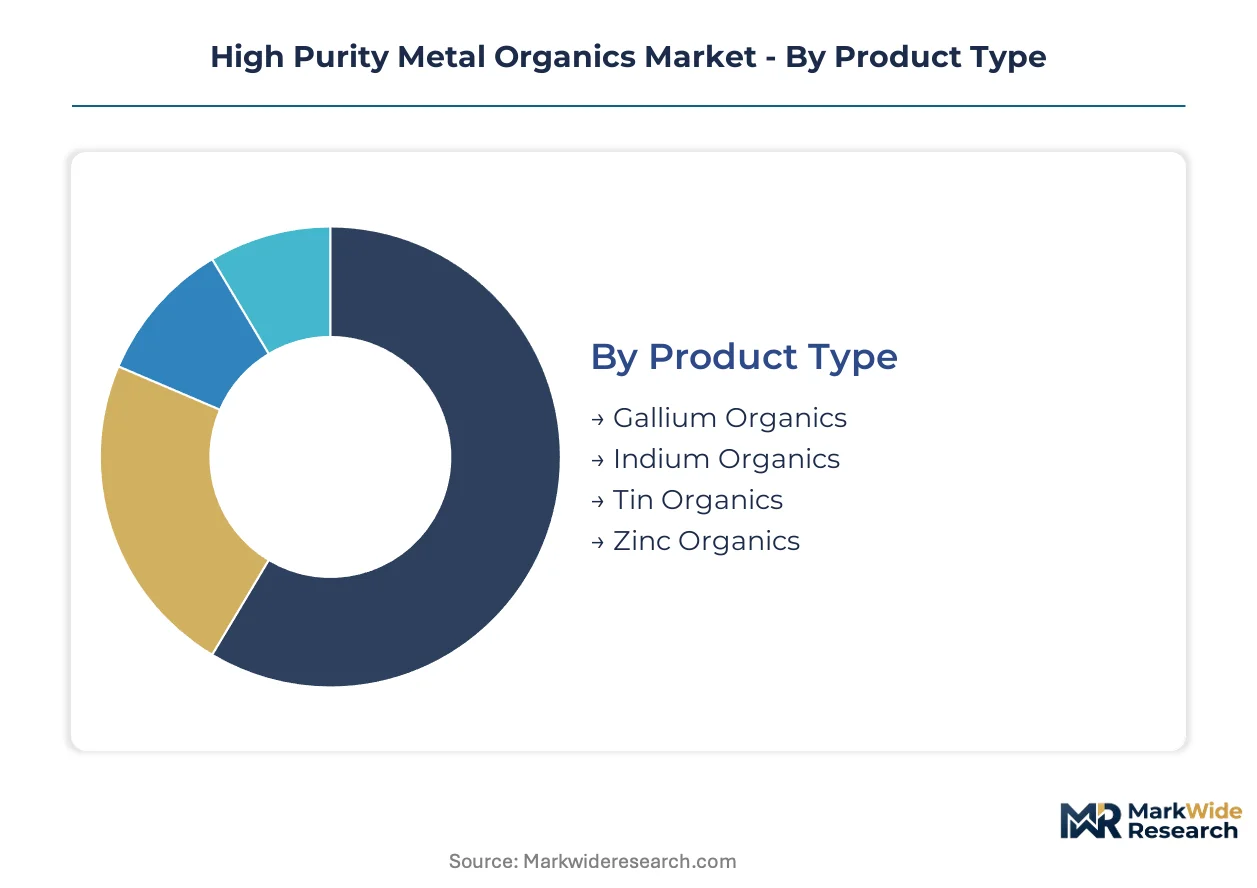
Precursor specification varies dramatically across deposition chemistries and end-use thermal budgets, forcing suppliers to maintain parallel synthesis trains with distinct purity protocols. Semiconductor foundries impose six-nines specifications that command 3-4x price premiums over photovoltaic-grade material, fragmenting production economics and customer qualification pathways.
Product Type:
Standardization dominates at the feedstock level—gallium and indium metal sources converge on common purity grades—while customization intensifies at the organometallic synthesis stage where ligand selection determines vapor pressure and decomposition kinetics.
- Gallium Organics:Trimethylgallium and triethylgallium synthesized via Grignard routes achieve six-nines purity through fractional distillation under argon atmosphere. Taiwan Semiconductor Manufacturing Company and Samsung Foundry consume volumes sufficient to justify dedicated synthesis lines with captive gallium feedstock hedging against Chinese export license volatility.
- Indium Organics:Trimethylindium serves atomic layer deposition of InGaN quantum wells and InP heterojunctions with thermal stability windows narrower than gallium analogs. Samsung Display and AUO are pulling capacity toward micro-LED blue emitter qualification, tightening spot availability for traditional phosphor applications.
- Tin Organics:Tetramethyltin and dibutyltin precursors enable perovskite solar cell architectures and tin oxide transparent conductors, though pyrophoric handling limits supplier participation.
- Zinc Organics:Diethylzinc dominates atomic layer deposition of ZnO buffer layers in CIGS photovoltaics and thin-film transistor backplanes.
Leading the category by volume: Gallium Organics. Growing fastest: Indium Organics.
Application:
Cost tier stratification separates deposition processes by thermal budget and layer thickness precision, with semiconductor applications absorbing capital-intensive six-nines capacity while photovoltaics tolerates five-nines specifications at volume discounts.
- Semiconductors:Atomic layer deposition and metal-organic chemical vapor deposition for GaN power devices, RF amplifiers, and logic node interconnects demand sub-ppb metallic impurity thresholds. Korean and Taiwanese foundries specify lot-to-lot consistency metrics that disqualify second-tier compounders lacking statistical process control infrastructure.
- Photovoltaics:Perovskite and CIGS cell manufacturing consumes organometallic precursors at wafer-area throughputs 10-100x semiconductor rates, prioritizing cost-per-watt over ultimate purity.
- Catalysts:Polymerization and fine chemical synthesis employ lower-purity grades with tolerance for trace oxygen and moisture.
- Coatings:Transparent conductive oxide and barrier layer applications utilize vapor-phase deposition with intermediate specification requirements.
Dominating margin capture: Semiconductors. Expanding most quickly: Photovoltaics.
End User:
Customer type determines contract structure, with integrated device manufacturers negotiating multi-year take-or-pay agreements while merchant chemical buyers transact on spot markets with 30-60 day pricing exposure.
- Electronics:Logic and memory fabs in Taiwan, South Korea, and Japan consolidate procurement under consolidated supplier panels with dedicated synthesis line requirements. REACH compliance and Korea's MFDS precursor registration create transnational qualification friction that favors incumbent relationships.
- Automotive Components:Electric vehicle inverters and onboard charging systems utilizing GaN power electronics are emerging as volume consumers with automotive-grade reliability specifications distinct from consumer electronics.
- Renewable Energy:Solar cell manufacturers prioritize precursor cost-per-watt and supply security over ultimate purity, with Chinese CIGS fabs driving regional procurement concentration.
- Chemicals:Fine chemical and pharmaceutical intermediates represent fragmented demand with heterogeneous specification requirements.
Commanding procurement concentration: Electronics. Gaining share fastest: Automotive Components.
Supply Chain:
Geographic concentration of primary metal smelting—particularly Chinese gallium refining—creates upstream bottlenecks that downstream synthesis stages cannot bypass, embedding feedstock risk into all channel configurations.
- Raw Material Suppliers:Chinese smelters control primary gallium feedstock; German and Japanese traders maintain strategic inventories for qualified precursor manufacturers. EU Green Deal carbon border adjustments are embedding Scope 3 emission thresholds into supplier qualification, favoring hydroelectric-powered reduction routes.
- Manufacturers:Albemarle Corporation, Merck KGaA, and Sumitomo Chemical operate integrated synthesis networks with captive bromine or metal positions. Fractional distillation capex intensity—40 million dollars per six-nines train—limits new entrant participation.
- Distributors:Specialized chemical distributors handle lower-volume, multi-precursor orders for research institutions and pilot lines, though semiconductor fabs prefer direct manufacturer relationships.
- End Users:Taiwan Semiconductor Manufacturing Company is piloting on-site synthesis pods at its Tainan fab complex, eliminating transport hazards while compressing inventory carrying costs.
Controlling value capture: Manufacturers. Restructuring most rapidly: End Users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary gallium smelting concentrates in Chinese refineries while precursor consumption clusters in East Asian semiconductor fabs, creating a trans-Pacific supply-demand asymmetry that shapes procurement risk profiles.
China
Chinese smelters under SAMR oversight control roughly 90% of primary gallium feedstock, embedding export license volatility into global precursor economics. The dual carbon goals framework is accelerating domestic substitution of halogenated precursors with metal-organic alternatives in LED epitaxy. Yangtze River Delta fabs in Jiangsu and Shanghai are scaling captive consumption of trimethylgallium for GaN power device production.
Taiwan
TSMC and United Microelectronics Corporation are consolidating six-nines precursor procurement under multi-year take-or-pay contracts with dedicated synthesis line requirements. Taiwan's Industrial Development Bureau coordinates with Korea's MFDS on precursor impurity threshold alignment to reduce transnational qualification friction. The Tainan Science Park is piloting on-site trimethylindium synthesis pods that eliminate maritime transport hazards.
South Korea
Samsung Foundry and SK Hynix are negotiating five-year gallium precursor agreements with fixed minimum offtake, displacing spot market transactions. Korea's MFDS precursor registration protocols create compliance barriers favoring incumbent supplier relationships. The Pyeongtaek-Dongtan cluster anchors memory and logic fab demand with localized blending facilities serving HBM3 and advanced node production.
United States
EPA toxic substance reporting frameworks elevate analytical certification burdens for precursor imports, restricting unqualified market entrants. The CHIPS Act subsidy corridors are attracting compound semiconductor foundries to Arizona and Texas that will require qualified precursor supply chains. Intel's Fab 52 in Chandler and Samsung's Taylor expansion are driving regional procurement concentration with automotive-grade reliability specifications.
Germany
ECHA REACH substance evaluation protocols are accelerating substitution of legacy halogenated precursors with metal-organic alternatives in European deposition tools. EU Green Deal carbon border adjustments embed Scope 3 emission thresholds into precursor qualification, favoring hydroelectric-powered feedstock. Bavarian and Saxon compound semiconductor foundries are prioritizing precursors with disclosed gallium ore smelting energy intensity metrics.
High Purity Metal Organics Market Competitive Environment
The competitive structure tilts toward integrated chemical conglomerates with captive feedstock positions and specialized organometallic synthesis capabilities. Three to five players control the majority of six-nines purification capacity, while regional specialists occupy photovoltaic and research-grade tiers. The dominant archetypes comprise bromine-integrated majors, European diversified chemicals groups, and Asia-Pacific electronics-focused suppliers. Competitive moves concentrate on backward integration into primary metal refining and multi-jurisdiction qualification acceleration.
Among bromine-integrated majors, Albemarle Corporation leverages its upstream chemical position to secure gallium and indium compound feedstock access. Merck KGaA, through its Gelest acquisition, sustains European supply continuity with localized synthesis networks. Sumitomo Chemical anchors Asia-Pacific demand through Japanese and Korean fab relationships with regional production assets. These three occupy positions that exemplify the feedstock-captive, geography-anchored archetype dominating premium-tier precursor supply.
| Leading Market Players |
|---|
| Nouryon |
| Albemarle Corporation |
| Umicore |
| Merck KGaA |
| Sumitomo Chemical |
| American Elements |
| BASF SE |
| Azelis |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange gallium price volatility cascades through precursor synthesis economics, compressing margins for non-integrated compounders while amplifying pricing power for feedstock-captive majors serving semiconductor foundries under multi-year contracts.
Pricing Analysis
Yield-guaranteed pricing anchors six-nines trimethylgallium contracts, with foundries paying premiums tied to wafer throughput guarantees rather than raw material input costs. Price differentiation rests on certification grade—REACH-registered precursors command substantial premiums over research-grade alternatives—and volume scale, with Taiwanese IDMs securing dedicated synthesis lines through minimum offtake commitments. Cost compression in photovoltaic-grade material is intensifying as Chinese CIGS fabs drive spot market competition. Merchant chemical buyers exhibit highest price sensitivity, while Korean memory fabs under take-or-pay structures show lowest elasticity.
Supply Chain Analysis
REACH, China's GB standards, and Korea's MFDS registration protocols function as qualification gates that fragment supplier participation and extend product launch cycles. Primary gallium refining concentrates in China, with German and Japanese traders maintaining strategic buffer inventories for qualified manufacturers. Synthesis draws from high-purity metal feedstock, specialized ligand chemistries, and tantalum-lined distillation infrastructure. Single-source vulnerability pervades the Chinese gallium smelting base, where export license volatility threatens non-integrated compounders. Distribution runs through direct manufacturer relationships for semiconductor fabs, with specialized distributors serving research and pilot-scale demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
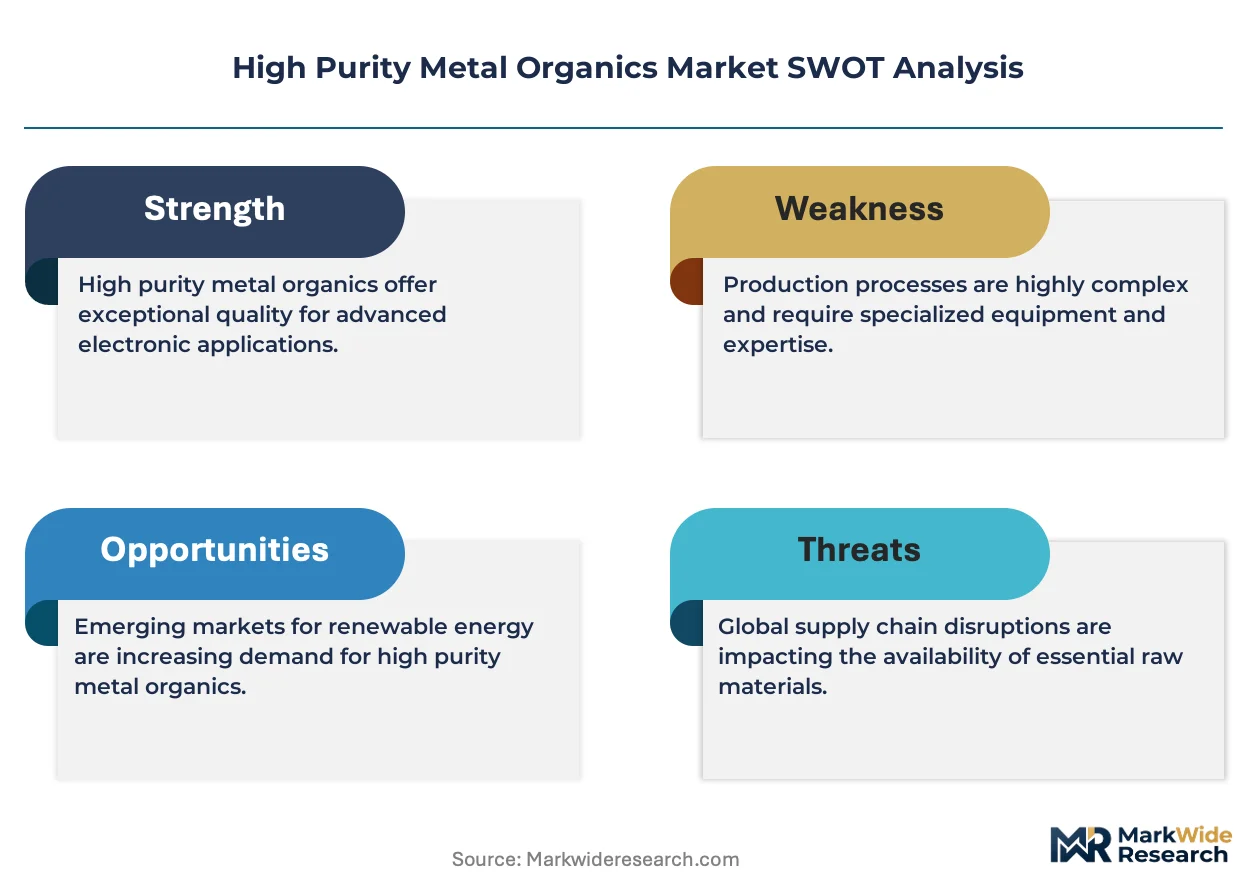
This market functions as a cost-of-compliance story where ECHA REACH substance evaluation protocols erect barrier-to-entry moats favoring incumbent players with established multi-jurisdiction certification infrastructure.
For Market Incumbents: Acquire captive gallium feedstock positions to hedge against Chinese export license volatility and secure synthesis cost advantages. Expand six-nines fractional distillation capacity in Taiwan and South Korea to meet foundry demands for dedicated synthesis lines. Tin-based perovskite research lines pose substitution threats to indium organics in photovoltaics, requiring monitoring of academic-commercial transition timelines. For New Entrants and Emerging Players: Continuous flow microreactor synthesis technology offers entry pathways through point-of-use generation modules that bypass centralized batch plant capital barriers. Target Indian semiconductor subsidy corridors in Gujarat and Tamil Nadu where localized precursor blending facilities face import duty penalties and incumbent presence remains thin. Pursue joint development agreements with emerging compound semiconductor foundries seeking supply chain diversification. For Investors and Strategic Acquirers: Distressed-cycle entries favor bromine-integrated chemical majors with existing organometallic synthesis capabilities and established foundry relationships in East Asia. Long-term viability hinges on carbon intensity disclosure capabilities aligned with EU Green Deal Scope 3 emission thresholds. Monitor SAMR carbon benchmark acceleration in China as inflection indicator for domestic precursor preference shifts toward metal-organic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Gallium Refining | Secures feedstock positions against Chinese export license volatility for major compounders. |
| Multi-Jurisdiction Qualification Acceleration | Compresses 18-24 month REACH, GB standards, and MFDS timelines to capture foundry procurement windows. |
| On-Site Synthesis Pod Deployment | Eliminates maritime transport hazards while reducing inventory carrying costs for TSMC-class fabs. |
| Hydroelectric-Powered Feedstock Sourcing | Meets EU Green Deal carbon border adjustments for Bavarian and Saxon compound semiconductor foundries. |
| PhD-Level Organometallic Chemist Recruitment | Addresses air-free synthesis expertise scarcity that university programs are not replenishing. |
Study Parameters
Trade flow databases, ECHA substance evaluation registers, and SEC 10-K filings formed the secondary backbone, cross-referenced with primary interviews involving precursor synthesis plant managers, procurement leads at Taiwanese and Korean foundries, distribution channel partners, and technical R&D directors at organometallic compounders. Bottom-up triangulation across deposition tool utilization rates and top-down validation through customs export data established volume estimates.
Historical trendline analysis of gallium precursor consumption patterns across semiconductor fabrication capacity expansions informed projection modeling. Segmentation dimensions encompassed product type, application thermal budget, end-user contract structure, and regional regulatory cluster. CAGRs were derived through regression analysis of foundry capex cycles and precursor intensity per wafer layer. Forecast inputs incorporated GaN-on-SiC power electronics adoption curves and micro-LED display pivot timelines.
Several conditions sit outside the modeled scope, including perovskite solar commercialization trajectories and potential tin-organic displacement of indium precursors. Forecasts reflect assumptions regarding Chinese gallium export policy continuity and REACH substance evaluation expansion timelines. A model refresh is warranted upon material change in EU carbon border adjustment implementation or SAMR dual carbon goal acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Soy Chemicals Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Trimethylcyclohexanone Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
1,3-Dichloroacetone Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Bromobenzene Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Dioctyl Phthalate Market