
 Organic Hydrosols Market | 2026-2036
Organic Hydrosols Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Hydrosols Market Analytics
Clean beauty formulators is recalibrating raw material sourcing toward certified organic inputs. Biolandes SAS leverages vertical integration across French lavender supply chains. Alteya Organics anchors Bulgarian rose damascena distillation at scale. Florihana Distillerie differentiates through CO2-neutral certification and small-batch artisan positioning.
Organic hydrosols constitute aqueous co-products of steam distillation, containing trace essential oil fractions (0.02–0.05%) and water-soluble plant metabolites, functioning primarily as natural toners, antimicrobial bases, and flavor carriers in formulated goods. Floral waters dominate volume throughput due to established rose and lavender distillation infrastructure, while citrus hydrosols represent the fastest-expanding category as cold-pressed peel alternatives gain traction in natural fragrance compounding. Margin pools concentrate in pharmaceutical-grade certifications where USP and EP monograph compliance commands price premiums over cosmetic-grade equivalents.
USDA Organic certification and EU REACH registration shape raw material eligibility and cross-border market access for hydrosol exporters. FDA oversight of cosmetic ingredient safety and ECHA substance evaluation drive testing expenditures upward for suppliers serving dual-market portfolios. Stakeholders must monitor evolving organic equivalence agreements between regulatory jurisdictions to preserve supply chain continuity and certification validity.
Market Dynamics
EU REACH substance evaluation is tightening traceability mandates for hydrosol exporters, forcing distillation networks to consolidate certification documentation and fragmenting small-batch producers from pharmaceutical-grade supply chains.
Growth Catalysts
- USDA Organic certification:Cosmetic formulators in the United States are mandating certified organic hydrosols for clean beauty portfolios, pulling volume through accredited distillation cooperatives.
- Steam distillation infrastructure:Bulgaria and France maintain captive rose and lavender processing capacity that locks in raw material security for fragrance compounders.
- Cold-pressed peel alternatives:Citrus hydrosols are capturing share in natural fragrance compounding as synthetic solvent restrictions harden under EU Green Deal implementation timelines.
Market Restraints
- Input cost volatility:Organic botanical feedstock prices fluctuate with climate stress on lavender and rose harvests in Provence and Kazanlak Valley.
- Supply concentration risk:Pharmaceutical-grade hydrosol output clusters in Bulgarian and French distillation zones, creating single-source vulnerability for USP and EP monograph-compliant material.
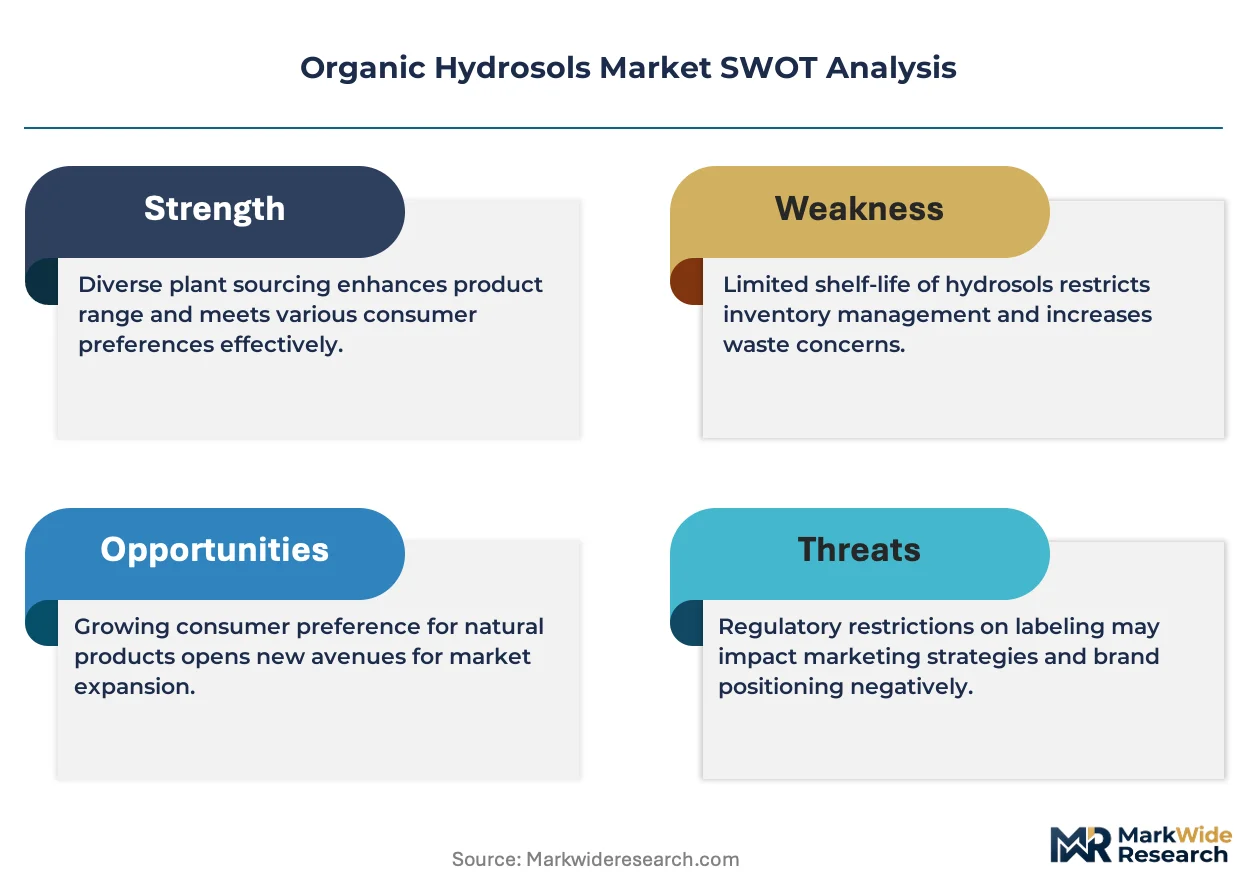
- Substitution threat:Synthetic antimicrobial bases and petroleum-derived emollients retain cost advantages in mass-market personal care formulations.
Strategic Opportunities
- Underpenetrated United States market:Domestic hydrosol distillation remains underdeveloped relative to aromatherapy consumption, creating white space for regional production investment.
- Pharmaceutical-grade certification:USP and EP compliance commands price premiums that widen margin pools for laboratory-validated suppliers.
- Direct-to-formulator channels:Artisan distilleries are bypassing traditional distributors through B2B e-commerce platforms serving indie cosmetic brands.
Industry Challenges
- Certification timeline compression:USDA Organic and EU REACH parallel compliance requires 18-24 month documentation cycles that strain working capital for mid-scale distillers.
- Skilled distillation technician scarcity:Traditional steam distillation expertise is concentrating in aging workforce pools across Bulgarian rose-growing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Hydrosols Market |
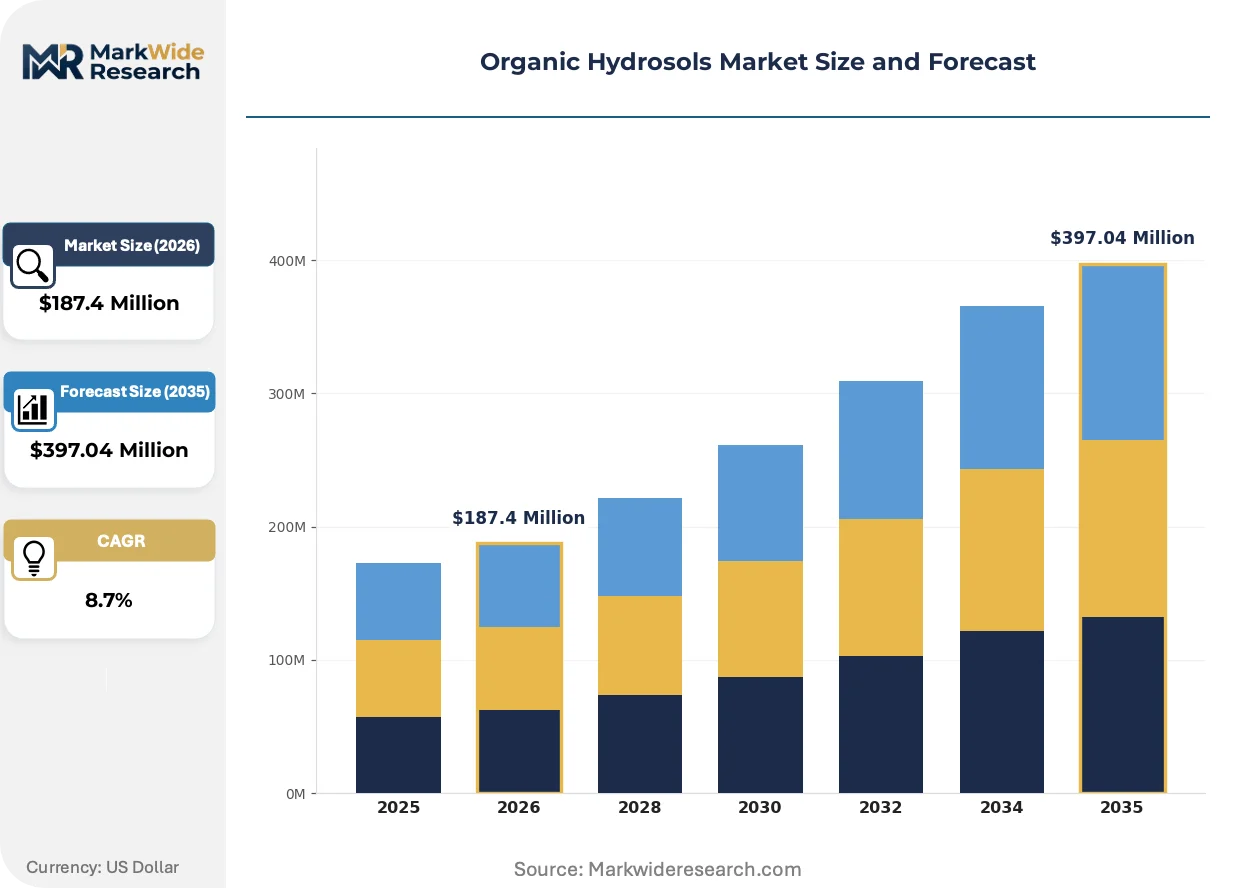
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floral Waters, Herbal Extracts, Citrus Hydrosols, Fruit Hydrosols Application: Cosmetics, Food & Beverage, Aromatherapy, Pharmaceuticals End User: Manufacturers, Retailers, Wellness Centers, Private Consumers Distribution Channel: Online Stores, Health Shops, Supermarkets, Specialty Stores |
| Companies Covered | Biolandes SAS, Alteya Organics, Floracopeia, Inc., Hydrosol GmbH & Co. KG, Plant Therapy Essential Oils, The Mountain Rose Herbs, Florihana Distillerie, Aromatics International LLC, Eden Botanicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Hydrosols Market Evolving Landscape
Clean beauty certification standards are compressing formulation timelines and forcing hydrosol suppliers to pre-validate organic chain-of-custody documentation before contract negotiation.
Supercritical CO2 extraction is expanding into hydrosol co-product recovery, capturing water-soluble metabolites at lower thermal degradation rates than conventional steam distillation. Pharmaceutical compounders in Switzerland and Germany are adopting this technology for heat-sensitive botanical matrices. The process is expanding into premium cosmetic-grade supply tiers where oxidative stability commands specification premiums.
EU REACH substance evaluation is accelerating data requirements for botanical extracts imported into European cosmetic supply chains. ECHA's 2024-2025 rolling action plan targets additional floral water constituents for toxicological profiling. French and Bulgarian exporters are responding by consolidating testing laboratories under shared compliance consortia to distribute analytical cost burdens.
Formulator procurement patterns are fragmenting toward multi-origin sourcing strategies that dilute single-region climate risk. Indie cosmetic brands in California and New York are building supplier rosters spanning French lavender, Bulgarian rose, and domestic citrus hydrosols. This rotation is most visible in direct-to-consumer skincare lines where origin storytelling substitutes for mass-market advertising spend.
Organic Hydrosols Market Segmentation
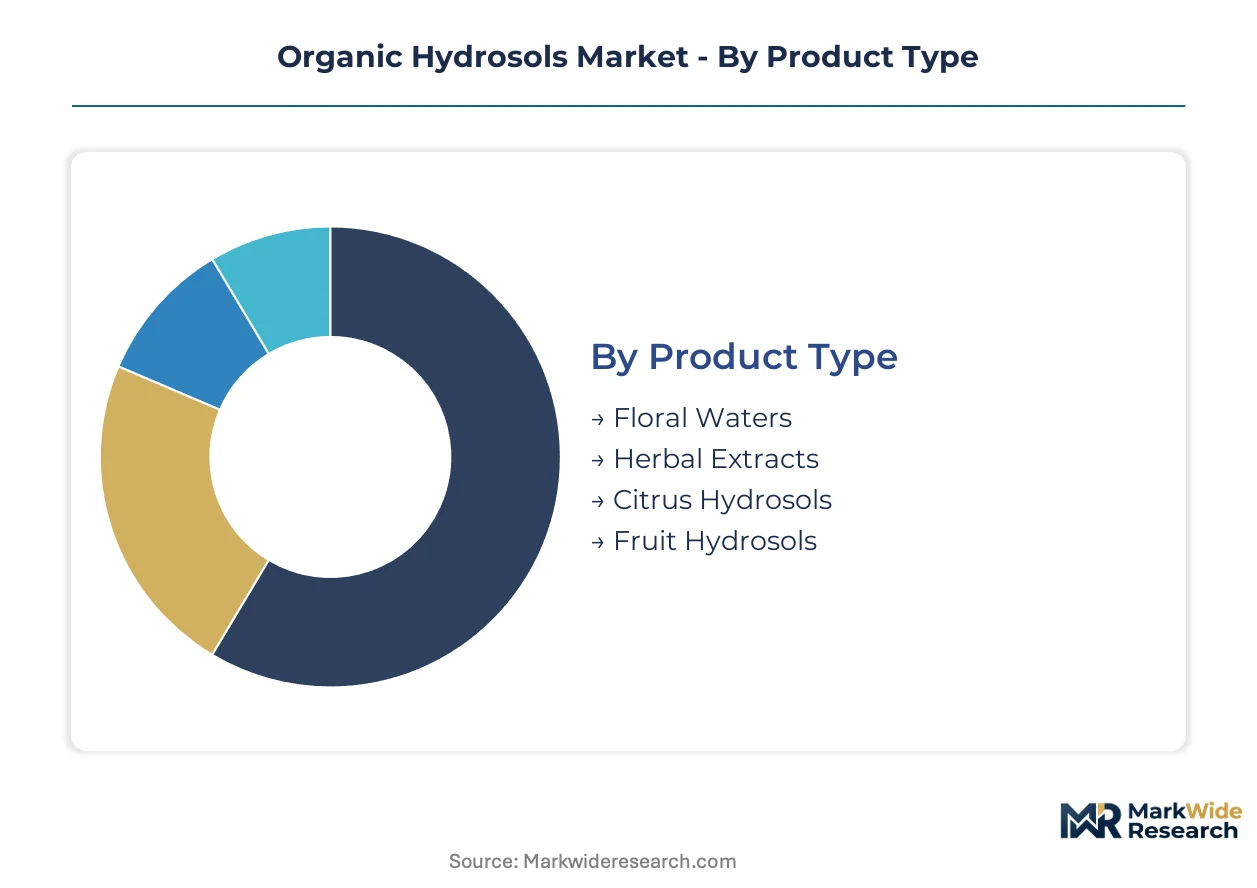
Segmentation in organic hydrosols reflects divergent purity standards, regulatory thresholds, and supply chain configurations across end-use verticals. Distillers must align certification tiers—cosmetic-grade, food-grade, pharmaceutical-grade—with specific buyer procurement protocols.
Product Type:
Steam distillation parameters and botanical matrix thermal sensitivity define product category economics.
- Floral Waters:Aqueous co-products of rose damascena and lavender angustifolia steam distillation containing 0.02–0.05% essential oil fractions. Demand clusters in French and Bulgarian distillation zones where captive processing infrastructure locks in raw material security for fragrance compounders.
- Herbal Extracts:Distillates from rosemary, chamomile, and witch hazel biomass, valued for water-soluble polyphenol content. Wellness centers in Germany and Switzerland specify these for therapeutic topical applications where anti-inflammatory metabolite profiles drive formulation decisions.
- Citrus Hydrosols:Cold-pressed peel alternatives capturing volatile terpene fractions without thermal degradation. Natural fragrance compounders specify these for EU Green Deal-compliant solvent-free formulations.
- Fruit Hydrosols:Distillates from apple, pear, and berry biomass, primarily serving food-grade flavor carriers and natural preservative bases.
Mature deployment sits with Floral Waters. Newer deployment is concentrated in Citrus Hydrosols.
Application:
Regulatory jurisdiction determines permissible botanical matrices and residue limits for each use case.
- Cosmetics:USDA Organic-certified hydrosols function as natural toners, antimicrobial bases, and preservative-free formulation vehicles. Clean beauty brands in California mandate certified organic inputs, pulling volume through accredited distillation cooperatives.
- Food & Beverage:Flavor carriers and natural antimicrobial agents in beverage and confectionery applications. FDA GRAS status and EFSA novel food evaluations gate market access for botanical water extracts.
- Aromatherapy:Therapeutic-grade hydrosols for inhalation and topical wellness protocols. Swiss and German pharmaceutical compounders specify heat-sensitive matrices processed via supercritical CO2 co-product recovery.
- Pharmaceuticals:USP and EP monograph-compliant hydrosols command price premiums for laboratory-validated suppliers serving sterile formulation requirements.
Volume concentration rests with Cosmetics. Steepest expansion trajectory belongs to Pharmaceuticals.
End User:
Procurement scale and specification rigor fragment the buyer landscape across four operational models.
- Manufacturers:Cosmetic, food, and pharmaceutical formulators sourcing bulk volumes with chain-of-custody documentation requirements. These buyers consolidate supplier rosters to dilute single-region climate risk.
- Retailers:Health food chains and apothecaries stocking private-label and branded hydrosol SKUs for consumer self-selection.
- Wellness Centers:Spas and clinical aromatherapy practitioners specifying therapeutic-grade materials with batch-specific chromatographic profiles.
- Private Consumers:Direct purchasers via B2C e-commerce channels, primarily indie skincare enthusiasts in urban coastal markets.
Contract volume aggregates with Manufacturers. Direct-channel growth concentrates in Private Consumers.
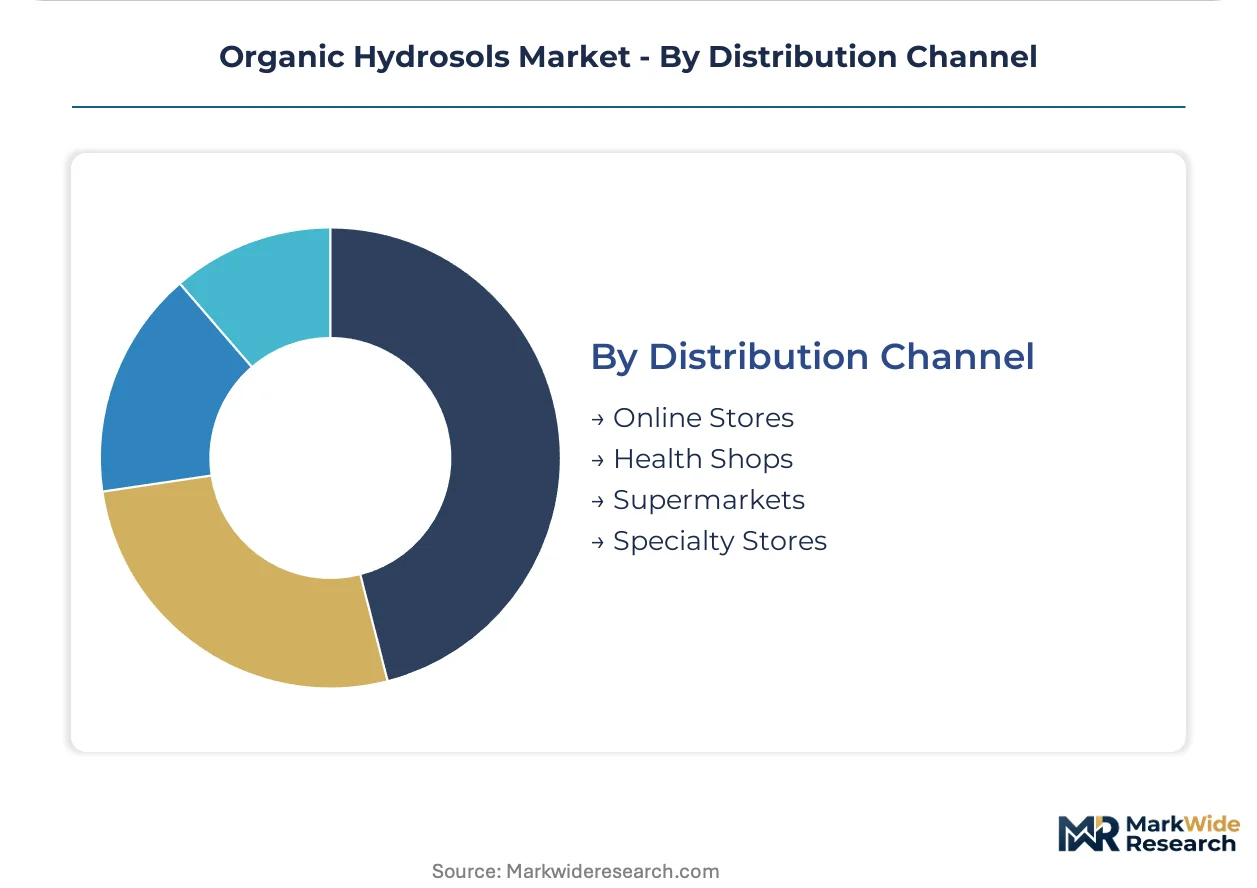
Distribution Channel:
Channel selection tracks buyer sophistication and certification verification requirements.
- Online Stores:B2B platforms serving indie cosmetic brands and B2C direct-to-consumer operations. Artisan distilleries bypass traditional distributors through these channels.
- Health Shops:Brick-and-mortar apothecaries and natural product retailers with trained staff for origin storytelling and usage guidance.
- Supermarkets:Mass-market retail placement for commodity-grade floral waters in conventional personal care aisles.
- Specialty Stores:Perfumeries and high-end beauty retailers curating small-batch artisan positioning with CO2-neutral certification claims.
Established penetration sits with Health Shops. Digital migration is accelerating fastest in Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
French tax incentives for organic agriculture concentrate distillation infrastructure in Provence-Alpes-Côte d'Azur. Bulgarian state subsidies for rose oil processing anchor pharmaceutical-grade capacity in Kazanlak Valley. USDA cost-share programs for organic certification pull investment toward California and Oregon processing cooperatives.
France
Grasse-based fragrance compounders mandate certified organic lavender hydrosol for European luxury skincare formulations. ANSM enforces cosmetic ingredient safety dossiers that extend documentation timelines for artisan distillers. Biolandes SAS operates captive distillation networks across Drôme and Vaucluse departments.
Bulgaria
Kazanlak Valley rose damascena harvests supply USP-grade hydrosol for Swiss pharmaceutical compounders. EU REACH substance evaluation forces consolidation of testing laboratories under shared compliance consortia. Alteya Organics anchors industrial-scale distillation capacity with backward integration into organic rose cultivation.
United States
California clean beauty brands specify USDA Organic hydrosol for preservative-free toner formulations. FDA cosmetic ingredient oversight drives testing expenditures upward for suppliers serving dual-market portfolios. Oregon and Washington distillation cooperatives expand cold-pressed citrus hydrosol output for natural fragrance applications.
Switzerland
Swissmedic pharmaceutical-grade requirements command price premiums for laboratory-validated hydrosol suppliers. Supercritical CO2 extraction technology penetrates premium cosmetic tiers for heat-sensitive botanical matrices. Basel and Geneva formulation houses specify batch-specific chromatographic profiles for sterile applications.
Germany
German wellness centers specify therapeutic-grade herbal hydrosols for topical anti-inflammatory protocols. ECHA's 2024-2025 rolling action plan targets additional floral water constituents for toxicological profiling. Bavarian and Baden-Württemberg natural product retailers expand private-label hydrosol SKUs through trained apothecary staff.
Organic Hydrosols Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade certification tiers, while mid-scale distillers occupy artisan positioning with CO2-neutral claims. The vendor base stratifies across three operational models: vertically integrated agricultural processors, laboratory-validated pharmaceutical suppliers, and direct-to-formulator e-commerce specialists. Strategic moves concentrate on backward integration into organic cultivation and shared compliance consortia for EU REACH documentation.
Among French and Bulgarian agricultural processors, Biolandes SAS and Alteya Organics exemplify captive supply chain control from cultivation through distillation. Florihana Distillerie occupies a position within the artisan tier, representing small-batch positioning with environmental certification claims. These three entities anchor the competitive structure through divergent scale and certification strategies.
| Leading Market Players |
|---|
| Biolandes SAS |
| Alteya Organics |
| Floracopeia, Inc. |
| Hydrosol GmbH & Co. KG |
| Plant Therapy Essential Oils |
| The Mountain Rose Herbs |
| Florihana Distillerie |
| Aromatics International LLC |
| Eden Botanicals |
| Others |
Value Network & Pricing Analysis
Traditional steam distillation expertise concentrates in aging workforce pools across Bulgarian rose-growing regions, compressing labor-cost differentials between artisan small-batch producers and industrial-scale pharmaceutical-grade suppliers into pricing-tier spreads that widen margin gaps across certification levels.
Pricing Analysis
Short lead-time premiums command substantial markups over spot inventory discounts in contract negotiations between fragrance compounders and distillation cooperatives. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and artisan small-batch levels separates USP and EP monograph-compliant suppliers from standard cosmetic certification holders and CO2-neutral positioned craft distilleries. Price differentiation hinges on certification documentation burden and batch-specific chromatographic validation, with pharmaceutical-grade tiers capturing widest spreads. Cost compression in commodity floral waters is intensifying because synthetic antimicrobial substitutes retain cost advantages in mass-market personal care. Indie cosmetic brands in California exhibit highest price sensitivity; Swiss pharmaceutical compounders demonstrate least.
Supply Chain Analysis
Dual-sourcing qualification mandates from FDA- and ECHA-regulated formulators fragment procurement patterns toward multi-origin supplier rosters spanning French lavender, Bulgarian rose, and domestic citrus hydrosols. Geographic supply concentration anchors in France, Bulgaria, and the United States where distillation infrastructure and aromatherapy consumption clusters intersect. Raw material dependencies rest on organic lavender and rose damascena botanical feedstocks, cold-pressed citrus peel biomass, and certified organic cultivation acreage. Single-source vulnerability concentrates in Kazanlak Valley pharmaceutical-grade output. Distribution runs through B2B e-commerce platforms serving indie cosmetic brands, health shop apothecaries, and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into organic cultivation and captive distillation capacity anchors competitive positioning as players race to lock in raw material security and certification control.
For Market Incumbents: Hedge climate-driven harvest volatility by diversifying cultivation geography beyond Provence and Kazanlak Valley. Consolidate testing laboratories under shared compliance consortia to distribute EU REACH documentation cost burdens. Certification timeline compression from parallel USDA Organic and REACH compliance cycles strains working capital; pre-validate chain-of-custody documentation before contract negotiation to defend margin position. For New Entrants and Emerging Players: Capture white space in underpenetrated United States domestic distillation where aromatherapy consumption outpaces regional production investment. Citrus hydrosols represent fastest-expanding category as cold-pressed peel alternatives gain traction in natural fragrance compounding. Direct-to-formulator B2B e-commerce channels bypass traditional distributor markups and enable origin storytelling for indie cosmetic brands. For Investors and Strategic Acquirers: Re-rating potential sits with laboratory-validated pharmaceutical-grade suppliers given ECHA's 2024-2025 rolling action plan accelerating toxicological profiling requirements for botanical extracts. Long-term viability favors entities with backward integration into organic cultivation and Swissmedic or USP certification credentials. Watch supercritical CO2 extraction technology penetration into premium cosmetic tiers as inflection indicator for heat-sensitive matrix processing capability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive supply of certified lavender and rose damascena biomass locks in raw material security for fragrance compounders. |
| Shared Compliance Consortium Formation | French and Bulgarian exporters distribute ECHA analytical cost burdens across distillation networks. |
| Supercritical CO2 Extraction Adoption | Swiss and German pharmaceutical compounders capture water-soluble metabolites at lower thermal degradation rates. |
| Direct-to-Formulator E-Commerce Channel | Artisan distilleries bypass traditional distributors and access indie cosmetic brand procurement. |
| Multi-Origin Sourcing Strategy | California and New York formulators dilute single-region climate risk through supplier roster rotation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this organic hydrosols market assessment. Primary interviews with distillation cooperative managers, cosmetic formulation chemists, pharmaceutical procurement officers, and aromatherapy wellness practitioners combined with secondary validation from USDA organic certification databases, ECHA substance evaluation registers, and EU customs trade flows. Bottom-up volume triangulation across product type, application, and end-user segments cross-checked against top-down value estimates from fragrance compounder revenue disclosures and natural product retailer SKU audits.
Segment-level modeling captured floral waters, herbal extracts, citrus hydrosols, and fruit hydrosols across cosmetics, food and beverage, aromatherapy, and pharmaceutical applications. End-user differentiation spanned manufacturers, retailers, wellness centers, and private consumers. Distribution channel granularity tracked online stores, health shops, supermarkets, and specialty stores. CAGRs derived from weighted average growth assumptions across certification tiers and regional demand clusters. Forecast inputs incorporated organic cultivation acreage expansion, EU REACH compliance timeline compression, and supercritical CO2 extraction technology penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate stress on lavender and rose harvests in Provence and Kazanlak Valley. Forecasts reflect documented assumptions regarding organic equivalence agreement stability between regulatory jurisdictions and skilled distillation technician workforce replacement rates. Deviation in EU Green Deal synthetic solvent restriction implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Cyclopentanone Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
N-Hexanol Market
Organic Chemicals
2-Iodophenol Market
Organic Chemicals
Benzyl Cyanide Market
Organic Chemicals
Diethyl Ketone Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Chloroethylene Market
Organic Chemicals
Global Carboxylic Acid Market